
 Global Disposable Hemoperfusion Market | 2026-2036
Global Disposable Hemoperfusion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disposable Hemoperfusion Market Foresight
Hospital-grade cartridge specifications is unwinding competitive dynamics across the disposable hemoperfusion landscape. Jafron Biomedical leverages integrated resin production and captive sorbent supply to control cost positioning in Asia-Pacific markets. Baxter International anchors North American distribution through its established critical care channel infrastructure. Toray Medical specializes in high-porosity activated carbon formulations that differentiate its cartridges in Japanese academic medical centers.
Disposable hemoperfusion refers to an extracorporeal blood purification technique wherein blood passes through a cartridge packed with adsorbent material—typically activated carbon, synthetic resin, or polymyxin B-immobilized fibers—to remove toxins, inflammatory mediators, or drug overdoses without dialytic clearance. The cartridge operates at blood flow rates of 100–250 mL/minute with treatment sessions lasting 2–6 hours, depending on clinical indication and adsorbent saturation kinetics. Resin cartridge formats lead current revenue pools due to superior biocompatility profiles and broader toxin-binding affinity, while CytoSorb cartridge deployments accelerate fastest among cytokine-adsorption applications in sepsis treatment protocols. Intensive care units represent the dominant end-user channel, though emergency care facilities are expanding fastest as pre-hospital and bedside hemoperfusion protocols standardize.
FDA 510(k) clearance requirements and the EU MDR's strengthened clinical evidence mandates shape product development timelines and market access barriers for hemoperfusion manufacturers. China's NMPA and Japan's PMDA enforce distinct biocompatibility testing protocols that fragment regulatory submission strategies across major production centers. ISO 10993 biological evaluation standards provide a baseline reference, though national deviations in cytotoxicity and hemolysis thresholds compel region-specific validation studies. Stakeholders must monitor evolving sepsis treatment guidelines from critical care societies and anticipate reimbursement code revisions that could restructure end-user procurement economics.
Market Dynamics
Hospital procurement consolidation and ICU protocol standardization are compressing vendor margins while amplifying volume concentration among resin cartridge suppliers with captive sorbent production.
Growth Catalysts
- Sepsis protocol expansion:Critical care societies in the United States and Germany are embedding cytokine-adsorption hemoperfusion into surviving sepsis campaign guidelines, institutionalizing repeat cartridge procurement.
- China's NMPA streamlining:Expedited 510(k)-equivalent pathways for resin-based devices have collapsed domestic approval timelines from 24 months to under 12 months.
- Activated carbon formulation advances:High-porosity variants with enhanced endotoxin binding are displacing plasma exchange in Japanese academic medical centers for acute liver failure.
Market Restraints
- Raw sorbent concentration:Pharmaceutical-grade styrene-divinylbenzene resin production concentrates in three Chinese chemical parks, exposing buyers to single-source disruption risk.
- EU MDR clinical evidence mandates:Strengthened biocompatibility documentation requirements under 2017/745 have extended European market access timelines by 18-24 months for new cartridge entrants.
- Plasma exchange substitution:Membrane-based therapeutic plasma exchange systems with broader metabolite clearance profiles threaten hemoperfusion's position in autoimmune neurological indications.
Strategic Opportunities
- Emergency department pre-hospital deployment:Bedside hemoperfusion protocols in United States trauma centers are creating cartridge consumption outside traditional ICU settings.
- India's critical care infrastructure buildout:Government-funded tertiary hospital expansion under the Ayushman Bharat scheme is generating first-time demand for extracorporeal blood purification in tier-2 cities.
- Polymyxin B fiber convergence:Integration of endotoxin-adsorbing fibers with continuous renal replacement therapy circuits is opening hybrid device categories for septic shock management.
Industry Challenges
- Perfusionist training scarcity:Specialized extracorporeal technician certification programs in Brazil and Mexico cannot match ICU expansion velocity, constraining treatment session throughput.
- ISO 10993-4 hemolysis validation:Regional deviations in acceptable plasma-free hemoglobin thresholds between Japan's PMDA and China's NMPA force redundant testing protocols for multi-market submissions.
- Legacy hemodialysis infrastructure incompatibility:Proprietary cartridge-to-monitor interfaces from dominant dialysis equipment manufacturers block plug-and-play hemoperfusion adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disposable Hemoperfusion Market |
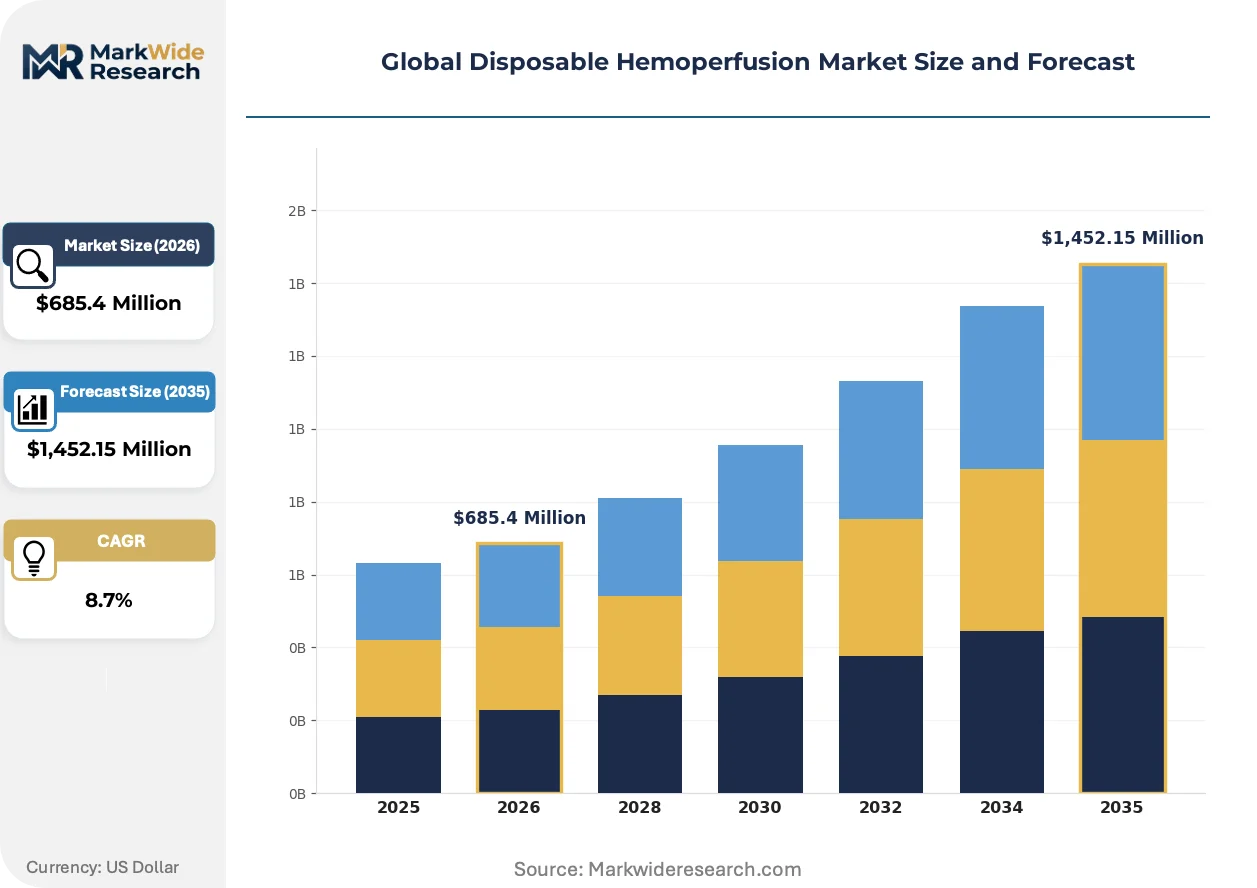
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon Cartridge, Resin Cartridge, Polymyxin B Cartridge, CytoSorb Cartridge, Others Application: Sepsis Treatment, Liver Failure Management, Drug Overdose Detoxification, Acute Kidney Injury Support, Poisoning Intervention End User: Intensive Care Units, Emergency Care Facilities, Specialty Clinics, Academic Medical Centers Deployment: Single-Use Systems, Semi-Automated Devices, Manual Operation Kits, Disposable Modular Units |
| Companies Covered | Asahi Kasei Corporation, Jafron Biomedical, Baxter International, Toray Medical, Kaneka Pharma, Kangbei Medical Device, Tianjin Zibo High Technology, Biosun Corporation, CytoSorbents, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disposable Hemoperfusion Market Shifts & Advancements
Cartridge engineering is converging with point-of-care device architectures, compressing treatment initiation time and expanding deployable settings beyond centralized dialysis units.
Portable hemoperfusion systems with integrated pumps and battery backup are miniaturizing treatment delivery from dedicated dialysis suites to emergency bays and transport vehicles. United States air medical services are piloting these units for in-flight toxin removal. The technology is compressing the window between poisoning presentation and adsorption initiation from hours to minutes.
Japan's PMDA revised biocompatibility testing guidance for adsorbent devices in 2023, mandating extended leachable studies for resin formulations with novel cross-linking chemistries. Domestic manufacturers Toray Medical and Kaneka have restructured R&D roadmaps to front-load toxicology packages. The policy is accelerating consolidation toward established players with in-house preclinical capabilities.
Group purchasing organizations in the United States are unbundling hemoperfusion cartridges from bundled dialysis service contracts, enabling direct hospital procurement of sepsis-specific cytokine adsorbers. Academic medical centers in Boston and Houston are negotiating multi-year supply agreements directly with resin cartridge specialists. The behavioral shift is most visible in tertiary ICU networks with dedicated extracorporeal teams.
Global Disposable Hemoperfusion Market Segmentation
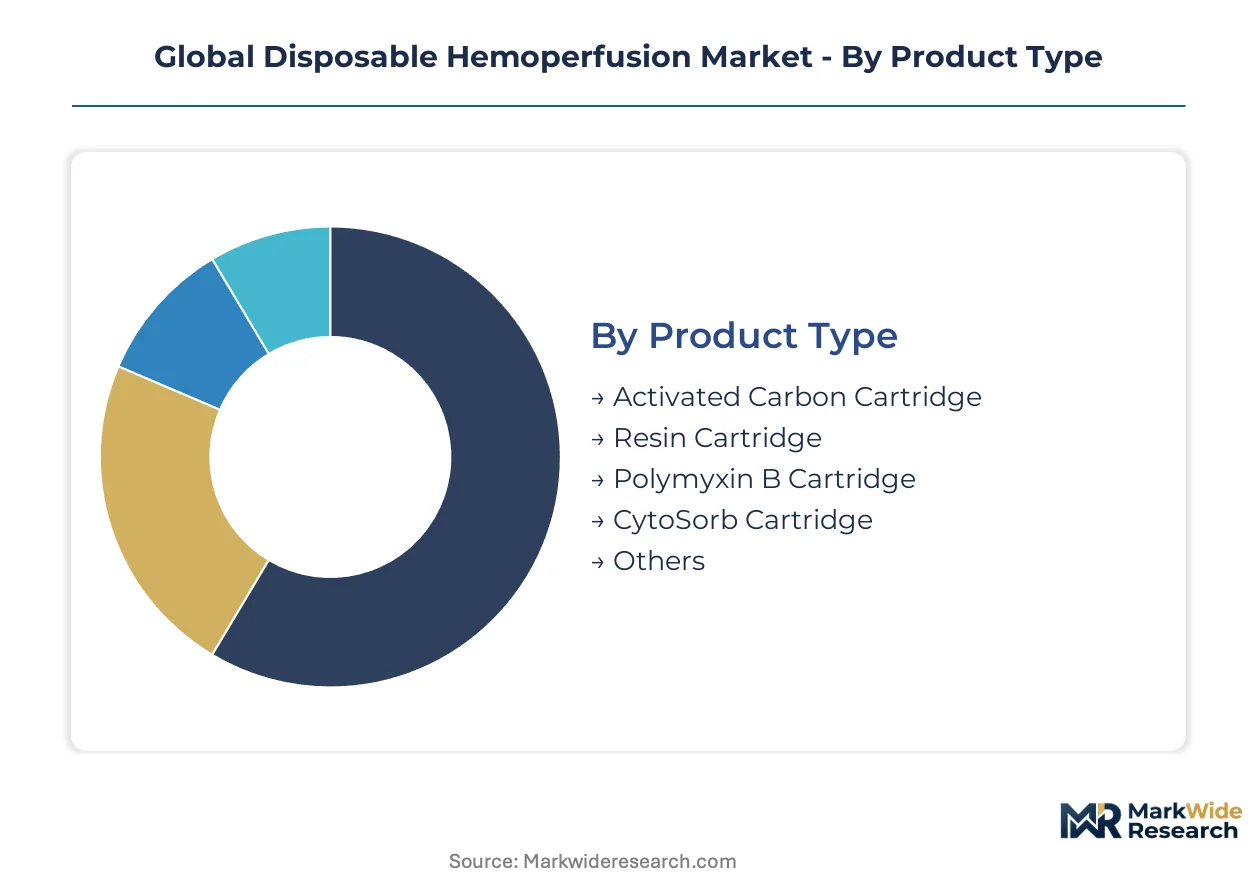
Cartridge format selection directly determines treatment protocol compatibility and reimbursement eligibility across critical care settings. Each segmentation dimension reveals distinct substitution pressures and procurement concentration patterns that shape vendor positioning strategies.
Product Type:
Plasma exchange and membrane-based alternatives exert uneven substitution pressure across cartridge chemistries, with resin formats most insulated and activated carbon most exposed.
- Resin Cartridge:Styrene-divinylbenzene copolymers with controlled pore architecture bind mid-molecular-weight toxins and inflammatory mediators. China's NMPA streamlined approval pathways have concentrated manufacturing scale-up in Guangdong and Jiangsu province chemical parks. Hospital procurement in Asia-Pacific favors resin for sepsis protocols due to superior biocompatibility profiles and broader toxin-binding affinity relative to carbon alternatives.
- Activated Carbon Cartridge:High-porosity formulations derived from coconut shell or petroleum precursors excel at low-molecular-weight toxin adsorption. Japanese academic medical centers in Tokyo and Osaka deploy these cartridges for acute liver failure, though therapeutic plasma exchange systems threaten share in autoimmune neurological indications where broader metabolite clearance matters.
- Polymyxin B Cartridge:Endotoxin-adsorbing fiber matrices integrated with continuous renal replacement therapy circuits for septic shock management.
- CytoSorb Cartridge:Cytokine-adsorption technology embedding into surviving sepsis campaign guidelines across United States and German critical care networks.
- Others:Emerging sorbent chemistries including immobilized enzyme and molecularly imprinted polymer formats in preclinical validation.
Resin Cartridge retains volume leadership; CytoSorb Cartridge holds the steepest expansion curve.
Application:
Clinical indication determines session frequency, cartridge consumption velocity, and protocol standardization maturity across hospital networks.
- Sepsis Treatment:Cytokine-adsorption hemoperfusion embedded into surviving sepsis campaign guidelines institutionalizes repeat cartridge procurement. Critical care societies in the United States and Germany drive protocol adoption, with tertiary ICU networks negotiating multi-year supply agreements directly with resin specialists.
- Liver Failure Management:High-porosity activated carbon formulations displace plasma exchange in Japanese academic medical centers for acute hepatic encephalopathy. Treatment sessions extend 4-6 hours with adsorbent saturation kinetics dictating cartridge replacement intervals.
- Drug Overdose Detoxification:Emergency department deployment of bedside hemoperfusion compresses initiation windows from hours to minutes in United States trauma centers.
- Acute Kidney Injury Support:Adjunctive blood purification integrated with continuous renal replacement therapy circuits in hybrid device configurations.
- Poisoning Intervention:Pre-hospital and transport vehicle applications expanding with portable system miniaturization in United States air medical services.
Sepsis Treatment commands the largest installed base; Drug Overdose Detoxification is climbing the fastest as emergency protocols standardize.
End User:
Facility type shapes technical staffing requirements, capital equipment compatibility, and procurement contract structures.
- Intensive Care Units:Dominant consumption channel with dedicated extracorporeal teams managing 2-6 hour treatment sessions at 100-250 mL/minute blood flow rates. Group purchasing organizations in the United States are unbundling cartridges from bundled dialysis service contracts, enabling direct hospital procurement.
- Emergency Care Facilities:Fastest-expanding setting as bedside hemoperfusion protocols standardize outside traditional ICU infrastructure. United States trauma centers in Boston and Houston pilot pre-hospital deployment.
- Specialty Clinics:Concentrated in hepatology and toxicology referral networks with protocolized poisoning intervention workflows.
- Academic Medical Centers:Tokyo, Osaka, Boston, and Houston clusters drive clinical evidence generation and guideline formulation for emerging indications.
Intensive Care Units maintain procurement dominance; Emergency Care Facilities show the sharpest volume acceleration.
Deployment:
System architecture determines operator training burden, treatment initiation speed, and interoperability with existing dialysis infrastructure.
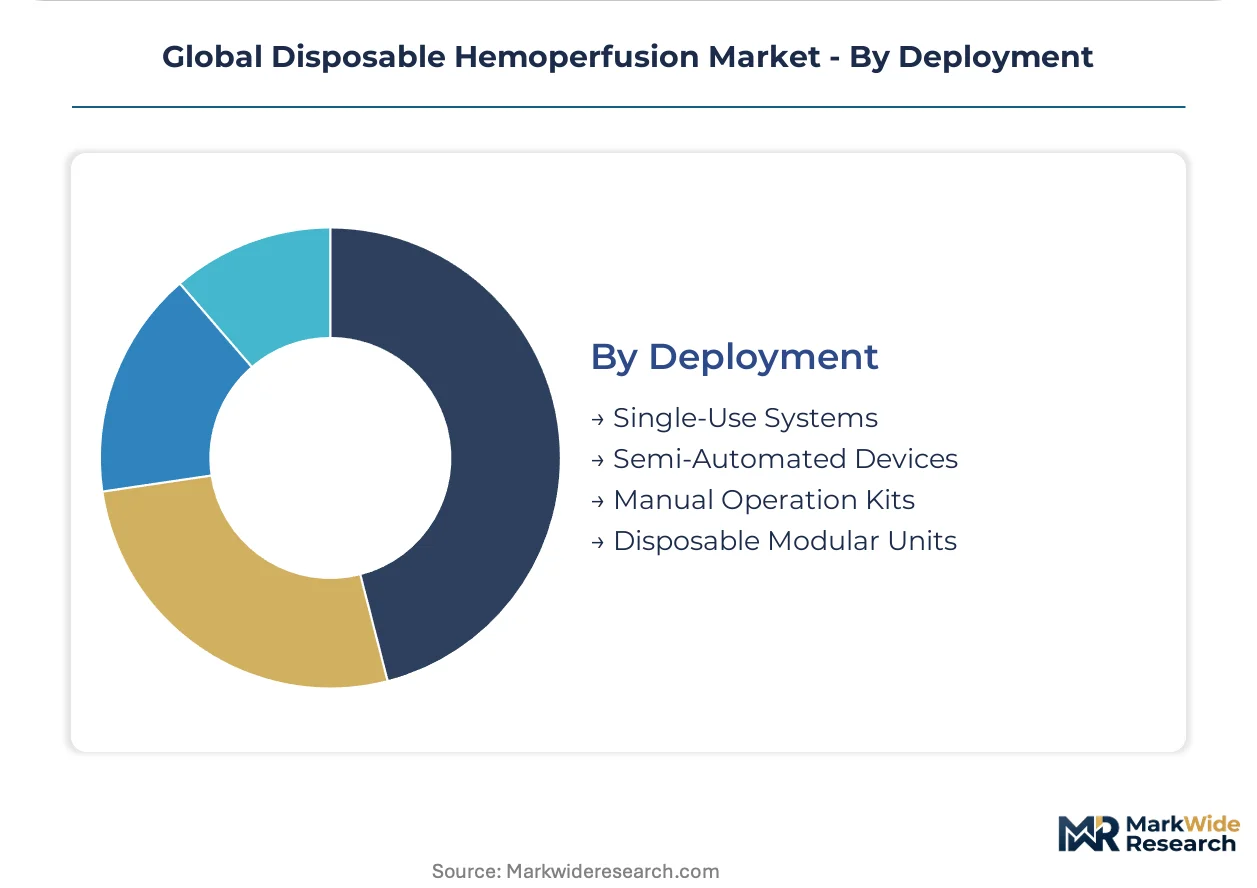
- Single-Use Systems:Fully integrated disposable cartridges with pre-attached bloodlines eliminate reprocessing protocols. Proprietary cartridge-to-monitor interfaces from dominant dialysis equipment manufacturers block plug-and-play adoption, constraining vendor switching.
- Semi-Automated Devices:Portable configurations with integrated pumps and battery backup miniaturize treatment delivery to emergency bays and transport vehicles. United States air medical services pilot in-flight toxin removal capabilities.
- Manual Operation Kits:Lower-cost configurations for resource-constrained settings requiring perfusionist oversight throughout 2-6 hour sessions.
- Disposable Modular Units:Cartridge formats compatible with multiple monitor platforms through standardized connectors, though legacy hemodialysis infrastructure incompatibility persists.
Single-Use Systems anchor current revenue pools; Semi-Automated Devices are gaining share fastest as point-of-care architectures converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese resin cartridge exports supply tertiary hospitals across Southeast Asia and the Middle East, while Japanese activated carbon formulations reach academic medical centers in Australia and South Korea through established distributor networks.
United States
FDA 510(k) clearance pathways structure competitive entry timelines for sepsis-specific cytokine adsorbers. Group purchasing organizations in Boston and Houston unbundle cartridges from dialysis service contracts, enabling direct hospital procurement from resin specialists. Academic medical centers in these clusters drive clinical evidence generation for emergency department deployment protocols.
China
NMPA streamlined approval pathways collapsed domestic timelines from 24 months to under 12 months for resin-based devices. Government-funded tertiary hospital expansion under regional healthcare infrastructure programs sustains procurement volumes in Guangdong and Jiangsu province chemical parks. Domestic manufacturers scale captive sorbent production to serve Asia-Pacific export demand.
Germany
EMA regulatory frameworks and EU MDR clinical evidence mandates extend market access timelines for new cartridge entrants. Critical care societies embed cytokine-adsorption hemoperfusion into surviving sepsis campaign guidelines, institutionalizing repeat procurement from academic hospital networks in Berlin and Munich. The country's regulator enforces strengthened biocompatibility documentation requirements.
Japan
PMDA revised biocompatibility testing guidance in 2023, mandating extended leachable studies for novel resin cross-linking chemistries. High-porosity activated carbon formulations from domestic manufacturers displace plasma exchange in Tokyo and Osaka academic medical centers for acute liver failure management. The regulatory shift accelerates consolidation toward established players with in-house preclinical capabilities.
India
Government-funded tertiary hospital expansion under the Ayushman Bharat scheme generates first-time demand for extracorporeal blood purification in tier-2 cities. CDSCO regulatory pathways for imported resin cartridges shape procurement decisions in Delhi-NCR and Maharashtra hospital networks. Domestic distribution partnerships with Chinese manufacturers concentrate supply in South Asian markets.
Global Disposable Hemoperfusion Market Competitive Landscape
Listed leaders compete with private specialists across regulatory submission capacity and captive sorbent supply security. The vendor base stratifies into three tiers: integrated resin producers controlling upstream chemical synthesis, critical care device multinationals leveraging established distribution infrastructure, and regional specialists focused on single-market regulatory navigation. Dominant competitive moves include backward integration into pharmaceutical-grade styrene-divinylbenzene resin production and strategic partnerships with academic medical centers for clinical evidence generation.
Among Asia-Pacific-based integrated manufacturers, Jafron Biomedical and Tianjin Zibo High Technology occupy positions anchored to Guangdong and Jiangsu chemical park infrastructure. Baxter International exemplifies the critical care multinational archetype through North American channel infrastructure. Toray Medical and Kaneka Pharma represent the Japanese specialist tier with concentrated positioning in academic medical center networks.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| Jafron Biomedical |
| Baxter International |
| Toray Medical |
| Kaneka Pharma |
| Kangbei Medical Device |
| Tianjin Zibo High Technology |
| Biosun Corporation |
| CytoSorbents |
| Others |
Supply & Pricing Matrix
Twelve-to-eighteen-month cartridge approval timelines in Europe compress inventory turns for distributors serving German academic hospital networks, amplifying pricing power for resin producers with captive sorbent synthesis in Guangdong chemical parks. This lead-time band concentrates procurement leverage among integrated manufacturers while forcing spot-market buyers into premium positioning for emergency stock.
Pricing Analysis
Hospital procurement committees anchor contract structures around multi-year supply agreements with resin cartridge specialists. Pricing stratifies across FDA-cleared premium tiers, CE-marked standard configurations, and economy-grade unbundled formats for tier-2 facilities. Cost compression in emergency care segments is intensifying because GPOs are extracting volume discounts for bedside hemoperfusion protocols. Emergency departments show highest price sensitivity; tertiary ICU networks with dedicated extracorporeal teams demonstrate lowest.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for Japanese activated carbon formulations reaching Australian academic centers. Pharmaceutical-grade styrene-divinylbenzene resin production centers on China, with secondary concentration in South Korea and Japan for specialty fiber matrices. Raw material dependencies span styrene monomer, divinylbenzene cross-linkers, and coconut shell carbon precursors. Single-source vulnerability concentrates in three Chinese chemical parks. Distribution runs through regional GPOs and specialized critical care distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies early-cycle expansion as sepsis protocol standardization institutionalizes repeat cartridge procurement beyond pilot deployments.
For Market Incumbents: Compound defensive positioning through backward integration into pharmaceutical-grade resin production and captive sorbent supply security. Plasma exchange substitution in autoimmune neurological indications threatens activated carbon share; counter by embedding cytokine-adsorption cartridges into surviving sepsis campaign guidelines across United States and German critical care networks. Prioritize NMPA-equivalent pathway expertise for Asia-Pacific volume concentration. For New Entrants and Emerging Players: Anchor in emergency department pre-hospital deployment as the most penetrable white-space channel, where portable system miniaturization creates first-mover advantage outside legacy ICU infrastructure. Target tier-2 Indian cities under Ayushman Bharat infrastructure buildout for first-time extracorporeal blood purification demand. Pursue direct hospital procurement relationships unbundled from dialysis service contracts as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across resin cartridge manufacturing as NMPA streamlining accelerates domestic scale-up requirements. Long-term viability favors integrated producers controlling upstream chemical synthesis rather than device assemblers dependent on spot sorbent markets. Acquisition targets should demonstrate in-house ISO 10993 validation capabilities and multi-regulatory submission track records. Monitor EU MDR clinical evidence mandate compliance timelines as the critical inflection signal for European market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive sorbent supply secures margin control against Guangdong chemical park concentration. |
| NMPA Streamlined Pathway Navigation | Twelve-month approval timelines in China unlock Asia-Pacific export volume scaling. |
| Sepsis Protocol Clinical Evidence Generation | Surviving sepsis campaign guideline embedding institutionalizes repeat procurement cycles. |
| Emergency Department Direct Procurement | GPO unbundling enables margin capture outside bundled dialysis service contracts. |
| Portable System Miniaturization | Battery-integrated configurations expand addressable settings to transport vehicles and pre-hospital care. |
Research Methodology
Operator-level perspectives from critical care physicians, hospital procurement committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interview findings triangulated against secondary sources including FDA 510(k) filings, NMPA approval databases, hospital procurement contract repositories, and critical care society guideline documents. Bottom-up cartridge volume estimates converged with top-down market sizing across resin, activated carbon, and cytokine-adsorption technology platforms.
Sensitivity analysis tested forecast robustness across regulatory approval timeline scenarios, sepsis protocol adoption curves, and plasma exchange substitution rates. Segmentation dimensions modeled include cartridge chemistry format, clinical indication, end-user facility type, and deployment architecture complexity. CAGRs derived from procedure volume projections, cartridge consumption per session, and pricing trajectory assumptions. Industry-specific inputs incorporated perfusionist training pipeline constraints and ISO 10993-4 hemolysis validation protocol variations.
Underlying assumptions cover NMPA pathway stability, EU MDR enforcement continuity, and sepsis guideline revision cycles, with deviation risk concentrated in raw sorbent supply disruptions and therapeutic plasma exchange technology advances. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Langerhans Cell Histiocytosis Management Market
Hematology
Myelodysplastic Syndrome (MDS) Treatment Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market
Hematology
Immune Thrombocytopenia (ITP) Market
Hematology
Hemoglobin Analyzer Market
Hematology
Multiple Myeloma Market
Hematology
Blood Disorder Therapeutics Market
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
Haematocrit Centrifuge Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Rare Hematology Market
Hematology
Anemia Drugs Market
Hematology
Bone Marrow Transplant Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Global Hemoglobin Meter Market