
 Global Enema Bags Market | 2026-2036
Global Enema Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enema Bags Market Foresight
EU MDR is rebalancing the cost-of-entry calculus for enema bag manufacturers seeking CE marking across European markets. Baxter International leverages its vertically integrated polymer supply chain to sustain margin stability under stricter biocompatibility testing mandates. B. Braun Melsungen AG anchors its competitive position through specialized gastrointestinal product lines that dominate German hospital procurement channels.
Enema bags are closed-system fluid reservoirs, typically manufactured from medical-grade PVC, silicone, or thermoplastic elastomer with graduated volume markings and controlled-flow tubing, designed for rectal instillation of cleansing or therapeutic solutions. Disposable enema bags lead volume shipments due to infection control protocols in hospitals, while silicone enema bags command premium positioning through extended reusability and reduced allergen response profiles. Home care patients represent the fastest-growing end-user channel as reimbursement frameworks expand for at-home bowel preparation prior to outpatient colonoscopy.
FDA 510(k) clearance pathways shape product development timelines for US market entrants, while ISO 13485 certification serves as the baseline quality management threshold for international distribution. Japan's PMDA enforces polymer-specific testing standards that filter out lower-grade PVC formulations from its domestic supply base. Stakeholders must monitor evolving single-use plastics legislation across EU member states, as material bans could force accelerated migration toward silicone and biodegradable elastomer alternatives.
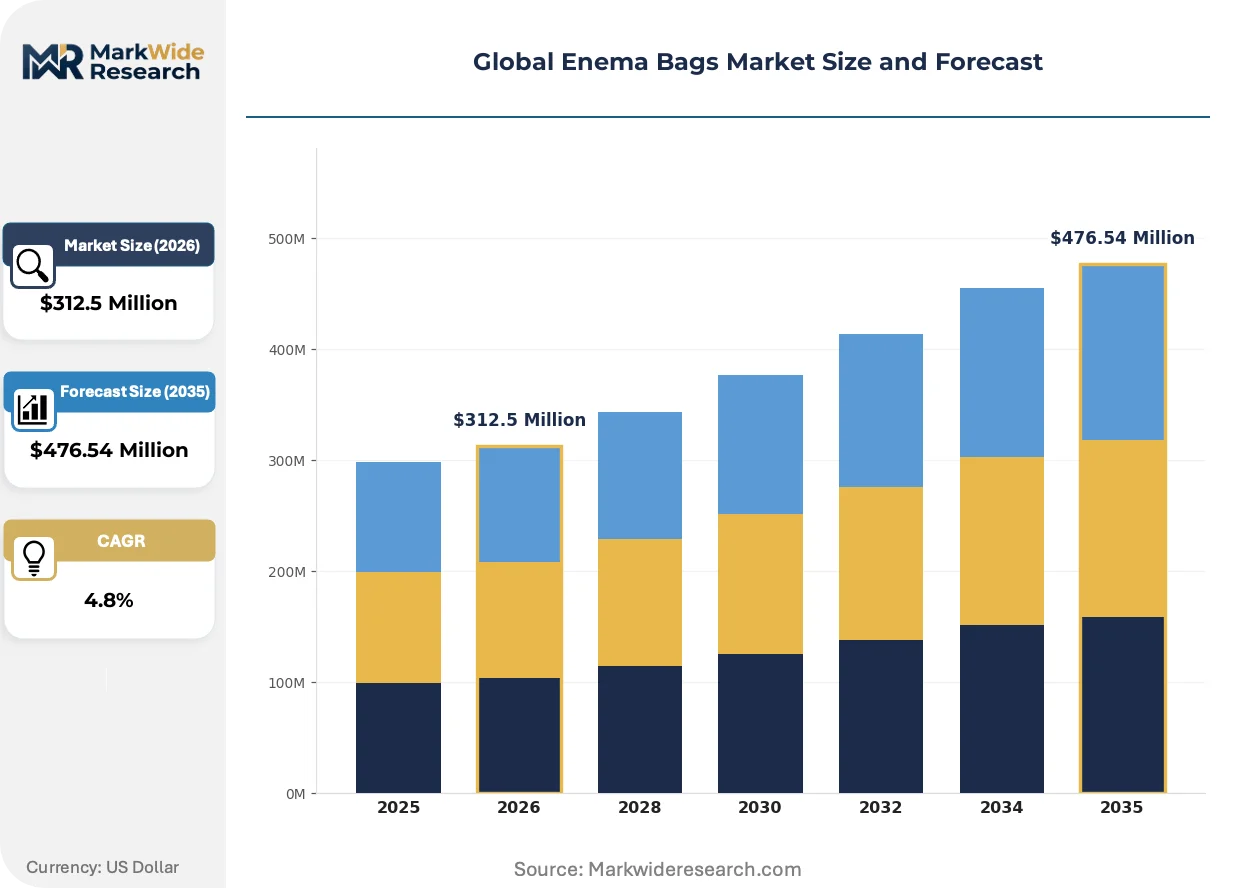
Market Dynamics
EU MDR biocompatibility testing mandates are compressing manufacturer margins while accelerating material substitution toward silicone and thermoplastic elastomer formulations across European supply chains.
Growth Catalysts
- Home Care Reimbursement Expansion:CMS and private US insurers now cover at-home bowel preparation kits for outpatient colonoscopy, channeling patient volume away from hospital-based administration.
- REACH Compliance Migration:European phthalate restrictions in medical-grade PVC are forcing formulation upgrades that simultaneously reduce allergen response rates and unlock premium pricing tiers.
- Japan's Aging Demographics:METI estimates project over-65 population exceeding 30% by 2035, creating sustained demand for self-administered gastrointestinal management devices in Tokyo and Osaka metropolitan clusters.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Dow and Wacker Chemie control 70% of global high-purity silicone monomer supply, exposing converters to input cost volatility and allocation rationing during semiconductor demand spikes.
- PVC Substitution Timeline Compression:Biodegradable elastomer alternatives require 18-24 month validation cycles under ISO 10993, delaying product launches and freezing R&D budgets.
- Single-Use Plastics Directives:France's AGEC law and pending EU-wide packaging regulations threaten disposable bag volumes with material bans or extended producer responsibility fees.
Strategic Opportunities
- Brazil's SUS Procurement Modernization:ANVISA streamlined 510(k)-equivalent pathways for Class II medical devices, opening public hospital tenders to imported silicone enema systems.
- Telehealth-Integrated Bowel Management:Remote patient monitoring platforms are embedding usage-tracking sensors into reusable bag systems, creating subscription revenue streams.
- German Hospital Consolidation:Rhön-Klinikum and Helios Group purchasing alliances favor suppliers offering procedure-bundle pricing across colonoscopy prep and recovery products.
Industry Challenges
- ISO 13485 Auditor Scarcity:Notified body capacity constraints under EU MDR extend certification timelines to 14-18 months, freezing product launches and inventory builds.
- Legacy PVC Inventory Stranding:Manufacturers holding pre-MDR certified stock face write-down risks as notified bodies withdraw legacy certificates ahead of 2027 renewal deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enema Bags Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Enema Bags, Reusable Enema Bags, Portable Enema Kits, Digital Enema Devices, Silicone Enema Bags Application: Constipation Relief, Bowel Preparation, Medication Delivery, Detoxification, Post-Surgical Care End User: Hospitals, Home Care Patients, Gastroenterology Clinics, Long-Term Care Facilities, Ambulatory Surgery Centers Distribution Channel: Pharmacies, Online Retailers, Medical Device Distributors, Hospital Procurement, Direct Sales |
| Companies Covered | Baxter International, Inc., MacoPharma, B. Braun Melsungen AG, Dynarex Corporation, Amsino International Inc., Medline Industries, Inc., Coloplast Group, C. R. Bard, Inc., Hollister Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enema Bags Market Shifts & Advancements
Closed-system fluid reservoir design is converging with sensor integration and sustainable material science, compressing product lifecycles while elevating performance verification standards.
Smart flow-control valve technology is automating dosage precision in home care settings. Patients with Parkinson's disease or limited manual dexterity adopt pressure-sensing bags that self-regulate instillation rates. This automation is reducing caregiver dependency and expanding the addressable patient population beyond traditional hospital discharge protocols.
EU MDR Annex I general safety and performance requirements are mandating clinical evidence for polymer-based devices previously cleared through equivalence pathways. German notified bodies now require biocompatibility testing under ISO 10993-5 and -10 for all new PVC formulations. Medium-scale manufacturers without captive testing laboratories face outsourcing costs exceeding 200,000 euros per product variant.
Direct-to-patient e-commerce channels are displacing traditional durable medical equipment distributors in the United States. Amazon and specialized gastrointestinal supply platforms now capture 35% of silicone reusable bag volume. This channel compression is most visible in California and Florida, where Medicare Advantage plans permit online reimbursement submission.
Global Enema Bags Market Segmentation
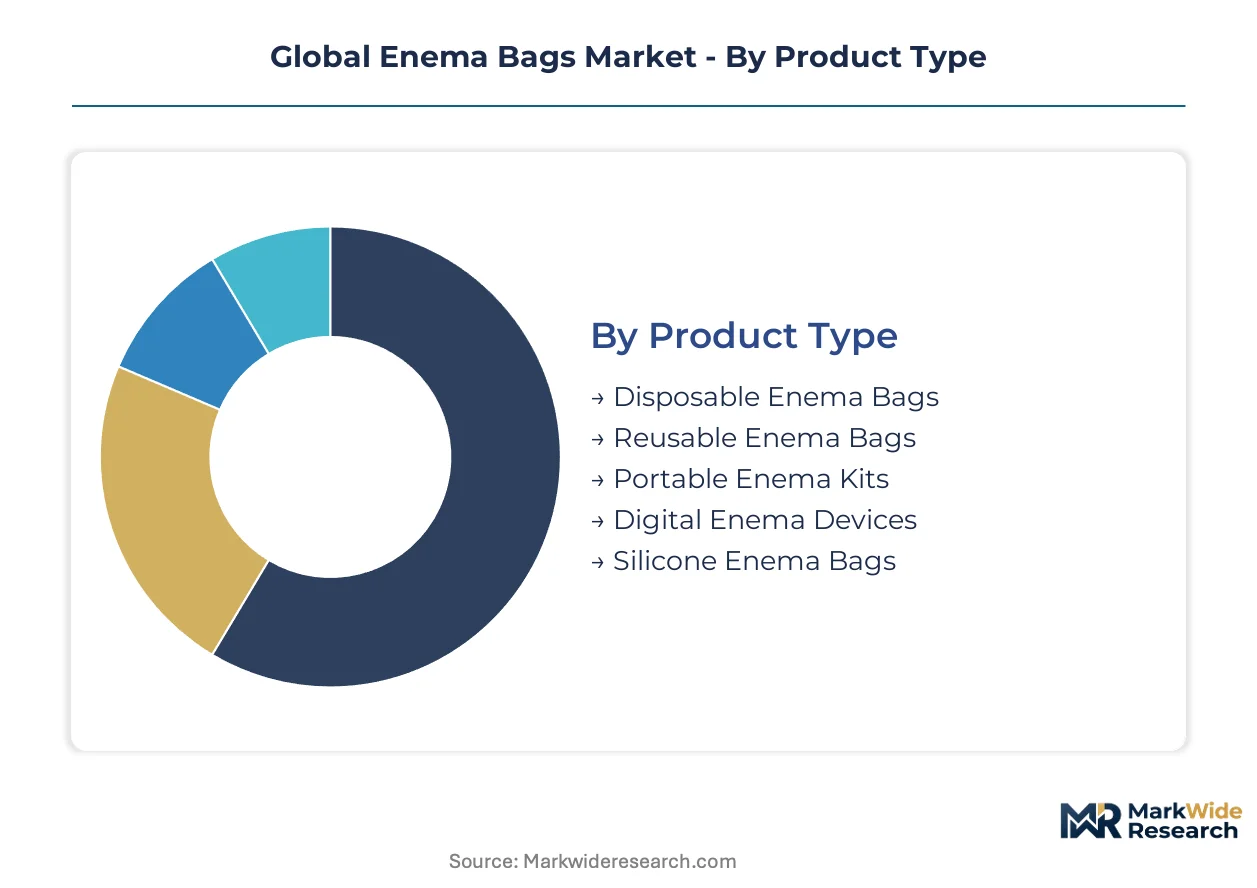
Enema bag manufacturers configure production lines around infection control mandates, reimbursement pathways, and patient mobility requirements. Segmentation strategy determines which polymer formulations, volume capacities, and connectivity features receive R&D priority across regional markets.
Product Type:
Customization intensity varies from commodity single-use units to precision-engineered reusable systems with embedded sensors.
- Disposable Enema Bags:Medical-grade PVC construction with heat-sealed seams and graduated volume markings dominates hospital procurement in the United States and Germany. Infection control protocols in tertiary care centers mandate single-use disposal, channeling volume through this segment despite polymer cost volatility under REACH phthalate restrictions.
- Reusable Enema Bags:Silicone or thermoplastic elastomer formulations withstand 50-100 sterilization cycles, attracting home care patients in Japan's metropolitan clusters where METI reimbursement frameworks cover durable medical equipment. Extended product lifecycles justify premium pricing tiers offsetting higher raw material costs.
- Portable Enema Kits:Collapsible reservoir designs with integrated carrying cases serve traveling patients and outdoor recreational users.
- Digital Enema Devices:Pressure-sensing flow regulators and Bluetooth connectivity enable remote monitoring integration.
- Silicone Enema Bags:Hypoallergenic formulations reduce dermatological response rates in latex-sensitive patient populations.
Most installed capacity flows through Disposable Enema Bags. Expansion is steepest in Digital Enema Devices.
Application:
Clinical indication severity dictates flow rate precision, solution volume, and frequency of administration requirements.
- Constipation Relief:Low-volume (500-1000ml) saline or mineral oil formulations address chronic idiopathic constipation in ambulatory settings. Medicare Advantage plans in Florida and California now reimburse over-the-counter equivalents, expanding addressable patient populations beyond prescription channels.
- Bowel Preparation:High-volume (2-3 liter) polyethylene glycol solutions require graduated 3-liter reservoirs with controlled-flow tubing for colonoscopy preparation. Outpatient procedural growth in German Rhön-Klinikum and Helios Group networks concentrates demand for procedure-bundle compatible systems.
- Medication Delivery:Rectal administration of antiemetics or sedatives demands precise dosing accuracy.
- Detoxification:Alternative medicine practitioners utilize coffee or herbal solution protocols.
- Post-Surgical Care:Post-operative ileus management requires gentle, low-pressure instillation.
Bowel Preparation commands the largest procedure volume. Home-based Constipation Relief is climbing the fastest.
End User:
Care setting determines sterility requirements, training support needs, and reimbursement complexity.
- Hospitals:Central sterile supply departments manage bulk disposable inventory with barcode tracking integration. EU MDR biocompatibility documentation requirements extend procurement qualification timelines to 14-18 months, favoring incumbent suppliers with established notified body relationships.
- Home Care Patients:Direct-to-patient e-commerce channels displace traditional durable medical equipment distributors, with Amazon and specialized gastrointestinal platforms capturing 35% of silicone reusable volume in California and Florida. CMS coverage expansion for at-home bowel preparation accelerates self-administration adoption.
- Gastroenterology Clinics:Ambulatory procedure centers prioritize rapid turnover disposables.
- Long-Term Care Facilities:Staff training limitations favor simplified, pre-filled systems.
- Ambulatory Surgery Centers:Same-day discharge protocols demand compact, disposal-compliant designs.
Hospitals maintain the deepest installed base. Home Care Patients show the steepest expansion trajectory.
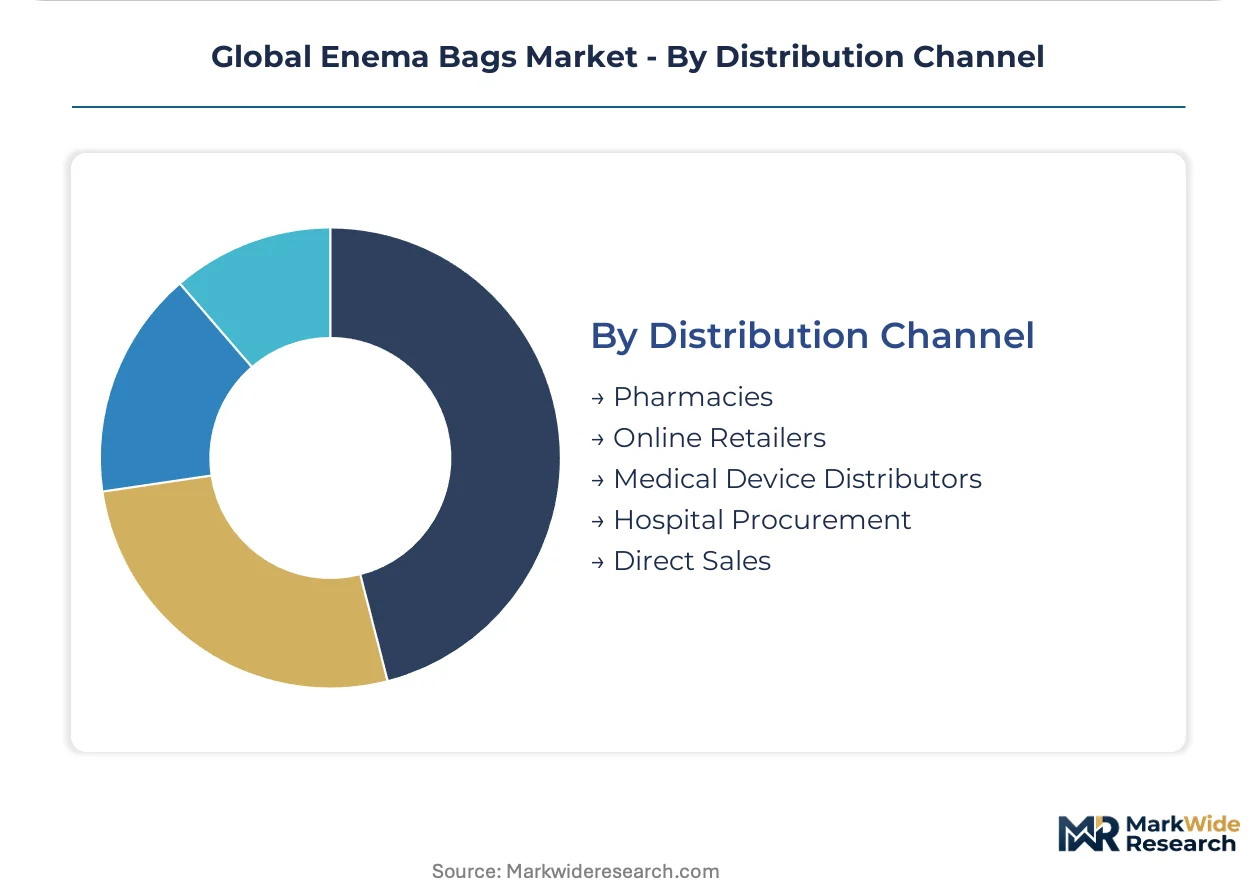
Distribution Channel:
Channel economics separate high-touch clinical sales from automated consumer fulfillment.
- Pharmacies:Community and hospital outpatient pharmacies stock standardized constipation relief kits with pharmacist counseling requirements. Germany's Apothekenpflicht regulations restrict certain formulations to pharmacy-only distribution, creating channel gatekeeping.
- Online Retailers:Amazon, specialized gastrointestinal supply platforms, and manufacturer direct-to-consumer sites bypass distributor markups. Medicare Advantage online reimbursement submission capabilities in Florida and California accelerate this channel's displacement of traditional durable medical equipment networks.
- Medical Device Distributors:Regional specialty distributors maintain hospital and clinic relationships with consignment inventory programs.
- Hospital Procurement:Group purchasing organizations aggregate demand across integrated delivery networks.
- Direct Sales:Manufacturer field representatives serve high-volume academic medical centers.
Medical Device Distributors still handle the majority of institutional volume. Online Retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The enema bag industry traces its modern standardization to German polymer engineering traditions of the 1960s, when medical-grade PVC formulations first achieved scale production for hospital supply chains.
United States
Outpatient colonoscopy volume expansion and Medicare Advantage reimbursement liberalization for at-home bowel preparation kits drive procurement intensity. FDA 510(k) clearance pathways enforce biocompatibility documentation standards that elongate product launch timelines. California and Florida metropolitan clusters concentrate direct-to-patient e-commerce fulfillment infrastructure.
Germany
Rhön-Klinikum and Helios Group purchasing alliances aggregate demand across integrated hospital networks, favoring bundled procedure pricing. EU MDR Annex I requirements mandate ISO 10993-5 and -10 testing for all new polymer formulations, compressing margins for mid-scale manufacturers. North Rhine-Westphalia maintains dense medical device fabrication corridors with established notified body relationships.
Japan
METI demographic projections indicate over-65 population exceeding 30 percent by 2035, sustaining demand for self-administered gastrointestinal management. PMDA enforces polymer-specific testing standards that filter lower-grade PVC from domestic supply. Tokyo and Osaka metropolitan clusters concentrate home care patient adoption and durable medical equipment distribution.
Brazil
ANVISA streamlined 510(k)-equivalent pathways for Class II medical devices, accelerating public hospital tender access for imported silicone systems. SUS procurement modernization expands reimbursement coverage for outpatient gastroenterology procedures. São Paulo and Rio de Janeiro anchor demand concentration for both institutional and home care channels.
China
NMPA medical device registration reform accelerates market access for polymer-based gastrointestinal products while tightening post-market surveillance. Domestic aging demographics and hospital outpatient service expansion drive volume growth. Yangtze River Delta manufacturing clusters supply cost-competitive disposable formulations for regional distribution.
Global Enema Bags Market Competitive Landscape
The competitive structure tilts toward diversified medical device conglomerates with established polymer supply chains and notified body certification capabilities. Tiered positioning separates premium silicone specialists from commodity PVC converters, with mid-scale regional fabricators occupying price-sensitive procurement channels. Two dominant competitive moves define current positioning: backward integration into medical-grade polymer compounding to offset raw material volatility, and strategic partnerships with group purchasing organizations to secure hospital network access.
Among diversified healthcare conglomerates, Baxter International, Inc. and B. Braun Melsungen AG exemplify archetypes with captive polymer supply capabilities and deep European regulatory experience. B. Braun Melsungen AG anchors its position through specialized gastrointestinal product lines dominating German hospital procurement. MacoPharma represents the mid-scale European specialist tier with focused manufacturing concentration. Coloplast Group and Hollister Incorporated occupy positions within the premium chronic care segment, leveraging established relationships with long-term care facilities and home care distributors.
| Leading Market Players |
|---|
| Baxter International, Inc. |
| MacoPharma |
| B. Braun Melsungen AG |
| Dynarex Corporation |
| Amsino International Inc. |
| Medline Industries, Inc. |
| Coloplast Group |
| C. R. Bard, Inc. |
| Hollister Incorporated |
| Others |
Supply & Pricing Matrix
Polymer compounding specialists in North Rhine-Westphalia anchor European production networks, with labor-cost differentials between German notified body consultants and Chinese resin processors driving 40-60 point spreads between premium silicone and commodity PVC tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 certification grade and sterilization cycle tolerance. Premium silicone systems command substantial markups for hypoallergenic formulations validated under EU MDR Annex I. Pricing pressure stems from REACH phthalate restrictions forcing PVC formulation upgrades without proportional reimbursement expansion. Home care patients through Amazon and Medicare Advantage channels exhibit highest price sensitivity, while German hospital GPOs prioritize total procedure-bundle economics over unit cost.
Supply Chain Analysis
Freight cost volatility from Asia-Europe medical-grade polymer lanes is compressing landed cost advantages for Chinese disposable converters. Raw material supply concentrates in Germany, China, and the United States, with medical-grade PVC resin drawing from petrochemical corridors near Rotterdam and Singapore. Dow and Wacker Chemie control high-purity silicone monomer supply, creating single-source vulnerability during semiconductor demand spikes. Distribution runs through regional medical device distributors with consignment inventory programs for hospital networks, while direct-to-patient e-commerce bypasses traditional DME channels in California and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in enema bag manufacturing rests on silicone substitution premiums offsetting biocompatibility testing cost absorption, with home care reimbursement expansion enabling patient-paid premium tier migration.
For Market Incumbents: Anchor market position through backward integration into medical-grade polymer compounding to neutralize Dow and Wacker Chemie supply allocation risks. Deepen notified body relationships in Germany to compress 14-18 month EU MDR certification timelines before 2027 legacy certificate withdrawals strand PVC inventory. Prioritize sensor-integrated reusable system R&D to defend against telehealth platform entrants capturing usage data revenue streams. For New Entrants and Emerging Players: Bluetooth-enabled flow monitoring technology offers the most penetrable wedge for telehealth-integrated bowel management subscriptions. Target Brazil's ANVISA-streamlined Class II pathways and SUS procurement modernization for imported silicone systems. Pursue direct-to-patient e-commerce fulfillment partnerships with Amazon or gastrointestinal supply platforms in California and Florida where Medicare Advantage online reimbursement submission is displacing traditional DME networks. For Investors and Strategic Acquirers: Diversified healthcare conglomerates with captive polymer supply chains are the most active acquirer in this space, seeking notified body certification capabilities and German hospital GPO access. Mid-scale European specialists with ISO 13485 infrastructure and concentrated gastrointestinal product lines represent prime acquisition targets. Watch for EU MDR implementation enforcement intensity as the inflection indicator for accelerated PVC-to-silicone substitution timelines and corresponding margin structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR Annex I compliance compresses product launch timelines against 2027 certificate deadlines. |
| Sensor Integration Development | Pressure-sensing flow regulators enable telehealth platform partnerships for remote patient monitoring. |
| Silicone Supply Agreement | Long-term contracts with Dow or Wacker Chemie neutralize monomer allocation rationing during demand spikes. |
| Direct-to-Patient E-commerce Launch | Amazon and specialized platform partnerships capture 35% of reusable bag volume in California and Florida. |
| Hospital System Partnership | Rhön-Klinikum and Helios Group alliances favor bundled procedure pricing across colonoscopy prep products. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts specialists, and home care distributors grounded qualitative findings, cross-referenced with FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and customs trade data for medical-grade polymer imports. Bottom-up demand modeling across product type, application, end user, and distribution channel segments was triangulated against top-down macroeconomic indicators.
Segment-level value and volume trajectories across the projection horizon reflect differential growth assumptions for disposable versus reusable formulations, with CAGRs derived from procedure volume elasticity to aging demographics and reimbursement expansion parameters. Modeled dimensions include product material tier, sterility requirements, patient mobility profiles, and regional regulatory cluster stringency.
The model holds under stable EU MDR implementation timelines and REACH phthalate restriction enforcement; deviation in notified body capacity constraints or single-use plastics directive acceleration would shift substitution timelines and inventory valuation assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Blood Processing Disposables Market
Medical Supplies
Lavage Kits Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Medical Tourniquets Market