
 Fluidizers in Plasterboard Market | 2026-2036
Fluidizers in Plasterboard Market Size, Share, and Industry Trends Forecast 2026-2036
Fluidizers in Plasterboard Market Analysis
Specialty chemical distribution is tilting toward direct manufacturer-to-board producer relationships as plasterboard makers seek formulation control. Saint-Gobain leverages captive supply chains across European gypsum operations. Knauf Group anchors volume through integrated fluidizer blending in its wallboard plants. Georgia-Pacific LLC competes via regional distribution partnerships with independent additive suppliers.
Fluidizers in plasterboard are surface-active additives that reduce water demand in gypsum slurry processing, typically comprising sulfonated polymers or ethoxylated compounds that enable low-density board formation at reduced binder ratios. Their primary purpose is to improve flow characteristics during continuous casting lines while maintaining compressive strength below 1.5 MPa for standard wallboard grades. Polymer fluidizers dominate formulation value pools due to patent-protected molecular architectures, while glycol-based variants capture fastest-growing share as manufacturers reformulate to meet ECHA substance restrictions. Wallboard manufacturing absorbs the majority of volume, though fire-resistant board applications command premium positioning through higher active loading requirements.
REACH registration requirements and ECHA candidate list screenings constrain raw material selection for European producers, while EPA TSCA oversight governs new chemical introductions in US manufacturing. The EU Construction Products Regulation mandates CE marking for plasterboard performance declarations, directly influencing fluidizer efficacy testing protocols. Stakeholders must monitor evolving substance restrictions and decide between regional formulation customization versus global platform standardization.
Market Dynamics
Specialty additive chemistry in gypsum wallboard is fragmenting along regulatory fault lines, with European REACH restrictions forcing molecular redesign while North American builders prioritize lightweight density targets for residential framing efficiency.
Growth Catalysts
- EU Green Deal renovation mandates:France and Germany face binding targets to retrofit existing building stock, elevating demand for reformulated fluidizers that enable thinner, lighter board profiles without thermal bridging.
- Continuous casting line automation:Slurry flow optimization systems now integrate real-time viscosity monitoring, creating specification pull for polymer fluidizers with predictable shear-thinning behavior under variable line speeds.
- Wildfire-resistant construction codes:California's Title 24 and similar ordinances in Colorado and Texas mandate enhanced fire-rated assemblies, requiring higher active loading of fluidizers in Type X and C gypsum cores.
Market Restraints
- Ethylene oxide feedstock volatility:Ethoxylated fluidizer precursors track petrochemical spreads, compressing formulation margins when naphtha crackers run at reduced utilization in Gulf Coast complexes.
- ECHA substance restriction timelines:Candidate list screenings for persistent, bioaccumulative, and toxic substances force multi-year reformulation cycles before sunset dates, freezing R&D budgets in uncertainty.
- Portland cement-lime plaster substitution:Exterior cladding markets in Mediterranean climates increasingly specify traditional wet trades over gypsum board, displacing fluidizer demand in commercial facade applications.
Strategic Opportunities
- India's affordable housing pipeline:The Pradhan Mantri Awas Yojana urban mission targets 11.2 million dwelling units, creating first-mover advantage for glycol-based fluidizers adapted to monsoon humidity and variable raw gypsum quality.
- Prefabricated panel manufacturing:Offsite construction factories in the UK and Netherlands require extended slurry pot life for robotic pouring stations, favoring slow-release fluidizer blends with retarded set characteristics.
- Carbon border adjustment mechanisms:The EU CBAM phase-in from 2026 creates competitive opening for fluidizer producers with verified low-carbon ethoxylation routes or bio-based glycol feedstocks.
Industry Challenges
- Formulation chemist scarcity:Gypsum-specific rheology expertise concentrates among retiring technical staff at legacy European additive houses, constraining product development velocity for mid-tier suppliers.
- CE marking test protocol divergence:National application documents in Italy and Spain interpret EN 520 compressive strength requirements differently, forcing redundant fluidizer validation campaigns for pan-European product registration.
- Legacy ERP integration with batch automation:Wallboard plants running 1990s distributed control systems face data architecture gaps when connecting fluidizer dosing pumps to modern manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluidizers in Plasterboard Market |
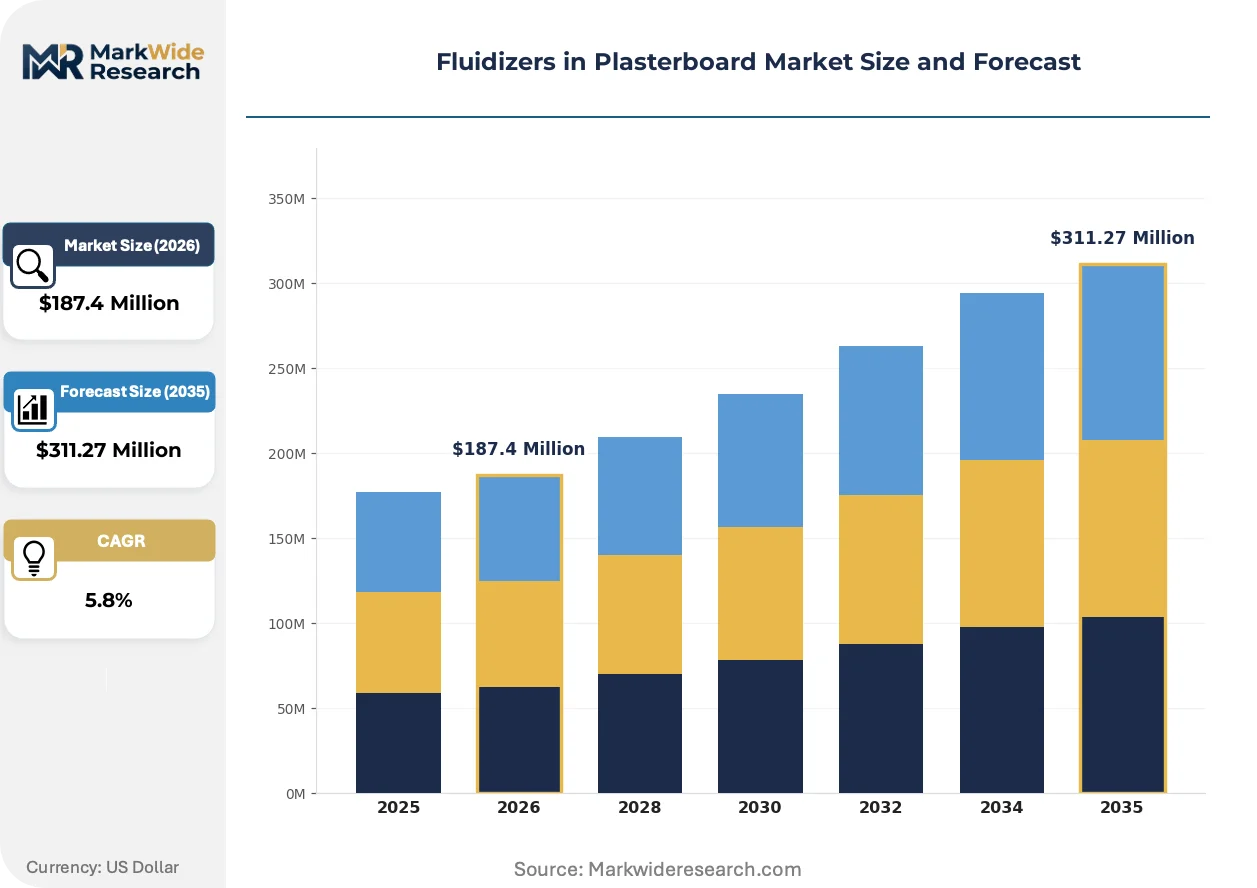
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Fluidizers, Glycol-based Fluidizers, Synthetic Fluidizers, Organic Fluidizers Application: Wallboard Manufacturing, Fire-resistant Board, Soundproof Board, Lightweight Board End User: Construction Companies, Contractors, Manufacturers, Retailers Form: Powder, Liquid, Granular, Concentrate |
| Companies Covered | Etex Group, National Gypsum Company, Saint-Gobain, Yoshino Gypsum Co., Ltd., Rockwool International, USG Corporation, Georgia-Pacific LLC, CertainTeed Corporation, Knauf Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluidizers in Plasterboard Market Emerging Trajectories
Active molecular engineering is compressing the trade-off between water reduction and mechanical strength, enabling next-generation gypsum cores that satisfy both sustainability metrics and building code performance floors.
Polyether-polycarboxylate comb architectures are hybridizing sulfonate backbone chemistry with grafted polyethylene oxide side chains, delivering 25-30% water demand reduction without the set retardation typical of naphthalene condensates. Mid-tier wallboard producers in Poland and the Czech Republic are adopting these hybrids fastest, pressured by energy costs that favor lower slurry water content and faster dryer throughput.
REACH authorization requirements for 1,2-dichloroethane as a process solvent in ethoxylate manufacturing are forcing European fluidizer suppliers to certify alternative synthesis routes or import finished products from non-EU jurisdictions. The regulatory friction concentrates most acutely on fire-resistant board grades, where high ethoxylate loading historically delivered the required air entrainment and pore structure.
Specification authority is migrating from distributor technical sales representatives to plasterboard plant process engineers, who now negotiate directly with fluidizer manufacturers for customized viscosity curves and set-time windows. This disintermediation is most advanced in Germany, where Knauf and Saint-Gobain operate captive blending facilities, and is now penetrating the US Southeast as Georgia-Pacific consolidates supplier panels at its Atlanta-area wallboard complex.
Fluidizers in Plasterboard Market Segmentation
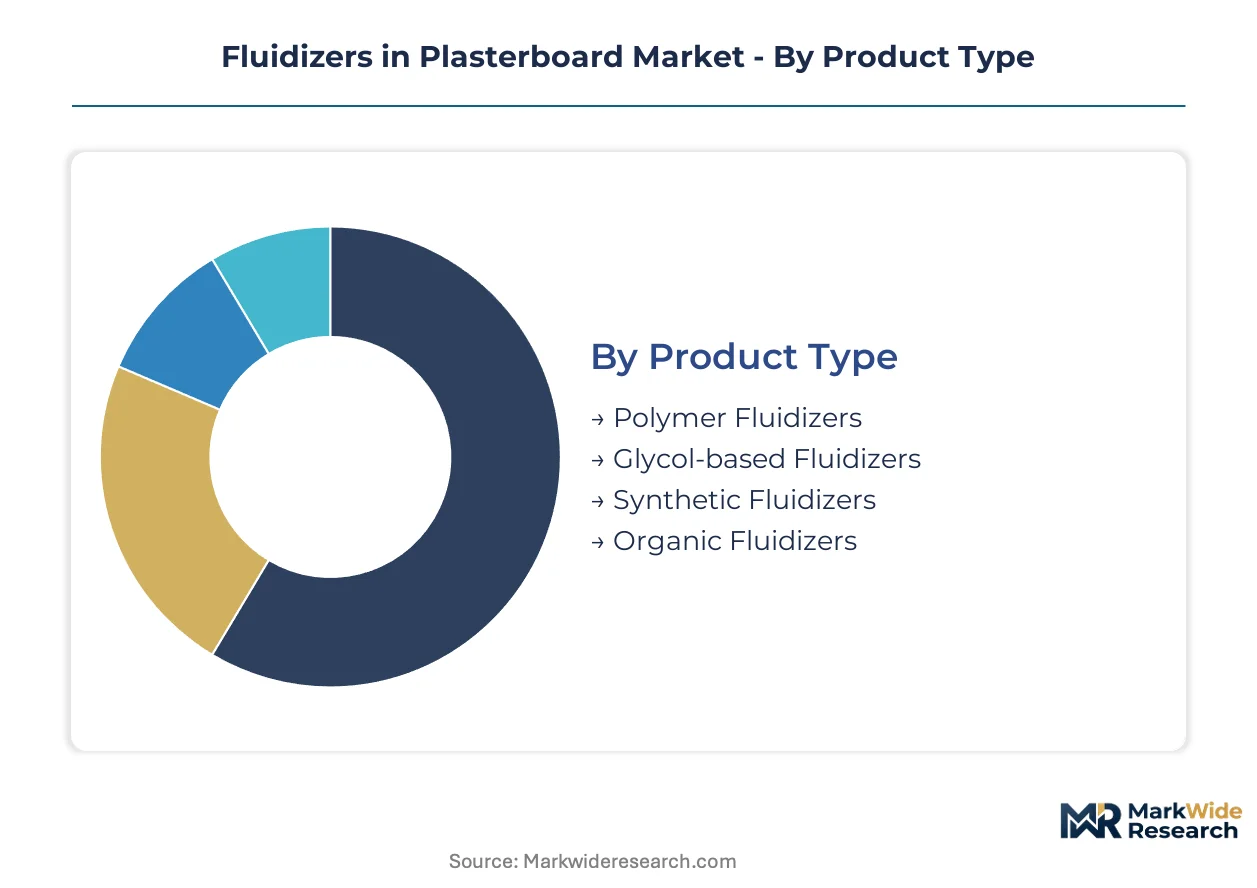
Fluidizer segmentation in plasterboard markets tracks divergent formulation requirements across regulatory jurisdictions and end-use performance specifications. Each dimension—chemistry, application, customer channel, and physical form—carries distinct margin profiles and technical barriers that reshape supplier positioning.
Product Type:
Cost tier stratification separates patent-protected molecular architectures from commodity glycol alternatives, with reformulation pressures from ECHA substance restrictions driving portfolio rebalancing.
- Polymer Fluidizers:Sulfonated naphthalene condensates and polyether-polycarboxylate comb polymers deliver 25-30% water demand reduction through steric stabilization mechanisms. Specification authority concentrates with Knauf and Saint-Gobain captive blending facilities in Germany, where energy costs reward lower slurry moisture and accelerated dryer throughput.
- Glycol-based Fluidizers:Ethoxylated compounds and propylene glycol derivatives enable REACH-compliant formulations as ECHA candidate list screenings restrict legacy chemistries. Demand is climbing fastest in France and Italy where renovation mandates under the EU Green Deal require thinner, lighter board profiles without thermal bridging penalties.
- Synthetic Fluidizers:Laboratory-engineered molecular architectures with tunable side-chain densities address niche fire-resistant grades.
- Organic Fluidizers:Bio-derived alternatives from renewable feedstocks target CBAM-compliant supply chains for EU export markets.
Polymer fluidizers command the established base. The steepest expansion runs through glycol-based alternatives.
Application:
Volume concentration varies sharply by board grade, with standard wallboard absorbing raw tonnage while specialty cores extract premium positioning through higher active loading requirements.
- Wallboard Manufacturing:Continuous casting lines for standard gypsum cores consume the majority of fluidizer volume, with slurry flow optimization systems integrating real-time viscosity monitoring. Procurement concentrates among integrated producers in Poland and the Czech Republic seeking predictable shear-thinning behavior under variable line speeds.
- Fire-resistant Board:Type X and C gypsum cores require elevated air entrainment and controlled pore structure through higher ethoxylate loading, commanding formulation premiums. California's Title 24 and Colorado wildfire ordinances mandate enhanced fire-rated assemblies, pulling specification toward REACH-authorized molecular architectures.
- Soundproof Board:High-density cores with tuned acoustic damping properties use specialized viscosity modifiers.
- Lightweight Board:Low-density formulations for residential framing efficiency prioritize water reduction without compressive strength sacrifice.
Wallboard manufacturing anchors volume throughput. Fire-resistant board delivers the strongest margin expansion.
End User:
Customer type determines channel economics, with direct manufacturer relationships displacing distributor intermediaries as formulation control migrates to plant process engineers.
- Construction Companies:Large-scale developers and general contractors specify fluidizer-enabled board grades through performance-based procurement frameworks, with India's Pradhan Mantri Awas Yojana urban mission creating specification pull for humidity-adapted glycol formulations.
- Contractors:Installation-focused trades prioritize board handling characteristics and set-time predictability on job sites.
- Manufacturers:Plasterboard producers with captive additive blending—exemplified by Georgia-Pacific's Atlanta-area consolidation—negotiate directly with fluidizer suppliers for customized viscosity curves.
- Retailers:Distribution intermediaries retain residual influence in fragmented regional markets lacking integrated supply chains.
Manufacturers control the deepest specification relationships. Construction companies in emerging markets are gaining procurement influence fastest.
Form:
Physical state selection balances dosing precision, storage logistics, and integration with legacy plant automation systems running 1990s distributed control architectures.
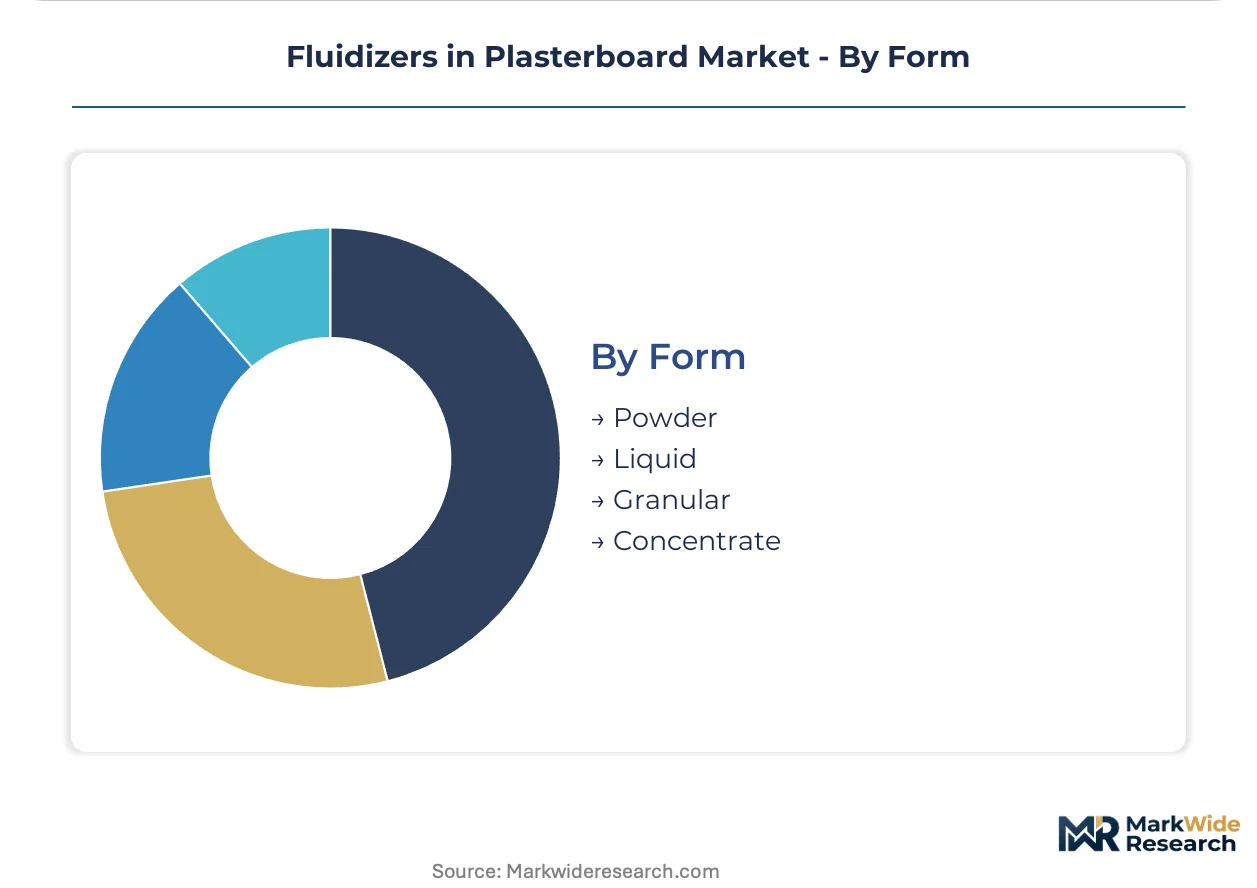
- Powder:Dry-blend fluidizers enable stable shelf life and bulk pneumatic conveying into wallboard plants, with adoption concentrated in Germany and France where renovation activity sustates elevated throughput.
- Liquid:Pumpable concentrates allow precise metering through automated dosing skids, preferred by UK and Netherlands prefabricated panel factories requiring extended slurry pot life for robotic pouring stations.
- Granular:Free-flowing particulate forms reduce dust exposure during handling.
- Concentrate:High-active formulations minimize transport costs and enable on-site dilution.
Powder forms dominate established plant infrastructure. Liquid concentrates are penetrating automated facilities most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail network underwrites Germany's centrality in European plasterboard chemistry, while the Port of Rotterdam's bulk chemical terminals anchor feedstock flows for northwest European fluidizer production.
Germany
Renovation mandates under the EU Green Deal drive reformulation toward REACH-compliant glycol-based fluidizers in residential retrofit projects. ECHA substance restriction timelines force multi-year molecular redesign cycles before sunset dates. The North Rhine-Westphalia chemical cluster around Leverkusen and Düsseldorf concentrates captive blending operations for integrated wallboard producers.
United States
Wildfire-resistant construction codes in California, Colorado, and Texas mandate enhanced fire-rated gypsum assemblies requiring elevated fluidizer loading. EPA TSCA oversight governs new chemical introductions in Gulf Coast manufacturing complexes. The Atlanta-area wallboard corridor in Georgia anchors regional supplier consolidation and direct manufacturer negotiations.
France
Binding EU Green Deal retrofit targets elevate demand for thinner, lighter board profiles without thermal bridging penalties. CE marking under the EU Construction Products Regulation mandates performance declaration protocols for fluidizer efficacy testing. The Paris Basin construction corridor sustains elevated renovation throughput driving specification pull.
India
The Pradhan Mantri Awas Yojana urban mission targets 11.2 million dwelling units, creating specification pull for humidity-adapted glycol formulations. BIS standards govern construction chemical quality benchmarks for affordable housing materials. The Mumbai-Pune industrial corridor concentrates emerging plasterboard manufacturing capacity.
United Kingdom
Offsite construction factories in the Midlands and southeast require extended slurry pot life for robotic pouring stations. The country's national building safety regulator enforces post-Grenfell fire performance standards for wallboard assemblies. The East Midlands prefabricated panel cluster favors slow-release fluidizer blends with retarded set characteristics.
Fluidizers in Plasterboard Market Vendor Landscape
On the supply side, the industry is consolidating around integrated gypsum-to-additive platforms and direct manufacturer relationships that displace distributor intermediaries. Specialty chemical distribution tilts toward formulation control partnerships as plasterboard makers seek customized viscosity curves. Three archetypes dominate: captive blending facilities operated by multinational wallboard producers, independent additive suppliers with regional distribution partnerships, and hybrid polymer-glycol specialists navigating REACH compliance. Capacity expansion and strategic partnerships represent the dominant competitive vectors as players position for EU Green Deal renovation cycles and India's affordable housing pipeline.
Among European-integrated producers, Saint-Gobain and Knauf Group exemplify the captive blending archetype, operating in-house additive formulation within their wallboard manufacturing networks. Georgia-Pacific LLC occupies a position representing the North American regional consolidation model, negotiating directly with fluidizer suppliers for plant-specific customization. These three anchors illustrate how specification authority migrates from distributor technical representatives toward process engineers at manufacturing complexes.
| Leading Market Players |
|---|
| Etex Group |
| National Gypsum Company |
| Saint-Gobain |
| Yoshino Gypsum Co., Ltd. |
| Rockwool International |
| USG Corporation |
| Georgia-Pacific LLC |
| CertainTeed Corporation |
| Knauf Group |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European ethoxylate production capacity is compressing spot pricing for glycol-based fluidizer precursors while simultaneously pushing suppliers toward long-term offtake contracts with captive blenders at integrated wallboard plants. This utilization dynamic rewards polymer fluidizer specialists with patented molecular architectures, who command formulation premiums as commodity glycol alternatives face margin erosion from REACH-driven reformulation cycles.
Pricing Analysis
Volume-discount tiering structures separate captive blending arrangements at Knauf and Saint-Gobain facilities from spot-market procurement by independent wallboard producers. Price differentiation rests on certification grade—REACH-authorized molecular architectures versus candidate-list alternatives—and customization depth for plant-specific viscosity curves. Cost compression in glycol-based tiers is intensifying because ethylene oxide feedstock volatility tracks Gulf Coast petrochemical spreads. Regional distributors in fragmented markets exhibit highest price sensitivity, while integrated manufacturers with captive blending show lowest sensitivity due to formulation lock-in effects.
Supply Chain Analysis
Export-control regime restrictions on dual-use chemical process technology limit European fluidizer producers from licensing advanced ethoxylation reactor designs to Indian and Southeast Asian manufacturing partners. Geographic supply concentration centers on Germany, the United States, and China, with the North Rhine-Westphalia chemical cluster and Gulf Coast petrochemical complexes anchoring feedstock flows. Raw material dependencies draw from ethylene oxide, naphthalene sulfonate precursors, and propylene glycol derivatives. Single-source vulnerability runs through specialized sulfonation reactor vessels concentrated among legacy European additive houses. Distribution runs through direct manufacturer relationships displacing distributor intermediaries in Germany and the US Southeast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluidizer formulation services represent a service-attach opportunity expanding faster than base chemical supply, as plasterboard producers increasingly outsource viscosity curve customization and regulatory compliance documentation to specialist partners.
For Market Incumbents: Entrench specification authority by deepening captive blending relationships with process engineers at manufacturing complexes, while investing in REACH-authorized molecular architectures ahead of ECHA sunset dates. The threat of glycol-based commodity substitution from Asian entrants demands accelerated patent filing around polyether-polycarboxylate comb architectures. Backward integration into ethoxylation capacity at the Port of Rotterdam secures feedstock cost control.
For New Entrants and Emerging Players: Establish a beachhead in India's affordable housing segment by adapting humidity-tolerant glycol formulations for the Pradhan Mantri Awas Yojana pipeline, where BIS standards enforcement remains nascent. The most penetrable white space sits in prefabricated panel manufacturing across the UK Midlands, where extended slurry pot life requirements outpace incumbent response times. A technical service-led go-to-market approach—embedding formulation chemists at customer plants—overcomes brand disadvantage against established European suppliers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH compliance costs and ECHA authorization timelines create durable moats around authorized molecular architectures that commodity producers cannot replicate. Acquisition targets should concentrate on hybrid polymer-glycol specialists with verified low-carbon ethoxylation routes positioned for EU CBAM phase-in. The signal to watch is accelerated plant engineer turnover at legacy additive houses, which would signal capability scarcity opening for consolidated platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethoxylation Capacity | Captive supply of REACH-compliant glycol precursors insulates margin from petrochemical spread volatility at Rotterdam terminals. |
| Long-term Supply Agreement with Integrated Producers | Direct formulation partnerships with Georgia-Pacific's Atlanta complex lock out distributor competitors from specification influence. |
| Green Manufacturing Transition | Bio-based glycol feedstocks and verified low-carbon ethoxylation routes position for EU CBAM compliance from 2026. |
| Joint Venture for Regional Production | Local blending facilities in India's Mumbai-Pune corridor address monsoon humidity adaptation without cross-border regulatory friction. |
| Capacity Expansion in Fire-Resistant Grades | Enhanced loading capacity for Type X and C cores captures California Title 24 specification pull for wildfire-resistant assemblies. |
Methodological Framework
Operator-level perspectives from plasterboard plant process engineers, fluidizer formulation chemists, specialty chemical procurement leads, and ECHA regulatory affairs specialists anchored the qualitative base for this study. Primary interviews with technical directors at captive blending facilities in Germany and distribution channel partners in France were cross-referenced against secondary validation from SEC 10-K filings of integrated wallboard producers, Cefic chemical industry reports, customs trade data for ethoxylate precursor flows, and EU Construction Products Regulation performance declaration databases. Bottom-up volume modeling triangulated against top-down market sizing across chemistry type and application segments.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning fluidizer chemistry class, board grade application, end-user procurement channel, and physical form factor. CAGRs were derived from fitted growth curves applied to base-year volume estimates, incorporating industry-specific inputs including EU Green Deal renovation mandate trajectories, continuous casting line automation penetration rates, and wildfire-resistant construction code adoption timelines across US jurisdictions.
Stress conditions across ethylene oxide feedstock price bands, ECHA substance restriction sunset date delays, and Portland cement-lime plaster substitution rates in Mediterranean markets were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and construction activity cyclicality. Material shifts in REACH authorization timelines or EU CBAM carbon border adjustment scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Tetrafluoroethane (R134A) Refrigerant Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Profenofos Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Pressure Filter Market
Industrial Chemicals
Hydrogen Silicone Fluid Market
Industrial Chemicals
Sulfur Recovery Technology Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Drum Melters Market