
 Chlorophyll Color Market | 2026-2036
Chlorophyll Color Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorophyll Color Market Outlook
Clean-label food and beverage manufacturers are unwinding legacy reliance on synthetic dyes, redirecting procurement budgets toward plant-derived colorants. Chr. Hansen leverages its fermentation expertise to anchor supply security for high-purity chlorophyll extracts. Sensient Technologies competes through vertical integration from raw leaf sourcing to finished color systems. DDW The Color House specializes in custom chlorophyll blends that navigate regional regulatory variance.
Chlorophyll color denotes green pigments extracted from alfalfa, spinach, or nettle sources, standardized to specified copper content and stabilized against pH degradation for industrial use. The natural extract segment dominates volume as food processors reformulate away from azo dyes under EFSA and FDA scrutiny. Powder form leads in logistics efficiency for bulk ingredient buyers, while liquid form captures premium positioning in beverage applications where dispersion speed governs production throughput. Nutraceuticals represents the fastest-growing application as supplement brands adopt chlorophyll for antioxidant positioning.
EFSA purity standards, FDA color additive regulations, and EU REACH chemical restrictions collectively elevate compliance costs for synthetic alternatives while widening chlorophyll's competitive aperture. The USDA National Organic Program and Japan's MHLW food additive standards further segment export qualification requirements. Stakeholders must monitor regulatory harmonization progress between the EU Green Deal implementation and emerging state-level clean-label mandates in the United States.
Market Dynamics
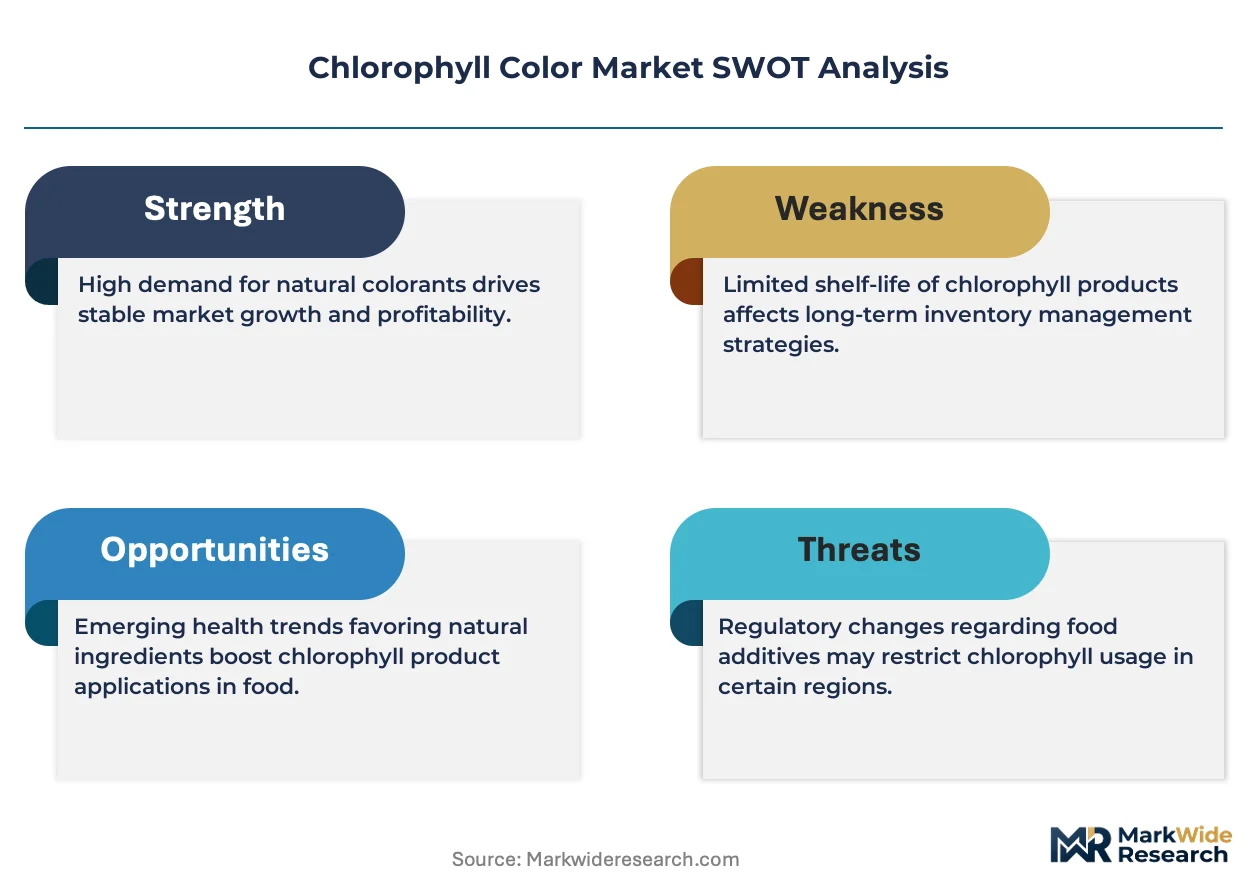
Clean-label mandates from the EU Green Deal and FDA color additive scrutiny are compressing synthetic dye viability, redirecting procurement budgets toward plant-derived alternatives with traceable supply chains.
Growth Catalysts
- EU REACH restrictions:Chemical authorization barriers for azo dyes are eliminating incumbent colorants from food-contact applications, expanding chlorophyll's addressable market in confectionery and beverage formulations.
- Nutraceutical antioxidant positioning:Supplement brands are adopting chlorophyll extracts for functional health claims, creating incremental demand beyond traditional coloring applications.
- German clean-label premiums:Retailers in Germany command price positioning for products with natural ingredient declarations, incentivizing manufacturer reformulation across Central European supply chains.
Market Restraints
- Alfalfa input volatility:Weather-driven crop yields and agricultural commodity pricing create margin pressure for extractors dependent on specific leaf sources.
- pH stabilization costs:Technical limitations in thermal and acidic environments require expensive encapsulation or copper-complexing processes that erode cost parity with synthetics.
- Chinese extraction concentration:Raw material processing capacity clusters in specific provinces, creating geographic supply risk and qualification complexity for Western buyers.
Strategic Opportunities
- India FSSAI natural colorant pathway:Regulatory streamlining for plant-derived additives in processed foods opens underpenetrated volume in South Asian markets.
- Japan METI functional food convergence:Chlorophyll integration with antioxidant-labeled beverages aligns with aging-population health positioning in Japanese retail.
- Direct-to-manufacturer digital procurement:B2B platform adoption by mid-size food processors is disintermediating traditional distributor channels for colorant sourcing.
Industry Challenges
- EFSA purity certification timelines:Batch-specific heavy metal and copper content validation creates 12-18 month qualification delays for new extract suppliers.
- Legacy formulation retooling:Beverage manufacturers face capital expenditure for dispersion equipment compatible with oil-soluble chlorophyll variants versus water-based synthetics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorophyll Color Market |
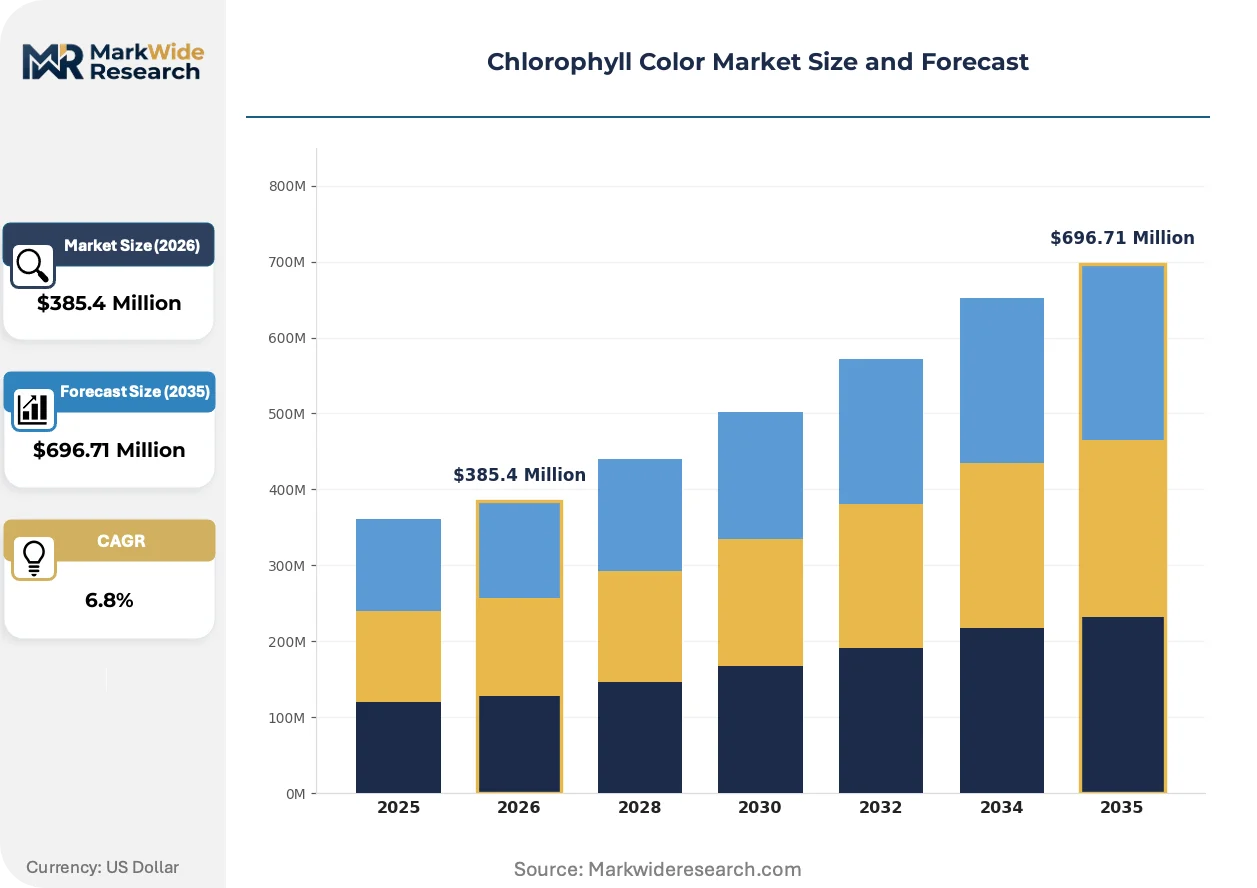
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extract, Synthetic Variant, Liquid Form, Powder Form Application: Cosmetics, Food & Beverage, Nutraceuticals, Agriculture End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online Retail, Brick-and-Mortar, Wholesalers, Direct Sales |
| Companies Covered | Sensient Technologies, Chr. Hansen, DDW The Color House, Naturex, Döhler Group, Kalsec, Archer Daniels Midland Company, GNT Group, Roha Dyechem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorophyll Color Market Strategic Shifts
Extraction technology advances and regulatory harmonization pressures are compressing production timelines while expanding application scope beyond conventional food coloring into functional positioning.
Micro-encapsulation technology is miniaturizing chlorophyll particles to sub-micron scales, enabling stable dispersion in acidic beverages and transparent packaging. Sports drink manufacturers in North America are adopting these systems at accelerated procurement cycles. The technology is miniaturizing particle size thresholds that previously restricted chlorophyll to opaque dairy and confectionery applications.
EFSA purity standards and FDA color additive regulations are tightening in parallel, elevating compliance documentation burdens for synthetic alternatives while widening competitive aperture for certified natural extracts. Food processors face divergent testing protocols across Atlantic markets. Nutraceutical applications in Germany and France are responding with dedicated supply chain segregation for pharmaceutical-grade chlorophyll lots.
Buyer concentration among multinational food processors is consolidating supplier qualification lists, favoring extractors with multi-jurisdiction certification portfolios. Mid-size regional manufacturers are losing distributor access as procurement centralizes at headquarters level. This pattern is most visible in Nordic markets where retail private-label concentration accelerates vendor rationalization programs.
Chlorophyll Color Market Segmentation
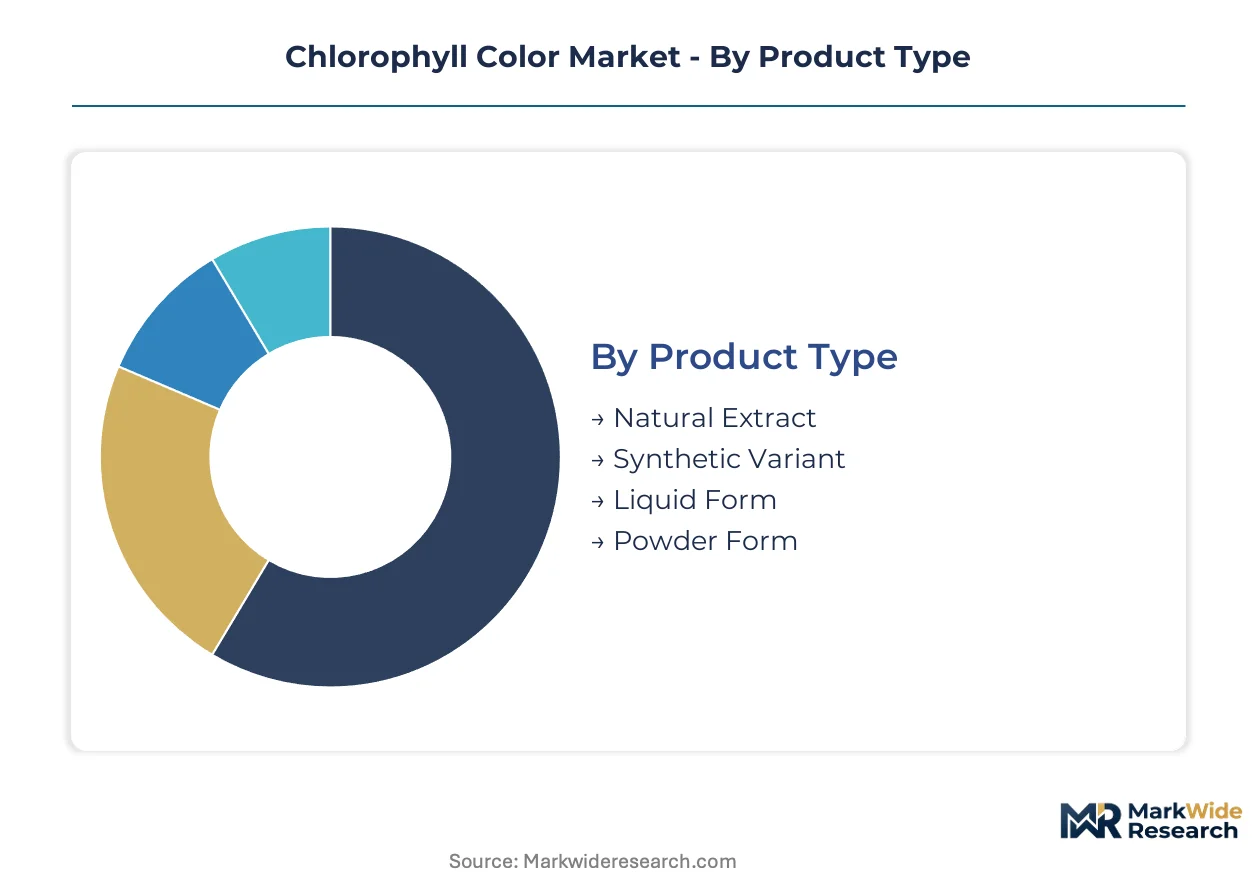
Chlorophyll color segmentation reveals distinct margin architectures across extraction methods and end-use applications. Procurement patterns diverge sharply between bulk food processors seeking logistics efficiency and nutraceutical brands prioritizing purity certification.
Product Type:
Margin pools concentrate in stabilized extract formats where copper-complexing and encapsulation technologies create differentiation against commodity alternatives.
- Natural Extract:Alfalfa and spinach-derived pigments standardized to EFSA copper content specifications. Food manufacturers in Germany and France are redirecting procurement budgets here as EU REACH restrictions eliminate azo dye alternatives.
- Synthetic Variant:Chemically synthesized copper chlorophyllin compounds. Cost-sensitive confectionery producers in India leverage this for price positioning under FSSAI streamlining, though clean-label penalties in premium European retail constrain expansion.
- Liquid Form:Oil-soluble dispersions for beverage applications requiring rapid production throughput. Sports drink manufacturers in North America favor this format despite capital retooling costs for dispersion equipment.
- Powder Form:Spray-dried extracts optimized for logistics efficiency in bulk ingredient procurement. Dominates volume in Central European dairy and bakery supply chains.
The dominant share belongs to Natural Extract, while Liquid Form is closing the gap fastest.
Application:
Volume concentration follows reformulation mandates, with regulatory pressure creating tiered demand structures across end-use sectors.
- Food & Beverage:Confectionery, dairy, and beverage reformulations driving procurement shifts. EFSA and FDA parallel scrutiny of synthetic dyes is compressing incumbent viability across Atlantic markets.
- Nutraceuticals:Supplement brands adopting chlorophyll for antioxidant health claims. Pharmaceutical-grade supply chain segregation in Germany and France commands premium positioning.
- Cosmetics:Topical formulations leveraging natural green pigments. Clean-label beauty positioning in Japanese retail aligns with METI functional convergence trends.
- Agriculture:Foliar feed and plant health applications. Remains niche relative to human-consumption segments.
Food & Beverage anchors current volume, though Nutraceuticals demonstrates the steepest expansion trajectory.
End User:
Buyer concentration patterns determine channel power, with procurement centralization reshaping supplier access tiers.
- Manufacturers:Multinational food processors consolidating qualification lists. Headquarters-level procurement in Nordic markets is accelerating vendor rationalization programs.
- Distributors:Traditional intermediaries facing disintermediation as B2B platforms enable direct-to-manufacturer digital procurement among mid-size processors.
- Retailers:German and French retail private-label concentration driving specification standardization upstream.
- Consumers:Direct purchase limited to specialty supplement and cosmetic channels. Represents smallest volume pool.
Manufacturers control procurement volume, while Distributors are losing share fastest to platform-enabled direct sourcing.
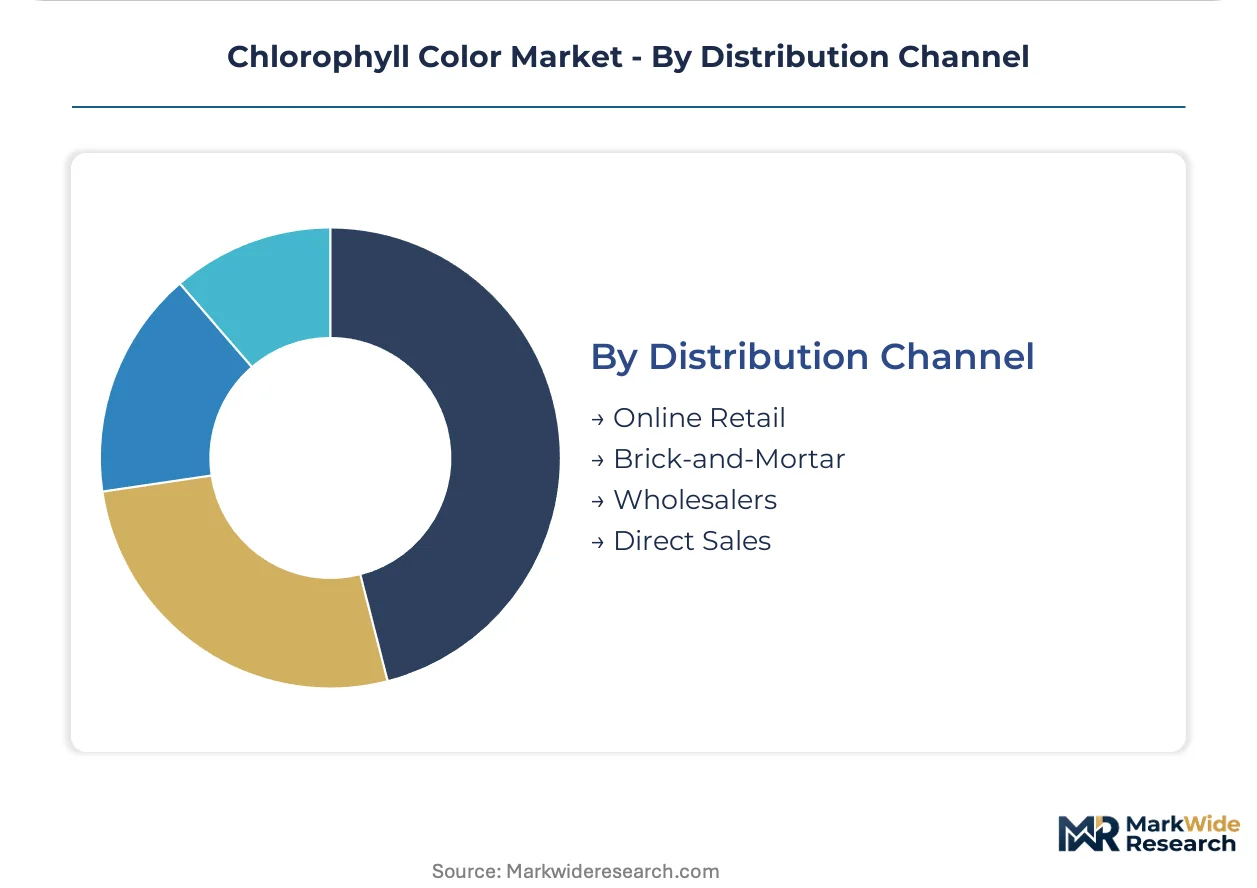
Distribution Channel:
Channel economics reflect customer scale segmentation, with digital infrastructure investments reshaping mid-market access.
- Direct Sales:Long-term supply agreements between extractors and multinational processors. Chr. Hansen and Sensient Technologies anchor relationships through multi-jurisdiction certification portfolios.
- Wholesalers:Regional ingredient distributors serving mid-size manufacturers. Losing ground to platform consolidation in North American and European markets.
- Online Retail:B2B platform adoption accelerating among mid-size food processors. Disintermediates traditional distributor channels for colorant sourcing.
- Brick-and-Mortar:Physical distributor networks remaining relevant for qualification-heavy pharmaceutical-grade transactions. EFSA batch-specific validation creates friction for digital-only procurement.
Direct Sales commands the largest volume commitment, though Online Retail is gaining share most rapidly among emerging processor segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese extraction facilities supply chlorophyll concentrates to German and North American food processors, creating a trans-Pacific trade corridor that channels raw material through Rotterdam and Hamburg ports for EU distribution.
Germany
Retail private-label concentration in Berlin and Hamburg drives specification standardization for clean-label formulations. EU REACH chemical authorization barriers eliminate azo dye alternatives from food-contact applications. The Baden-Württemberg industrial corridor hosts pharmaceutical-grade chlorophyll segregation facilities serving nutraceutical exporters.
United States
Sports drink manufacturers in California and Texas adopt micro-encapsulated chlorophyll systems for acidic beverage stabilization. FDA color additive scrutiny compresses synthetic dye viability across Atlantic markets. Chicago-based procurement headquarters consolidate supplier qualification lists, accelerating vendor rationalization programs.
China
Alfalfa processing capacity clusters in specific provinces serving Western extract buyers. The country's national food safety regulator maintains dual carbon goals that shape agricultural input sourcing. Yangtze River Delta chemical parks concentrate copper-complexing and encapsulation technology production for export markets.
India
FSSAI regulatory streamlining for plant-derived additives opens processed food volume in Maharashtra and Gujarat. Cost-sensitive confectionery producers leverage synthetic chlorophyllin variants for domestic price positioning. Mumbai and Ahmedabad distribution hubs face disintermediation pressure from B2B platform adoption.
Japan
METI functional food convergence aligns chlorophyll integration with antioxidant-labeled beverages targeting aging-population health positioning. Tokyo and Osaka retail channels command premium positioning for natural ingredient declarations. Kansai industrial zones host beverage formulation facilities retooling for oil-soluble chlorophyll dispersion equipment.
Chlorophyll Color Market Competitive Environment
Listed leaders compete with private specialists across certification portfolios and supply chain control dimensions. The vendor base stratifies into three tiers: multinational extractors with multi-jurisdiction regulatory filings, regional specialists with backward integration into leaf sourcing, and commodity traders dependent on Chinese processing intermediaries. Strategic moves concentrate on M&A for certification asset accumulation and capacity expansion in copper-complexing stabilization technology.
Within the fermentation-anchored tier, Chr. Hansen occupies a position exemplifying supply security through biotechnology expertise. Sensient Technologies represents vertical control from raw leaf procurement through finished color system delivery. DDW The Color House sits within the custom formulation specialist archetype, navigating regional regulatory variance through blend-specific compliance architecture.
| Leading Market Players |
|---|
| Sensient Technologies |
| Chr. Hansen |
| DDW The Color House |
| Naturex |
| Döhler Group |
| Kalsec |
| Archer Daniels Midland Company |
| GNT Group |
| Roha Dyechem |
| Others |
Value Chain & Pricing Dynamics
Alfalfa-to-spinach substitution in European extraction facilities simultaneously redistributes sourcing geography toward German and French leaf processors while compressing copper-complexing cost premiums against synthetic chlorophyllin alternatives. This input shift concentrates pricing power among stabilized extract specialists holding EFSA certification portfolios, leaving commodity traders exposed to margin erosion from pH stabilization technology gaps.
Pricing Analysis
Encapsulation-technology pricing gaps separate micro-encapsulated premium tiers from conventional extract grades and emerging fermentation-derived alternatives. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels anchors contract structures, with EFSA batch-validation costs driving differentiation between certified and uncertified lots. Pricing pressure stems from alfalfa crop volatility in Chinese agricultural zones, compressing margins for non-integrated extractors. Cost-sensitive confectionery producers in India exhibit highest price elasticity, while German nutraceutical brands absorb premiums for pharmaceutical-grade segregation.
Supply Chain Analysis
Strategic stockpile preferences dominate chlorophyll procurement, with multinational food processors maintaining six-to-nine-month copper-complexed extract inventories against alfalfa harvest cycles. Supply concentrates in Chinese alfalfa processing provinces, German pharmaceutical-grade segregation facilities, and Indian synthetic chlorophyllin manufacturing hubs. Raw material flows draw from Yangtze River Delta chemical parks for encapsulation technology, Baden-Württemberg for EFSA-certified extraction, and Maharashtra for FSSAI-compliant distribution. Single-source vulnerability runs through Chinese alfalfa concentrate supply to Western extractors. Distribution runs through Rotterdam and Hamburg port consolidation for EU manufacturers, with direct sales agreements displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in mid-tier extractors lacking multi-jurisdiction certification, as EU REACH enforcement and FDA parallel scrutiny bifurcate demand between compliant and non-compliant supply tiers.
For Market Incumbents: Consolidate certification asset portfolios through targeted acquisition of EFSA-registered German extraction facilities, defending against fermentation-anchored biotechnology entrants. Prioritize backward integration into alfalfa sourcing cooperatives in drought-resilient agricultural zones, reducing exposure to Chinese crop volatility. Capacity expansion in copper-complexing stabilization technology creates margin defense against synthetic price competition. For New Entrants and Emerging Players: Differentiate on micro-encapsulation technology for acidic beverage applications, targeting North American sports drink manufacturers retooling dispersion equipment. White-space concentration sits in Indian FSSAI-compliant natural colorant supply, where regulatory streamlining outpaces domestic extraction capacity. Direct-to-manufacturer digital procurement platforms offer channel entry against entrenched distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European extraction specialists holding REACH-registered portfolios but lacking fermentation technology integration. Long-term viability hinges on pharmaceutical-grade nutraceutical segmentation, where antioxidant positioning commands sustainable premium structures. Acquisition targets center on copper-complexing technology holders with multi-jurisdiction regulatory filings. The inflection signal to watch is EFSA-FDA regulatory harmonization progress, which would compress qualification timelines and accelerate vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Certification Expansion | Multi-jurisdiction registration unlocks German and French retail private-label procurement centralization. |
| Micro-Encapsulation Capacity Buildout | Sub-micron particle production enables North American acidic beverage manufacturer adoption at scale. |
| Backward Integration into Alfalfa Sourcing | Captive agricultural supply reduces Chinese crop volatility exposure for Western extraction facilities. |
| Fermentation Technology Licensing | Biotechnology-derived chlorophyll extracts bypass agricultural input constraints for supply security. |
| B2B Platform Distribution Partnership | Digital procurement channels disintermediate traditional wholesalers for mid-size processor access. |
Study Parameters
Operator-level perspectives from extraction facility managers, EFSA regulatory consultants, food processor procurement directors, and nutraceutical brand supply chain heads anchored the qualitative base. Secondary validation drew from EU REACH registration databases, FDA color additive petitions, FSSAI regulatory notifications, and customs trade data for alfalfa concentrate flows. Bottom-up volume modeling triangulated against top-down expenditure analysis across application segments.
Sensitivity analysis tested forecast robustness against alfalfa price volatility scenarios, EFSA certification timeline variations, and synthetic dye regulatory restriction acceleration. Segmentation dimensions included extraction method, stabilization technology, application sector, and geographic regulatory cluster. CAGRs derived from regression analysis of historical procurement shifts correlated with regulatory enforcement milestones. Industry-specific inputs incorporated copper-complexing cost curves and micro-encapsulation technology adoption rates.
Material uncertainties — EFSA-FDA harmonization delays, Chinese agricultural policy shifts, and fermentation technology cost breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and extraction technology diffusion patterns. Revision becomes warranted when synthetic dye restriction intensity crosses thresholds triggering accelerated manufacturer reformulation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Ponceau 4R Colors Market
Dyes and Pigments
Classic Organic Pigments Market
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
Pigment Additive Film Market
Dyes and Pigments
White Pigment Market
Dyes and Pigments
Colorants Market
Dyes and Pigments
Ultramarine Pigments Market
Dyes and Pigments
Arylamide Pigments Market
Dyes and Pigments
Global Paint Pigments Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Middle East and Africa Hair Colorants Market
Dyes and Pigments
Dyes and Pigments Market
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Light Interference Pigments Market
Dyes and Pigments
Photochromic Pigments Market