
 Explosive Chargers Market | 2026-2036
Explosive Chargers Market Size, Share, and Industry Trends Forecast 2026-2036
Explosive Chargers Market Foresight
Polymer-based encapsulation materials is shifting away from traditional metal housings in detonator manufacturing, cutting unit weight and corrosion susceptibility. Orica Limited leverages integrated blasting services to control channel economics across Australasia. Dyno Nobel anchors its position through ammonium nitrate fuel oil supply chain ownership. Austin Powder Company specializes in site-specific emulsion formulations for hard-rock quarries.
Explosive chargers are devices that store and deliver controlled electrical or shock-wave energy to initiate detonators in blasting sequences, typically operating at voltage thresholds between 1.5 kV and 4.5 kV with millisecond-precision timing circuits. Their primary purpose is to synchronize multiple blast holes for optimal rock fragmentation while minimizing ground vibration and flyrock hazards. Electronic detonators within the technology segment command premium pricing due to programmable delay accuracy that reduces oversize boulders and improves diggability. Non-electric systems still dominate volume in developing mining corridors where infrastructure fragility favors shock-tube reliability. Mining companies as an end-user category represent the deepest margin pool, with long-term supply agreements locking in multi-year emulsion and initiation contracts.
The US Bureau of Alcohol, Tobacco, Firearms and Explosives enforces strict record-keeping and licensing that limits market entry to capital-intensive operators with proven safety protocols. Australia's Work Health and Safety Regulations mandate blast pattern modeling and post-shot vibration monitoring, which elevates demand for integrated charger-analyzer systems. Stakeholders must weigh electronic migration investments against the residual installed base of non-electric systems when allocating R&D budgets across product portfolios.
Market Dynamics
Electronic initiation systems are absorbing procurement budgets across underground mining corridors, forcing incumbent manufacturers to reconfigure product portfolios around programmable delay precision rather than shock-tube reliability.
Growth Catalysts
- EU Explosives Directive:Stricter storage and transport mandates are accelerating product redesign cycles, compelling manufacturers to invest in polymer-based encapsulation that reduces corrosion susceptibility.
- Copper belt depth extensions:Chilean open-pit operations are demanding precision blasting tools to manage rock fragmentation at increasing depths, pulling advanced charger configurations into South American supply chains.
- Electronic detonator technology:Programmable millisecond-precision timing circuits are enabling synchronized blast sequences that minimize ground vibration and improve diggability metrics.
Market Restraints
- Ammonium nitrate fuel oil supply concentration:Vertical ownership of precursor chemical networks by dominant suppliers limits price competition and creates single-source vulnerability for regional blasting contractors.
- ATF licensing friction:The US Bureau of Alcohol, Tobacco, Firearms and Explosives enforces capital-intensive safety protocol demonstrations that bar smaller operators from market entry.
- Non-electric installed base inertia:Developing mining corridors retain shock-tube infrastructure due to electrical grid fragility, compressing upgrade timelines for electronic systems.
Strategic Opportunities
- Australia's integrated service model:Blasting contractors bundling charger-analyzer systems with post-shot vibration monitoring are capturing long-term supply agreements under Work Health and Safety Regulations mandates.
- Hard-rock quarry specialization:Site-specific emulsion formulation partnerships between charger manufacturers and aggregate producers open margin pools outside commodity mining.
- Polymer housing convergence:Material science advances in corrosion-resistant encapsulation are enabling lighter unit designs that reduce transport costs and field handling complexity.
Industry Challenges
- Blast pattern modeling expertise shortage:Electronic migration requires skilled technicians capable of programming delay sequences and interpreting vibration data, creating recruitment bottlenecks in remote mining districts.
- Legacy system integration complexity:Mines operating mixed electronic and non-electric inventories face synchronization failures and inventory management friction during phased technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosive Chargers Market |
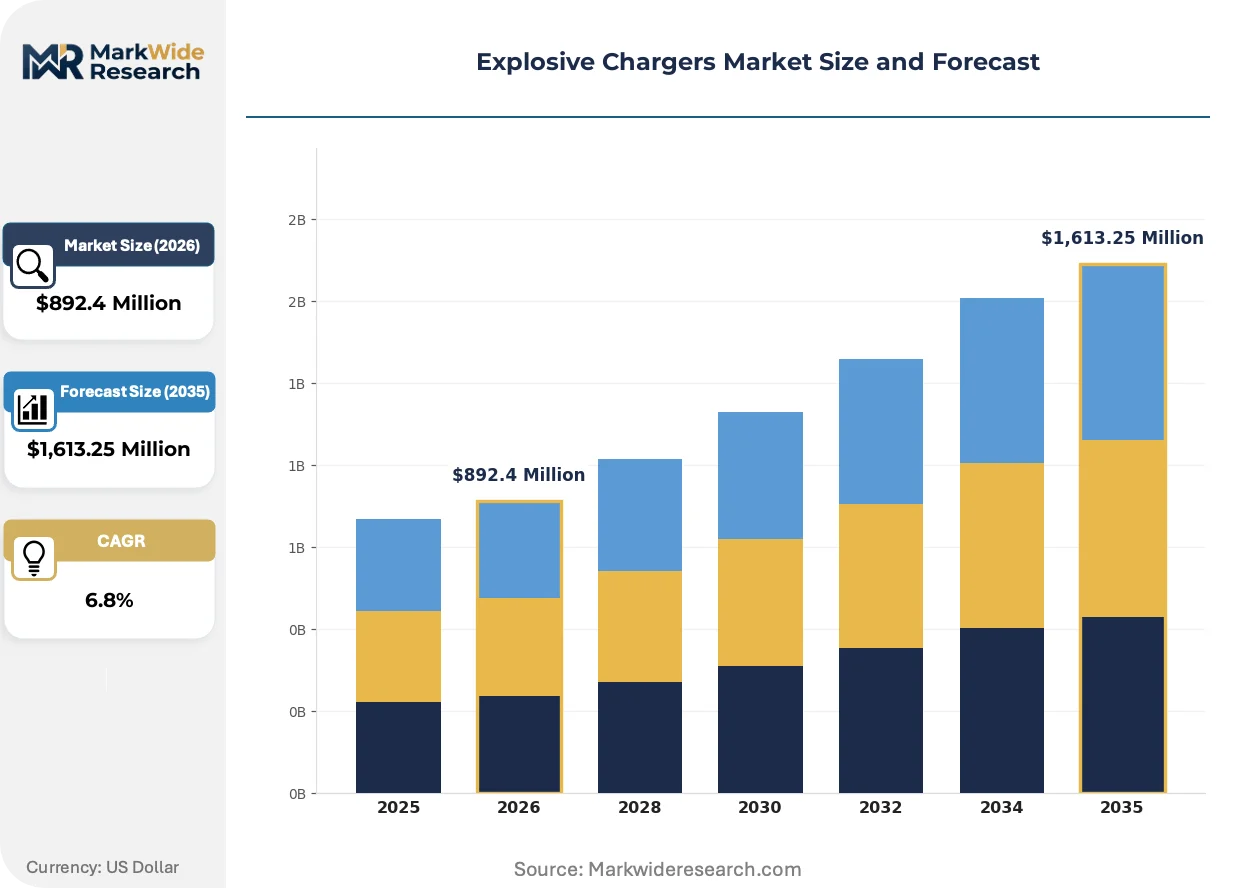
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detonators, Initiators, Boosters, Emulsions Application: Mining, Construction, Demolition, Oil & Gas Technology: Non-electric, Electric, Shock Wave, Hybrid End User: Mining Companies, Construction Firms, Military, Oil Companies |
| Companies Covered | Orica Limited, Dyno Nobel, Austin Powder Company, Enaex S.A., MaxamCorp Holding, Normet Group, Sandvik AB, Epiroc AB, MacLean Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosive Chargers Market Shifts & Advancements
Digital precision is displacing analog reliability as the primary purchasing criterion across mining procurement departments, reshaping how initiation system vendors structure service contracts and technical support offerings.
Solid-state timing circuits are absorbing development resources from electromechanical delay technologies. Underground operators in Australia's metallurgical coal districts are adopting these systems at accelerated rates to satisfy post-shot vibration monitoring requirements. The technology is absorbing margin from conventional shock-tube suppliers by bundling programmable accuracy with integrated blast pattern modeling software.
Australia's Work Health and Safety Regulations now mandate blast pattern modeling and post-shot vibration monitoring for all commercial blasting operations. This regulatory framework elevates demand for charger-analyzer integrated systems that combine initiation energy delivery with real-time measurement feedback. Surface mining contractors in Western Australia and Queensland are responding by consolidating supplier relationships around vendors offering compliant bundled packages.
Buyer concentration among tier-one mining houses is compressing switching cycles for initiation system procurement. Long-term supply agreements locking in multi-year emulsion and initiation contracts are displacing spot-market purchasing in Chile's copper belt and Australia's iron ore districts. This pattern is most visible in Pilbara operations where vertically integrated miners demand vendor-managed inventory and on-site technical support as standard contract terms.
Explosive Chargers Market Segmentation
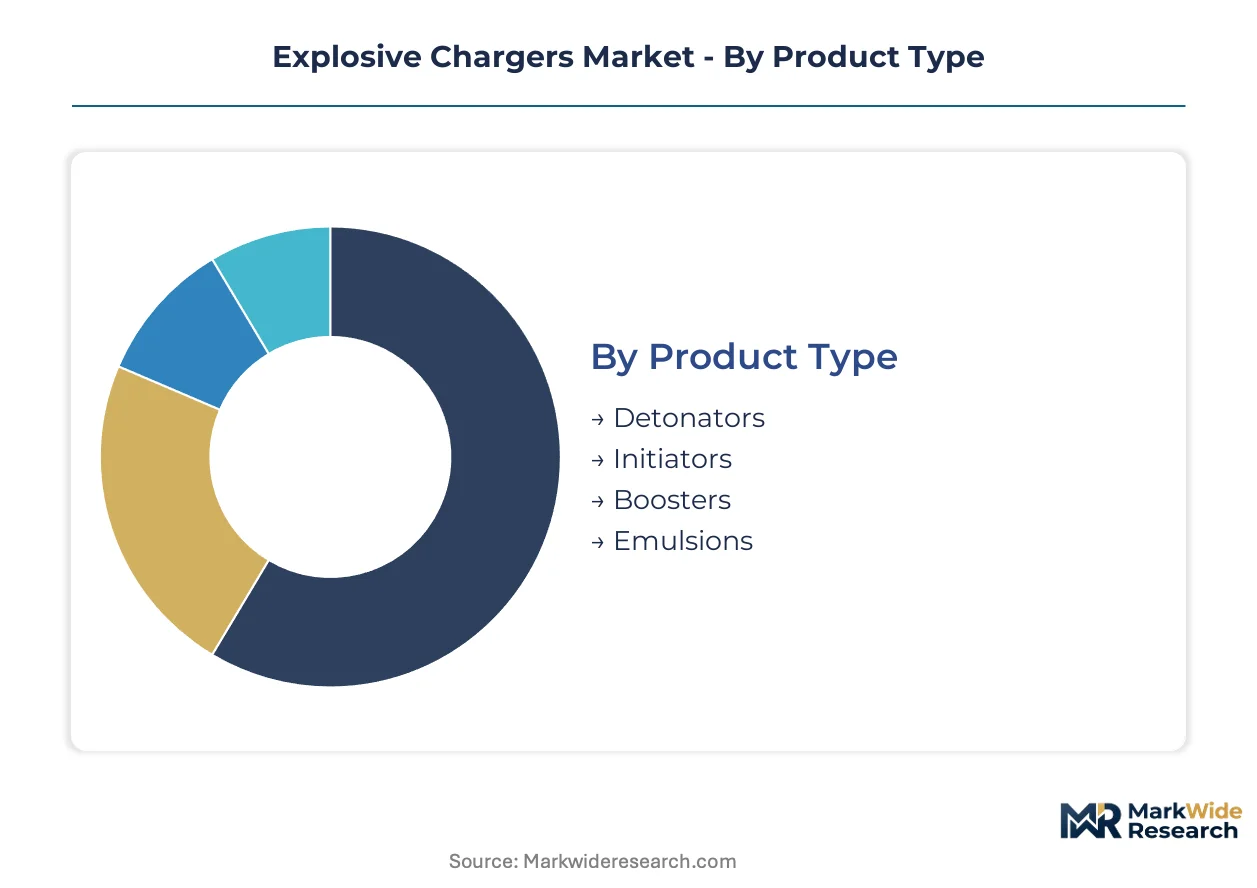
Explosive chargers serve divergent operational requirements across mining, construction, and military applications, with product specifications varying dramatically by blast environment and regulatory jurisdiction. Procurement patterns cluster around technology maturity and end-user capital intensity, creating distinct margin pools within each segment category.
Product Type:
Buyer selection hinges on blast sequence complexity and rock hardness profiles, with premium electronic configurations commanding longer procurement cycles but superior fragmentation outcomes.
- Detonators:Electronic detonators incorporate programmable delay circuits operating between 1.5 kV and 4.5 kV with millisecond-precision timing. Australian underground metallurgical coal operations are absorbing these systems at accelerated rates to satisfy post-shot vibration monitoring mandates under Work Health and Safety Regulations.
- Initiators:Shock-tube initiators maintain dominance in developing mining corridors where electrical grid fragility favors mechanical reliability. Chilean copper belt contractors retain these systems for open-pit depth extensions where infrastructure constraints limit electronic migration.
- Boosters:Cast boosters provide high-density explosive energy amplification for hard-rock fragmentation.
- Emulsions:Site-specific emulsion formulations adapt rheological properties to quarry geology and ambient temperature conditions.
Detonators lead on scale; initiators lead on momentum in developing corridors.
Application:
End-use economics dictate charger specification tiers, with commodity mining operations driving volume and specialized demolition work demanding precision premiums.
- Mining:Underground and surface mining operations consume the deepest margin pool through long-term supply agreements locking in multi-year emulsion and initiation contracts. Chile's copper belt and Australia's Pilbara iron ore districts concentrate procurement among tier-one mining houses demanding vendor-managed inventory and on-site technical support.
- Construction:Hard-rock quarry operations in Western Europe and North America require precision blasting tools for aggregate production near populated areas, elevating demand for integrated charger-analyzer systems that minimize ground vibration and flyrock hazards.
- Demolition:Urban structural demolition commands premium pricing for programmable delay sequences that control debris scatter and structural collapse timing.
- Oil & Gas:Seismic exploration and well stimulation applications utilize specialized high-temperature tolerant configurations for downhole environments.
Mining dominates absolute volume; construction exhibits the steepest expansion trajectory for integrated monitoring systems.
Technology:
Technology migration patterns reflect infrastructure maturity curves, with electronic systems displacing shock-tube reliability where power grids and technical labor pools support transition.
- Non-electric:Shock-tube systems retain volume leadership in developing mining corridors across Africa, Central Asia, and South America where electrical infrastructure fragility and technician scarcity compress upgrade timelines. These systems operate without external power sources, maintaining initiation reliability in remote field conditions.
- Electric:Cap-sensitive electric detonators serve legacy operations with established blasting pattern libraries and trained electrician workforces.
- Shock Wave:Advanced shock wave initiation systems enable precise timing control without electrical continuity requirements.
- Hybrid:Dual-mode systems bridge electronic precision with non-electric backup capabilities for critical blast sequences.
Non-electric systems lead on installed base scale; hybrid configurations gain share fastest among safety-critical applications.
End User:
Customer capital intensity and procurement sophistication create tiered demand patterns, with vertically integrated miners extracting maximum service bundling from suppliers.
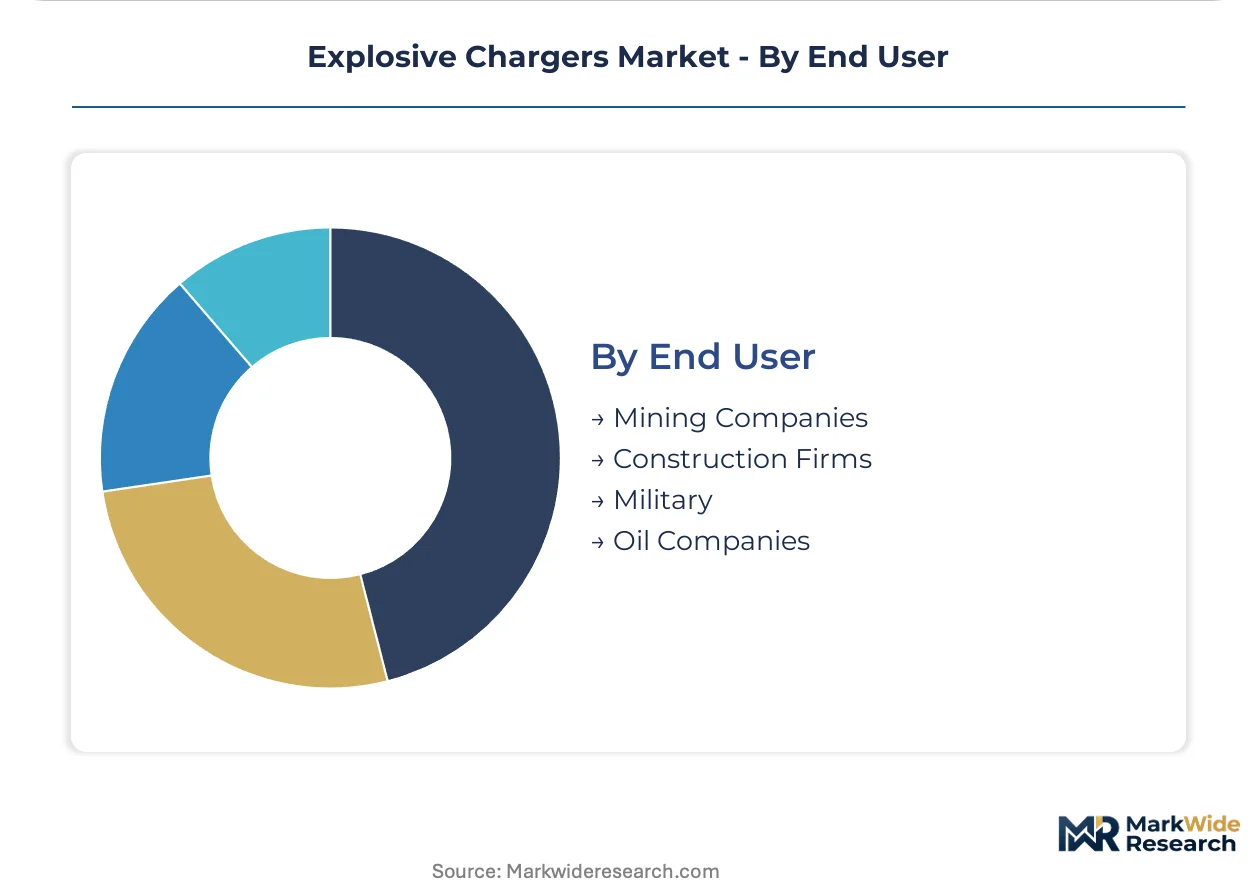
- Mining Companies:Tier-one mining houses in Australia and Chile consolidate supplier relationships around long-term agreements incorporating vendor-managed inventory, on-site technical support, and post-shot vibration monitoring compliance. These buyers capture premium service tiers through volume concentration and multi-site procurement coordination.
- Construction Firms:Regional aggregate producers and infrastructure contractors operate on shorter purchasing cycles with greater price sensitivity, favoring spot-market emulsion procurement and standardized initiation systems.
- Military:Defense procurement channels demand specialized ruggedized configurations with extended storage stability and electromagnetic interference hardening.
- Oil Companies:Exploration and production divisions source through oilfield service intermediaries with integrated perforating and stimulation service packages.
Mining companies lead on contract value concentration; construction firms lead on transaction frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Pilbara iron ore districts concentrate procurement of integrated charger-analyzer systems. Underground metallurgical coal operations in Queensland and New South Wales drive electronic initiation adoption under Work Health and Safety Regulations mandates. Copper belt depth extensions in Chile pull precision blasting tools into South American supply chains.
Australia
Pilbara iron ore miners consolidate supplier relationships around vendor-managed inventory and on-site technical support. Australia's Work Health and Safety Regulations mandate blast pattern modeling and post-shot vibration monitoring. Queensland underground coal operations absorb electronic detonators at accelerated rates to satisfy compliance requirements.
Chile
Open-pit copper operations demand precision blasting tools for rock fragmentation at increasing depths. Stricter environmental impact assessments govern blasting near populated areas in the Antofagasta Region. Tier-one mining houses in the Atacama Desert lock in multi-year emulsion and initiation contracts through long-term supply agreements.
United States
Hard-rock quarry operations in the Appalachian and Rocky Mountain regions require precision blasting near populated areas. The Bureau of Alcohol, Tobacco, Firearms and Explosives enforces capital-intensive licensing that limits market entry to proven safety protocols. Surface mining contractors in Arizona and Nevada respond by consolidating supplier relationships around compliant bundled packages.
China
Coal mining operations in Shanxi and Inner Mongolia drive volume demand for initiation systems. The Ministry of Emergency Management enforces stricter storage and transport safety standards across mining corridors. Underground contractors in the Datong coalfield upgrade to electronic systems to satisfy vibration control mandates.
Peru
Copper and gold mining operations in the Andes require reliable initiation systems for high-altitude blasting conditions. The Ministry of Energy and Mines enforces environmental compliance for operations near watersheds. Southern copper belt contractors in the Arequipa region retain shock-tube infrastructure due to electrical grid fragility.
Explosive Chargers Market Competitive Landscape
Long-term supply agreement consolidation dominates the current landscape as tier-one mining houses compress switching cycles for initiation system procurement. The vendor base organizes around three structural tiers: integrated blasting service providers, chemical precursor specialists, and precision timing technology developers. Two competitive moves shape positioning: backward integration into ammonium nitrate fuel oil supply chains and geographic expansion through on-site technical support deployment.
Among Australia-based integrated service providers, Orica Limited exemplifies the bundled offering archetype combining charger systems with blast pattern modeling software. Dyno Nobel anchors the chemical supply tier through upstream control over precursor networks. Austin Powder Company occupies a position within the site-specific formulation specialist tier serving hard-rock quarry markets.
| Leading Market Players |
|---|
| Orica Limited |
| Dyno Nobel |
| Austin Powder Company |
| Enaex S.A. |
| MaxamCorp Holding |
| Normet Group |
| Sandvik AB |
| Epiroc AB |
| MacLean Engineering |
| Others |
Supply & Pricing Matrix
Ammonium nitrate fuel oil precursor costs flow from vertically integrated chemical networks through tiered charger configurations, with electronic detonator premiums absorbing upstream volatility while shock-tube economies compete on spot-market emulsion procurement in developing corridors.
Pricing Analysis
Input-cost pass-through from ammonium nitrate fuel oil supply concentration shapes a contract-based long-term offtake model dominating tier-one mining procurement. Price differentiation separates programmable electronic systems with integrated blast pattern modeling from standard shock-tube initiators. Pricing pressure intensifies in the non-electric tier as developing mining corridors compress upgrade timelines. Mining companies exhibit lowest price sensitivity through multi-year supply agreements, while regional construction contractors face acute margin pressure on spot-market purchasing.
Supply Chain Analysis
Direct-to-mine-site technical support channels handle tier-one mining house demand across Australia's Pilbara and Chile's Atacama Desert. Manufacturing concentration rests on Australia, Chile, and the United States for integrated blasting services and precision timing systems. Raw material dependencies draw from ammonium nitrate fuel oil precursor networks, polymer encapsulation feedstocks, and solid-state timing circuit components. Single-source vulnerability in ammonium nitrate fuel oil supply creates structural risk for regional blasting contractors. Distribution runs through vendor-managed inventory agreements with on-site technical support bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement shifts toward programmable electronic detonators with millisecond-precision timing and integrated vibration monitoring compliance.
For Market Incumbents: Deploy integrated service bundling to lock in long-term supply agreements before electronic migration accelerates. Backward integration into ammonium nitrate fuel oil supply chains defends margin position against chemical precursor volatility. Certification investment in polymer-based encapsulation materials addresses EU Explosives Directive compliance requirements and creates switching costs for tier-one mining houses. For New Entrants and Emerging Players: Enter via hard-rock quarry specialization in Western Europe and North America where precision blasting near populated areas commands premium pricing. Site-specific emulsion formulation partnerships with aggregate producers offer the most penetrable white-space target outside commodity mining corridors. A go-to-market angle emphasizing integrated charger-analyzer systems with post-shot vibration monitoring captures construction sector procurement upgrading from standardized initiation systems. For Investors and Strategic Acquirers: Consolidation pressure builds where tier-one mining houses compress supplier relationships around vendors offering compliant bundled packages with vendor-managed inventory. Long-term viability over the projection horizon favors precision timing technology developers with electronic detonator capabilities over shock-tube legacy exposure. Acquisition target archetypes include site-specific formulation specialists serving hard-rock quarry markets. The signal to watch is electronic initiation system procurement rates in Australia's underground metallurgical coal districts as a leading indicator of technology migration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemical Networks | Captive ammonium nitrate fuel oil supply secures margin control against raw material volatility in Chilean copper belt operations. |
| Integrated Charger-Analyzer System Development | Combined initiation energy delivery with real-time vibration monitoring satisfies Australia's Work Health and Safety Regulations mandates. |
| Site-Specific Emulsion Formulation Partnerships | Tailored rheological properties for hard-rock quarry geology open margin pools outside commodity mining procurement. |
| Polymer Housing Material Science Investment | Corrosion-resistant encapsulation reduces unit weight and transport costs under stricter EU Explosives Directive storage rules. |
| On-Site Technical Support Deployment | Blast pattern modeling expertise placement addresses technician shortage bottlenecks in remote mining districts. |
Research Methodology
Multiple input streams — procurement director interviews at tier-one mining houses, regulatory compliance officer discussions, and blasting contractor operational assessments — were reconciled with secondary validation from customs and trade data, SEC filings of listed explosives manufacturers, and national mining safety regulator publications. Bottom-up demand modeling across product type, application, technology, and end-user segments was cross-checked against top-down market sizing from industry association reports.
Data-stream reconciliation anchored volume and value outputs across the analysis window through segmentation-dimensional modeling incorporating product type tier, application environment, technology maturity curve, and end-user capital intensity. CAGRs were derived from slope analysis of historical trajectory patterns adjusted for electronic migration acceleration factors and regulatory compliance mandate timelines. Industry-specific forecast inputs included blast pattern modeling adoption rates and post-shot vibration monitoring equipment deployment curves.
Inputs from procurement directors and regulatory compliance officers were available through the study window; gaps in emerging mining corridor shock-tube inventory data introduce uncertainty bands around non-electric system share projections. Forecasts reflect assumptions about electronic initiation system cost reduction trajectories and technician training pipeline expansion. Periodic stress-testing of base assumptions is recommended against actual procurement budget allocations and regulatory enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
Hydrofluoric Acid (HF) for Semiconductor Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market
Industrial Chemicals
Honing Oil Market
Industrial Chemicals
2-Ethoxy Propene Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Rodenticides Market
Industrial Chemicals
Wood Preservative Market