
 Activated Bleaching Earth Market | 2026-2036
Activated Bleaching Earth Market Size, Share, and Industry Trends Forecast 2026-2036
Activated Bleaching Earth Market Intelligence
Edible oil refining is repositioning as the dominant demand pillar for activated bleaching earth, displacing slower-growing industrial applications. Clariant leverages its European manufacturing footprint to supply food-grade specifications across multiple continents. Musim Mas Holdings anchors procurement decisions through captive palm oil refining operations in Southeast Asia. Taiko Group of Companies competes on volume scale in the Asia-Pacific edible oils corridor.
Activated bleaching earth consists of acid-activated bentonite clay with enhanced surface area and porosity, typically treated with sulfuric or hydrochloric acid to boost adsorption capacity for pigments, free fatty acids, and oxidation byproducts in vegetable and mineral oils. The natural product type dominates current volumes due to lower production costs and established supply chains, though synthetic and hybrid grades are capturing margin pools in pharmaceutical and high-purity cosmetic applications where chemical consistency matters more than price. Oil refining applications lead absolute consumption, while food processing segments are shifting toward customized particle-size distributions that reduce filtration downtime.
REACH in Europe and FDA food-contact regulations in the United States set divergent purity and migration-limit standards that force suppliers to maintain multiple certification pathways. BIS standards in India and China's GB standards for food additives add further compliance layers for exporters serving Asian refining markets. Stakeholders must track regulatory harmonization progress between major jurisdictions, as misaligned contaminant thresholds threaten to fragment product formulations and inflate qualification costs for multinational suppliers.
Market Dynamics
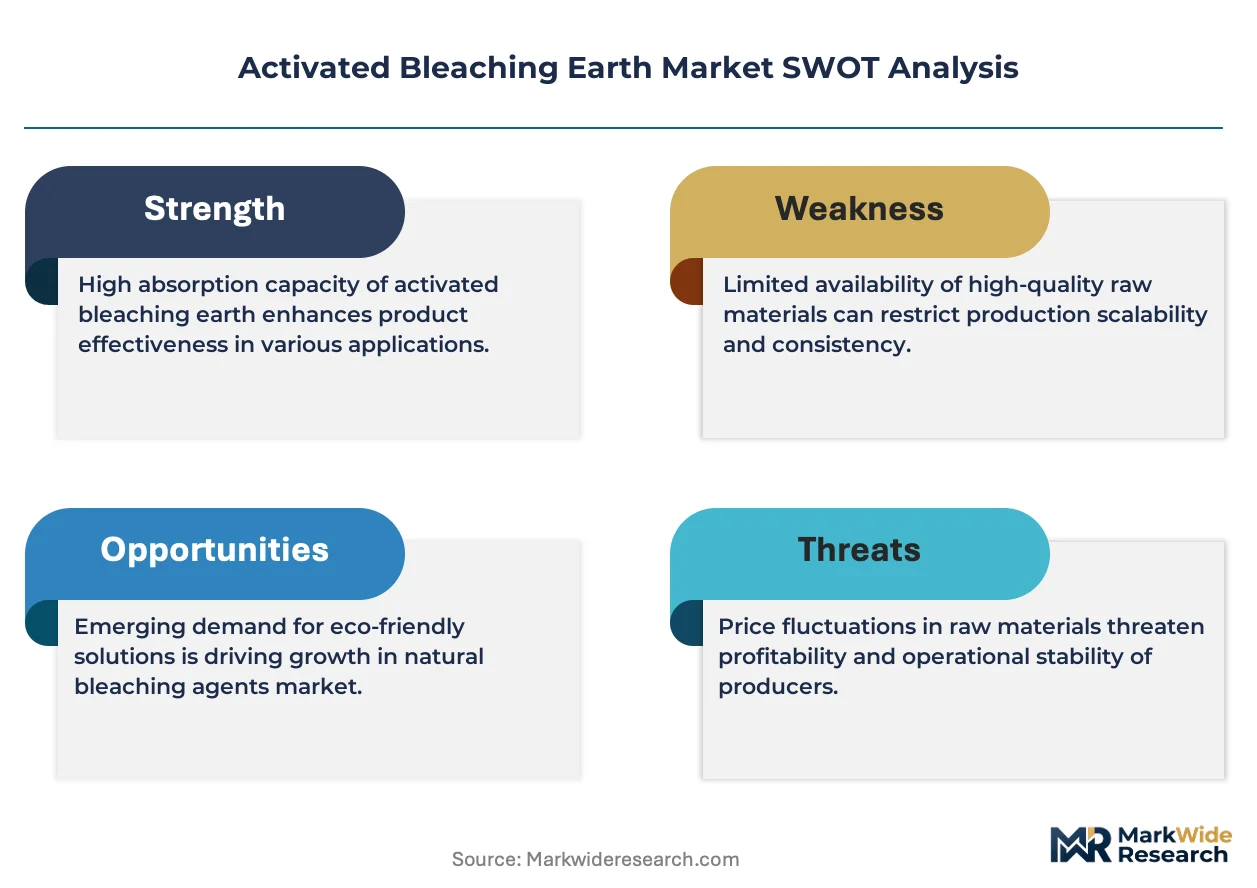
Palm oil refining capacity expansion in Southeast Asia is pulling bleaching earth demand toward high-volume, specification-grade contracts that favor suppliers with captive clay deposits and acid-activation infrastructure.
Growth Catalysts
- REACH compliance mandates:European ECHA purity requirements for food-contact materials are forcing refiners to upgrade from standard to acid-activated grades, expanding addressable volume for certified suppliers.
- Edible oil processing intensity:Indonesian and Malaysian palm oil clusters are running refineries at higher throughput rates, consuming more bleaching earth per ton of crude processed to meet color and oxidation specifications.
- Surface area engineering:Advanced acid-activation protocols using controlled sulfuric acid dosing are yielding clays with 300+ m²/g surface area, enabling single-pass decolorization that cuts filtration cycles.
Market Restraints
- Bentonite supply geography:Premium calcium bentonite deposits concentrate in Wyoming (US) and Gujarat (India), creating freight cost penalties for Southeast Asian refiners and input price volatility during currency swings.
- Silica gel substitution:Synthetic amorphous silica products are capturing share in high-value cosmetic and pharmaceutical oil purification where batch consistency outweighs clay's cost advantage.
- FDA food-contact migration limits:Evolving FDA thresholds for acid-soluble metals in bleaching earth are disqualifying some traditional activation chemistries, forcing reformulation investments.
Strategic Opportunities
- India BIS grade harmonization:Convergence of Indian BIS food additive standards with Codex Alimentarius frameworks is opening export pathways for European-certified suppliers into subcontinental edible oil refining.
- Spent earth regeneration:Pyrolysis-based oil recovery and clay reactivation services are emerging as a parallel revenue stream, addressing waste disposal liabilities for large refiners.
- Pharmaceutical-grade hybrid clays:Synthetic-bentonite composite materials with controlled pore size distributions are penetrating injectable oil and API purification applications.
Industry Challenges
- Acid-activation process engineering:Scaling from pilot to commercial acid-activation reactors requires precise temperature and residence time control that few plant operators have mastered.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of REACH, FDA, and BIS approvals stretches qualification cycles to 18-24 months, freezing product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Activated Bleaching Earth Market |
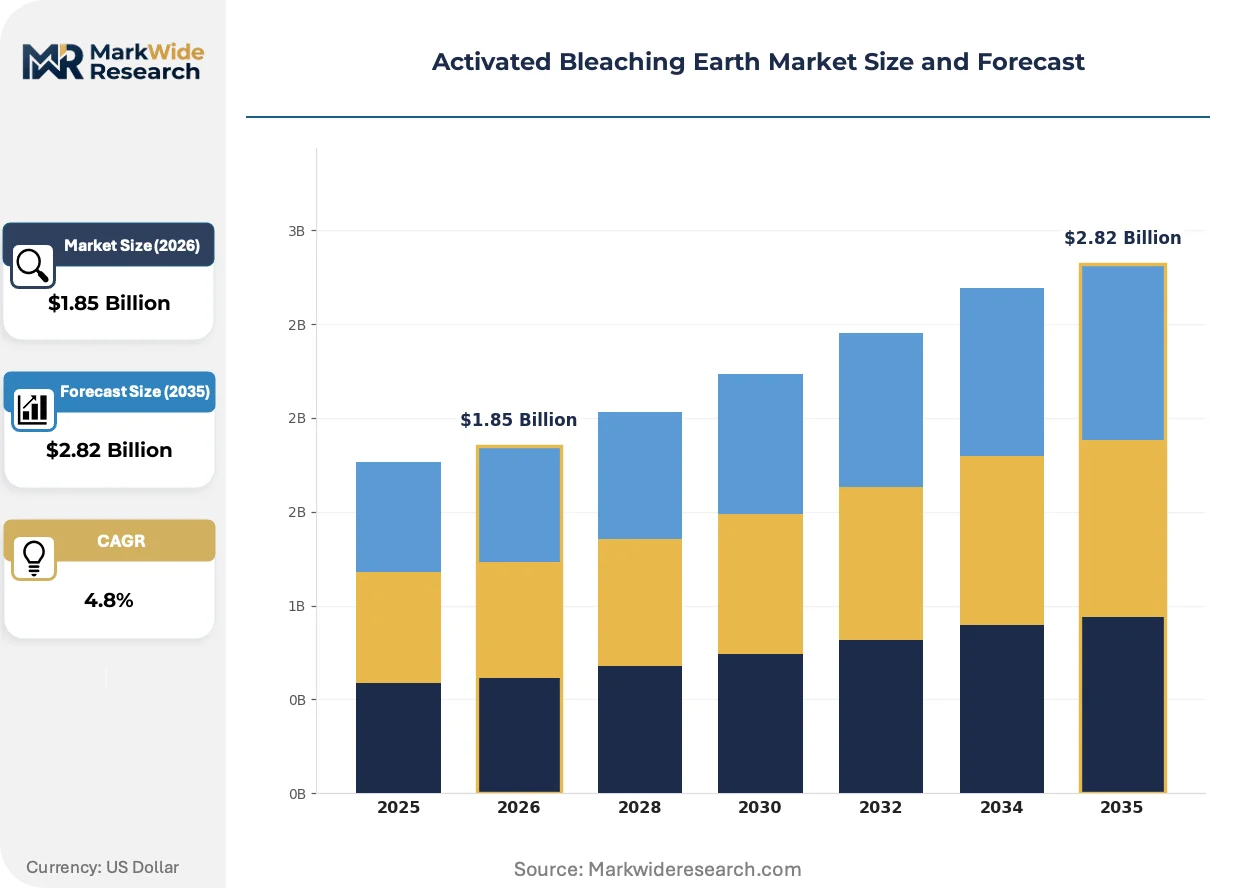
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Chemical, Synthetic, Hybrid Application: Food Processing, Oil Refining, Cosmetic, Pharmaceuticals End User: Food Industry, Textile Industry, Personal Care, Paints Distribution Channel: Direct Sales, Wholesalers, Online Retail, Export |
| Companies Covered | Clariant, Musim Mas Holdings, Oil-Dri Corporation of America, Taiko Group of Companies, Ashapura Perfoclay Limited, BASF SE, AMC (UK) Ltd., The W Clay Industries Sdn. Bhd., Refoil Earth Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Activated Bleaching Earth Market Strategic Shifts & Innovations
Acid-activation chemistry and spent-earth valorization are converging to reshape how suppliers capture margin across the bleaching earth value chain, with sustainability compliance emerging as a parallel competitive axis.
Controlled acid-activation using microwave-assisted heating is decentralizing production economics for mid-scale clay processors. Indonesian and Malaysian edible oil refiners are adopting these systems to reduce dependence on imported high-performance grades. The technology is decentralizing supply chain risk by enabling regional activation hubs that source raw bentonite and perform surface modification locally.
REACH authorization requirements for sulfuric acid handling are tightening occupational exposure benchmarks across European activation facilities. The ECHA framework is forcing capital deployment into closed-loop acid recovery systems and automated dosing controls. Food-grade bleaching earth destined for EU export markets now carries documentation burdens that add 8-12% to delivered costs.
Refiner procurement departments are consolidating supplier rosters around integrated service contracts that bundle clay supply with spent-earth collection and oil recovery. Large palm oil processors in Malaysia are displacing transactional spot purchasing with three-year framework agreements. This concentration is most visible in the Port Klang-Johor refining corridor, where three processors now account for majority volume.
Activated Bleaching Earth Market Segmentation
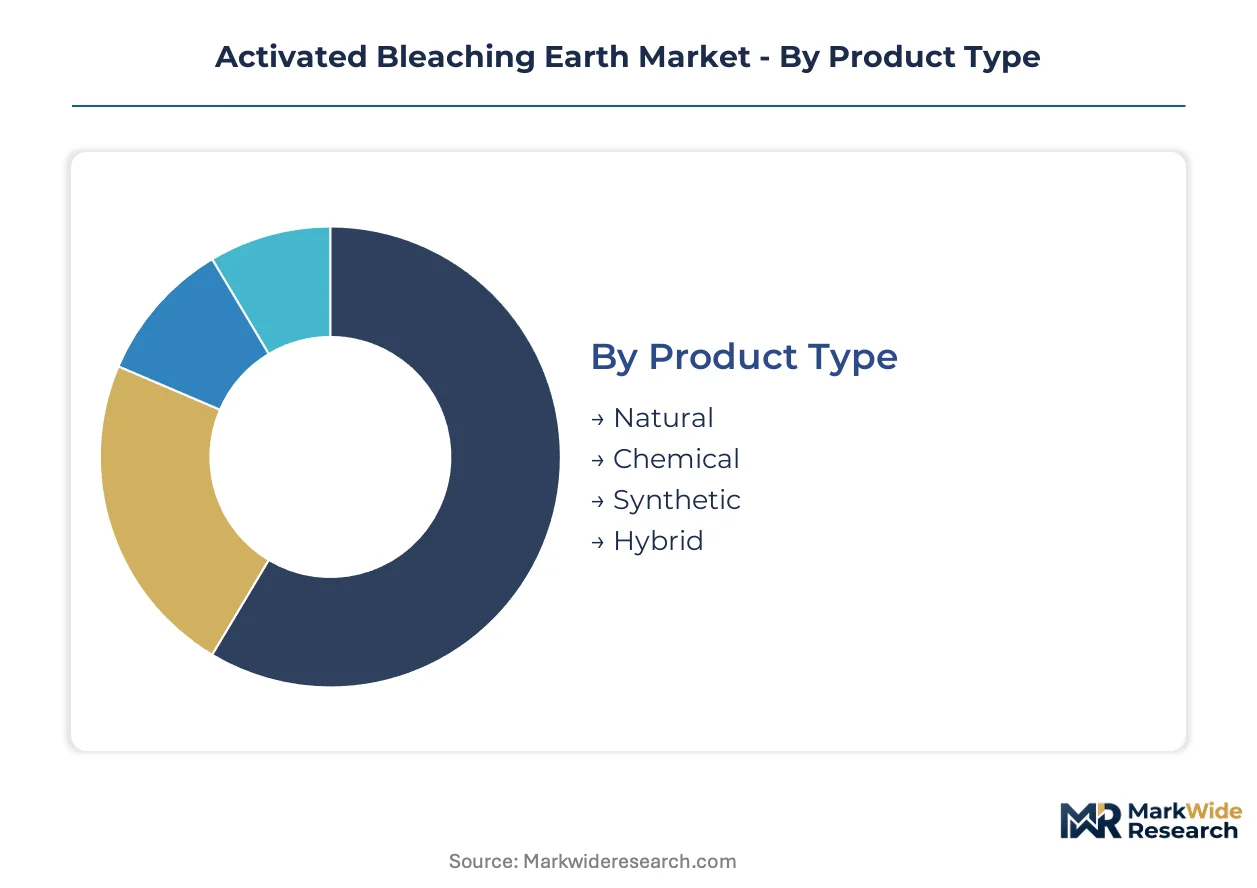
Segmentation in activated bleaching earth reveals how product chemistry, application intensity, and channel structure determine margin capture. Suppliers must align formulation investments with the specific purity thresholds and volume profiles that each segment demands.
Product Type:
Natural grades operate as standalone bulk commodities in high-volume refining, while synthetic and hybrid variants embed into specialized purification systems where batch consistency overrides unit cost.
- Natural:Acid-activated bentonite clay with 200-300 m²/g surface area dominates palm oil decolorization in Indonesia and Malaysia. Southeast Asian refiners consume this grade in 500-tonne monthly contracts tied to throughput guarantees.
- Chemical:Modified clays with enhanced acid solubility profiles serve European edible oil processors navigating ECHA migration limits. REACH documentation requirements add certification overhead that filters out smaller regional suppliers.
- Synthetic:Engineered silica-alumina matrices with uniform pore distributions target pharmaceutical injectable oil purification.
- Hybrid:Bentonite-synthetic composites balance cost and performance in cosmetic-grade mineral oil refining.
Volume placements concentrate in Natural; the faster expansion belongs to Hybrid.
Application:
Application segments separate by processing intensity and contaminant load, with oil refining demanding the highest adsorption capacity per tonne processed.
- Oil Refining:Palm, soybean, and rapeseed refineries deploy acid-activated grades in continuous bleaching towers. Malaysian processors at Port Klang run filtration cycles consuming 3-5 kg bleaching earth per tonne crude palm oil to meet color specifications below 3 Red.
- Food Processing:Specialty fat and shortening manufacturers use customized particle-size distributions to reduce press cake oil retention. Indonesian margarine plants specify 80-120 micron grades that cut filtration downtime by 15%.
- Cosmetic:Mineral oil and wax purification for skincare formulations requires heavy metal thresholds below 10 ppm.
- Pharmaceuticals:API and excipient purification demands USP-grade documentation with full batch traceability.
Revenue concentration sits with Oil Refining; Pharmaceutical applications command the steepest price premiums.
End User:
End user categories reflect divergent procurement sophistication, from commodity spot purchasing in textiles to multi-year framework agreements in food manufacturing.
- Food Industry:Integrated palm oil processors in Malaysia negotiate three-year supply contracts bundling clay, technical service, and spent earth collection. Musim Mas Holdings and IOI Corporation anchor procurement volumes through captive refining operations.
- Personal Care:Cosmetic formulators in Western Europe specify hybrid grades with microbial contamination certificates. L'Oréal and Unilever suppliers face dual audits under ISO 22716 and customer-specific protocols.
- Textile Industry:Yarn and fabric finishers use standard natural grades for oil removal in scouring operations.
- Paints:Coating manufacturers employ bleaching earth for pigment dispersion and viscosity control in alkyd resins.
Contract value aggregates in Food Industry; Personal Care generates the highest margin per kilogram.
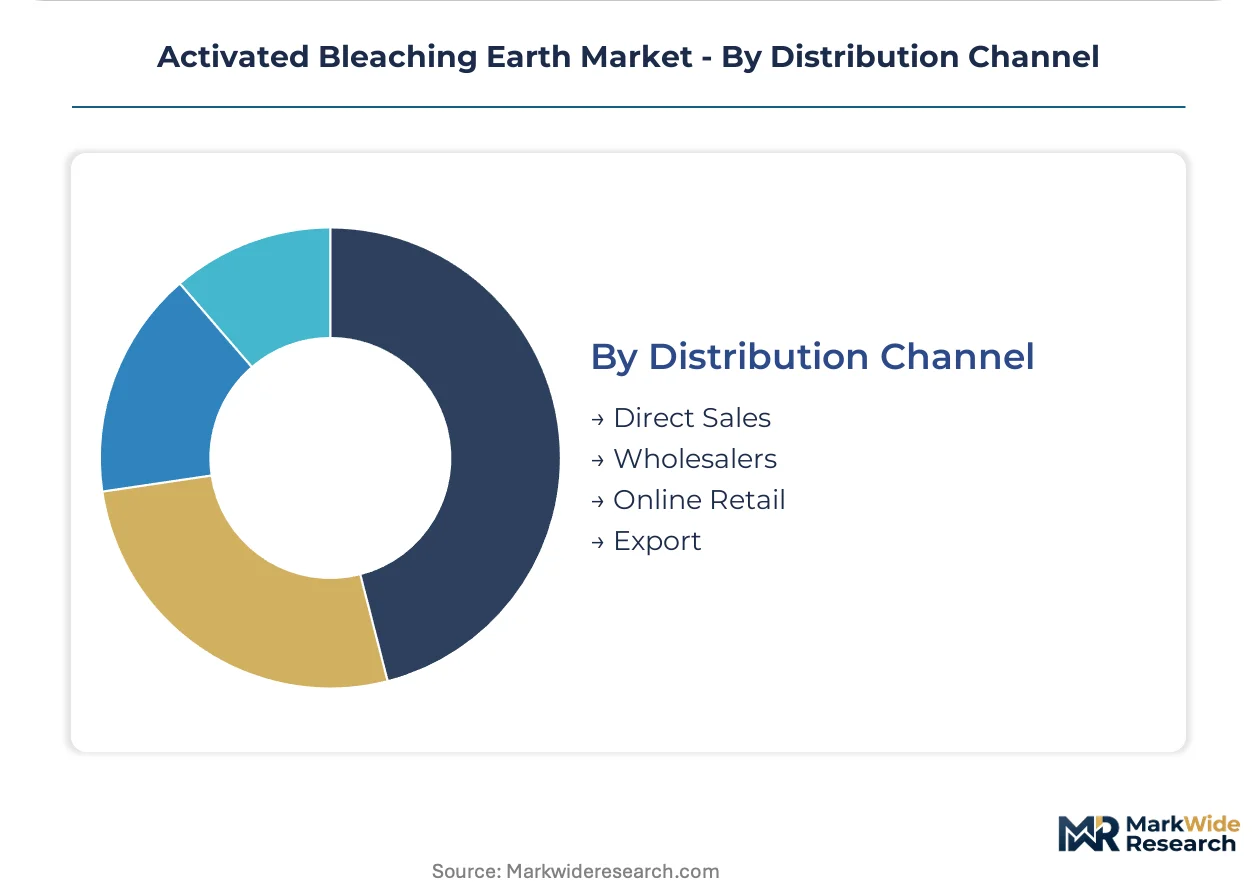
Distribution Channel:
Channel structure maps to customer scale and geographic concentration, with direct relationships dominating where refining clusters create density.
- Direct Sales:Clariant and Taiko Group deploy technical sales teams to Indonesian and Malaysian refineries for specification development and filtration optimization. Direct relationships capture 60-70% of volume in the Port Klang-Johor corridor through integrated service contracts.
- Wholesalers:Regional distributors serve mid-scale Indian edible oil processors in Gujarat and Rajasthan with BIS-certified inventory held in bonded warehouses.
- Online Retail:Alibaba and IndiaMART facilitate spot purchases for small cosmetic compounders seeking 1-5 tonne lots.
- Export:Cross-border traders manage documentation complexity for European suppliers reaching Southeast Asian markets.
Shipment volume flows through Direct Sales; Online Retail exhibits the most rapid channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian special economic zones in North Sumatra and Riau are concentrating palm oil refining infrastructure, pulling activated bleaching earth procurement toward integrated supply contracts. Malaysia's Port Klang-Johor corridor anchors Southeast Asian demand density.
Indonesia
Palm oil refining clusters in Medan and Dumai are consuming specification-grade bleaching earth at monthly volumes exceeding 500 tonnes per facility. Indonesia's national standardization agency enforces SNI food additive protocols that align with Codex Alimentarius frameworks. The Riau Islands refining zone is consolidating supplier rosters around three-year framework agreements bundling clay supply with spent earth collection services.
Malaysia
Port Klang refineries are running continuous bleaching towers at elevated throughput rates, demanding acid-activated grades with 300+ m²/g surface area for single-pass decolorization. Malaysia's Department of Standards implements MS food-contact material regulations that mirror EU REACH migration limits. Johor's Pasir Gudang industrial zone is displacing spot purchasing with integrated service contracts covering technical optimization and filtration downtime reduction.
India
Gujarat's edible oil processors in Kandla and Mundra are scaling refined capacity, driving BIS-certified bleaching earth procurement through regional distributors holding bonded warehouse inventory. India's Food Safety and Standards Authority enforces contaminant thresholds for acid-soluble metals that filter out non-compliant activation chemistries. The Rajasthan bentonite belt around Bhuj is supplying raw clay to domestic acid-activation facilities serving subcontinental refiners.
United States
Wyoming's calcium bentonite deposits are supplying acid-activation facilities serving domestic soybean and canola refiners, though freight cost penalties limit Southeast Asian export competitiveness. The FDA's evolving food-contact migration limits for bleaching earth are disqualifying traditional sulfuric acid activation protocols. Texas Gulf Coast refineries are qualifying hybrid clay grades for high-volume vegetable oil processing.
Germany
Ruhr Valley chemical processors are supplying REACH-compliant acid-activated grades to European edible oil refiners navigating ECHA purity requirements. Germany's Federal Institute for Risk Assessment coordinates with EFSA on food-contact material safety assessments that shape supplier qualification protocols. Bavarian specialty chemical producers are engineering synthetic-bentonite composites for pharmaceutical-grade oil purification applications.
Activated Bleaching Earth Market Key Industry Players
Top-tier vendors anchor integrated service contracts, while mid-scale regional processors compete on activation infrastructure proximity to refining clusters. The supplier base stratifies across multinational chemical conglomerates with captive bentonite deposits, specialized clay processors with acid-activation mastery, and regional distributors managing certification complexity for smaller refiners. Strategic moves concentrate on backward integration into raw clay sourcing and pyrolysis-based spent earth regeneration capabilities.
Within the multinational chemical tier, Clariant and BASF SE exemplify European-anchored suppliers leveraging REACH certification pathways to access Asian refining markets. Oil-Dri Corporation of America occupies a position tied to Wyoming bentonite deposit control. Taiko Group of Companies and Musim Mas Holdings represent Southeast Asian-integrated players where refining operations and clay supply decisions sit under common ownership, compressing procurement cycles.
| Leading Market Players |
|---|
| Clariant |
| Musim Mas Holdings |
| Oil-Dri Corporation of America |
| Taiko Group of Companies |
| Ashapura Perfoclay Limited |
| BASF SE |
| AMC (UK) Ltd. |
| The W Clay Industries Sdn. Bhd. |
| Refoil Earth Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap clay processors in Gujarat and Wyoming anchor supply discipline through generational control of premium calcium bentonite deposits, translating captive mineral access into pricing power that resists spot-market volatility. Their long-tenured relationships with acid-activation facilities create contract structures where volume commitments lock in preferential pricing tiers unavailable to traders sourcing through open markets.
Pricing Analysis
Short lead-time premiums of 12-18% apply to emergency spot orders from Indonesian refiners facing filtration tower downtime, while contracted volume commitments secure 8-12% discounts against published tariffs. Three-tier pricing structure across REACH-certified premium, BIS-standard mid-grade, and unregistered economy levels separates multinational suppliers from regional distributors. Cost compression in the economy tier is intensifying because Chinese acid-activation capacity is flooding Southeast Asian spot markets. Integrated palm oil processors exhibit lowest price sensitivity due to throughput guarantee penalties, whereas small Indian edible oil refiners in Rajasthan demonstrate acute responsiveness to per-tonne differentials.
Supply Chain Analysis
Dual-sourcing mandates from Malaysian processors at Port Klang require qualification of at least two acid-activation suppliers to mitigate single-facility disruption risk. Geographic supply concentrates in the United States, India, and Indonesia, with Wyoming and Gujarat furnishing raw bentonite and North Sumatra hosting emerging activation infrastructure. Raw material dependencies encompass sulfuric acid for surface modification, natural gas for thermal processing, and specialized filtration equipment for quality control. Single-source vulnerability persists in pharmaceutical-grade hybrid clay formulations where German and Swiss specialty chemical producers control proprietary synthesis protocols. Distribution runs through integrated service contracts bundling clay supply with spent-earth collection rather than traditional commodity trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over Wyoming and Gujarat bentonite deposits to secure margin against raw material volatility.
For Market Incumbents: Lock in multi-year framework agreements with Indonesian and Malaysian palm oil clusters before microwave-assisted acid-activation technology enables regional self-sufficiency. Prioritize pyrolysis-based spent-earth regeneration capabilities to capture parallel revenue streams from waste disposal liabilities. Defend against silica gel substitution in cosmetic applications by embedding hybrid clay formulations into L'Oréal and Unilever supplier audits. For New Entrants and Emerging Players: Launch via regional distributors serving mid-scale Indian edible oil processors in Gujarat and Rajasthan with BIS-certified inventory held in bonded warehouses. Target pharmaceutical-grade synthetic-bentonite composites where batch consistency requirements filter out commodity suppliers. Penetrate the cosmetic mineral oil purification segment through microbial contamination certification pathways that European formulators demand. For Investors and Strategic Acquirers: Distressed-cycle entries favor acid-activation specialists with underutilized reactor capacity in Southeast Asian special economic zones, particularly where palm oil refining expansion outpaces local clay processing infrastructure. Long-term viability hinges on positioning for regulatory harmonization between REACH, FDA, and BIS frameworks over a 5-10 year compliance convergence window. Monitor ECHA authorization timelines for sulfuric acid handling as the inflection signal for capital deployment into closed-loop recovery systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bentonite Deposits | Captive supply from Wyoming and Gujarat deposits insulates margin against freight cost penalties during currency swings. |
| Spent-Earth Regeneration Service Launch | Pyrolysis-based oil recovery addresses waste disposal liabilities for Malaysian processors at Port Klang. |
| REACH-FDA-BIS Multi-Certification Investment | Simultaneous qualification pathways unlock export access to European, American, and subcontinental refining markets. |
| Microwave-Assisted Activation Technology Deployment | Decentralized production economics enable Indonesian refiners to reduce dependence on imported high-performance grades. |
| Hybrid Clay Formulation Development | Synthetic-bentonite composites penetrate pharmaceutical injectable oil applications where USP-grade documentation is mandatory. |
Research Approach
Multi-period observation of acid-activation capacity utilization, spent-earth disposal volumes, and regulatory certification timelines anchored the trend analysis, supplemented by interviews with plant managers at Southeast Asian refineries, procurement leads at integrated palm oil processors, technical R&D directors at clay activation facilities, and distribution channel partners managing bonded warehouse inventory. Secondary validation drew from customs and trade data, BIS and ECHA regulatory filings, SEC 10-K disclosures from listed chemical conglomerates, and industry association reports tracking edible oil refining throughput. Bottom-up volume estimates from individual facility consumption profiles triangulated against top-down market sizing derived from regional production statistics.
Input-output matrices modeled consumption intensity per tonne of crude palm oil processed across natural, chemical, synthetic, and hybrid product grades, segmented by application intensity in oil refining, food processing, cosmetic, and pharmaceutical end uses. CAGRs were computed from fitted trend lines across the projection horizon, incorporating acid-activation reactor capacity expansion schedules and palm oil refining cluster development timelines as industry-specific forecast inputs. Regional regulatory convergence scenarios between REACH, FDA, and BIS frameworks informed geographic demand distribution assumptions.
The model assumes a particular technology adoption path for microwave-assisted acid-activation; alternative pathways involving conventional thermal processing would alter the outlook for regional self-sufficiency in Southeast Asia. Forecasts reflect assumptions regarding sustained palm oil refining capacity expansion in Indonesia and Malaysia, continued ECHA enforcement of sulfuric acid handling benchmarks, and stable Wyoming bentonite deposit access. Deviation in FDA food-contact migration limit stringency would shift the outlook materially for acid-activation chemistry qualification costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Europe Soda Ash Market
Bulk Chemicals
Di-Isobutylene Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Europe Ammonium Nitrate Market
Bulk Chemicals
Vinyl Cyclohexane Market
Bulk Chemicals
Alunite Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
Potassium Chlorate Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
Precipitated Calcium Carbonate Market
Bulk Chemicals
Sodium Ferrocyanide Market
Bulk Chemicals
North America Glycerol Market
Bulk Chemicals
Mangiferin Market