
 Black Rice Protein Market | 2026-2036
Black Rice Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Black Rice Protein Market Analytics
Asset-light contract manufacturing is narrowing the capital barrier for mid-tier brands seeking black rice protein scale. Amazonia leverages its Brazilian supply base to control raw material costs across South American markets. Axiom Foods, Inc. anchors North American distribution through specialized plant-protein extrusion capabilities. Kerry Group plc competes via its integrated flavor-mask systems that offset black rice protein's bitter notes in finished applications.
Black rice protein is an anthocyanin-rich plant protein extracted from Oryza sativa L. indica through aqueous or enzymatic separation, typically yielding 80-90% protein content with a PDCAAS approaching 0.75. The ingredient serves primarily as a hypoallergenic alternative to soy and whey in premium nutrition formulations. Isolate commands the dominant margin pool due to its superior amino acid completeness and lower carbohydrate residue, while hydrolysate posts the fastest trajectory as sports nutrition brands prioritize rapid absorption kinetics. Powder form sustains the largest volume share, though bar applications are gaining traction as convenience formats expand in health-food retail channels.
FDA GRAS self-affirmation and USDA Organic certification govern U.S. market access, while EFSA Novel Food authorizations constrain European ingredient introductions. The EU Green Deal's Farm to Fork strategy tightens traceability requirements for imported Asian protein sources. Stakeholders must monitor evolving amino acid fortification standards and dual carbon compliance across supplier jurisdictions.
Market Dynamics
Clean-label formulation mandates from major retail chains are compressing the acceptable ingredient list for plant-based proteins, forcing suppliers to eliminate masking agents and synthetic additives that historically offset black rice protein's sensory limitations.
Growth Catalysts
- EU Green Deal traceability requirements:Farm to Fork strategy mandates are accelerating supplier investment in certified organic cultivation chains across Southeast Asian sourcing regions.
- Sports nutrition brands:German and US athletic supplement manufacturers are expanding black rice protein isolate procurement for hypoallergenic product lines targeting soy-intolerant consumers.
- Enzymatic extraction advances:Novel protease blends are improving protein yield rates from Oryza sativa L. indica while preserving anthocyanin bioactivity for functional positioning.
Market Restraints
- Input cost volatility:Black rice cultivation concentrates in specific Thai and Indonesian floodplains, exposing processors to climate-driven harvest variability and price spikes.
- Regulatory friction:EFSA Novel Food authorization timelines extend 18-24 months for new black rice protein entrants, freezing capital in pre-market compliance phases.
- Substitution threat:Pea protein isolates with improved amino acid profiles and established GRAS status capture shelf space in mid-tier nutrition formulations.
Strategic Opportunities
- Brazilian contract manufacturing:Asset-light production partnerships in São Paulo and Minas Gerais states offer US brands tariff-advantaged access to South American functional beverage markets.
- Bar format expansion:Convenience-oriented health-food retail channels are creating formulation demand for black rice protein with enhanced binding properties and moisture retention.
- Dual carbon compliance:China's national carbon trading scheme and EU CBAM are incentivizing processors to certify low-emission supply chains for premium market access.
Industry Challenges
- Flavor chemistry expertise gap:Formulation teams lack specialized knowledge in anthocyanin-protein interactions, delaying clean-label taste optimization for finished applications.
- Organic certification backlog:USDA-accredited bodies face inspection scheduling delays of 8-14 months for new Southeast Asian processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Black Rice Protein Market |
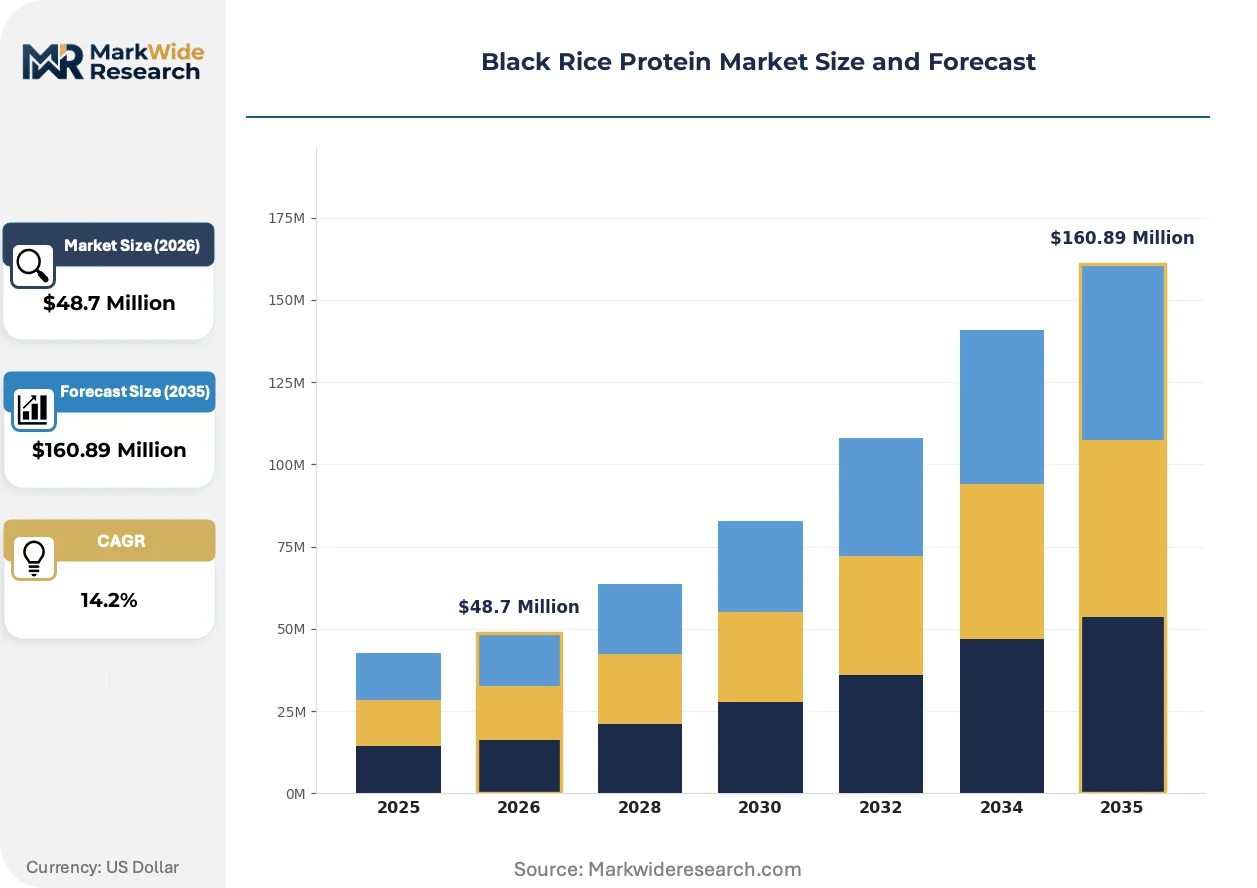
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $160.89 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolysate, Blends End User: Food & Beverage, Nutritional Supplements, Bakery, Confectionery Form: Powder, Liquid, Granules, Bars Application: Weight Management, Muscle Building, Health Foods, Sports Nutrition |
| Companies Covered | Amazonia, Nutraonly (Xi’an Nutrition Inc.), Bioway (Xi'an) Organic Ingredients Co., Ltd., Axiom Foods, Inc., ETChem, Kerry Group plc, Gulshan Polyols Ltd., Shafi Gluco Chem, Südzucker AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Black Rice Protein Market Evolving Landscape
Enzymatic hydrolysis protocols and precision fermentation adjuncts are compressing the traditional extraction-to-application timeline, enabling faster product iteration cycles for nutrition brands.
Membrane filtration technology with ceramic microfiltration modules is rendering obsolete conventional acid-precipitation methods for protein isolation. Specialty ingredient houses in California and Bavaria are adopting these systems at commercial scale. The shift is compressing capital recovery periods while improving PDCAAS consistency across batch runs.
EFSA's evolving position on protein hydrolysate novel food categories is tightening amino acid fortification documentation requirements for European market entry. This regulatory recalibration is extending formulation validation timelines. Sports nutrition applications face the most acute compliance burden, with several brands reformulating to preempt authorization delays.
Direct-procurement relationships between finished goods manufacturers and Thai cultivation cooperatives are displacing traditional trader-mediated supply chains. This disintermediation is most visible in US organic-certified product lines, where brands require farm-level traceability for retail compliance. The model is compressing working capital cycles while transferring price risk to processors.
Black Rice Protein Market Segmentation
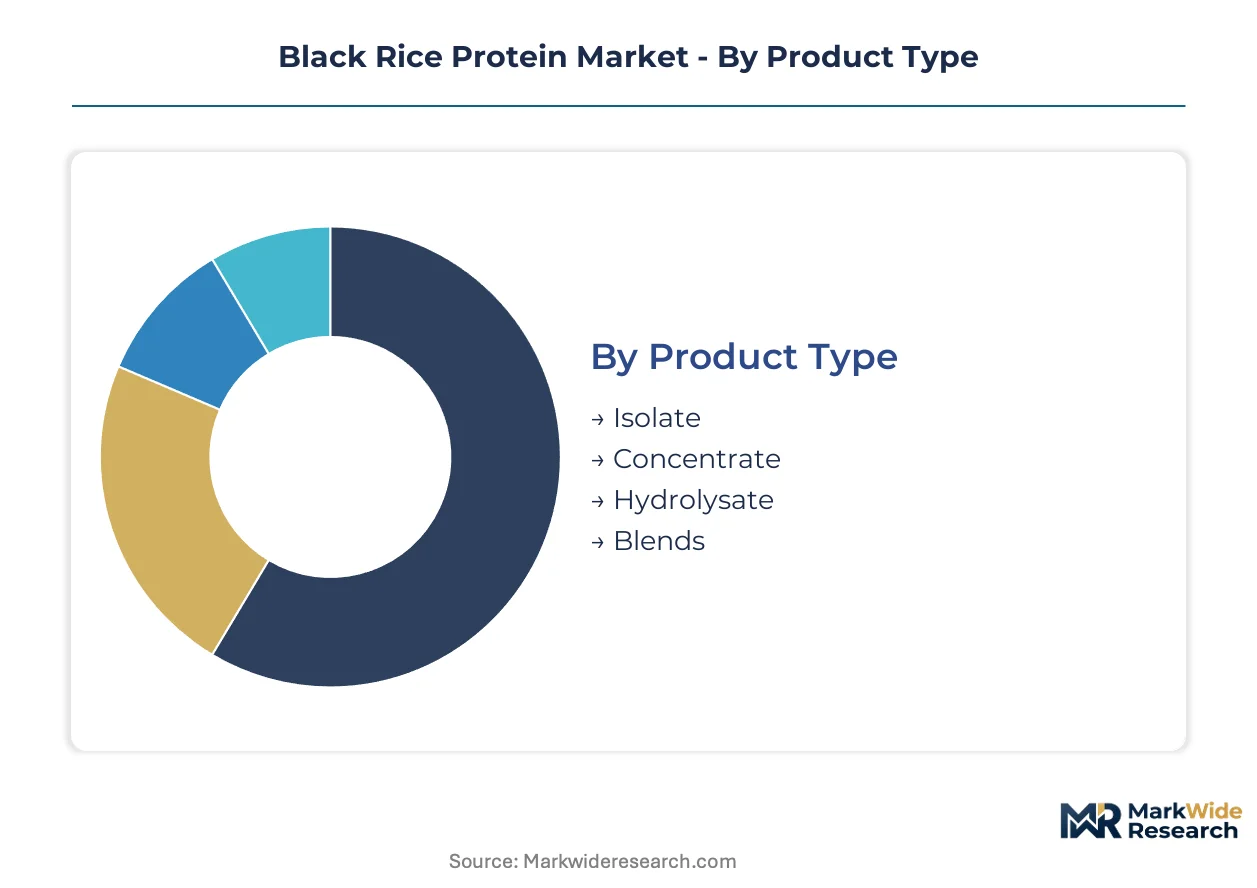
Segmentation in black rice protein reveals how extraction technology, end-use requirements, and delivery formats create distinct margin pools and procurement patterns across the value chain. Manufacturers configure production assets around isolate versus hydrolysate yields, while brand owners select forms based on shelf stability and consumer convenience expectations.
Product Type:
Mature isolation technology anchors the revenue base, while enzymatic hydrolysis represents the emerging performance tier commanding formulation premiums.
- Isolate:Aqueous or enzymatic separation yields 80-90% protein content with PDCAAS approaching 0.75 and minimal carbohydrate residue. German sports nutrition brands and US functional beverage manufacturers concentrate procurement here for hypoallergenic positioning against soy and whey alternatives.
- Hydrolysate:Partial enzymatic cleavage reduces peptide chain length for accelerated gastric emptying and absorption kinetics. Sports nutrition applications in North America and Western Europe drive demand as athletes prioritize recovery speed over cost economics.
- Concentrate:Lower purity grade retains more starch and fiber fractions, serving cost-sensitive bakery and confectionery applications where protein fortification takes secondary priority to texture and moisture binding.
- Blends:Co-processed combinations with pea or rice proteins optimize amino acid completeness and mask sensory limitations in finished goods targeting mass-market retail channels.
Isolate handles the majority of throughput; hydrolysate is the fastest mover on share.
End User:
Cost tier stratification separates premium nutritional formulations from commodity food processing applications with divergent specification tolerances.
- Nutritional Supplements:Capsule, tablet, and ready-to-drink formats demand highest protein purity with full amino acid profiling and heavy metal documentation. US and German brands lead procurement for clean-label athletic and wellness positioning.
- Food & Beverage:Plant-based dairy alternatives, meat analogs, and functional beverages incorporate black rice protein for color distinction from beige competitors and anthocyanin antioxidant claims.
- Bakery:Bread, muffin, and cookie applications leverage the ingredient's natural pigmentation and moisture retention, though protein content requirements remain modest compared to supplement grades.
- Confectionery:Chocolate and snack bar inclusions utilize black rice protein for visual differentiation and premium health halo, with binding functionality secondary to aesthetic appeal.
Nutritional supplements capture the dominant margin pool; food and beverage applications are expanding most quickly as mainstream retail distribution accelerates.
Form:
Volume concentration favors dry processing infrastructure, though convenience formats are reshaping packaging and logistics requirements.
- Powder:Spray-dried or roller-dried particulate dominates bulk ingredient shipments and consumer-facing canister formats. US functional beverage manufacturers and European supplement blenders standardize procurement around this form for reconstitution flexibility.
- Bars:Extruded and cold-pressed snack formats require specialized binding properties and moisture retention to prevent hardening during shelf life. Health-food retail channels in Germany and California drive specification innovation.
- Liquid:Pre-hydrated suspensions reduce manufacturing steps for ready-to-drink applications but constrain distribution radius and require aseptic processing investments.
- Granules:Agglomerated particles improve dispersibility in instant beverage applications, serving niche demand from hospitality and foodservice channels.
Powder sustains the largest volume position; bars show the steepest expansion trajectory as convenience-oriented consumption patterns solidify.
Application:
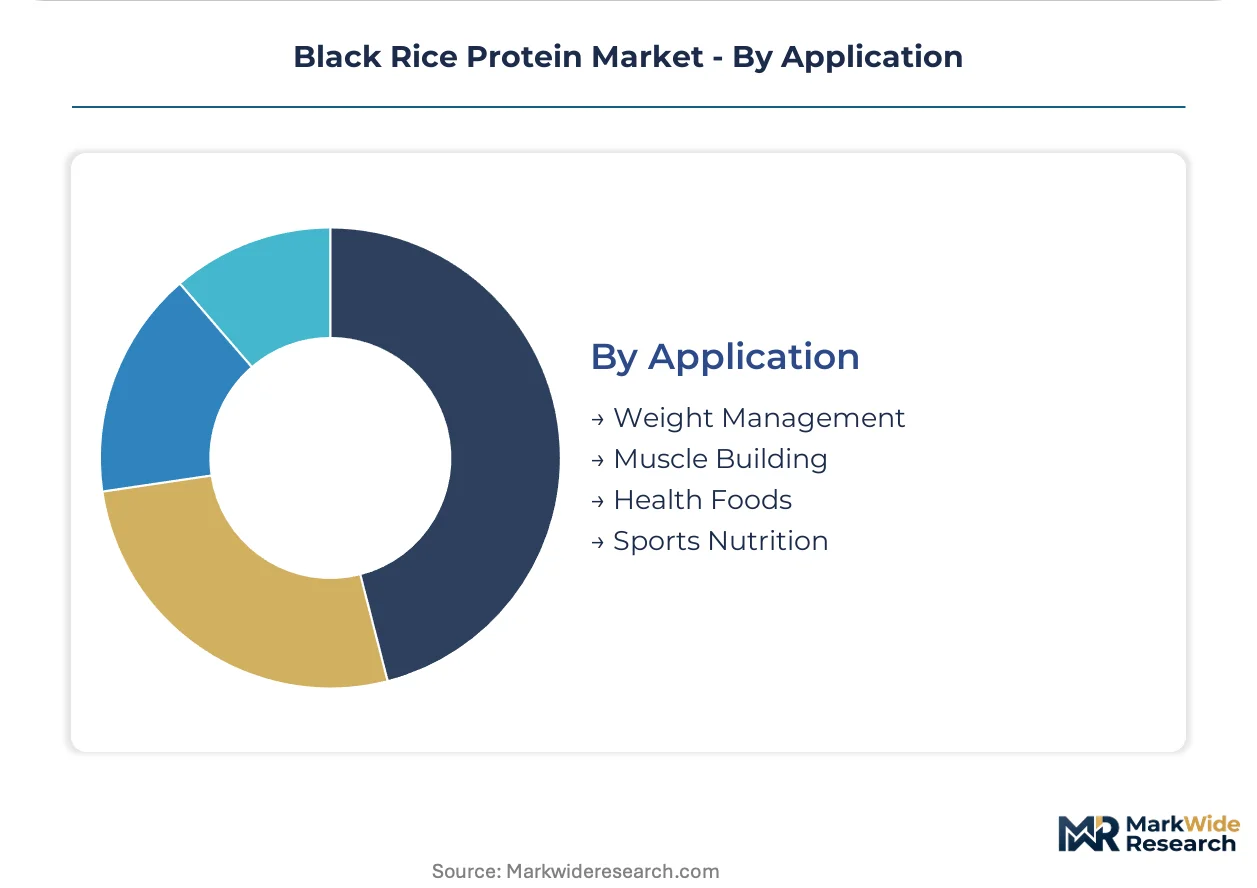
Customer type differentiation separates performance-driven athletic segments from lifestyle wellness consumers with distinct price elasticity and certification requirements.
- Sports Nutrition:Pre-workout, intra-workout, and recovery formulations demand rapid absorption kinetics and complete amino acid profiles. German athletic supplement manufacturers and US CrossFit-oriented brands anchor procurement with organic and NSF Certified for Sport requirements.
- Health Foods:General wellness positioning emphasizes antioxidant anthocyanin content and hypoallergenic credentials over performance metrics. Natural product retailers in California and Bavaria concentrate distribution.
- Weight Management:Meal replacement and satiety-focused applications leverage protein density and fiber co-fractions to prolong gastric emptying and reduce caloric intake.
- Muscle Building:Hypertrophy-oriented formulations prioritize leucine content and digestibility speed, competing directly with whey protein isolates in bodybuilding channels.
Sports nutrition commands the premium price tier; health foods are gaining share fastest as mainstream grocery distribution erases specialty channel boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean-label sports nutrition brands in Germany and functional beverage manufacturers in the United States drive the bulk of procurement volume, while contract manufacturing hubs in Brazil and cultivation clusters in Thailand anchor upstream supply.
United States
FDA GRAS self-affirmation and USDA Organic certification govern market access for black rice protein isolates. The IRA's bio-based manufacturing incentives are accelerating domestic processing investments. California's functional beverage manufacturers and Texas-based contract packers concentrate demand for hypoallergenic protein fortification.
Germany
EFSA Novel Food authorization timelines extend 18-24 months, freezing capital for new entrants. The EU Green Deal's Farm to Fork strategy tightens traceability requirements for imported Asian protein sources. Bavarian sports nutrition brands and North Rhine-Westphalia-based flavor houses drive isolate procurement for clean-label athletic formulations.
Brazil
Asset-light contract manufacturing partnerships in São Paulo and Minas Gerais states offer tariff-advantaged access to South American functional beverage markets. ANVISA's evolving novel food framework shapes ingredient approval pathways. Amazonia leverages its domestic supply base to control raw material costs across Mercosur distribution channels.
Thailand
Black rice cultivation concentrates in specific floodplains, exposing processors to climate-driven harvest variability. Direct-procurement relationships between US finished goods manufacturers and Thai cultivation cooperatives are displacing traditional trader-mediated supply chains. Bangkok-based processors and Chiang Mai organic certification bodies anchor the upstream supply base.
China
The national carbon trading scheme and impending EU CBAM are incentivizing processors to certify low-emission supply chains for premium market access. SAMR's food safety standards govern domestic processing quality. Yangtze River Delta ingredient houses and Shandong Peninsula extraction facilities concentrate enzymatic hydrolysis capacity expansion.
Black Rice Protein Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base separates into three strategic archetypes: integrated flavor-mask system providers, raw material origin controllers, and specialized plant-protein extrusion operators. Dominant competitive moves include backward integration into certified organic cultivation chains and geographic expansion through contract manufacturing partnerships in tariff-advantaged jurisdictions.
Within the origin-control archetype, Amazonia exemplifies Brazilian supply base leverage. Among North American extrusion specialists, Axiom Foods, Inc. occupies a position representing specialized plant-protein processing capabilities. On the integrated systems tier, Kerry Group plc anchors flavor-mask technology integration that offsets sensory limitations in finished applications. These three represent distinct competitive vectors: raw material cost control, processing specialization, and formulation integration.
| Leading Market Players |
|---|
| Amazonia |
| Nutraonly (Xi'an Nutrition Inc.) |
| Bioway (Xi'an) Organic Ingredients Co., Ltd. |
| Axiom Foods, Inc. |
| ETChem |
| Kerry Group plc |
| Gulshan Polyols Ltd. |
| Shafi Gluco Chem |
| Südzucker AG |
| Others |
Value Network & Pricing Analysis
Thai floodplain cultivation clusters anchor upstream supply, concentrating margin capture with processors who command certified organic premiums while exposing finished goods manufacturers to harvest-driven price volatility. Isolate grades with USDA Organic and EU Organic certification command substantial premiums over conventional hydrolysate, as German sports nutrition brands and US functional beverage manufacturers absorb cost differentials for clean-label positioning.
Pricing Analysis
Certification level creates the primary spread between USDA Organic and conventional grades, with isolate purity and amino acid completeness as secondary differentiation drivers. Three-tier pricing structure across premium certified-organic, standard food-grade, and economy feed-grade levels dominates contract negotiations. Cost compression in mid-tier hydrolysate is intensifying because enzymatic extraction capacity expansion in China and Brazil outpaces near-term demand absorption. Nutritional supplement manufacturers show least price sensitivity due to end-consumer premium tolerance, while bakery and confectionery applications face acute margin pressure.
Supply Chain Analysis
Tariff exposure between Thailand and the European Union dominates strategic sourcing decisions for organic-certified isolates. Raw material procurement draws from Thai floodplain cooperatives, Indonesian smallholder networks, and emerging Vietnamese cultivation zones. Anthocyanin stability during ocean freight, enzymatic extraction yield variability, and EFSA Novel Food authorization delays constitute primary structural vulnerabilities. Distribution runs through specialized ingredient houses in California and Bavaria, with direct-procurement relationships displacing traditional trader intermediation for traceability-compliant product lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The black rice protein market sits in early-cycle expansion as sports nutrition brands accelerate hypoallergenic formulation adoption and enzymatic hydrolysis technology matures. Penetration tailwinds from clean-label mandates at major retail chains create durable demand foundations for certified-organic supply chains.
For Market Incumbents: Build captive organic cultivation networks through equity partnerships with Thai cooperatives to lock in traceability-compliant supply. Kerry Group plc's integrated flavor-mask systems demonstrate how formulation integration moats offset commodity protein substitution threats. Expand enzymatic hydrolysis capacity in tariff-advantaged jurisdictions to preempt emerging Brazilian contract manufacturing competition. Deepen backward integration into certified organic cultivation to defend margin position against pea protein isolate encroachment.
For New Entrants and Emerging Players: Pursue bar-format specialization targeting California and German health-food retail channels where binding property innovation commands formulation premiums. White-space concentration in liquid ready-to-drink applications remains underpenetrated due to aseptic processing capital barriers. Brazilian contract manufacturing partnerships offer tariff-advantaged Mercosur market access with lower regulatory friction than EU Novel Food pathways. Direct-procurement relationships with Indonesian smallholder networks bypass established Thai processor oligopoly.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Brazilian agribusiness platforms seeking downstream processing integration. Long-term viability hinges on dual carbon compliance certification as EU CBAM implementation accelerates premium market access requirements. Acquisition targets include enzymatic extraction technology specialists with EFSA pre-submission dossiers and Southeast Asian processors with USDA-accredited organic certification. Signal to monitor: EFSA Novel Food authorization timeline compression for hydrolysate categories indicating regulatory inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Cultivation | Captive Thai supply chains secure traceability compliance for EU Green Deal Farm to Fork mandates. |
| Enzymatic Hydrolysis Capacity Expansion | Accelerated absorption kinetics command sports nutrition formulation premiums in North American markets. |
| Flavor-Mask Technology Integration | Anthocyanin-protein interaction expertise offsets sensory limitations blocking clean-label adoption. |
| Brazilian Contract Manufacturing Partnership | Tariff-advantaged Mercosur access reduces EU Novel Food authorization dependency for South American penetration. |
| Dual Carbon Compliance Certification | China national carbon trading scheme alignment unlocks premium positioning under impending EU CBAM frameworks. |
Research Methodology
Operator-level perspectives from extraction technology directors, sports nutrition brand formulation leads, organic certification body inspectors, and Thai cultivation cooperative managers anchored the qualitative base. Primary interview intelligence combined with secondary validation from FDA GRAS notification databases, EFSA Novel Food submission registers, USDA organic certification records, and ASEAN customs trade statistics. Bottom-up procurement volume modeling triangulated against top-down functional beverage and supplement market sizing.
Scenario-bracketing around EFSA authorization timeline variability and climate-driven Thai harvest volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include isolate versus hydrolysate versus concentrate grade tiers, nutritional supplement versus food and beverage versus bakery end-use applications, and powder versus bar versus liquid delivery formats. CAGRs derived from elasticity-adjusted adoption curves incorporating enzymatic extraction yield improvements and clean-label retail mandate diffusion rates.
Sensitivities concentrate around EFSA Novel Food authorization delays extending capital freeze periods and Thai floodplain climate volatility disrupting organic certified supply. Forecasts reflect documented assumptions regarding enzymatic technology maturation and retail chain clean-label compliance deadlines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Plant-Based Seafood Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
United States Textured Vegetable Protein Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Plant-Based Food and Beverages Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Vegan Food Market
Plant Based Food
Vegan Diet Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Vegan Alternatives Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Veggie Meals Market