
 Plant-Based Sausages Market | 2026-2036
Plant-Based Sausages Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Sausages Market Analytics
Premium clean-label tiering is rotating the Plant-Based Sausages Market toward higher-margin positioning. Beyond Meat leverages pea-protein extrusion scale to sustain North American retail penetration. Impossible Foods anchors foodservice partnerships through heme technology differentiation. The Vegetarian Butcher competes in European private-label supply with Unilever's manufacturing footprint.
Plant-based sausages are emulsified or extruded protein products, typically containing 10-20% fat and 15-25% protein by weight, designed to replicate the texture, flavor, and cooking performance of conventional pork or poultry sausages for direct consumer preparation or foodservice integration. Pea protein formulations now lead volume due to superior gelation and lower allergen profiles versus soy, while seitan-based variants occupy specialty stores with wheat-gluten chew structures that appeal to flexitarian meat reducers seeking familiar bite resistance. Retail channel dominance persists in refrigerated cases, though online retail growth reflects subscription-model adoption among health-conscious consumers seeking recurring delivery of clean-label options.
EFSA novel-food authorizations and FDA GRAS self-affirmation pathways govern ingredient approvals, with EFSA's stricter toxicology requirements delaying some fermentation-derived protein launches in Europe. USDA-FSIS labeling disputes over "sausage" terminology create compliance friction for US market entrants, while EU Green Deal agricultural subsidy shifts indirectly advantage domestic plant-protein sourcing. Stakeholders must monitor evolving protein-isolate tariff classifications and anticipate which regulatory jurisdiction's standards will become the de facto export benchmark.
Market Dynamics
Clean-label ingredient mandates from EFSA and the FDA are compressing formulation timelines while foodservice operators accelerate adoption curves, forcing manufacturers to reconcile regulatory compliance with scaled production.
Growth Catalysts
- EFSA Novel-Food Pathway:Accelerated approvals for fermentation-derived proteins enable faster European market entry for next-generation formulations.
- Foodservice Channel Expansion:Restaurant chains and institutional caterers now drive the fastest volume uptake as menu integration simplifies consumer trial.
- Pea Protein Extrusion Scale:Superior gelation properties and lower allergen profiles versus soy concentrate production in North American processing facilities.
Market Restraints
- Input Cost Volatility:Pea protein isolate and coconut oil prices fluctuate with agricultural yields, squeezing margin structures at mid-tier price points.
- Supply Concentration Risk:European pea protein processing clusters in France and Denmark create single-point vulnerability for continental formulation supply.
- USDA-FSIS Labeling Friction:Disputes over "sausage" terminology compliance create entry barriers and reformulation costs for US market entrants.
Strategic Opportunities
- German Retail Shelf Expansion:Refrigerated meat alternative case space growth creates premium positioning opportunities for clean-label entrants.
- Fermentation-Technology Convergence:Precision fermentation of heme and fat precursors converges with extrusion advances to unlock next-generation texture replication.
- EU Green Deal Agricultural Subsidies:Redirected domestic plant-protein sourcing incentives advantage regional supply chain development over import-dependent competitors.
Industry Challenges
- Formulation Talent Scarcity:Food scientists skilled in protein gelation and flavor masking command premium compensation, constraining R&D team scaling.
- Capex Intensity for Extrusion Lines:High-pressure twin-screw systems and cooling tunnels require substantial capital deployment for capacity expansion.
- Cross-Border Certification Timelines:Divergent EFSA and FDA toxicology requirements force parallel testing tracks, extending product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Sausages Market |
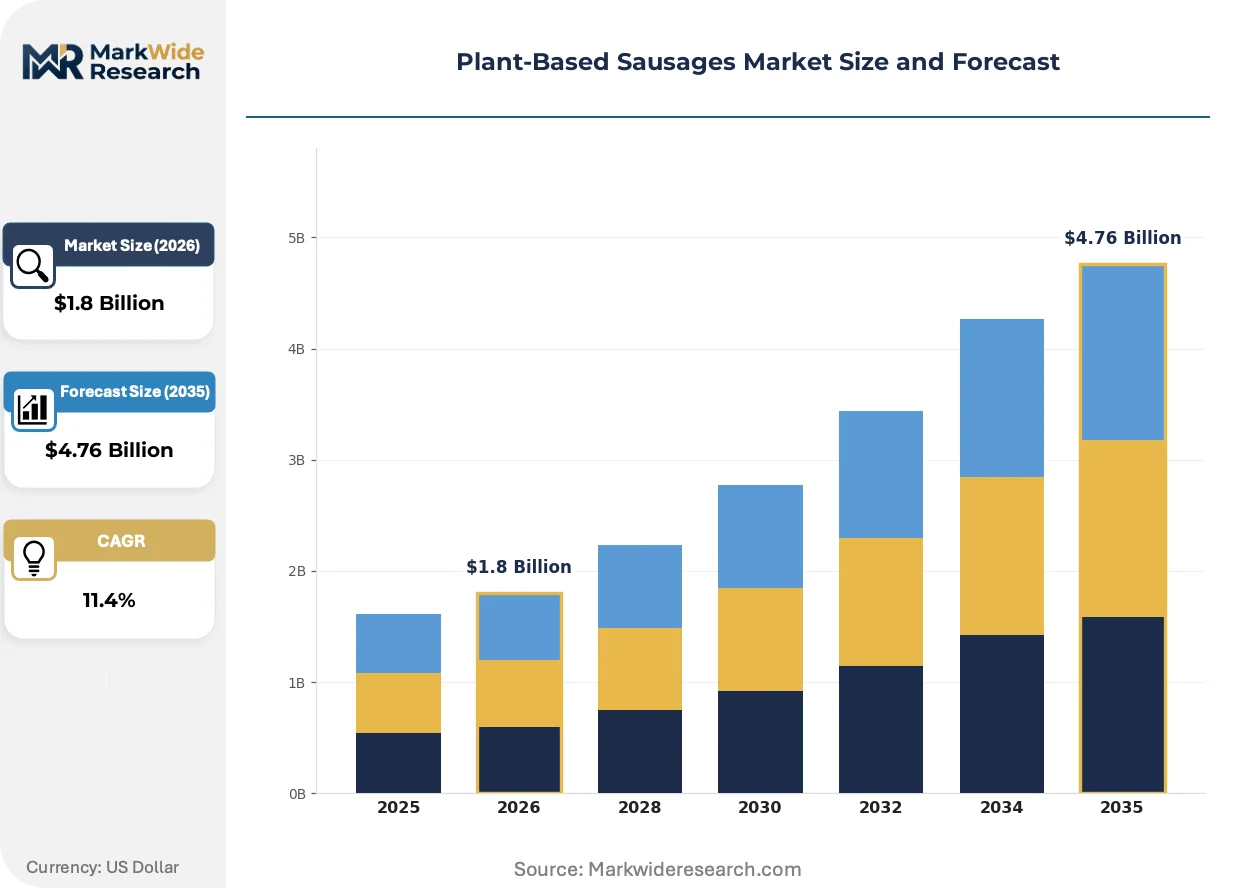
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chickpea, Tofu, Pea Protein, Seitan Application: Foodservice, Retail, Home Cooking, Vegan Diet Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Customer Type: Health Conscious Consumers, Vegans, Flexitarians, Meat Reducers |
| Companies Covered | Lightlife Foods, Quorn Foods, Beyond Meat, The Vegetarian Butcher, MorningStar Farms, Impossible Foods, Field Roast, Amy’s Kitchen, Tofurky, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Sausages Market Evolving Landscape
Extrusion technology advances and regulatory harmonization pressures are compressing product development cycles while demand patterns shift toward subscription-based recurring purchase models.
High-moisture extrusion systems are displacing traditional low-moisture processes in plant-based sausage manufacturing. Foodservice manufacturers adopt these systems to achieve fibrous muscle-like textures previously unattainable at production scale. The technology is displacing reliance on binders and texturizers, enabling shorter ingredient decks that satisfy clean-label mandates.
EFSA's stricter toxicology requirements for novel-food authorizations are reshaping European launch strategies. Fermentation-derived protein developers face extended safety evaluation timelines compared to FDA GRAS self-affirmation pathways. German and Dutch formulation teams now prioritize European sourcing to preempt regulatory scrutiny on imported novel ingredients.
Subscription retail models are capturing health-conscious consumers seeking recurring delivery of refrigerated clean-label options. Direct-to-consumer channels displace conventional supermarket trial purchases among flexitarian meat reducers. This pattern concentrates in urban German and UK markets where cold-chain logistics infrastructure supports reliable fulfillment.
Plant-Based Sausages Market Segmentation
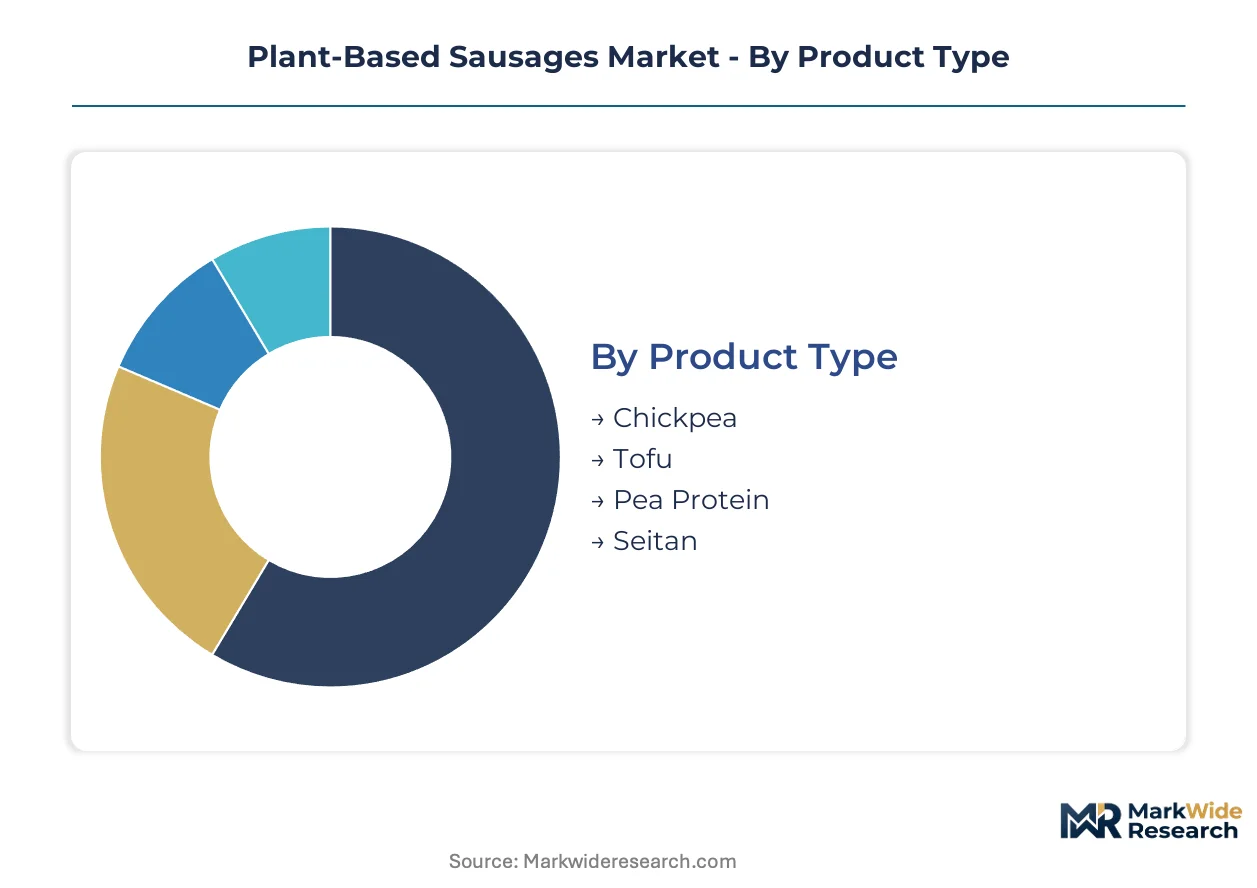
Plant-based sausage manufacturers must align formulation investments with distinct protein functionality requirements and channel-specific margin structures. Segmentation reveals where pea protein extrusion scale commands premium positioning versus where seitan and tofu occupy value-tier niches.
Product Type:
Pea protein formulations capture the widest margin pools due to superior gelation properties and clean-label positioning, while commodity tofu and seitan segments compete on price-accessibility.
- Pea Protein:Extruded isolates achieve 15-25% protein content with fibrous textures that replicate conventional sausage bite. German retail chains and North American foodservice operators concentrate procurement here, driven by EFSA's lower allergen burden versus soy and FDA GRAS pathway speed for novel isolates.
- Seitan:Wheat gluten matrices deliver 20-30% protein with pronounced chew resistance that appeals to flexitarian meat reducers seeking familiar mouthfeel. Specialty stores in France and the Netherlands stock these formats, constrained by gluten-content labeling disputes and limited high-moisture extrusion capacity.
- Chickpea:Emerging protein source with moderate emulsification properties suited to Mediterranean-flavored product lines.
- Tofu:Mature soy-based segment occupying economy tiers through established Asian supply chains and minimal processing requirements.
The dominant share belongs to Pea Protein, while Seitan is closing the gap fastest through European specialty channel expansion.
Application:
Channel selection determines formulation complexity, with foodservice demanding industrial-scale consistency and retail prioritizing refrigerated shelf-life extension.
- Foodservice:Restaurant chains and institutional caterers drive volume through standardized portioning and frozen distribution economics. Burger King, Ikea, and Compass Group procurement specifications favor high-moisture extruded formats with freeze-thaw stability, accelerating manufacturer investment in twin-screw production lines.
- Retail:Refrigerated case placement dominates in German supermarkets where expanded meat-alternative sections command premium price points. Clean-label ingredient decks with fewer than ten components satisfy EFSA disclosure requirements and support subscription-model adoption in UK urban markets.
- Home Cooking:Consumer preparation occasions favor pre-cooked formats with simplified cooking instructions and shorter ingredient lists.
- Vegan Diet:Strict plant-based adherence segments prioritize certified vegan supply chains and allergen-free production facilities.
Foodservice holds the volume lead, though Retail is expanding most quickly through German and UK refrigerated case growth.
Distribution Channel:
Supermarket refrigerated infrastructure anchors mainstream penetration, while digital channels capture subscription-driven recurring revenue with superior customer data capture.
- Supermarkets:German retailers including REWE and Edeka have expanded dedicated meat-alternative sections by 40% in refrigerated cases, creating premium positioning opportunities for clean-label entrants with EFSA-compliant ingredient decks.
- Online Retail:Direct-to-consumer subscription models concentrate in London, Berlin, and Amsterdam where cold-chain logistics infrastructure supports reliable fulfillment of refrigerated products.
- Specialty Stores:Natural food retailers and organic chains curate artisanal seitan and fermented protein formats.
- Convenience Stores:Limited refrigerated space restricts assortment to ambient-stable, pre-cooked formats with extended shelf life.
Supermarkets maintain the installed base advantage, yet Online Retail is climbing the fastest through urban subscription adoption.
Customer Type:
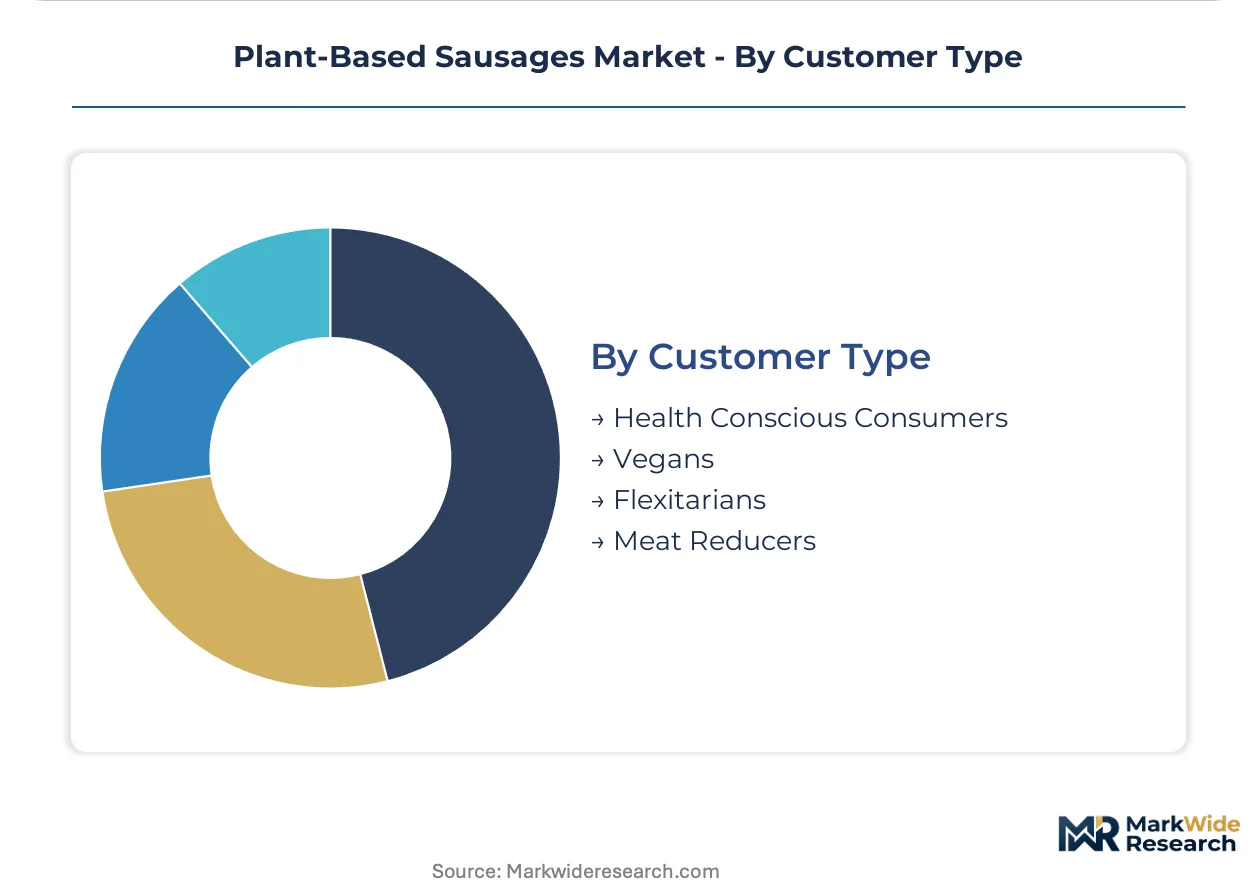
Flexitarian meat reducers present the largest addressable population, while vegan purists command premium pricing tolerance for certified supply chains.
- Flexitarians:Meat-reducing consumers seeking familiar taste and texture without dietary commitment drive mainstream volume. This segment tolerates moderate price premiums for products replicating conventional sausage cooking performance, particularly in German and UK urban households.
- Health Conscious Consumers:Protein-seeking buyers prioritize nutritional density and sodium reduction, favoring pea protein isolates with complete amino acid profiles and clean-label positioning that satisfies FDA nutritional disclosure requirements.
- Vegans:Strict plant-based adherence requires certified vegan production facilities and supply chain documentation.
- Meat Reducers:Environmental and ethical motivation segments respond to carbon-footprint labeling and EU Green Deal agricultural sourcing claims.
Flexitarians represent the deepest volume pool, while Health Conscious Consumers are gaining share fastest through protein-focused marketing and nutritional transparency requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pea protein processing clusters in France and Denmark concentrate European supply, while North American extrusion capacity expands fastest. German retail infrastructure anchors continental demand growth. Regulatory divergence between EFSA and FDA pathways shapes regional launch strategies.
Germany
REWE and Edeka have expanded refrigerated meat-alternative sections by 40%, creating premium positioning opportunities for clean-label entrants. The EU Green Deal redirects agricultural subsidies toward domestic plant-protein sourcing. Berlin and Hamburg anchor foodservice procurement networks for institutional caterers and restaurant chains.
United States
Burger King and Compass Group procurement specifications drive volume through standardized portioning and frozen distribution economics. USDA-FSIS labeling disputes over "sausage" terminology create compliance friction and reformulation costs. Twin-screw extrusion capacity concentrates in California and Illinois processing corridors.
United Kingdom
London and Amsterdam anchor subscription-model adoption among health-conscious consumers seeking recurring delivery of refrigerated clean-label options. EFSA disclosure requirements shape ingredient deck simplification strategies. Urban cold-chain logistics infrastructure supports reliable fulfillment of direct-to-consumer channels.
Netherlands
The Vegetarian Butcher leverages Unilever's manufacturing footprint to compete in European private-label supply. EFSA novel-food authorizations for fermentation-derived proteins face stricter toxicology requirements than FDA pathways. Dutch formulation teams prioritize European sourcing to preempt regulatory scrutiny on imported novel ingredients.
France
Specialty stores in Paris and Lyon stock seitan-based formats with pronounced chew resistance appealing to flexitarian meat reducers. Gluten-content labeling disputes constrain high-moisture extrusion capacity expansion. French pea protein processing clusters create single-point vulnerability for continental formulation supply.
Plant-Based Sausages Market Competitive Landscape
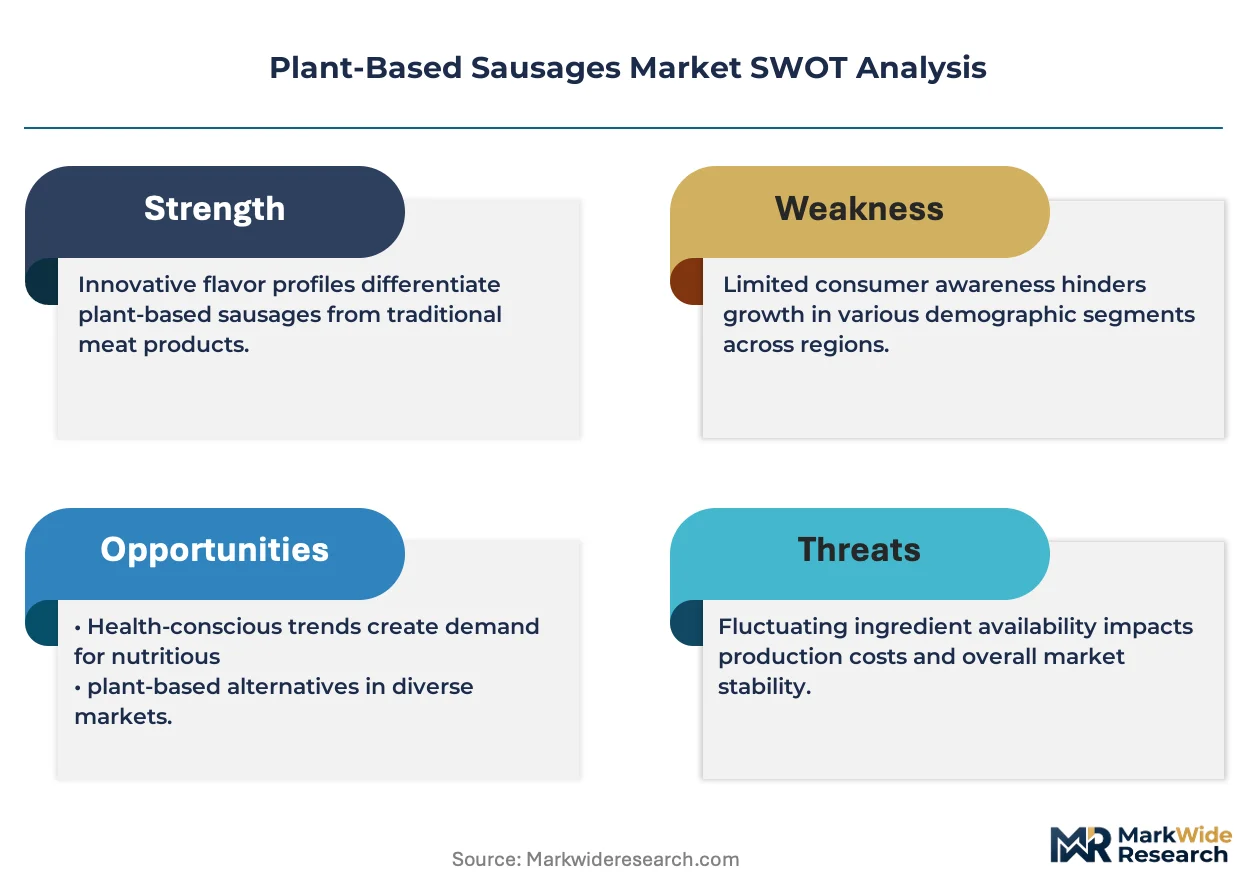
Technology leadership and cost leadership are held by different player archetypes within the plant-based sausages market. Pea-protein extrusion specialists command premium positioning through superior gelation properties, while soy and wheat-gluten processors compete on price-accessibility in economy tiers. The competitive landscape fragments across three strategic archetypes: venture-backed novel-protein developers, multinational consumer goods conglomerates with captive manufacturing, and artisanal specialists serving natural food retail. Dominant competitive moves include foodservice partnership anchoring and high-pressure twin-screw extrusion capacity expansion.
Among venture-backed protein technology developers, Beyond Meat and Impossible Foods occupy positions defined by differentiated platform approaches. Beyond Meat exemplifies the pea-protein extrusion scale archetype with North American retail penetration strategies. Impossible Foods represents the fermentation-technology differentiation vector through heme platform development and foodservice partnership concentration. Quorn Foods anchors the mycoprotein fermentation specialist tier with European manufacturing heritage.
| Leading Market Players |
|---|
| Lightlife Foods |
| Quorn Foods |
| Beyond Meat |
| The Vegetarian Butcher |
| MorningStar Farms |
| Impossible Foods |
| Field Roast |
| Amy's Kitchen |
| Tofurky |
| Others |
Value Network & Pricing Analysis
Pea protein displacement of soy concentrates redraws procurement geography toward French and Danish processing clusters while compressing mid-tier price points through input cost volatility. This substitution dynamic simultaneously elevates premium-tier positioning for clean-label isolates and squeezes margin structures where coconut oil and pea protein isolate prices fluctuate with agricultural yields.
Pricing Analysis
EFSA novel-food disclosure requirements dictate the pricing tier structure across European markets, separating premium clean-label formulations with sub-ten ingredient decks from standard extruded formats and economy-tier tofu alternatives. Price differentiation rests on certification grade for allergen-free production and volume scale for foodservice procurement contracts. Cost compression in the standard tier is intensifying because input cost volatility for pea protein isolates and coconut oil squeezes manufacturers without backward integration into processing. Foodservice operators demonstrate the lowest price sensitivity due to standardized portioning economics, while retail flexitarian consumers exhibit highest sensitivity to per-unit premiums.
Supply Chain Analysis
Strategic stockpiling of pea protein isolates prevails over just-in-time preferences as manufacturers buffer against agricultural yield volatility and French processing cluster disruptions. Geographic supply concentration centers on France, Denmark, and North American Midwest corridors for pea protein extraction, with coconut oil sourcing anchored in Southeast Asian and South American origins. Raw material dependencies draw from pea protein isolates, coconut oil, and heme fermentation precursors. Single-source vulnerability in European pea protein processing creates systemic risk for continental formulation supply. Distribution runs through frozen foodservice logistics networks and refrigerated retail cold chains with subscription-model direct fulfillment emerging in urban UK and German markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-model recurring revenue layers expand faster than unit sales in this market, creating service-attach opportunities through direct-to-consumer cold-chain fulfillment and personalized nutrition programming.
For Market Incumbents: Secure captive supply of pea protein isolates through backward integration into French or Danish processing assets before input cost volatility erodes mid-tier margins. Anchor foodservice partnerships with multi-year procurement contracts that lock in volume commitments from Burger King-scale operators and institutional caterers. Defend against fermentation-derived protein substitutes by accelerating EFSA novel-food pathway submissions for next-generation texture technologies. For New Entrants and Emerging Players: FDA GRAS self-affirmation fast-tracks offer the most penetrable regulatory entry point for North American market establishment before pursuing EFSA's stricter toxicology timeline. Target German refrigerated retail expansion where REWE and Edeka shelf space growth outpaces supply of clean-label entrants. Pursue direct-to-consumer subscription launch in London and Berlin urban corridors as the primary go-to-market angle, leveraging existing cold-chain infrastructure for recurring revenue capture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed novel-protein developers facing extended EFSA approval timelines and cash runway constraints. Long-term viability across the analysis window favors manufacturers with demonstrated high-moisture extrusion scale and established foodservice procurement relationships over technology-only platforms. Monitor fermentation-derived protein EFSA authorization velocity as the critical inflection signal for next-generation formulation competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | Twin-screw system deployment enables fibrous texture replication that satisfies Burger King procurement specifications. |
| EFSA Novel-Food Pathway Acceleration | Faster toxicology clearance unlocks European market entry for fermentation-derived heme and fat precursors. |
| Backward Integration into Pea Processing | Captive supply of French or Danish protein isolates insulates margins from agricultural yield volatility. |
| Foodservice Partnership Anchoring | Multi-year Compass Group contracts provide volume certainty that justifies capex-intensive production lines. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture in Berlin and London urban markets displaces conventional supermarket trial economics. |
Research Methodology
A spread of perspectives from foodservice procurement directors, plant-based R&D formulation scientists, refrigerated retail category buyers, and cold-chain logistics operators converged on the working assumptions underlying demand and supply trajectories. Primary interview insights combined with secondary validation from EFSA novel-food authorization databases, FDA GRAS notification filings, Nielsen retail audit data for meat-alternative sections, and customs records for pea protein isolate trade flows. Bottom-up volume builds for each protein source and application channel triangulated against top-down market sizing from agricultural subsidy redirection patterns under the EU Green Deal.
Segmentation dimensions modeled include protein source technology, application channel, distribution format, and customer dietary motivation archetype across the projection horizon. CAGRs derived from weighted regression of historical adoption curves against regulatory pathway velocity and foodservice penetration rates. Industry-specific forecast inputs incorporated twin-screw extrusion capacity expansion timelines and EFSA toxicology evaluation queue depths for fermentation-derived ingredients.
Decision-makers should treat outputs as directional under assumptions of sustained EFSA-FDA regulatory divergence and continued EU agricultural subsidy redirection; material deviation in either would warrant model refresh. Revision becomes warranted when foodservice procurement specification shifts or clean-label ingredient disclosure thresholds cross regulatory thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Margarine Market
Plant Based Food
India Plant Protein Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Spreads Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Vegan Bacon Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
Plant Based Tuna Market
Plant Based Food
United States Pea Protein Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
United States Textured Vegetable Protein Market
Plant Based Food
Veggie Burger Market
Plant Based Food
Vegan Cookies Market