
 Vegan Diet Market | 2026-2036
Vegan Diet Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Diet Market Insights
Flexitarian households is redrawing procurement priorities across retail and foodservice channels. Beyond Meat leverages its extrusion technology leadership to sustain premium positioning in North American grocery. Danone S.A. anchors European dairy-alternative supply through its specialized fermentation infrastructure. Amy's Kitchen competes on clean-label formulations that dominate the frozen vegan meal aisle.
A vegan diet excludes all animal-derived ingredients and relies on plant proteins, fortified nutrients, and emulsion-stabilized formulations to replicate sensory properties of conventional foods. The approach serves industrial meal production, direct retail, and clinical nutrition programs requiring controlled saturated-fat profiles. Dairy substitutes lead current revenue pools due to established oat and soy extraction scale, while meat alternatives represent the fastest-growing segment as mycoprotein and pea-isolate extrusion matures. Online retail channels are capturing disproportionate growth as direct-to-subscription models reduce conventional supermarket slotting costs.
The FDA governs allergen labeling and novel ingredient GRAS status for plant-based proteins entering US interstate commerce. EFSA and the EU Green Deal shape European formulation standards through carbon-footprint disclosure mandates and protein-source sustainability thresholds. Stakeholders must monitor evolving nomenclature rules that restrict dairy and meat terminology on vegan product labels across multiple jurisdictions.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing formulation timelines for plant-based food producers while mycoprotein extrusion advances compress the cost gap with animal proteins.
Growth Catalysts
- Carbon-footprint disclosure mandates:EFSA thresholds under the EU Green Deal force reformulation toward low-emission protein sources. Food manufacturers accelerate oat and pea-protein adoption to meet disclosure requirements.
- Institutional foodservice procurement:Hospital and university meal programs in Germany expand plant-based menu ratios. Contract caterers reconfigure supply agreements to capture flexitarian household demand.
- Direct-to-subscription retail:Online channels bypass supermarket slotting fees. Specialized vegan meal-kit providers capture recurring revenue through personalized nutrition algorithms.
Market Restraints
- Pea-protein input volatility:Concentrated Canadian and Ukrainian growing regions expose processors to climate-driven supply shocks. Price spikes compress margins for isolate producers.
- GRAS timeline friction:FDA novel-ingredient reviews for fermented proteins extend commercialization cycles. Startups face 18-24 month approval windows before interstate distribution.
- Dairy terminology restrictions:Evolving nomenclature rules across France, Germany, and Italy block "milk" and "cheese" labels on oat and soy products. Reformulation and rebranding costs accumulate.
Strategic Opportunities
- Clinical nutrition programs:Controlled saturated-fat profiles in vegan formulations meet cardiac rehabilitation protocols. Hospital systems in the Netherlands pilot prescription meal programs.
- Emulsion-stabilized seafood alternatives:Algae-protein and legume-starch combinations replicate flaky textures. Foodservice distributors in coastal Spain test placement in institutional cafeterias.
- EU protein-source sustainability thresholds:Incentive structures reward domestic pulse cultivation. French and German processors secure preferential sourcing contracts through Farm to Fork compliance.
Industry Challenges
- Fermentation infrastructure capex:Precision bioreactors for mycoprotein production require nine-figure facility investments. Mid-scale entrants struggle to achieve unit economics against established dairy-alternative players.
- Clean-label formulation expertise:Shortages of food scientists skilled in natural emulsion stabilization slow product pipeline velocity. Technical recruitment competes with pharmaceutical and cosmetics sectors.
- Allergen cross-contamination protocols:Shared extrusion lines between soy and nut proteins trigger labeling complexity. Manufacturers face batch segregation costs and extended sanitation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Diet Market |
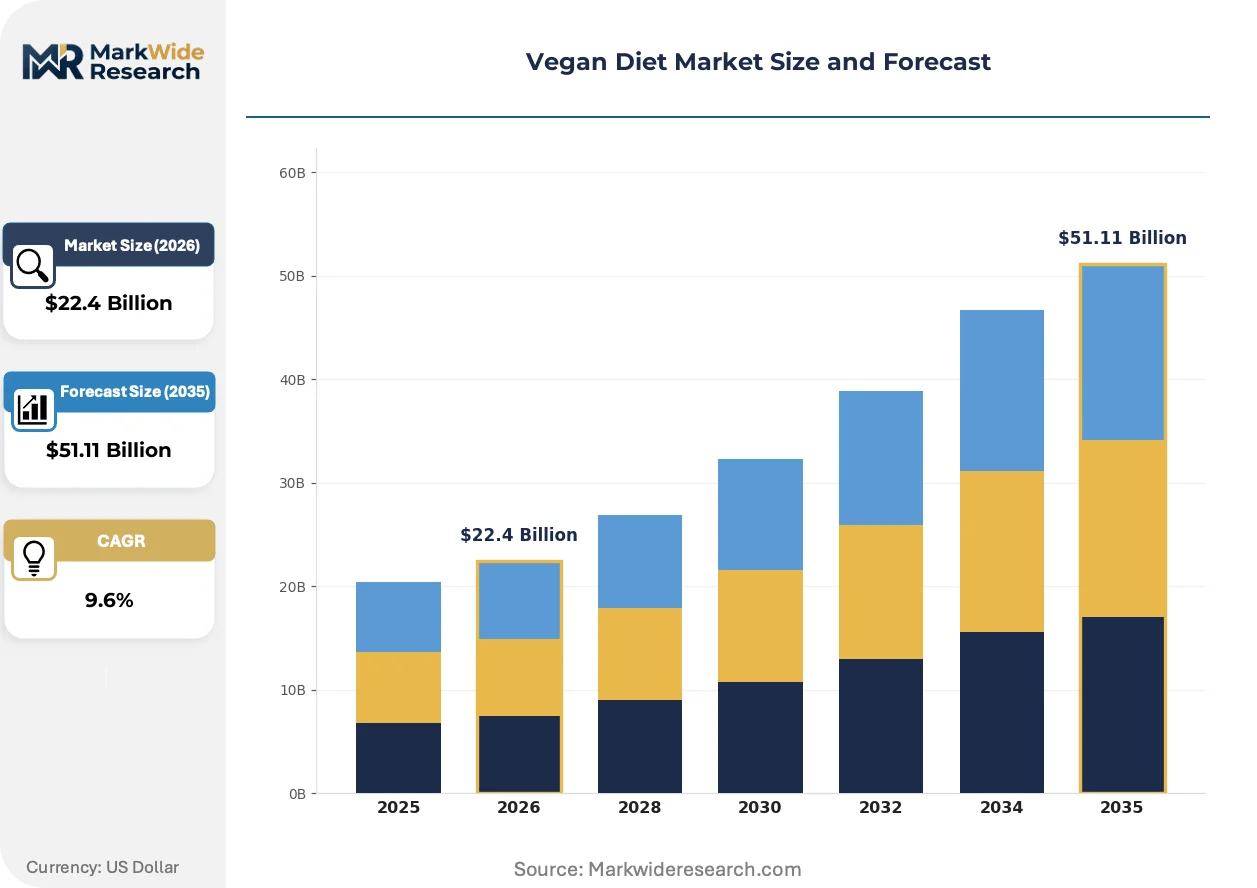
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $51.11 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Alternatives, Dairy Substitutes, Egg Replacements, Snacks Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Shops End User: Health-conscious Consumers, Environmental Advocates, Ethical Eaters, Fitness Enthusiasts Form: Frozen, Shelf-stable, Refrigerated, Ready-to-eat |
| Companies Covered | Danone S.A., Beyond Meat, Impossible Foods Inc., The Hain Celestial Group, Inc., Amy's Kitchen, Tofutti Brands Inc., Daiya Foods Inc., Archer Daniels Midland Company, SunOpta Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Diet Market Trends and Innovations
Extrusion technology advances and regulatory disclosure mandates are restructuring how plant-based proteins achieve sensory parity with conventional foods while supply chains localize.
High-moisture extrusion systems are miniaturizing. These units replicate muscle-fiber textures through shear-cell processing without cooling dies. Mid-sized European co-manufacturers deploy compact extruders to serve regional foodservice chains. Equipment footprint reduction is miniaturizing capital barriers for specialty protein entrants.
EFSA carbon-footprint disclosure mandates under the EU Green Deal reshape procurement specifications. Food manufacturers must document protein-source emissions across tier-two suppliers. Dairy-alternative processors in Germany and France renegotiate oat and soy contracts to secure verified low-carbon certificates. Reformulation priorities now weight emissions intensity alongside cost and functionality.
Subscription-based direct retail displaces conventional supermarket dominance. Vegan meal-kit providers capture recurring revenue through algorithm-driven personalization. German and UK households demonstrate highest conversion rates for weekly plant-based box deliveries. Channel disintermediation compresses slotting-fee burdens while extending customer lifetime value through data-driven menu curation.
Vegan Diet Market Segmentation
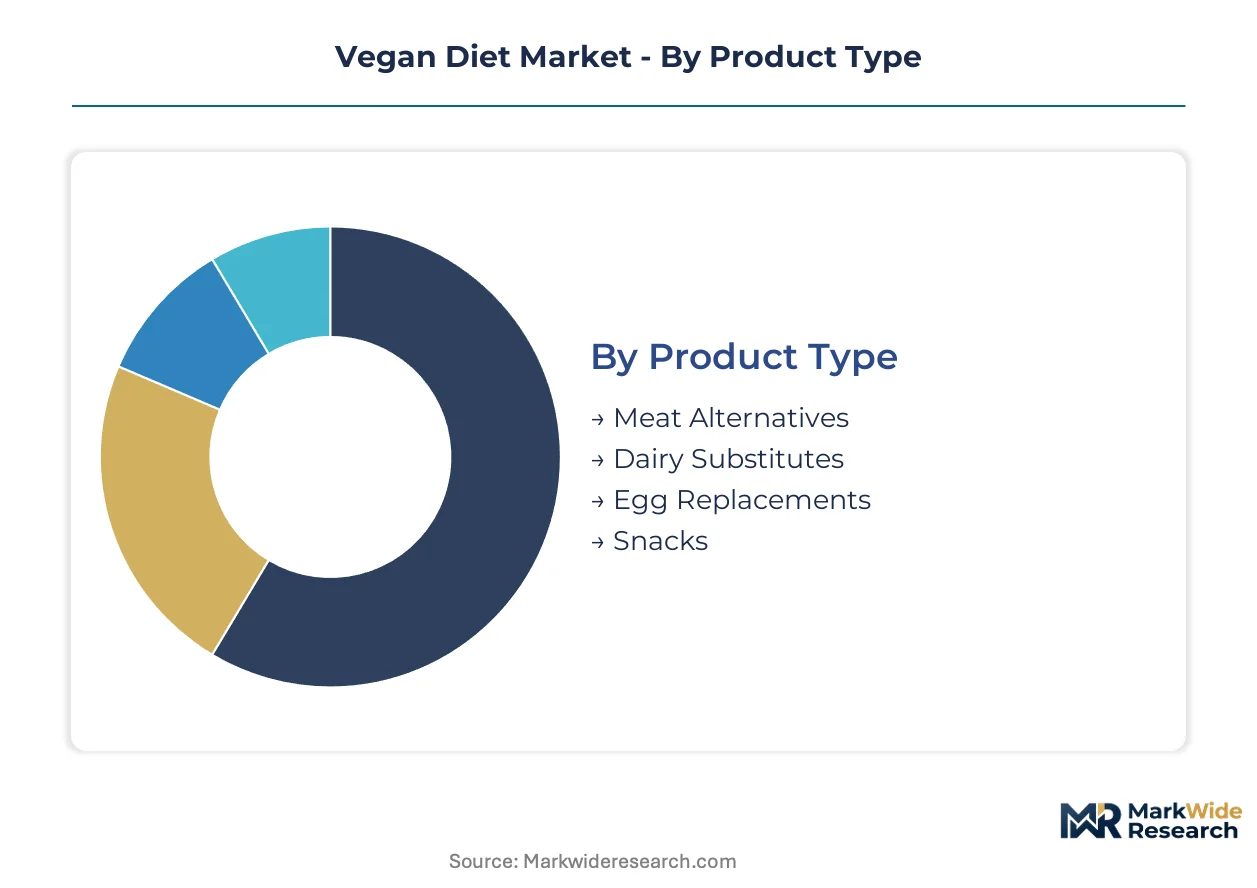
Plant-based food producers navigate divergent technical specifications and channel economics across product formats. Regulatory frameworks from FDA GRAS requirements to EFSA carbon-disclosure mandates reshape formulation priorities differently by segment.
Product Type:
FDA allergen protocols and EU dairy-terminology restrictions create uneven compliance burdens across protein categories.
- Dairy Substitutes:Oat and soy extraction infrastructure delivers established economies of scale. German retailers have expanded refrigerated shelf space for barista-grade oat formulations. EFSA carbon-footprint disclosure mandates accelerate contract renegotiations for low-emission certificates.
- Meat Alternatives:High-moisture extrusion replicates muscle-fiber textures through shear-cell processing. Pea-protein isolate supply from Canadian growing regions faces climate-driven volatility. Mycoprotein fermentation advances narrow the cost gap with conventional proteins.
- Egg Replacements:Legume-starch and algae-protein combinations emulate binding and foaming properties in industrial baking applications.
- Snacks:Extruded pulse crisps and puffed mycoprotein bites target convenience-channel placement with clean-label positioning.
Dairy Substitutes handles the majority of throughput; Meat Alternatives is expanding most quickly on share.
Distribution Channel:
Channel economics vary sharply between slotting-fee structures and customer acquisition costs.
- Online Retail:Direct-to-subscription models bypass supermarket slotting fees through algorithm-driven personalization. German and UK households demonstrate highest conversion rates for weekly plant-based box deliveries. Recurring revenue mechanics extend customer lifetime value through data-driven menu curation.
- Supermarkets:Conventional grocery dominates absolute volume but faces margin compression from refrigerated logistics and promotional spending. Retailers in France and Italy enforce evolving nomenclature rules that restrict dairy terminology on plant-based labels.
- Health Food Stores:Curated assortments command premium positioning through certified organic and non-GMO verification stacks.
- Specialty Shops:Independent retailers in urban clusters serve flexitarian households seeking novel fermentation-based proteins.
Supermarkets retains volume leadership; Online Retail climbs the fastest on penetration rates.
End User:
Motivation-based segmentation determines price elasticity and reformulation responsiveness.
- Health-conscious Consumers:Cardiac rehabilitation protocols and controlled saturated-fat requirements drive institutional procurement. Hospital systems in the Netherlands pilot prescription meal programs with verified nutritional profiles.
- Environmental Advocates:EU Green Deal compliance and carbon-footprint transparency dominate purchase decisions. Farm to Fork Strategy incentive structures reward domestic pulse cultivation with preferential sourcing contracts.
- Ethical Eaters:Animal-welfare certification and supply-chain auditability command substantial price premiums in specialty channels.
- Fitness Enthusiasts:High-protein formulations with complete amino-acid profiles target performance nutrition applications.
Health-conscious Consumers anchors institutional demand; Environmental Advocates gains share fastest on regulatory tailwinds.
Form:
Cold-chain requirements and shelf-life specifications dictate manufacturing location and inventory velocity.
- Frozen:Extended shelf life enables centralized production at scale. Amy's Kitchen dominates the frozen vegan meal aisle through clean-label formulations and extrusion technology integration.
- Refrigerated:Barista-grade oat milks and fresh meat alternatives command premium pricing but require regional distribution infrastructure. German retailers have expanded dedicated refrigerated sections.
- Shelf-stable:Aseptic packaging and retort processing reduce logistics costs for emergency foodservice procurement and export markets.
- Ready-to-eat:Chilled prepared meals target contract catering and university meal programs with portion-controlled convenience.
Frozen concentrates manufacturing scale; Refrigerated shows steepest expansion trajectory on fresh-format demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pea-protein processing infrastructure clusters in Canada and Ukraine, exposing manufacturers to climate-driven supply volatility. European fermentation capacity concentrates in Germany and the Netherlands, where precision bioreactors serve mycoprotein production. German retailers have expanded refrigerated shelf space for oat-based formulations, anchoring continental procurement patterns.
Germany
Hospital and university meal programs in Berlin and Munich expand plant-based menu ratios to capture flexitarian household demand. The EU Green Deal's Farm to Fork Strategy tightens carbon-footprint disclosure requirements through EFSA thresholds. Bavarian processors renegotiate oat and soy contracts to secure verified low-carbon certificates for dairy-alternative production.
United States
FDA novel-ingredient reviews for fermented proteins extend commercialization cycles for startups entering interstate distribution. Health-conscious consumers in institutional foodservice drive procurement of controlled saturated-fat formulations. California-based co-manufacturers deploy compact high-moisture extruders to serve regional foodservice chains with muscle-fiber texture replication.
Netherlands
Hospital systems in Amsterdam and Rotterdam pilot prescription meal programs with verified cardiac rehabilitation nutritional profiles. EFSA carbon-footprint mandates reshape procurement specifications across tier-two suppliers. Dutch fermentation specialists anchor European mycoprotein supply through precision bioreactor infrastructure.
France
Evolving nomenclature rules restrict "milk" and "cheese" terminology on oat and soy products, accumulating reformulation and rebranding costs. Environmental advocates dominate purchase decisions through EU Green Deal compliance requirements. Parisian retailers enforce dairy-terminology restrictions while expanding shelf space for compliant plant-based alternatives.
United Kingdom
Online retail channels capture disproportionate growth as direct-to-subscription models reduce conventional supermarket slotting costs. London households demonstrate highest conversion rates for weekly plant-based box deliveries with algorithm-driven personalization. British meal-kit providers extend customer lifetime value through data-driven menu curation.
Vegan Diet Market Competitive Landscape
Concentration sits with diversified food conglomerates and specialized plant-protein pure-plays. The vendor base spans multinational dairy-alternative processors, mycoprotein fermentation specialists, and frozen meal formulators with clean-label positioning. Three archetypes dominate: extrusion-technology leaders, fermentation-infrastructure owners, and direct-to-consumer subscription operators. Competitive moves center on capacity expansion in precision bioreactors and strategic partnerships with institutional foodservice distributors.
Among North American innovators, Beyond Meat and Impossible Foods Inc. exemplify the extrusion-technology archetype, while Danone S.A. anchors European dairy-alternative supply through specialized fermentation infrastructure. Amy's Kitchen occupies a position within the frozen meal tier, competing on clean-label formulations. These three entities represent distinct competitive vectors: mycoprotein cost-parity pursuit, established oat and soy extraction scale, and clean-label convenience positioning.
| Leading Market Players |
|---|
| Danone S.A. |
| Beyond Meat |
| Impossible Foods Inc. |
| The Hain Celestial Group, Inc. |
| Amy's Kitchen |
| Tofutti Brands Inc. |
| Daiya Foods Inc. |
| Archer Daniels Midland Company |
| SunOpta Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for Canadian and Ukrainian pea-protein isolate lock in supply access and price visibility for European extrusion processors, insulating them from spot-market volatility while compressing margin flexibility when climate shocks disrupt growing regions.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across plant-based protein categories. Three-tier pricing structure across premium, standard, and economy levels separates certified low-carbon oat formulations from conventional isolates and commodity-grade concentrates. Price differentiation rests on EFSA carbon-footprint verification and organic certification grade. Cost compression in standard-tier isolates is intensifying because pea-protein input volatility from concentrated growing regions squeezes processor margins. Health-conscious consumers in institutional foodservice demonstrate lowest price sensitivity, while flexitarian households in retail channels exhibit highest elasticity.
Supply Chain Analysis
Black Sea transit corridors for Ukrainian pulse exports expose European processors to geopolitical chokepoint risk. Supply concentrates in Canada, Ukraine, and France for pea-protein cultivation and processing infrastructure. Raw material dependencies center on yellow pea isolates, oat starch, and mycoprotein fermentation feedstock. Single-source vulnerability runs through concentrated Canadian prairie growing regions for high-protein cultivars. Distribution feeds from regional extrusion facilities in Germany and the Netherlands into refrigerated logistics networks serving retail and foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-moisture extrusion miniaturization is disrupting incumbent scale advantages, compressing the capital barrier for regional co-manufacturers and fragmenting production geography across the EU.
For Market Incumbents: Consolidate fermentation infrastructure ownership through precision bioreactor capacity additions in the Netherlands and Germany. Secure backward integration into domestic pulse cultivation under Farm to Fork incentive structures to defend against climate-driven input volatility from Canadian supply concentration. Capture flexitarian household demand through direct-to-subscription channel control, bypassing supermarket slotting-fee compression. For New Entrants and Emerging Players: Anchor in clinical nutrition programs requiring controlled saturated-fat profiles, where cardiac rehabilitation protocols in Dutch and German hospital systems create procurement pull. Target prescription meal program pilots as the most penetrable application, leveraging algorithm-driven personalization to differentiate from commodity frozen formats. Pursue co-manufacturing partnerships with mid-scale European extrusion operators to minimize nine-figure fermentation capex requirements. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation-infrastructure owners with established precision bioreactor networks and verified low-carbon supply contracts. Long-term viability favors processors demonstrating Farm to Fork compliance and EFSA disclosure readiness. Watch mycoprotein cost-parity milestones against conventional animal proteins as the signal for sector inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Bioreactor Capacity Expansion | Captures mycoprotein scale economies before fermentation infrastructure shortages harden. |
| Domestic Pulse Cultivation Contracts | Secures Farm to Fork compliance and EFSA carbon-footprint verification for German processors. |
| Direct-to-Subscription Channel Launch | Bypasses supermarket slotting fees while extending customer lifetime value through data-driven curation. |
| Clinical Nutrition Program Partnerships | Locks in institutional procurement from Dutch hospital systems piloting prescription meal protocols. |
| Clean-Label Formulation Certification | Differentiates frozen meal positioning against Amy's Kitchen dominance in retail aisles. |
Research Methodology
Operator-level perspectives from plant-protein procurement managers, extrusion technology engineers, institutional foodservice directors, and EFSA regulatory affairs specialists anchored the qualitative base. Primary interview data triangulated against secondary validation from EU Green Deal policy documents, EFSA carbon-footprint disclosure guidelines, German retail audit data, and SEC filings from publicly traded food conglomerates. Bottom-up volume modeling and top-down value reconciliation ensured cross-verification across the analysis window.
Sensitivity analysis tested forecast robustness across protein-source price volatility scenarios and regulatory timeline variations. Segmentation dimensions modeled include product type, distribution channel, end-user motivation, and form factor across the projection horizon. CAGRs derived from trend extrapolation of oat and soy extraction scale, mycoprotein fermentation yield improvements, and online retail penetration curves. Industry-specific inputs incorporated pea-protein isolate supply elasticity and refrigerated logistics cost trajectories.
Material uncertainties — climate-driven crop failures in prairie growing regions, FDA GRAS timeline extensions for novel fermented proteins, and evolving dairy-terminology restrictions across France, Germany, and Italy — sit outside the modeled envelope. Forecasts reflect assumptions about extrusion technology adoption rates and EFSA disclosure compliance timelines. Practitioners should keep alternative scenarios live as Farm to Fork incentive structures and carbon-certificate verification protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
United States Rice Protein Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
West Africa Plant Based Product Market
Plant Based Food
Africa Pea Protein Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
Global Plant Based Food Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
Global Organic Soy Protein Market