
 Smart Plant Based Food Packaging Market | 2026-2036
Smart Plant Based Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Plant Based Food Packaging Market Outlook
Subscription-based freshness monitoring is pivoting how packaging value gets captured, shifting one-time material sales toward recurring sensor-data revenue. Notpla leverages its seaweed-derived coating platform to anchor coastal manufacturing clusters in the UK. Ecovative Design sustains R&D intensity through mycelium-composite specialization. Xampla competes on molecular precision in plant-protein film formation.
Smart plant based food packaging comprises bio-derived barrier systems engineered from polysaccharides, proteins, and lipid complexes, typically 50-500 microns thick, designed to modulate oxygen transmission rates below 1 cc/m²/day for perishable goods. Its primary commercial purpose is replacing multilayer petroleum films while maintaining controlled atmosphere performance. PLA dominates current volume through thermoplastic processability and existing composting infrastructure compatibility. Active Packaging represents the fastest-expanding functionality segment, integrating enzymatic or antimicrobial agents that respond to spoilage metabolites. Food Retail channels occupy the deepest margin pools due to private-label sustainability commitments and direct consumer visibility.
The EU Green Deal, F-Gas Regulation, and EFSA migration limits collectively mandate measurable biodegradability timelines and restrict synthetic additives in food-contact materials. FDA's food-contact notification pathway shapes US market access timelines for novel plant-based barrier chemistries. Stakeholders must monitor composting infrastructure deployment rates against material degradation certifications to avoid stranded asset risk in packaging formats.
Market Dynamics
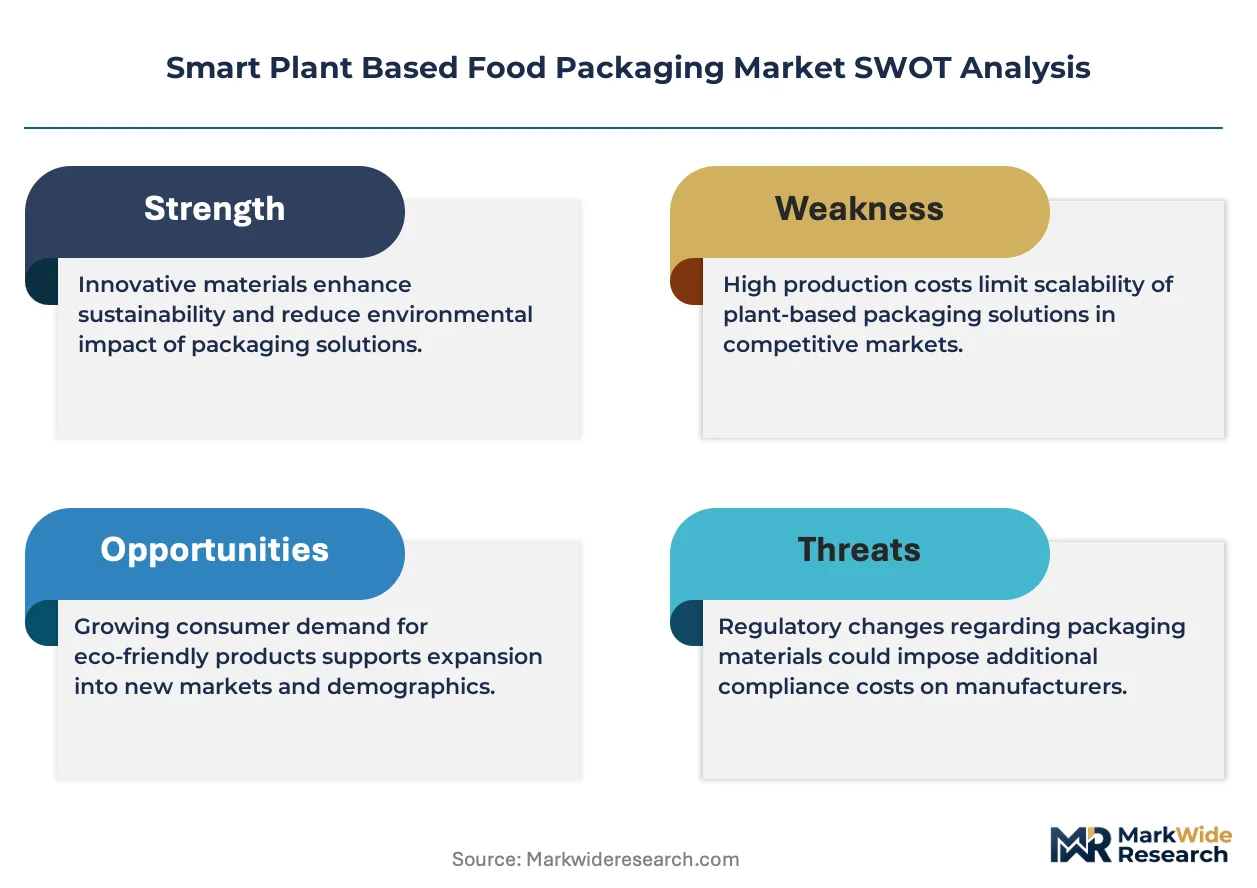
EU Green Deal enforcement is compressing petroleum-derived packaging margins while accelerating capital flows into cellulose and mycelium barrier platforms across Northern European manufacturing clusters.
Growth Catalysts
- EU F-Gas Regulation:Mandatory phase-down of fluorinated greenhouse gases in barrier films is redirecting R&D budgets toward polysaccharide-derived oxygen barriers in Germany and France.
- Fresh produce distributors:Shelf-life extension technologies are capturing procurement priority as spoilage reduction targets harden across European supermarket private-label programs.
- Cellulose nanocrystal platforms:Pilot-scale coating lines in the UK and Netherlands are demonstrating sub-1 cc/m²/day oxygen transmission rates for meat alternative applications.
Market Restraints
- Seaweed supply concentration:Coastal harvesting permits in Scotland and Norway limit raw material scaling for alginate-based coating producers.
- Industrial composting infrastructure gaps:Certification mismatch between EN 13432 timelines and actual anaerobic digestion capacity in Eastern Europe creates stranded asset exposure.
- PLA feedstock competition:Maize price volatility and biofuel mandate tensions in the US Midwest compress margin predictability for polylactic acid resin suppliers.
Strategic Opportunities
- Active Packaging convergence:Enzymatic spoilage sensors paired with pectin-based matrices open recurring revenue streams beyond one-time material sales.
- EFSA migration limit compliance:Stricter food-contact substance thresholds favor molecularly precise plant-protein films over conventional multilayer structures.
- Food Retail channel premium capture:Direct consumer visibility in supermarket sustainability labeling programs enables price realization above commodity packaging tiers.
Industry Challenges
- Composting certification timeline compression:TÜV Austria and DIN CERTCO review backlogs delay market entry for novel barrier chemistries by twelve to eighteen months.
- Barrier performance validation protocols:Standardized oxygen transmission testing at elevated humidity conditions remains inconsistently applied across national metrology institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Plant Based Food Packaging Market |
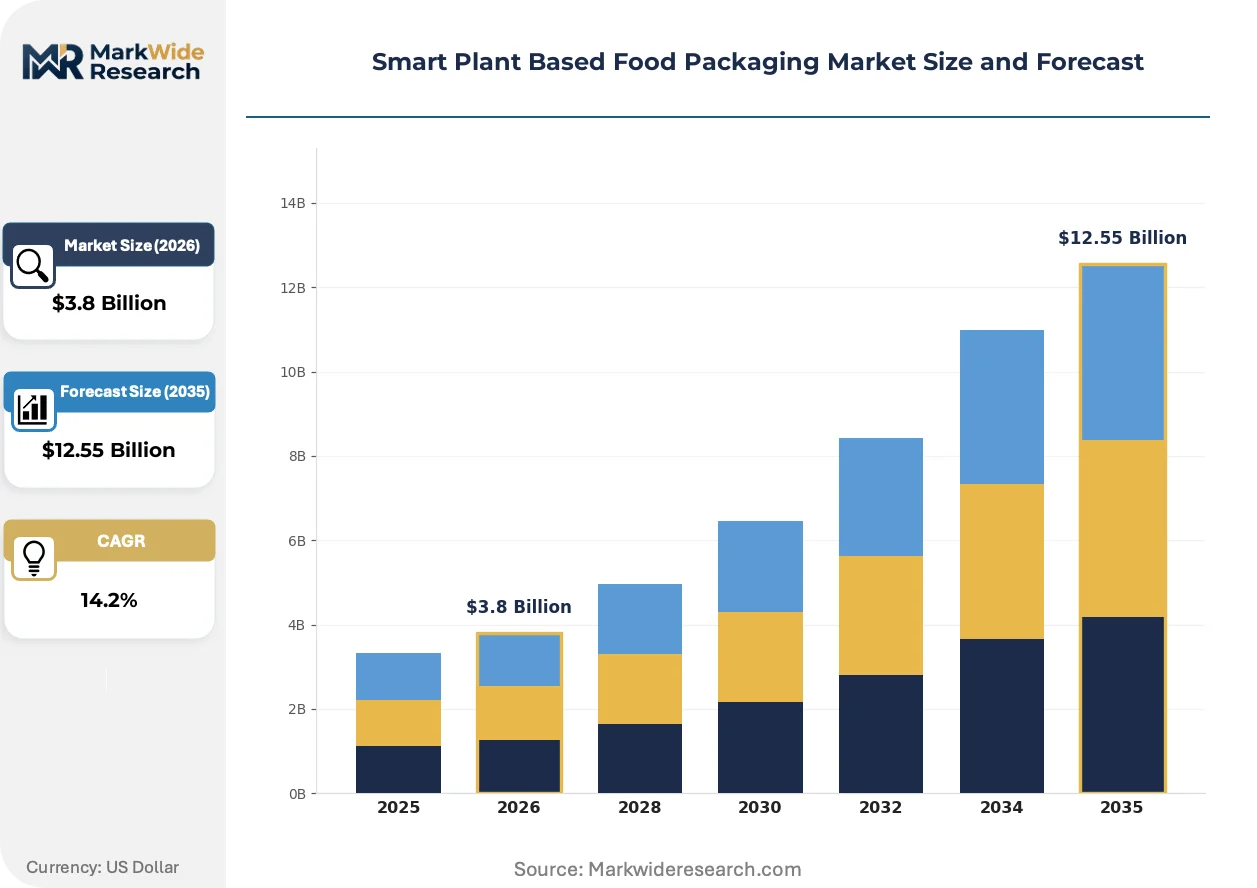
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, PHA, Starch-Based, Cellulose End User: Food Retail, E-Commerce, Food Service, Manufacturers Functionality: Barrier Protection, Biodegradability, Moisture Control, Active Packaging Distribution Channel: Online Retail, Supermarkets, Direct Sales, Specialty Stores |
| Companies Covered | Notpla, Apeel Sciences, Ecovative Design, Banana Leaf Technology, GreenPod Labs, Bloom Biorenewables, Xampla, Lactips, Genecis Bioindustries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Plant Based Food Packaging Market Strategic Shifts
Packaging value capture is migrating from material tonnage toward sensor-embedded freshness intelligence, rewiring how converters and brand owners monetize shelf-life extension.
Cellulose nanofibril barrier coatings are integrating enzymatic freshness indicators that respond to spoilage metabolites in real time. German supermarket chains are piloting these systems for plant-based meat alternatives. The technology is integrating predictive shelf-life data into inventory management systems, compressing working capital requirements for perishable categories.
REACH authorization requirements for persistent organic pollutants in food-contact materials are tightening migration testing protocols for petroleum-derived adhesives. Industrial laminate producers face reformulation costs exceeding seven figures per product line. Active packaging developers in Denmark and Sweden are accelerating plant-protein adhesive substitution to preempt authorization denial risks.
Retail procurement teams are consolidating supplier relationships around vertically integrated coating-to-converter platforms. Single-source accountability for barrier performance and composting certification is displacing multi-vendor laminate assemblies. French and Dutch food retailers are driving this consolidation through sustainability scorecard integration into vendor selection criteria.
Smart Plant Based Food Packaging Market Segmentation
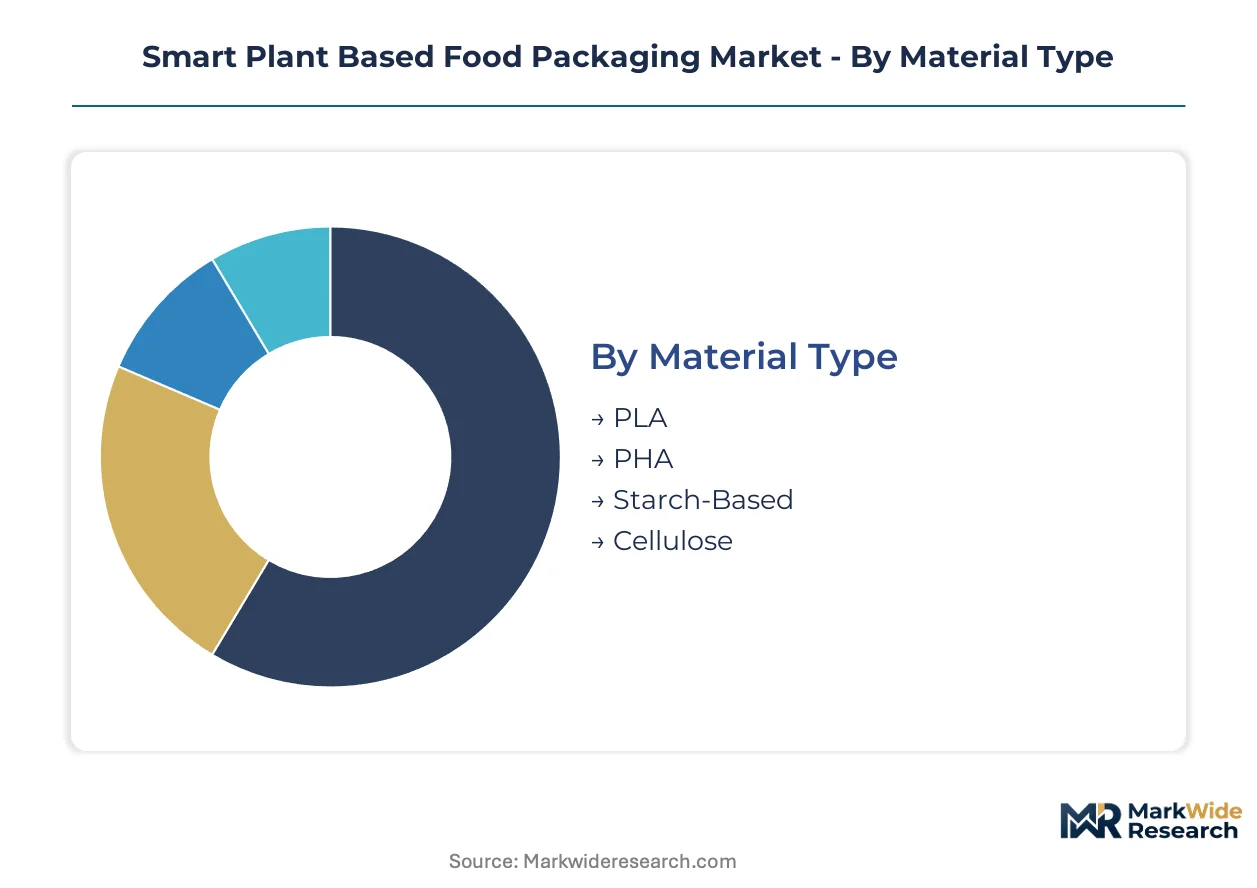
Material chemistry and functional integration determine commercial viability in smart plant-based packaging. Segmentation reveals where thermoplastic processability clashes with biodegradability timelines, and which end-use channels absorb premium pricing for active barrier systems.
Material Type:
Polylactic acid dominates volume through existing composting infrastructure and melt-process compatibility, though feedstock competition constrains margin stability.
- PLA:Corn-derived thermoplastic with crystallinity tunable for rigid trays or flexible films. Demand concentrates in German supermarket private-label programs where DIN CERTCO certification accelerates procurement approval. Maize price volatility and US biofuel mandate tensions compress resin cost predictability.
- Cellulose:Nanofibril and nanocrystal platforms achieve sub-1 cc/m²/day oxygen transmission through hydrogen-bonded dense networks. UK and Netherlands pilot lines are scaling for meat alternative barrier coatings. EFSA migration limit compliance favors molecular precision over multilayer petroleum adhesives.
- PHA:Microbial polyester with marine biodegradability certification. Coastal manufacturing clusters in Denmark evaluate PHA for fishing industry packaging where industrial composting infrastructure is absent.
- Starch-Based:Thermoplastic starch blends with limited moisture resistance. Applications concentrate in short-shelf-life produce where cost minimization outweighs barrier performance requirements.
Mature deployment sits with PLA. Newer deployment is concentrated in cellulose nanocrystal platforms.
End User:
Channel-specific sustainability commitments and spoilage cost structures reshape procurement priorities across the value chain.
- Food Retail:Supermarket private-label programs in France and the Netherlands integrate sustainability scorecards into vendor selection, enabling price realization above commodity tiers. Direct consumer visibility drives premium capture for cellulose-based barrier systems.
- Food Service:Quick-service and institutional catering operations prioritize cost minimization over biodegradability certification. Starch-based disposables dominate procurement where composting infrastructure gaps limit PLA adoption.
- E-Commerce:Last-mile freshness requirements and return logistics constraints favor lightweight, moisture-resistant formats. Active packaging integration with predictive shelf-life data compresses working capital for perishable categories.
- Manufacturers:Brand-owner sustainability targets and EPR compliance obligations drive specification of certified compostable materials. Procurement teams consolidate around vertically integrated coating-to-converter platforms.
Margin pools concentrate in Food Retail. Volume expansion is accelerating in E-Commerce.
Functionality:
Active and intelligent features are migrating value capture from material tonnage toward sensor-embedded freshness intelligence.
- Active Packaging:Enzymatic spoilage sensors paired with pectin-based matrices generate recurring revenue streams beyond one-time material sales. German pilot programs integrate predictive shelf-life data into inventory management for plant-based meat alternatives.
- Barrier Protection:Oxygen transmission modulation below 1 cc/m²/day remains the baseline specification for perishable goods. Cellulose nanofibril coatings are displacing multilayer petroleum films in high-humidity applications.
- Biodegradability:EN 13432 certification timelines clash with actual anaerobic digestion capacity in Eastern Europe, creating stranded asset exposure for material suppliers.
- Moisture Control:Lipid-composite and protein-based humidity buffers protect hydrophilic bio-derived matrices from performance degradation. Applications concentrate in fresh produce where respiration rates fluctuate.
Active Packaging represents the steepest expansion trajectory. Barrier Protection maintains the largest installed base.
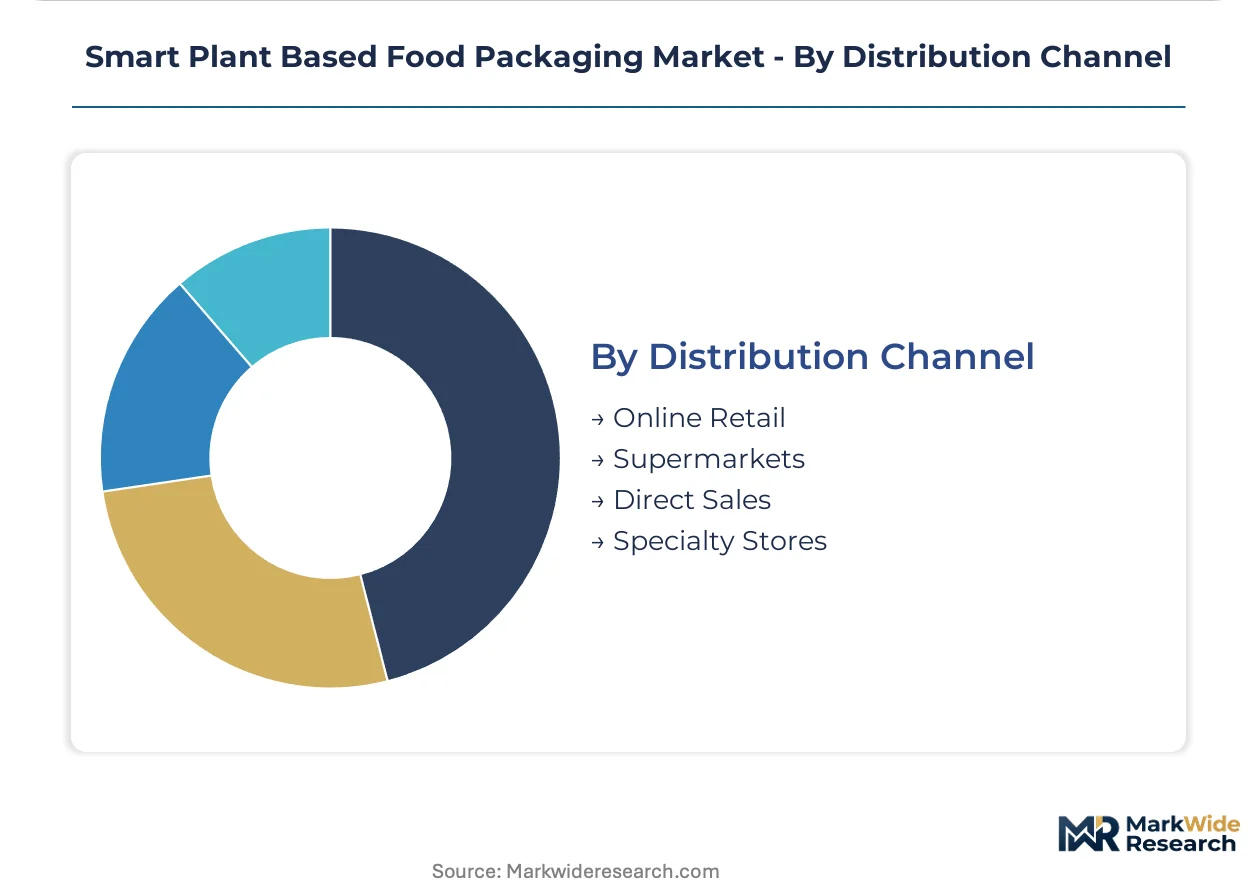
Distribution Channel:
Channel selection determines certification visibility requirements and working capital compression opportunities.
- Supermarkets:Sustainability labeling programs and consumer-facing composting instructions drive specification of certified materials. Procurement consolidation favors single-source accountability for barrier performance.
- Direct Sales:Converter-to-brand relationships enable co-development of application-specific barrier formulations. French food retailers are driving vertical integration through long-term coating platform partnerships.
- Online Retail:E-commerce pure-plays prioritize shipping durability over biodegradability certification. Secondary packaging requirements complicate primary material selection.
- Specialty Stores:Premium organic and zero-waste retail channels absorb highest price premiums for seaweed-derived and mycelium-composite formats.
Procurement scale concentrates in Supermarkets. Margin realization peaks in Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Northern European coating clusters while consumption pulls strongest through German and French retail procurement. Coastal seaweed harvesting in Scotland and Norway feeds alginate-based barrier development. Pilot-scale cellulose nanocrystal lines in the UK and Netherlands are validating sub-1 cc/m²/day oxygen transmission specifications.
Germany
Supermarket chains are piloting cellulose-based barrier coatings for plant-based meat alternatives. The EU F-Gas Regulation mandates fluorinated gas phase-down in barrier films, redirecting R&D budgets toward polysaccharide oxygen barriers. Manufacturing activity clusters around Hamburg and North Rhine-Westphalia coating-to-converter platforms.
United Kingdom
Notpla anchors coastal manufacturing clusters leveraging seaweed-derived coating supply chains. EFSA migration limit compliance pressures favor molecularly precise plant-protein films over petroleum adhesives. Pilot-scale nanofibril lines in the Netherlands corridor extend UK coating capacity into continental supply networks.
France
Food retailers drive supplier consolidation through sustainability scorecard integration into vendor selection criteria. REACH authorization requirements for persistent organic pollutants tighten migration testing protocols for conventional adhesives. Active packaging developers in the Paris basin accelerate plant-protein adhesive substitution to preempt regulatory denial risks.
Netherlands
Cellulose nanocrystal platforms demonstrate sub-1 cc/m²/day oxygen transmission rates for fresh produce applications. DIN CERTCO certification timelines for EN 13432 compliance accelerate procurement approval for compostable formats. Eindhoven-region coating lines scale toward meat alternative barrier production for German retail channels.
United States
PLA resin suppliers face maize price volatility and biofuel mandate tensions in the Midwest feedstock belt. FDA food-contact notification pathways shape market access timelines for novel plant-based barrier chemistries. California and Pacific Northwest retail sustainability commitments pull coated cellulose formats through e-commerce freshness requirements.
Smart Plant Based Food Packaging Market Competitive Environment
Top-tier vendors anchor integrated coating-to-converter platforms, while mid-scale specialists cluster around single-material process innovation. The vendor base stratifies across three strategic archetypes: coastal biomass harvesters with captive raw material access, precision-chemistry film formers, and enzymatic active packaging integrators. M&A activity concentrates on coating technology acquisition, while capacity expansion targets pilot-to-commercial scale-up in Northern European manufacturing clusters.
Among UK-based material innovators, Notpla exemplifies the coastal biomass archetype through seaweed-derived coating platforms. Ecovative Design occupies a position within mycelium-composite specialization, while Xampla represents molecular precision in plant-protein film formation. These three entities anchor distinct competitive vectors without overlapping material chemistries.
| Leading Market Players |
|---|
| Notpla |
| Apeel Sciences |
| Ecovative Design |
| Banana Leaf Technology |
| GreenPod Labs |
| Bloom Biorenewables |
| Xampla |
| Lactips |
| Genecis Bioindustries |
| Others |
Value Chain & Pricing Dynamics
Maize futures volatility in the US Midwest propagates through PLA resin cost structures, compressing margin predictability for converters and forcing tiered pricing stratification across certification-grade material tiers in European procurement channels.
Pricing Analysis
Cost-down pressure on standard-grade PLA accelerates because maize feedstock competition with biofuel mandates tightens resin supply elasticity. Three-tier pricing structure across premium cellulose-nanocrystal, standard PLA, and economy starch-based tiers reflects DIN CERTCO certification grade and oxygen transmission performance. Pricing pressure stems from supermarket private-label procurement consolidation demanding single-source accountability. Food Service channels exhibit highest price sensitivity due to cost-minimization procurement mandates, while Food Retail absorbs premium pricing for consumer-facing sustainability labeling.
Supply Chain Analysis
EU Green Deal domestic-content requirements for bio-derived materials reshape sourcing toward coastal seaweed harvesting clusters in Scotland and Norway, and cellulose nanofibril pilot lines in the UK and Netherlands. Raw material dependencies center on alginate harvest permits, corn starch feedstock, and mycelium substrate cultivation. Single-source vulnerability concentrates in Scottish coastal harvesting rights for Notpla and competing alginate coating producers. Distribution runs through vertically integrated coating-to-converter platforms serving German and French supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market hinges on backward integration into raw material supply, with coating-to-converter platform control emerging as the decisive margin defense mechanism.
For Market Incumbents: Extend barrier performance validation capabilities through captive cellulose nanocrystal coating lines in the Netherlands corridor to preempt certification backlog delays. Consolidate supplier relationships around single-source accountability for DIN CERTCO compliance and oxygen transmission specifications. Counter mycelium-composite substitution threats by accelerating pectin-based active packaging R&D intensity. For New Entrants and Emerging Players: Launch via direct sales partnerships with French food retailers seeking sustainability scorecard integration, bypassing incumbent converter relationships. Target E-Commerce freshness monitoring white space where predictive shelf-life data compresses working capital for perishable categories. Penetrate through enzymatic spoilage sensor co-development with German supermarket pilot programs. For Investors and Strategic Acquirers: The window for entry favors coastal biomass harvesters with captive seaweed or mycelium substrate access and molecular-precision film formers with EFSA migration limit compliance. Long-term viability rests on certification timeline acceleration and industrial composting infrastructure deployment rates. Watch TÜV Austria and DIN CERTCO review queue compression as inflection signal for market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Harvesting | Captive alginate supply secures coastal manufacturing clusters against Scottish permit scarcity. |
| Active Packaging Sensor Integration | Enzymatic freshness indicators generate recurring revenue beyond one-time material sales. |
| Cellulose Nanocrystal Capacity Scale-Up | Sub-1 cc/m²/day oxygen transmission validates meat alternative barrier coating specifications. |
| Coating-to-Converter Platform Consolidation | Single-source accountability displaces multi-vendor laminate assemblies in retail procurement. |
| DIN CERTCO Certification Fast-Track | Accelerated EN 13432 approval compresses twelve-to-eighteen month market entry delays. |
Study Parameters
Independent corroboration across packaging converter technical directors, supermarket private-label procurement managers, and composting facility operators underwrites the qualitative findings. Primary fieldwork encompassed coating platform engineers, EFSA regulatory affairs specialists, and industrial laminate producers facing REACH reformulation costs. Secondary validation drew from EU F-Gas Regulation implementation documents, EN 13432 certification databases, and customs data on PLA resin trade flows. Bottom-up demand modeling triangulated against top-down market sizing across material chemistry segments.
Rate-of-change decomposition across the analysis window disaggregated volume expansion into substitution-driven displacement of petroleum films and organic growth in active packaging functionality. Segmentation dimensions encompassed material type, end-user channel, functionality tier, and regional regulatory cluster. CAGRs derived from weighted average of historical adoption curves and infrastructure deployment timelines. Industry-specific forecast inputs included industrial composting capacity buildout rates and EFSA migration limit amendment trajectories.
Seaweed supply permit denials, maize price spike persistence, and composting certification timeline compression are the dominant revision risks. Forecasts embed assumptions on DIN CERTCO review velocity and anaerobic digestion capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Based Collagen Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
Vegan Bacon Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Oat Protein Market
Plant Based Food
Targeting Pod Market
Plant Based Food
United States Textured Vegetable Protein Market
Plant Based Food
Black Rice Protein Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
Packed Vegan Foods Market