
 Plant-Based Seafood Market | 2026-2036
Plant-Based Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Seafood Market Intelligence
Pea protein is expanding its role as the dominant base material in plant-based seafood formulations, displacing soy and wheat gluten in premium product lines due to superior allergen profiles and cleaner taste neutrality. Good Catch Foods leverages proprietary legume-protein blending technology to sustain texture fidelity in its tuna-style products. Sophie's Kitchen anchors its portfolio around konjac and pea-protein combinations that compete directly with traditional shellfish analogues.
Plant-based seafood comprises formulated food products engineered to replicate the sensory properties—texture, flavor, mouthfeel, and nutritional profile—of conventional fish and shellfish using non-animal proteins, binders, and lipid systems, typically achieving protein contents between 15-20 grams per serving through extrusion or shear-cell processing. The primary commercial purpose is to serve consumers seeking marine-protein alternatives without the environmental externalities of industrial fishing or aquaculture. Seafood analogues dominate current shelf space across North American retail channels, while shrimp formulations represent the fastest-growing product type as food service operators seek scalable substitutes for battered and tempura applications. Algae-derived omega-3 fortification is emerging as a critical margin pool, with ingredient-source differentiation increasingly separating premium positioning from commodity-grade offerings.
The FDA oversees labeling standards for plant-based seafood in the United States, while the USDA's Food Safety and Inspection Service coordinates with the FDA on hybrid jurisdiction products containing both plant and cell-cultured components. EFSA's novel food assessments in Europe create parallel compliance pathways that manufacturers must navigate for cross-border market access. Stakeholders must monitor how regulatory divergence between the FDA's draft guidance and emerging EU framework conditions shapes investment timing for production scale-up decisions.
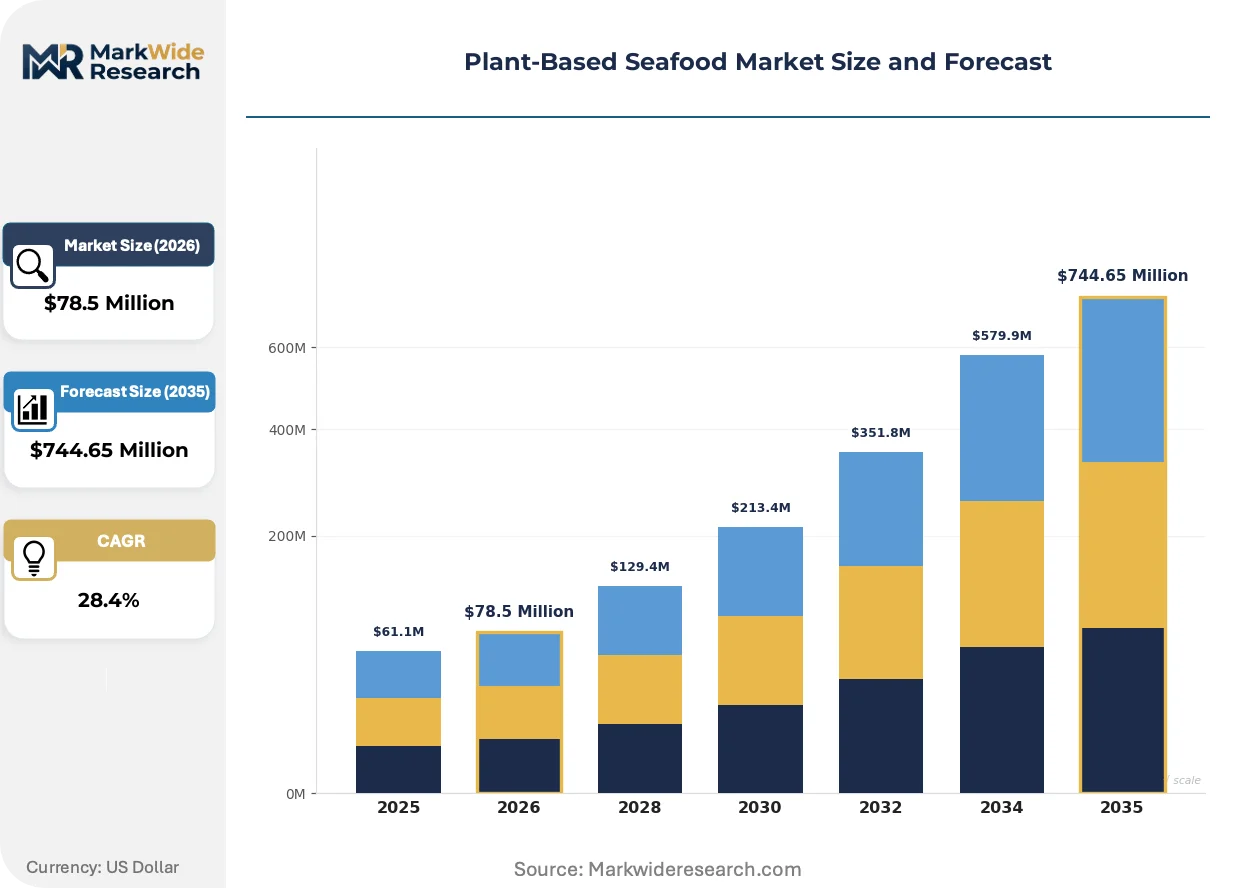
Market Dynamics
Shear-cell processing is compressing production timelines for plant-based seafood texture replication, enabling food service operators to swap conventional battered applications without reformulating kitchen workflows.
Growth Catalysts
- Algae-derived omega-3 fortification:Ingredient-source differentiation creates premium positioning pools as brands compete on nutritional parity with wild-caught fish.
- Coastal metropolitan corridor demand:United States food service operators along embedded seafood culture regions expand menu placements of plant-based alternatives.
- FDA labeling guidance evolution:Emerging compliance frameworks shape how brands communicate with buyers, reducing regulatory uncertainty for formulation investments.
Market Restraints
- Pea protein supply concentration:Premium product lines depend on limited North American and European processing capacity, exposing margins to crop volatility.
- Extrusion equipment capex intensity:Commercial-scale texture replication requires specialized machinery with long depreciation cycles, constraining mid-tier entrant expansion.
- Cell-cultured hybrid jurisdiction friction:USDA-FDA coordination on blended products creates labeling ambiguity that delays product launches.
Strategic Opportunities
- Tempura and battered shrimp applications:Food service operators seek scalable substitutes for high-volume fried seafood, opening white space for analogues optimized for hot-oil performance.
- EFSA novel food pathway alignment:Manufacturers navigating parallel EU compliance can capture cross-border market access with unified formulation investments.
- Direct-to-foodservice distribution:Bypassing retail shelf-space competition through institutional procurement contracts reduces slotting fee burdens.
Industry Challenges
- Extrusion technician skill scarcity:Shear-cell and high-moisture extrusion expertise concentrates among legacy meat-alternative engineers, forcing seafood-specialist recruitment from adjacent protein sectors.
- Dual certification timelines:Simultaneous FDA and EFSA approvals for algae-sourced omega-3 claims extend go-to-market schedules by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Seafood Market |
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $744.65 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fillets, Shrimp, Crab Cakes, Seafood Analogues Ingredient Source: Pea Protein, Algae, Soy, Wheat Gluten Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service End User: Restaurants, Households, Catering Services, Meal Kit Providers |
| Companies Covered | Good Catch Foods, Quorn, New Wave Foods, Cavi-art, Oshi, Garden Gourmet (Nestle), Ocean Hugger Foods, Sophie's Kitchen, Gardein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Seafood Market Strategic Shifts & Innovations
Formulation science is converging with regulatory clarity to reshape how plant-based seafood achieves sensory fidelity at commercial scale.
High-moisture extrusion is automating the replication of flaky fish muscle structure through precise temperature-pressure control, enabling contract manufacturers to produce tuna-style textures without batch-to-batch variation. Food service distributors across the United States are integrating these outputs into their protein portfolios at accelerating pace. The technology is automating quality consistency that previously required artisanal chef intervention, compressing the premium-to-commodity timeline for texture fidelity.
EFSA's novel food assessment framework is tightening scrutiny of algae-derived lipid claims in Europe, forcing reformulators to document bioavailability equivalence with marine sources. Manufacturers seeking premium positioning must now commission clinical validation studies before market entry. Shellfish analogue producers targeting EU distribution are responding by partnering with established novel food consultancies to accelerate dossier preparation.
Coastal urban food service procurement is consolidating around specification-driven tenders that require allergen-free certification and third-party sustainability verification. Large contract caterers in the United States are displacing open-market purchasing with pre-qualified supplier panels that audit ingredient provenance. This pattern concentrates demand among operators capable of documenting pea-protein supply chain integrity from field to finished good.
Plant-Based Seafood Market Segmentation
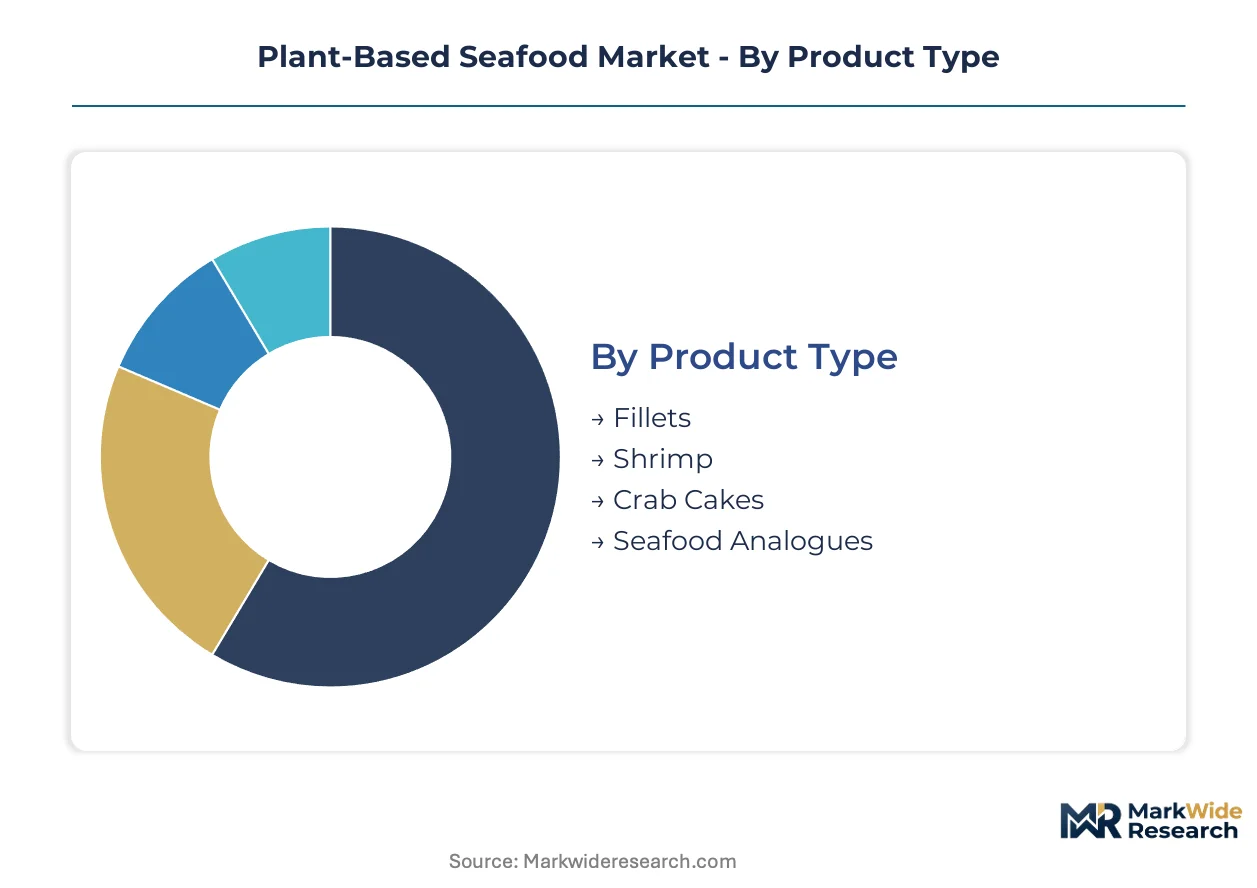
Plant-based seafood manufacturers configure production lines around discrete demand profiles, with formulation chemistry and channel economics diverging sharply across product formats. Segmentation discipline separates commodity-grade volume plays from premium positioning anchored to ingredient provenance and application-specific performance.
Product Type:
Upgrade cycles in food service kitchens drive replacement of conventional battered items with analogues that replicate fryer behavior and plate presentation without workflow disruption.
- Fillets:Extruded flake structures using high-moisture processing replicate cod and tilapia muscle architecture for center-plate retail and food service applications. Demand concentrates in United States coastal metropolitan school districts and healthcare cafeterias where procurement mandates prioritize sustainability verification without sacrificing portion cost controls.
- Shrimp:Konjac and pea-protein matrices achieve the snap and curl of conventional shrimp through precision molding and alginate setting, optimized for tempura and scampi preparations. United States Gulf Coast and Pacific Northwest food service distributors are expanding frozen shrimp analogue placements as fryer-compatible alternatives reduce kitchen cross-contamination protocols.
- Crab Cakes:Binder-heavy formulations using legume flours and vegetable gums replicate Maryland-style lump texture for regional specialty menus.
- Seafood Analogues:General-purpose shredded and chunked formats serve as ingredient inputs for chowders, fish tacos, and processed seafood products.
Volume placements concentrate in seafood analogues; the faster expansion belongs to shrimp.
Ingredient Source:
Cost tier stratification separates premium positioning from commodity competition based on protein digestibility scores and allergen labeling burden.
- Pea Protein:Isolated legume concentrates with PDCAAS scores approaching casein deliver neutral flavor canvases and clean-label appeal for premium fillet and shrimp applications. North American processing capacity constraints in Manitoba and North Dakota are forcing manufacturers into multi-year offtake contracts to secure supply for scaled food service rollouts.
- Algae:Whole-cell and extracted lipid systems provide DHA and EPA fortification that achieves nutritional parity claims with wild-caught fish oil. EFSA novel food dossier requirements and FDA GRAS notification timelines are extending algae-sourced omega-3 product launches by 18-24 months, compressing first-mover advantage windows.
- Soy:Established isolate infrastructure supports economy-tier analogues where allergen warnings are acceptable trade-offs for cost-sensitive institutional procurement.
- Wheat Gluten:Elastic protein networks excel in surimi-style textures but face declining use due to celiac labeling requirements and gluten-free menu mandates.
Cost leadership anchors to soy; margin capture and positioning premium flow to algae and pea protein systems.
Distribution Channel:
Application-specific packaging and temperature requirements segment logistics investment and margin recovery across channel types.
- Supermarkets:Refrigerated and frozen case placement requires slotting fee negotiations and velocity guarantees that favor established CPG portfolios with existing buyer relationships.
- Online Retail:Direct-to-consumer frozen fulfillment demands dry-ice logistics and subscription model economics that concentrate in coastal urban corridors with established cold-chain infrastructure.
- Specialty Stores:Natural and gourmet retail channels prioritize certified sustainable and non-GMO verified products with higher per-unit margins and lower volume throughput.
- Food Service:Institutional procurement through broadline distributors represents the dominant volume channel, with specification-driven tenders requiring HACCP documentation and allergen-free certification.
Revenue concentration sits with food service; steepest expansion trajectory belongs to online retail as subscription protein boxes penetrate suburban markets.
End User:
Customer type determines formulation priorities, with food service demanding fryer stability and households prioritizing convenience and clean labels.
- Restaurants:Full-service and fast-casual operators specify plant-based seafood for menu diversification and sustainability storytelling, with battered shrimp analogues showing fastest adoption in United States coastal quick-service chains.
- Households:Retail purchasers select frozen fillets and crab cakes for home preparation, with pea-protein and algae-fortified products commanding shelf space in premium natural grocers.
- Catering Services:Large-event and corporate dining procurement panels pre-qualify suppliers based on batch consistency and scalable portioning for buffet and plated service.
- Meal Kit Providers:Subscription box integrators demand 15-20 minute preparation formats with pre-portioned sauces and garnishes, favoring shelf-stable or quick-thaw seafood analogues.
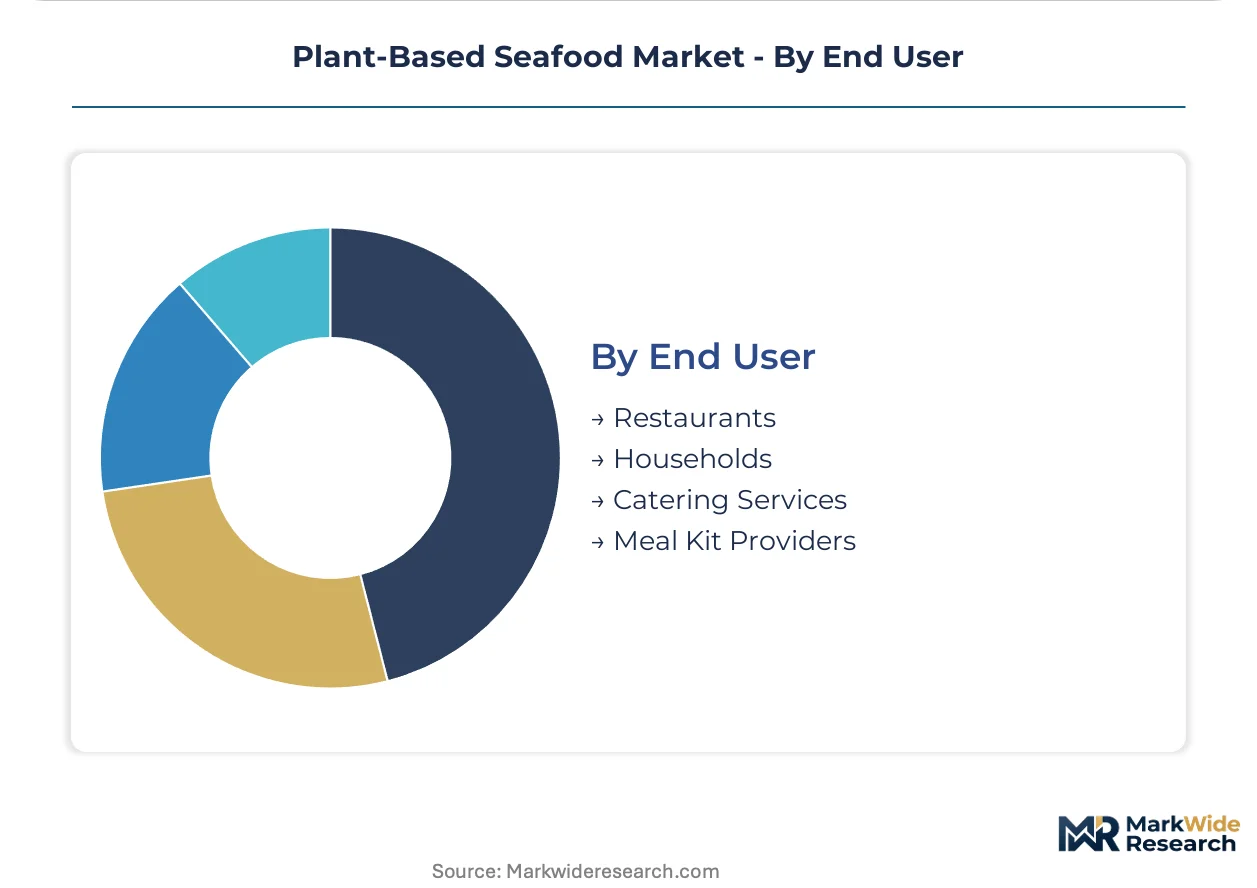
Procurement scale concentrates in restaurants; meal kit providers are gaining share fastest as subscription penetration deepens in United States metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States food service operators along coastal metropolitan corridors drive the dominant share of current demand, with procurement patterns clustering where seafood consumption culture is most embedded. Regulatory frameworks in multiple jurisdictions are simultaneously evolving, creating compliance complexity for manufacturers seeking cross-border scale.
United States
Coastal school districts and healthcare cafeterias in California, Massachusetts, and Washington State mandate sustainability verification in procurement tenders. The FDA's evolving guidance on cell-cultured and plant-based seafood labeling reduces regulatory uncertainty for formulation investments. Boston and Seattle metropolitan food service distributors are expanding frozen shrimp analogue placements as fryer-compatible alternatives.
Germany
Institutional catering contracts in Bavaria and North Rhine-Westphalia prioritize allergen-free certification and third-party sustainability verification. EFSA's novel food assessment framework tightens scrutiny of algae-derived lipid claims, forcing reformulators to document bioavailability equivalence. Berlin-based contract manufacturers are integrating high-moisture extrusion outputs into protein portfolios at accelerating pace.
United Kingdom
London and Southeast England quick-service chains specify plant-based seafood for menu diversification and sustainability storytelling. The Food Standards Agency coordinates with EFSA-aligned frameworks for novel food ingredient approvals. Midlands-based broadline distributors are consolidating procurement around specification-driven tenders requiring HACCP documentation.
Netherlands
Randstad region food service operators seek scalable substitutes for high-volume fried seafood applications. Dutch regulators align with EFSA novel food pathways while maintaining national enforcement discretion on algae-sourced omega-3 claims. Eindhoven Region extrusion equipment suppliers are compressing production timelines for texture replication technology.
Canada
Ontario and British Columbia meal kit providers demand 15-20 minute preparation formats with pre-portioned sauces. Health Canada coordinates labeling standards with FDA draft guidance to reduce cross-border friction. Vancouver and Toronto metropolitan subscription box integrators are penetrating suburban markets with quick-thaw seafood analogues.
Plant-Based Seafood Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers secure multi-year pea protein offtake contracts to support scaled food service rollouts. The vendor base clusters around three tiers: premium positioning anchored to algae-derived omega-3 fortification, mid-tier players optimizing for tempura and battered applications, and economy-grade soy-based volume producers. Strategic archetypes include formulation specialists leveraging proprietary legume-protein blending technology, contract manufacturers offering white-label extrusion services, and CPG incumbents extending existing plant-based portfolios into marine analogues. M&A activity and strategic partnerships concentrate on securing captive supply of high-PDCAAS protein isolates and shear-cell processing expertise.
Within the premium-tier vector, Good Catch Foods and Sophie's Kitchen exemplify formulation specialists competing on texture fidelity and ingredient-source differentiation. Among CPG-backed portfolios, Garden Gourmet represents incumbent extension strategies leveraging existing retail buyer relationships and slotting fee capacity. These three companies anchor the competitive structure while mid-tier entrants navigate extrusion equipment capex intensity and technician skill scarcity to challenge established positions.
| Leading Market Players |
|---|
| Good Catch Foods |
| Quorn |
| New Wave Foods |
| Cavi-art |
| Oshi |
| Garden Gourmet (Nestle) |
| Ocean Hugger Foods |
| Sophie's Kitchen |
| Gardein |
| Others |
Cost & Logistics Intelligence
Third-party sustainability verification from the Marine Stewardship Council and analogous certifiers gates qualified supply access and premium-tier pricing power, forcing manufacturers to absorb audit costs or forfeit food service contract eligibility in coastal United States procurement panels.
Pricing Analysis
The volume-versus-margin split separates commodity-grade soy-based analogues from algae-fortified premium lines, with price differentiation flowing from certification grade and protein digestibility scores. Three-tier pricing structure across premium, standard, and economy levels reflects ingredient-source stratification, with pea-protein formulations commanding shelf space in natural grocers. Pricing pressure stems from crop volatility in North American legume processing regions, compressing mid-tier margins. Institutional procurement in United States school districts exhibits highest price sensitivity, while specialty retail channels absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-compromised frozen seafood analogues remains underdeveloped, forcing distributors to absorb spoilage costs rather than recapture value through refurbishment flows. Manufacturing concentration centers on Manitoba and North Dakota for pea-protein isolation, with Dutch extrusion equipment suppliers and Chinese alginate providers completing the input matrix. Supply chain risk hinges on single-source vulnerability in high-moisture extrusion machinery, where technician scarcity constrains rapid supplier switching. Distribution runs through broadline food service distributors with cold-chain mandates, bypassing retail slotting fee structures for volume capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with upstream control over pea-protein processing capacity and downstream direct-to-food service contracts representing the decisive levers separating scalable players from margin-squeezed assemblers.
For Market Incumbents: To counter extrusion technician scarcity and equipment lead time extension, secure multi-year offtake contracts with Manitoba and North Dakota protein processors while acquiring captive shear-cell processing expertise through targeted hiring from adjacent meat-alternative engineering pools. Prioritize HACCP documentation and allergen-free certification investments to defend institutional procurement panel positioning against mid-tier challengers. For New Entrants and Emerging Players: Shear-cell processing automation for tempura-optimized shrimp analogues offers the most penetrable white space, as United States Gulf Coast and Pacific Northwest food service distributors actively seek fryer-compatible alternatives with reduced cross-contamination protocols. Target coastal quick-service chains with specification-driven tenders requiring battered item replacement without kitchen workflow disruption, leveraging contract manufacturing partnerships to bypass capital-intensive extrusion equipment ownership. For Investors and Strategic Acquirers: EFSA novel food dossier approvals for algae-derived omega-3 claims is the leading indicator that premium-tier margin pools are stabilizing for cross-border scale. Over the medium-term horizon, acquisition targets should profile as formulation specialists with proprietary legume-protein blending technology and established direct-to-food service distribution relationships, with regulatory clearance velocity serving as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Pea Protein Supply Contracting | Multi-year offtake agreements with Manitoba processors lock in input cost predictability for scaled rollouts. |
| Shear-Cell Processing Scale-Up | High-moisture extrusion automation compresses texture replication timelines for food service compatibility. |
| EFSA Novel Food Dossier Filing | European regulatory alignment enables unified formulation investments for cross-border market access. |
| Direct-to-Foodservice Distribution | Bypassing retail slotting fees through institutional procurement contracts improves margin recovery. |
| Algae-Derived Omega-3 Fortification | Nutritional parity claims with wild-caught fish oil separate premium positioning from commodity competition. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with food service procurement directors, extrusion equipment engineers, plant-based formulation scientists, and broadline distributor category managers. FDA draft guidance documents, EFSA novel food assessment frameworks, and Health Canada labeling coordination memos provided regulatory boundary conditions. Bottom-up volume modeling from pea-protein processing capacity and top-down demand triangulation from food service menu placement data were cross-validated for consistency.
Granularity-level modeling disaggregated volume and value across product type, ingredient source, distribution channel, and end user, with additional dimensioning by regional regulatory cluster and sustainability certification tier. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion across the analysis window. Forecast inputs incorporated shear-cell processing adoption curves, algae-sourced omega-3 bioavailability validation timelines, and coastal metropolitan corridor food service penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA-USDA jurisdiction friction on hybrid cell-cultured products and EFSA novel food assessment delays. Practitioners should monitor EFSA dossier approval velocity, pea-protein crop yield reports from North American growing regions, and food service distributor frozen analogue inventory turns for early signals of demand inflection or supply constraint.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
China Plant Protein Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
Lentil Protein Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
Plant-Based Wafer Biscuits Market
Plant Based Food
Vegan Flour Market
Plant Based Food
China Pea Protein Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
Indoor Leafy Green Precision Nutrition Program Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Asia-Pacific Plant-Based Seafood Market