
 Plant-Based Food Ingredients Market | 2026-2036
Plant-Based Food Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Food Ingredients Market Outlook
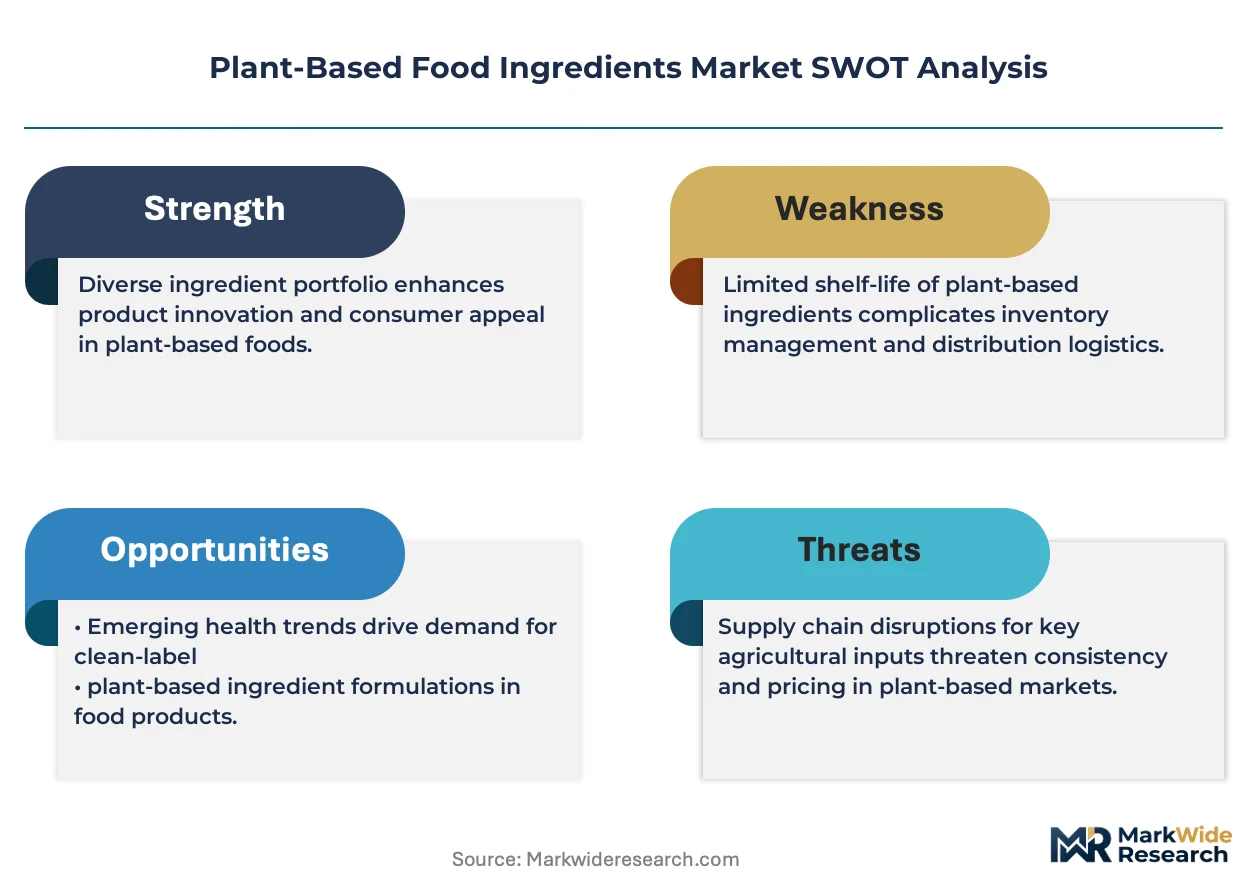
Clean-label certification tiers is redrawing competitive boundaries in plant-based ingredients. ADM leverages its vertical grain processing infrastructure to secure supply security across North American pea protein extraction. PURIS anchors domestic sourcing through regenerative agriculture partnerships with Midwestern growers. Nestlé differentiates via proprietary extrusion technologies that replicate meat fibrous textures at commercial scale.
Plant-based food ingredients comprise refined or minimally processed derivatives from legumes, cereals, tubers, and oilseeds, typically standardized to protein contents between 50% and 90% dry weight and functionalized through enzymatic or mechanical modification for water-binding, emulsification, or gelation in finished foods. Their primary commercial purpose is to replicate the sensory, nutritional, and functional performance of animal-derived components in formulated consumer products. Protein isolates and concentrates from pea and soy sources command the deepest margin pools due to extraction complexity and amino acid completeness, while starch fractions from potato and wheat function as lower-margin volume fillers in meat analog batters. Application demand in meat alternatives outpaces dairy alternatives on a unit-growth basis, though beverage formulations show the fastest acceleration as oat and pea milks displace traditional liquid dairy in café and retail channels.
The FDA governs ingredient safety through GRAS self-affirmation and food additive petitions, while USDA-FSIS regulates plant-based meat labeling disputes that directly affect market access and shelf placement. EFSA's novel food authorizations in Europe and China's SAMR food safety standards create divergent compliance pathways that multinational suppliers must navigate simultaneously. Stakeholders should monitor how evolving protein content thresholds and allergen disclosure mandates in major jurisdictions reshape formulation priorities and certification investments.
Market Dynamics
Clean-label certification tiers are redrawing competitive boundaries as foodservice operators and retail buyers demand verified provenance claims, forcing ingredient suppliers to invest in traceability infrastructure and third-party audit systems to maintain shelf access.
Growth Catalysts
- GRAS Self-Affirmation Pathway:The FDA's streamlined safety review process accelerates novel protein ingredient commercialization, reducing time-to-market for fermented and precision fermentation-derived inputs.
- Quick-Service Restaurant Expansion:Major chains are embedding plant-based proteins into core menu architectures, creating guaranteed offtake volumes that de-risk supplier capacity investments.
- Midwest Grower Clustering:Regenerative agriculture partnerships concentrate pea and soybean processing capacity near cultivation zones, compressing logistics costs and carbon intensity metrics.
Market Restraints
- Protein Isolate Cost Volatility:Energy-intensive wet-fractionation processes for 80-90% protein concentrates expose margins to natural gas price swings in North American processing hubs.
- Single-Source Geography Risk:Yellow pea protein extraction concentrates in Canadian Prairie provinces and US Upper Midwest, creating weather-dependent supply vulnerability.
- Amino Acid Profile Limitations:Most plant proteins require lysine or methionine fortification to match animal protein nutritional completeness, adding formulation complexity and cost.
Strategic Opportunities
- Fermentation-Enabled Novel Proteins:Mycelium and biomass fermentation technologies converge with precision fermentation for dairy-identical proteins, opening texture-replication capabilities beyond conventional extrusion.
- Beverage Channel Acceleration:Café and foodservice oat and pea milk demand outpaces retail velocity, creating dedicated ingredient supply contracts with shorter qualification cycles.
- EU Green Deal Protein Transition:Farm-to-Fork strategy incentives for domestic plant protein cultivation reduce import dependency and create localized processing demand.
Industry Challenges
- Extrusion Technician Scarcity:High-moisture extrusion operation requires specialized food engineering expertise that outstrips current vocational training pipeline output.
- Dual Jurisdiction Compliance Burden:Simultaneous FDA GRAS and EFSA novel food authorization timelines create parallel capital commitments without guaranteed reciprocity.
- Legacy Dairy Equipment Retrofit Costs:Converting fluid milk processing lines for oat or pea milk production demands stainless steel sanitation system overhauls and allergen segregation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Food Ingredients Market |
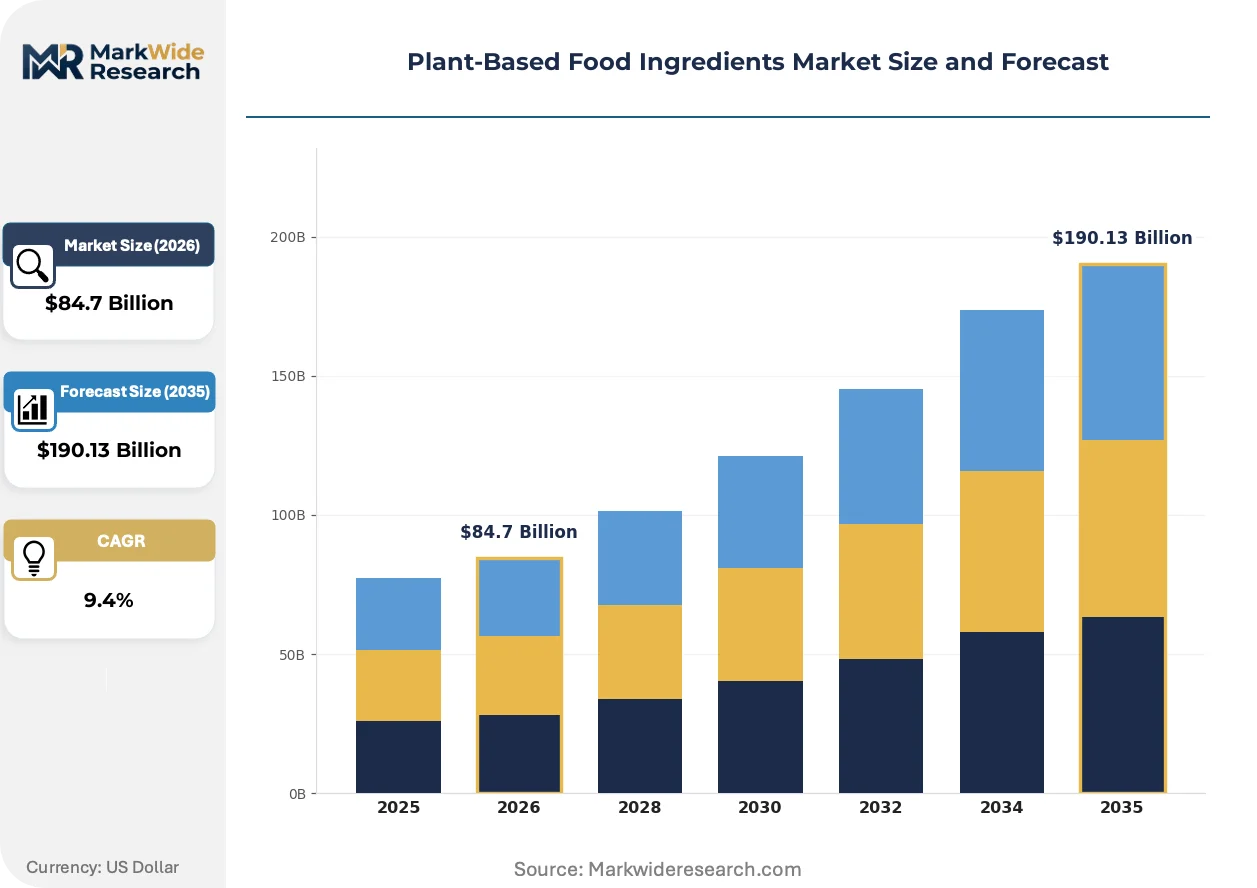
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $190.13 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteins, Starches, Sweeteners, Flavors Source: Pea, Soy, Wheat, Potato Form: Powder, Liquid, Granules, Paste Application: Meat Alternatives, Dairy Alternatives, Snacks, Beverages |
| Companies Covered | Kraft Heinz, Conagra Brands, ADM, Nestlé, Pulmuone Holdings, Maple Leaf Foods, The Hain Celestial Group, PURIS, Monde Nissin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Food Ingredients Market Strategic Shifts
Extrusion and fermentation technologies are fragmenting the texture-replication landscape as suppliers compete to replicate meat fibrous structures without historical reliance on soy protein isolates alone.
High-moisture extrusion is fragmenting the meat analog texturization market by enabling continuous protein fiber alignment that mimics muscle tissue architecture. Mid-scale specialty processors in Germany and the Netherlands are adopting twin-screw systems at accelerated replacement cycles. This capability compression is eroding the historical advantage of capital-intensive batch processing equipment.
EFSA's tightened novel food authorization requirements for cell-cultured and precision fermentation ingredients are extending commercialization timelines by 18-24 months for European market entry. The industrial consequence is a geographic bifurcation where suppliers prioritize US GRAS pathways first. Dairy alternative applications face the steepest compliance burden due to allergen cross-reactivity assessment mandates.
Direct-procurement contracting between ingredient suppliers and quick-service restaurant chains is displacing traditional distributor-mediated purchasing in North American foodservice. Chains are consolidating supplier rosters to three to five certified partners per protein category. This concentration is most visible in the United States, where venture-backed ingredient startups are establishing captive supply relationships with national restaurant groups.
Plant-Based Food Ingredients Market Segmentation
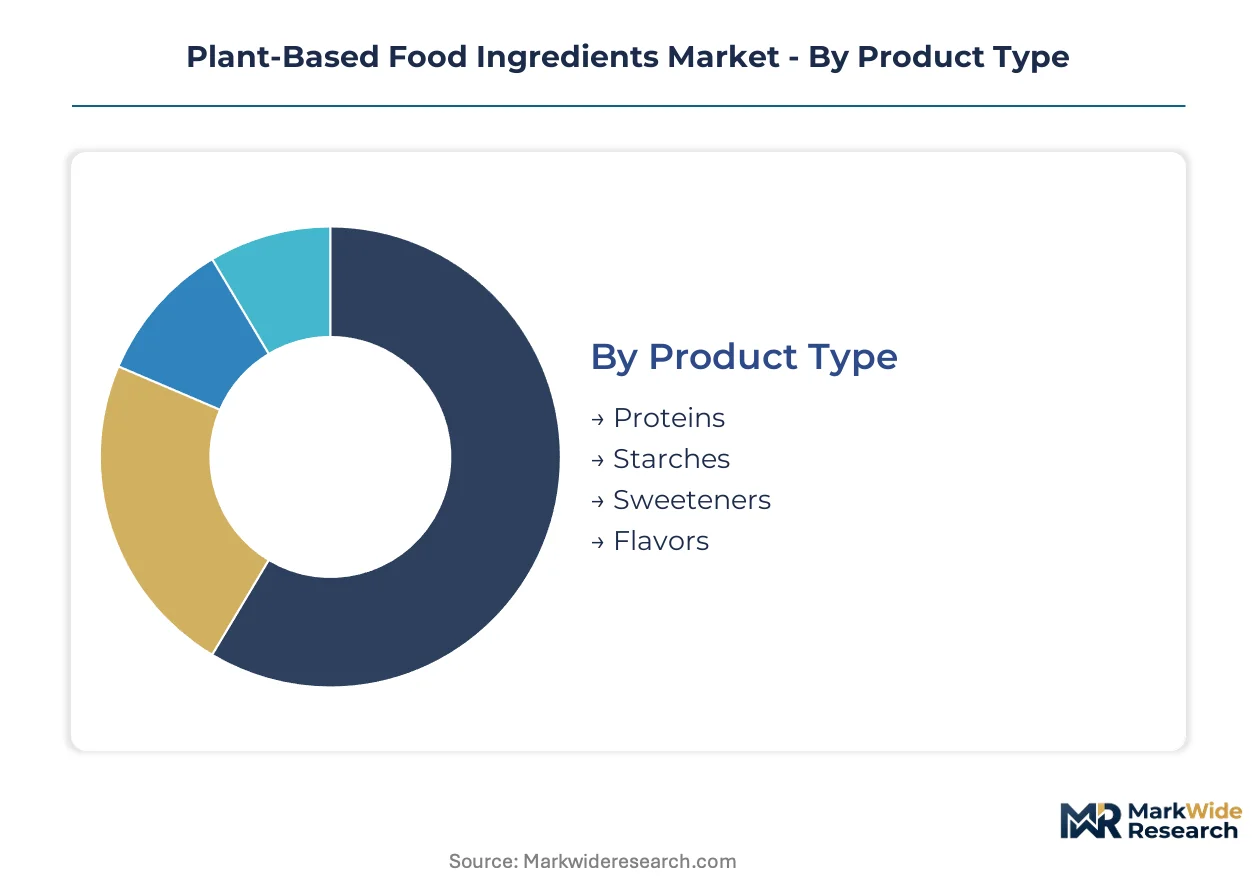
Plant-based food ingredients segment along four functional dimensions that determine formulation priorities, procurement costs, and regulatory pathways. Substitution dynamics vary sharply across these boundaries, with protein isolates facing precision fermentation disruption while starches compete mainly on price and functionality.
Product Type:
Protein isolates confront the steepest substitution pressure from emerging biomass fermentation technologies, while flavor systems defend position through proprietary extraction IP and clean-label certification tiers.
- Proteins:Isolates and concentrates standardized to 50-90% dry weight protein content, functionalized for water-binding, emulsification, or gelation. Wet-fractionation processing concentrates in North American prairie processing hubs where natural gas costs determine margin viability. Demand clusters in meat alternative extrusion applications requiring fibrous texture replication.
- Starches:Fractions from potato and wheat function as lower-margin volume fillers in meat analog batters, with amylose-amylopectin ratios tailored to gel strength requirements. European beverage formulators drive modified starch demand for oat milk mouthfeel stabilization.
- Sweeteners:Rice syrups and concentrated fruit extracts replace sucrose in clean-label positioned products, with glycemic index claims driving premium tier pricing differentiation.
- Flavors:Masking systems and savory precursors address beany off-notes in legume proteins, with yeast extract and natural flavor complexes commanding formulation lock-in through sensory performance guarantees.
Starches anchor the volume base while proteins gain share at the steepest rate.
Source:
Cost tier positioning separates commodity legumes from premium-positioned specialty crops, with regenerative agriculture certification creating price stratification within each botanical category.
- Pea:Yellow pea protein extraction dominates North American capacity expansion, with wet-fractionation yields of 80-90% isolates commanding the deepest margin pools. California and Midwest venture-backed startups cluster near Prairie province supply corridors.
- Soy:Historical texturization standard faces allergen labeling burdens and GMO disclosure requirements in major jurisdictions. Brazilian and Argentinian crush capacity supplies global isolate demand with amino acid completeness advantages.
- Wheat:Gluten fractions and starch streams from European milling operations serve meat analog binder applications, with FODMAP sensitivity concerns limiting beverage penetration.
- Potato:Starch and protein co-products from Dutch and German processing operations supply EU Green Deal compliant regional sourcing mandates for foodservice operators.
Soy maintains the broadest installed processing base while pea climbs fastest on foodservice menu penetration.
Form:
Application requirements dictate form selection, with powder formats defending scale economies while liquid concentrates capture beverage channel velocity advantages.
- Powder:Spray-dried isolates and concentrates enable extended shelf stability and freight efficiency, dominating ingredient supplier-to-manufacturer bulk shipments. Midwest distribution hubs serve North American meat alternative extrusion facilities.
- Liquid:Protein slurries and hydrolysates reduce hydration time in high-throughput beverage processing, with café and foodservice oat milk operations demanding tanker-delivered concentrates.
- Granules:Agglomerated formats improve dispersibility in dry-mix applications, with instant beverage and sports nutrition powder manufacturers specifying particle size distributions.
- Paste:High-moisture protein concentrates and texturized vegetable protein bases ship refrigerated to ready-meal manufacturers, with shorter qualification cycles than powder equivalents.
Powder commands the volume base while liquid formats expand most quickly on beverage channel acceleration.
Application:
Customer type concentration separates foodservice procurement with consolidated supplier rosters from fragmented retail brand formulation requirements.
- Meat Alternatives:High-moisture extrusion and shear-cell processing demand 80%+ protein isolates with precise water absorption indices. Quick-service restaurant chains consolidate supplier rosters to three to five certified partners per protein category, creating captive supply relationships with venture-backed ingredient startups.
- Dairy Alternatives:Oat and pea milk formulations show the fastest acceleration as café and retail channels displace traditional liquid dairy. Legacy dairy equipment retrofit costs for stainless steel sanitation and allergen segregation constrain supplier switching.
- Snacks:Puffed and extruded products utilize lower-protein concentrates and starch fractions, with texture replication requirements less stringent than center-plate protein applications.
- Beverages:Ready-to-drink protein fortification and plant milk bases require solubility and suspension stability, with barista-specific foam performance specifications driving ingredient qualification protocols.
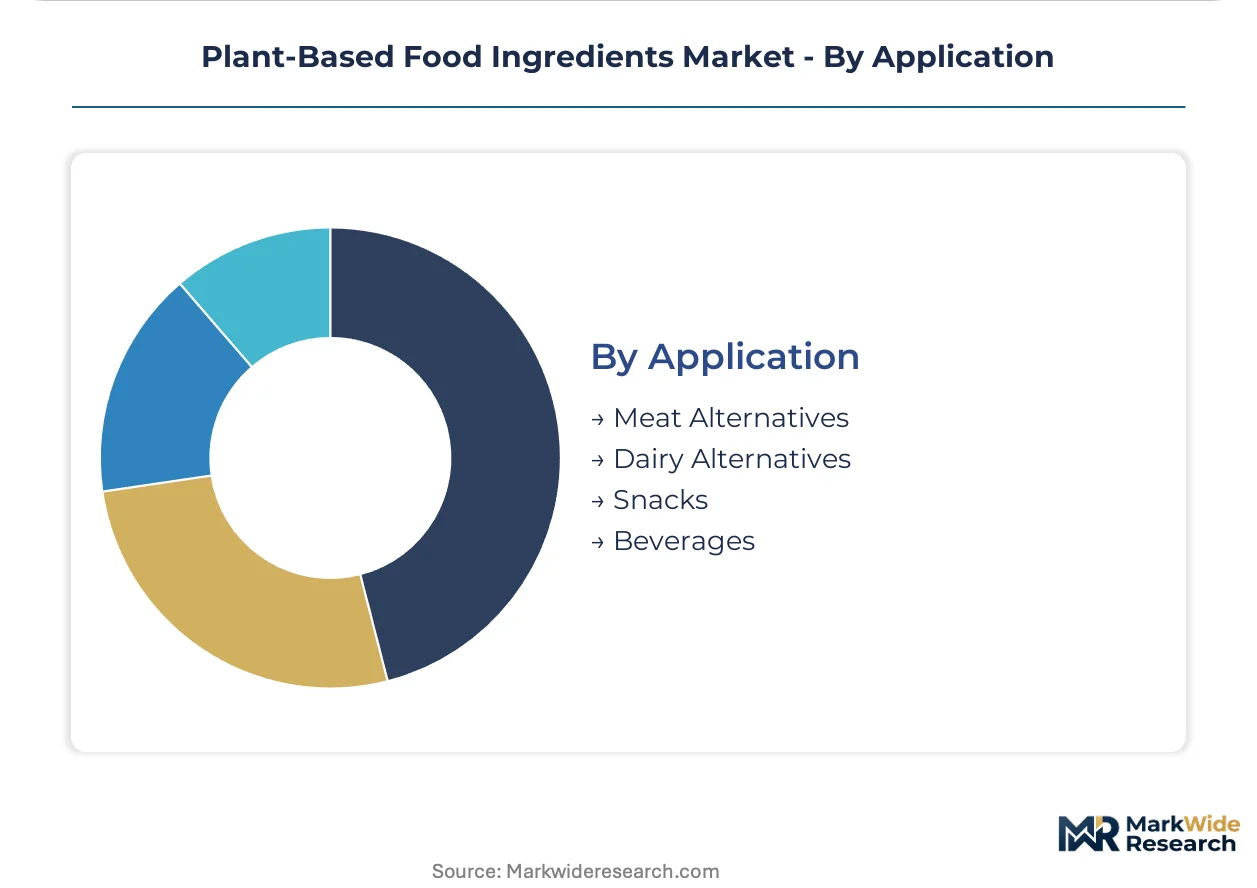
Meat alternatives anchor the volume base while dairy alternatives gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yellow pea protein extraction clusters in the Canadian Prairie provinces and US Upper Midwest, where wet-fractionation facilities sit adjacent to cultivation zones. This geographic concentration compresses logistics costs but exposes supply chains to weather-dependent yield volatility across North American breadbasket regions.
United States
California venture-backed ingredient startups cluster near Prairie province supply corridors to secure yellow pea protein offtake. The FDA's GRAS self-affirmation pathway accelerates novel protein commercialization timelines versus European authorization routes. Midwest regenerative agriculture partnerships concentrate processing capacity near cultivation zones in Minnesota and North Dakota.
Germany
Mid-scale specialty processors adopt twin-screw high-moisture extrusion systems at accelerated replacement cycles. EFSA's tightened novel food authorization requirements extend commercialization timelines for precision fermentation ingredients entering European markets. The Netherlands-German border region hosts potato starch and protein co-product operations serving EU Green Deal compliant regional sourcing mandates.
China
SAMR food safety standards create divergent compliance pathways that multinational suppliers must navigate alongside Western authorization systems. Domestic oat milk formulation demand accelerates as café chains displace traditional liquid dairy in tier-one cities. Yangtze River Delta processing hubs concentrate modified starch production for beverage mouthfeel stabilization.
Brazil
Soy crush capacity supplies global isolate demand with amino acid completeness advantages for meat analog applications. ANVISA labeling requirements for GMO disclosure shape export formulation priorities for North American and European destinations. São Paulo-state foodservice distributors mediate plant-based protein procurement for quick-service restaurant chain expansion across Latin America.
India
FSSAI food safety standards govern ingredient import and domestic manufacturing compliance for multinational suppliers entering the market. Punjab and Haryana cultivation zones supply chickpea and mung bean protein fractions for regional snack and beverage applications. Mumbai and Delhi-NCR foodservice operators pilot plant-based menu embedding with dedicated supplier qualification protocols.
Plant-Based Food Ingredients Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with proprietary extrusion capabilities separating premium-positioned suppliers from commodity processors. The vendor base spans grain traders with backward integration into protein extraction, specialty ingredient pure-plays, and diversified food conglomerates with captive R&D pipelines. Three archetypes dominate: vertical grain processors securing supply security, regenerative agriculture partners anchoring domestic sourcing, and precision fermentation entrants pursuing dairy-identical proteins. Competitive moves concentrate on capacity expansion near cultivation clusters and strategic partnerships with quick-service restaurant chains for guaranteed offtake volumes.
Among diversified food conglomerates, Nestlé and Kraft Heinz occupy positions that exemplify scale-driven portfolio diversification across protein categories. ADM represents the vertical grain processor archetype with North American prairie infrastructure. PURIS anchors the regenerative agriculture partnership model through Midwestern grower relationships. These three companies illustrate how supplier archetypes map to distinct competitive advantages in extraction scale, sourcing certification, and foodservice channel access.
| Leading Market Players |
|---|
| Kraft Heinz |
| Conagra Brands |
| ADM |
| Nestlé |
| Pulmuone Holdings |
| Maple Leaf Foods |
| The Hain Celestial Group |
| PURIS |
| Monde Nissin Corporation |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for yellow pea protein isolates compress margin buffers for North American processors while amplifying pricing power for Prairie province wet-fractionation facilities with captive supply corridors. This lead-time band concentrates procurement leverage among three to five certified suppliers per protein category, forcing foodservice chains into long-term offtake commitments that lock in volume discounts against spot-market volatility.
Pricing Analysis
FDA GRAS self-affirmation tiers dictate the pricing tier structure across novel protein ingredients, with fermented and precision fermentation-derived inputs commanding premium-mid-economy pricing differentiation based on authorization pathway completion. Clean-label certification grades and regenerative agriculture sourcing claims separate contract pricing for quick-service restaurant chains from spot transactions for retail brands. Cost compression in commodity pea protein concentrates is intensifying because energy-intensive wet-fractionation exposes margins to natural gas price swings in Midwest processing hubs. Retail brand formulators exhibit the highest price sensitivity due to fragmented procurement volumes, while national restaurant groups leverage consolidated supplier rosters for volume-scale discounts.
Supply Chain Analysis
Just-in-time inventory strategies dominate beverage channel procurement for oat and pea milk concentrates, while meat alternative extrusion facilities maintain strategic stockpiles of 80%+ protein isolates to buffer against weather-dependent yield volatility. Supply concentrates in Canadian Prairie provinces, the US Upper Midwest, and Brazilian soy crush corridors, with wet-fractionation capacity anchored in cultivation zones to compress logistics costs. Raw material dependencies center on yellow pea, soy, and potato feedstocks, with enzymatic processing inputs and natural gas feedstock for drying operations. Single-source geography risk creates weather-dependent supply vulnerability across North American breadbasket regions. Distribution runs through direct-procurement contracting between ingredient suppliers and quick-service restaurant chains, displacing traditional distributor-mediated purchasing in foodservice.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in this market center on extrusion technician training programs and sensory performance guarantees, with after-sales technical support contracts expanding faster than commodity protein isolate sales as high-moisture extrusion operation demands specialized food engineering expertise that outstrips vocational training pipeline output.
For Market Incumbents: Compound defensive positioning by securing captive supply relationships with national restaurant groups through three to five certified partner rosters per protein category, while investing in proprietary extrusion technologies that replicate meat fibrous textures at commercial scale. Threat from precision fermentation-derived dairy-identical proteins demands accelerated R&D in mycelium and biomass fermentation capabilities beyond conventional extrusion. Backward integration into regenerative agriculture partnerships with Midwestern growers anchors domestic sourcing certification against supply volatility. For New Entrants and Emerging Players: Anchor in beverage channel acceleration for oat and pea milk formulations, where café and foodservice demand outpaces retail velocity and creates dedicated ingredient supply contracts with shorter qualification cycles than meat alternative applications. White-space targets include barista-specific foam performance specifications and tanker-delivered liquid concentrate logistics. A go-to-market angle through direct-procurement contracting with regional restaurant chains bypasses consolidated distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with captive R&D pipelines but non-core plant-based ingredient divisions, particularly those lacking foodservice channel access or extrusion technology leadership. Long-term viability hinges on fermentation-enabled novel protein capabilities converging with precision fermentation for dairy-identical proteins. The signal to watch is EFSA novel food authorization timeline extensions for European market entry, which would validate US-first GRAS pathway prioritization strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Partnership | PURIS anchors domestic sourcing through Midwestern grower relationships securing supply security. |
| High-Moisture Extrusion Scale-Up | Nestlé differentiates via proprietary extrusion technologies replicating meat fibrous textures commercially. |
| Precision Fermentation Investment | Mycelium and biomass fermentation opens texture-replication beyond conventional extrusion capabilities. |
| Direct-Procurement Contracting | ADM leverages vertical grain processing infrastructure for captive supply with national restaurant groups. |
| Clean-Label Certification Tier | Third-party audit systems maintain shelf access as retail buyers demand verified provenance claims. |
Study Parameters
Initial hypotheses were tested against primary input from extrusion facility operators, quick-service restaurant procurement directors, ingredient supplier R&D heads, and regenerative agriculture program managers, and refined through secondary validation against FDA GRAS filings, USDA-FSIS labeling dispute records, EFSA novel food authorization databases, and trade customs data for pea and soy protein isolate flows. Bottom-up capacity modeling across North American wet-fractionation facilities triangulated against top-down demand segmentation from foodservice menu penetration data.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation modeling spanning protein content tiers, application categories, form factors, and regional regulatory clusters. CAGRs were derived from compound growth trajectory analysis across the analysis window, incorporating natural gas cost sensitivity for wet-fractionation margins, quick-service restaurant expansion pipelines, and EFSA authorization timeline assumptions for European market entry.
Decision-makers should treat outputs as directional under stable FDA GRAS pathway timelines and Prairie province yield assumptions; material deviation would warrant model refresh. Revision becomes warranted when energy cost volatility crosses thresholds that compress wet-fractionation margins below viable operating levels or when EFSA novel food authorization timelines extend beyond modeled assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
France Plant Protein Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Meat Substitutes Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
India Plant Protein Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
Fractionated Pulses Market
Plant Based Food
Plant-Based Seafood Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Vegan Food Market
Plant Based Food
Vegan Drink Mixes Market