
 Global Waterproofing Membrane Market | 2026-2036
Global Waterproofing Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waterproofing Membrane Market Outlook
Skilled applicator shortages across major construction corridors is unwinding project timelines and pushing demand toward self-adhesive and peel-and-stick technologies that reduce labor intensity. Sika AG leverages its integrated supply chain from polymer feedstock to site-delivery systems to sustain margin capture in European specifications. BASF SE anchors its position through liquid-applied polyurethane platforms that compete effectively in complex geometries where sheet membranes fail. Tremco Incorporated specializes in vegetated roofing assemblies where waterproofing must integrate with drainage and root-barrier functions.
Waterproofing membranes are synthetic or bituminous sheet or fluid-applied barriers, typically 1.5–3.0 mm thick, designed to prevent water ingress across concrete, steel, or wood substrates under hydrostatic pressure or capillary action. Their primary industrial purpose is to extend structural service life by isolating reinforced concrete from chloride, sulfate, and freeze-thaw damage. Bituminous membranes still dominate volume in infrastructure tunnels and below-grade foundations where torch-on installation tolerates damp substrates, though TPO is gaining specification share in commercial roofing where reflective surfaces reduce cooling loads. Liquid-applied systems command premium positioning in water features and irregular landscape geometries where seamless coverage eliminates lap-seam failure modes.
EPA stormwater regulations in the United States mandate impermeable liners for detention and retention systems, directly specifying EPDM or reinforced polypropylene for municipal infrastructure bids. REACH restrictions on polycyclic aromatic hydrocarbons in Europe are forcing reformulation of oxidized bitumen grades, with ECHA compliance timelines compressing R&D cycles for exporters. China's GB standards for underground engineering waterproofing classify membrane performance by tensile strength and low-temperature flexibility, with MEE enforcement tightening at provincial level. Stakeholders must monitor how building energy codes in India and Southeast Asia integrate cool-roof membrane specifications with waterproofing performance, as this convergence will determine which polymer chemistries capture the next wave of specification authority.
Market Dynamics
Polymer-based membrane chemistries are displacing oxidized bitumen formulations as ECHA's REACH restrictions on polycyclic aromatic hydrocarbons tighten compliance windows and force feedstock substitution across European supply chains.
Growth Catalysts
- Urban underground infrastructure:Tunneling and metro expansion in coastal megacities with salt-laden soils and high water tables is accelerating below-grade membrane specification for structural longevity.
- EPA stormwater mandates:Impermeable liner requirements for municipal detention and retention systems directly specify EPDM and reinforced polypropylene in US infrastructure bids.
- Self-adhesive installation:Skilled applicator shortages across major construction corridors are redirecting specification toward peel-and-stick technologies that compress labor intensity and project timelines.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane and TPO membrane costs fluctuate with propylene and ethylene pricing, compressing margin predictability for liquid-applied and thermoplastic systems.
- Bitumen supply concentration:Oxidized bitumen production clusters in specific refining corridors, exposing torch-on membrane manufacturers to regional supply disruptions and logistics bottlenecks.
- Substrate compatibility limits:Sheet membranes fail in complex geometries with multiple penetrations, restricting specification share in water features and irregular landscape structures.
Strategic Opportunities
- India cool-roof integration:Building energy codes in Indian states are converging waterproofing performance with solar reflectance specifications, creating specification authority for white TPO and PVC membranes.
- Vegetated roofing assemblies:Green roof mandates in German and Swiss urban planning codes are expanding demand for multi-functional membranes combining waterproofing with root-barrier and drainage integration.
- Prefabricated membrane panels:Offsite manufacturing of membrane-clad structural elements is emerging as a channel innovation that reduces field labor and quality variability in Nordic markets.
Industry Challenges
- Applicator certification gaps:Qualified torch-on and liquid-applied installers remain scarce across Central European construction corridors, forcing contractors to stretch crews across multiple projects.
- REACH compliance timelines:ECHA's compressed reformulation deadlines for bituminous products are compressing R&D cycles for exporters serving European specifications.
- Multi-system integration:Waterproofing layers must coordinate with insulation, drainage, and root-barrier functions in vegetated assemblies, multiplying interface failure risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waterproofing Membrane Market |
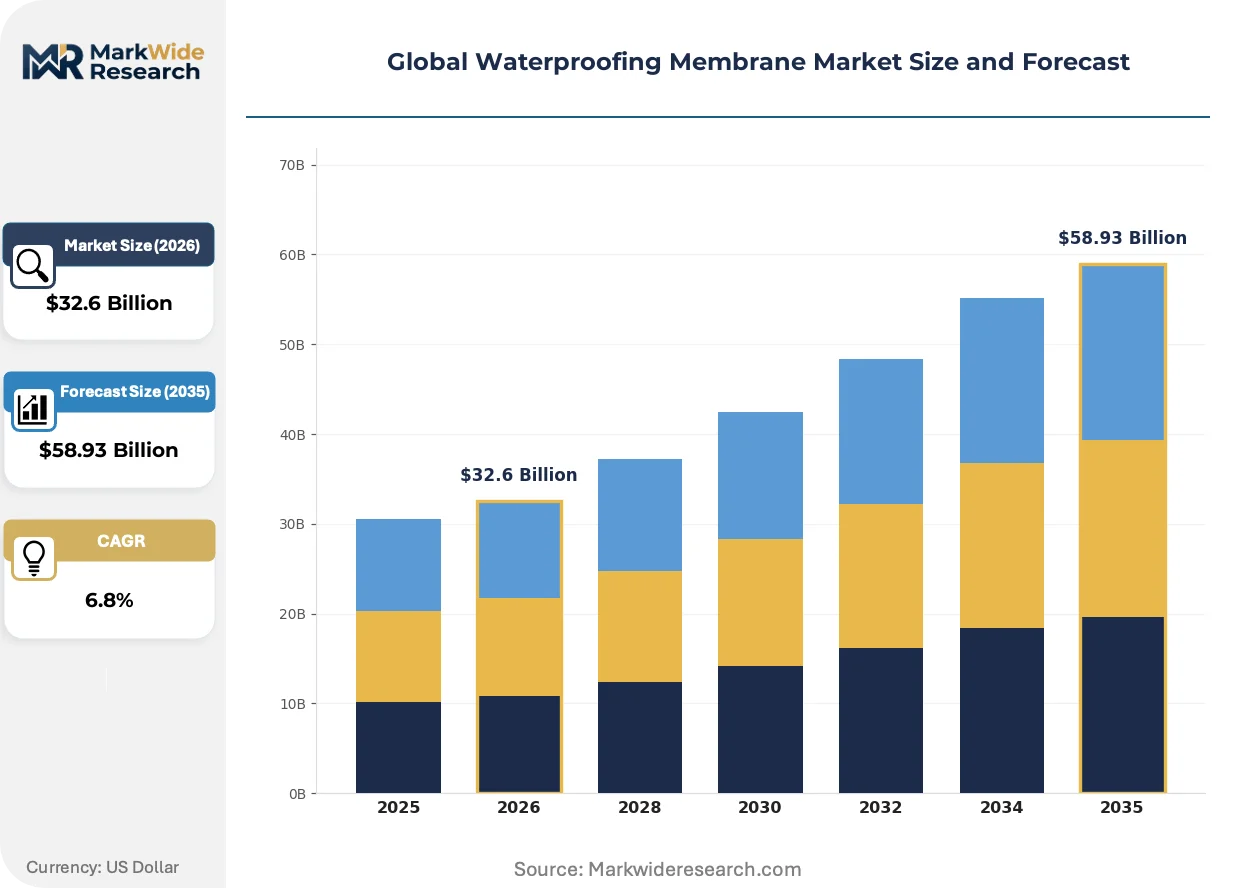
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $58.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bituminous, PVC, TPO, EPDM End User: Residential, Commercial, Industrial, Infrastructure Application: Roofing, Below Grade, Landscaping, Water Features Technology: Self-Adhesive, Liquid Applied, Torch On, Peel And Stick |
| Companies Covered | Sika AG, BASF SE, Tremco Incorporated, GCP Applied Technologies, Carlisle Companies, Soprema Group, Fosroc, Mapei, Johns Manville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waterproofing Membrane Market Strategic Shifts
Membrane technology is fragmenting along performance and installation-method axes as regulatory pressure and labor scarcity simultaneously reshape formulation priorities and field application protocols.
Self-adhesive polymer-modified bitumen is bifurcating the below-grade segment. Commercial contractors facing skilled labor shortages are specifying these membranes for foundation and plaza deck work where torch-on application is restricted or impractical. This shift is compressing demand for traditional torch-applied systems while expanding specification share for factory-applied adhesive layers that reduce field variability.
REACH restrictions on polycyclic aromatic hydrocarbons are forcing accelerated reformulation of oxidized bitumen grades across European supply chains. Membrane manufacturers serving ECHA-regulated markets are redirecting R&D investment toward SBS and APP modified bitumen alternatives. Exporters to the EU are restructuring supply chains to source compliant feedstocks or risk exclusion from municipal infrastructure tenders.
Buyer specification behavior is rotating toward performance-based warranty structures that bundle membrane supply with installation certification. General contractors in China's coastal provinces are increasingly requiring membrane suppliers to assume single-point accountability for system performance across 10-20 year horizons. This compression of risk allocation is favoring integrated manufacturers with captive installation networks over pure material suppliers.
Global Waterproofing Membrane Market Segmentation
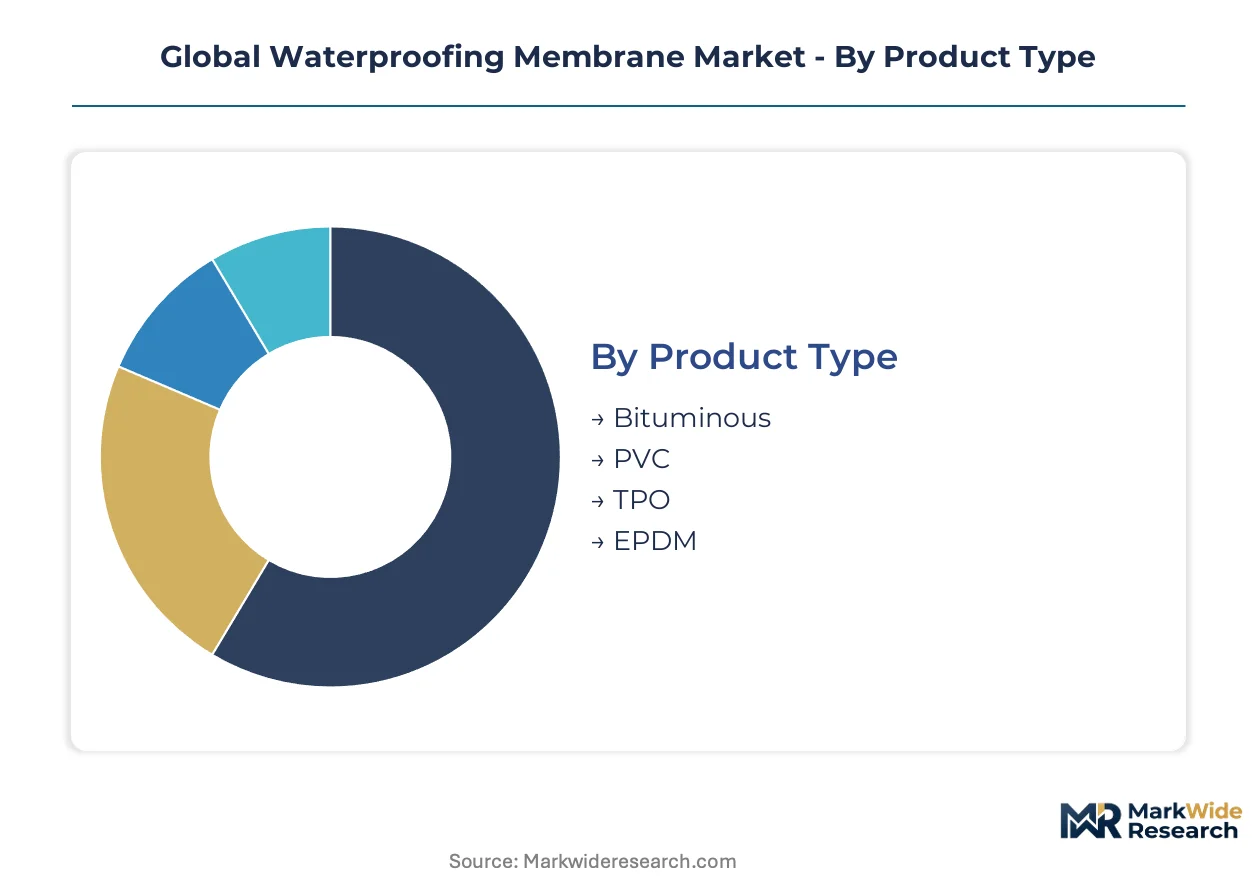
Waterproofing membrane specification diverges sharply across installation environments, with below-grade infrastructure demanding fundamentally different barrier properties than exposed roofing systems. Channel strategy must align product chemistry with substrate compatibility, labor availability, and regulatory compliance windows.
Product Type:
Channel flows separate oxidized bitumen grades toward municipal infrastructure bids through distributor-contractor relationships, while polymer membranes reach commercial roofing via specification-driven direct sales.
- Bituminous:Oxidized and polymer-modified bitumen formulations dominate tunnel and foundation specifications where torch-on installation tolerates damp concrete substrates. Demand concentrates in European infrastructure corridors where REACH restrictions on polycyclic aromatic hydrocarbons are compressing compliant feedstock availability.
- TPO:Thermoplastic polyolefin membranes deliver reflective white surfaces that reduce cooling loads in commercial roofing assemblies. China's coastal megacities with salt-laden atmospheres and high ambient temperatures are driving specification volume for energy-code-compliant building envelopes.
- PVC:Polyvinyl chloride sheets offer chemical resistance and dimensional stability across vegetated roof assemblies. German and Swiss green roof mandates are expanding procurement through specialized roofing contractors.
- EPDM:Ethylene propylene diene monomer rubber provides elastomeric performance for irregular geometries and expansion joints. EPA stormwater regulations directly specify EPDM for municipal detention and retention system liners in US infrastructure projects.
By volume, bituminous leads. By growth pace, TPO is climbing the fastest.
End User:
Cost tier differentiation separates premium-specified infrastructure membranes from standard-grade residential products, with warranty duration and performance certification driving price stratification.
- Infrastructure:Metro tunnels, highway underpasses, and water treatment facilities specify reinforced membranes under hydrostatic pressure conditions. China's MEE enforcement of GB standards for underground engineering is tightening qualification requirements for suppliers to provincial state-owned enterprises.
- Commercial:Office complexes, retail centers, and hospitality projects balance installation speed with warranty coverage. Skilled applicator shortages across Central European construction corridors are redirecting procurement toward self-adhesive systems that reduce labor intensity.
- Industrial:Manufacturing facilities and logistics warehouses require chemical-resistant barriers for process water containment and roof drainage. Indian industrial corridor development is expanding membrane specification for large-format single-ply roofing.
- Residential:Single-family and multi-family housing projects prioritize cost efficiency and installation simplicity. Nordic prefabrication trends are emerging as a channel innovation for membrane-clad structural elements.
Infrastructure commands the highest specification authority. Commercial is gaining share fastest.
Application:
Geographic clustering concentrates below-grade demand in coastal megacities with high water tables, while roofing applications track building energy code adoption across temperate climates.
- Below Grade:Foundation walls, plaza decks, and basement slabs require multi-layer systems resistant to ground moisture and soil chemistry. Salt-laden soils in China's coastal provinces are stressing reinforced concrete structures and accelerating membrane replacement cycles.
- Roofing:Exposed membrane assemblies must integrate thermal performance with waterproofing integrity. Indian state-level cool-roof mandates are converging solar reflectance specifications with barrier performance.
- Landscaping:Planter beds, podium gardens, and green roof substrates demand root-barrier integration with drainage coordination. Swiss urban planning codes are mandating vegetated surface ratios that expand multi-functional membrane procurement.
- Water Features:Fountains, reflecting pools, and artificial lakes require seamless liquid-applied coverage at complex penetrations. Irregular geometries in landscape architecture restrict sheet membrane specification.
Roofing leads by installed volume. Below grade shows the steepest expansion trajectory.
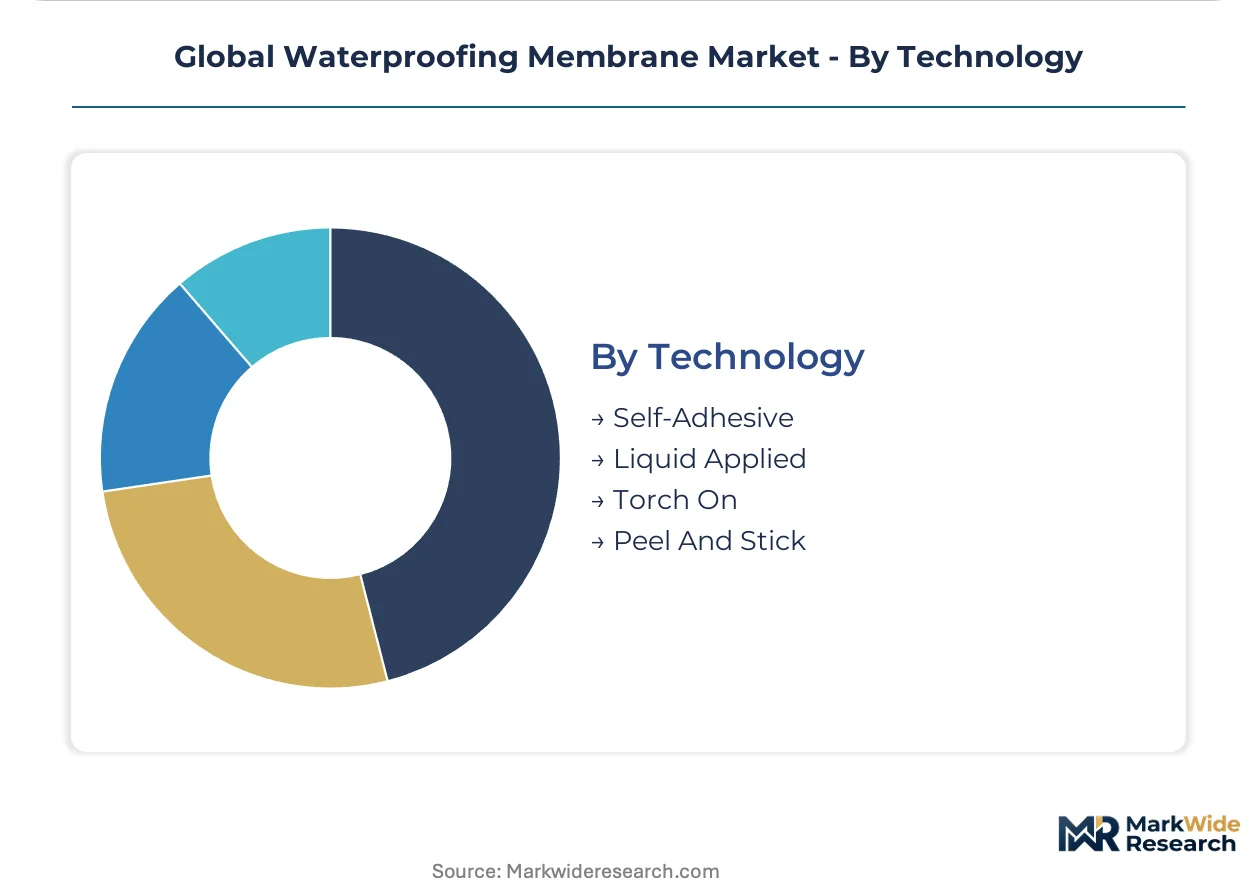
Technology:
Supply concentration in self-adhesive manufacturing is shifting procurement patterns as field labor availability tightens across major construction markets.
- Self-Adhesive:Factory-applied adhesive layers eliminate open-flame installation and reduce crew certification requirements. Applicator scarcity in German and French construction corridors is redirecting foundation and plaza deck specifications.
- Liquid Applied:Seamless polyurethane and polyurea coatings conform to irregular substrates and complex penetrations. Water feature and landscape geometries where sheet membranes fail are driving premium positioning.
- Torch On:Heat-welded bitumen installation remains dominant in infrastructure tunnels where damp substrate conditions preclude adhesive bonding. ECHA compliance timelines for PAH restrictions are compressing reformulation cycles for European supply chains.
- Peel And Stick:Simplified field application reduces labor intensity and installation variability. Commercial contractors facing compressed project timelines are specifying these systems for residential and light commercial foundations.
Torch on retains volume leadership. Self-adhesive is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Switzerland where REACH-compliant polymer formulations command specification premiums, while cost-sensitive procurement in India's emerging construction corridors compresses margins for standard bituminous systems.
United States
EPA stormwater regulations directly specify EPDM and reinforced polypropylene liners for municipal detention and retention infrastructure. The Infrastructure Investment and Jobs Act channels federal funding toward below-grade waterproofing in coastal resilience projects. Gulf Coast metropolitan areas with high water tables and hurricane exposure are accelerating membrane replacement cycles in existing commercial foundations.
Germany
ECHA enforcement of stricter VOC limits on bituminous products is redirecting formulation strategies toward SBS and APP modified bitumen alternatives. Green roof mandates in urban planning codes are expanding procurement of multi-functional membranes combining waterproofing with root-barrier integration. The Rhine-Ruhr industrial corridor hosts concentrated manufacturing capacity for polymer-modified systems serving compliant European specifications.
China
MEE enforcement of GB standards for underground engineering waterproofing is tightening qualification requirements for suppliers to provincial state-owned enterprises. Coastal megacities including Shanghai and Shenzhen face salt-laden soils and high water tables stressing below-grade structures. Yangtze River Delta infrastructure investment is accelerating membrane specification for metro tunneling and foundation work.
India
State-level building energy codes are converging waterproofing performance with solar reflectance specifications for cool-roof compliance. Industrial corridor development in Gujarat and Maharashtra is expanding membrane specification for large-format single-ply roofing. Delhi-NCR commercial construction is redirecting procurement toward self-adhesive systems to address skilled applicator shortages.
Switzerland
Urban planning codes mandating vegetated surface ratios are expanding multi-functional membrane procurement combining waterproofing with drainage coordination. Cantonal enforcement of energy efficiency standards favors white reflective membranes in commercial roofing assemblies. The Zurich-Geneva corridor concentrates specification authority for premium-grade systems in Alpine tunneling and foundation applications.
Global Waterproofing Membrane Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the waterproofing membrane market. Integrated chemical conglomerates with captive polymer feedstock operations compete against specialized roofing system fabricators with focused installation networks. The vendor base stratifies into three tiers: multinational material-science groups with specification-driven direct sales, regional membrane specialists serving contractor channels, and commodity bitumen processors competing on volume and logistics reach. Dominant competitive moves include backward integration into polymer resin production and geographic expansion through distributor partnerships in emerging construction corridors.
Among European-based integrated suppliers, Sika AG and BASF SE exemplify the technology-forward archetype with captive supply chains from polymer feedstock to site-delivery systems. Tremco Incorporated represents the specialized roofing system fabricator model with focused expertise in vegetated assemblies and complex building envelope integration. These three companies anchor distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Tremco Incorporated |
| GCP Applied Technologies |
| Carlisle Companies |
| Soprema Group |
| Fosroc |
| Mapei |
| Johns Manville |
| Others |
Value Chain & Pricing Dynamics
REACH compliance timelines for polycyclic aromatic hydrocarbons gate both feedstock qualification and price differentiation across European waterproofing membrane supply chains. Manufacturers serving ECHA-regulated markets command specification premiums for certified polymer-modified alternatives while oxidized bitumen processors absorb margin compression from reformulation costs.
Pricing Analysis
Germany and Switzerland sustain 15-25% price premiums over Indian procurement for REACH-compliant SBS-modified membranes. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade polymer systems from commodity torch-on bitumen. Cost compression in standard-grade bituminous tiers is intensifying because of petrochemical feedstock volatility and applicator scarcity. Infrastructure contractors demonstrate lowest price sensitivity due to performance warranty requirements, while residential developers in emerging corridors prioritize per-square-meter economy.
Supply Chain Analysis
Strait of Malacca transit underwrites polymer resin flows from Middle Eastern and Southeast Asian petrochemical hubs to membrane manufacturing centers. Feedstock concentration clusters in Germany, China, and the United States for SBS and APP modifiers, with oxidized bitumen production anchored in specific European and North American refining corridors. Single-source vulnerability runs through concentrated bitumen oxidation capacity subject to regional supply disruptions. Distribution runs through specification-driven direct sales for polymer membranes and distributor-contractor channels for infrastructure-grade bituminous systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The waterproofing membrane market sits in early-cycle expansion as below-grade infrastructure investment accelerates across coastal megacities with salt-laden soil conditions. Regulatory convergence of building energy codes with waterproofing performance creates new specification authority for reflective polymer systems.
For Market Incumbents: Fortify captive polymer feedstock positions through backward integration into SBS and APP modifier production. ECHA's compressed PAH compliance deadlines threaten oxidized bitumen-dependent product lines; accelerate reformulation R&D to defend municipal infrastructure tender participation. Channel control through certified installer networks protects margin capture as labor scarcity intensifies specification competition. For New Entrants and Emerging Players: CE marking fast-track for self-adhesive polymer-modified systems opens procurement access across German and Swiss commercial construction corridors. White-space concentration sits with prefabricated membrane-clad structural elements in Nordic residential markets where offsite manufacturing reduces field labor dependency. Partner with regional distributors possessing existing contractor relationships rather than building specification sales from origin. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid-applied polyurethane manufacturing due to specialized blending equipment and quality certification requirements. Long-term viability favors integrated manufacturers with captive resin production and installation service networks over pure material suppliers. Watch ECHA enforcement intensity as the inflection signal for bitumen-dependent asset stranded-risk timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Sika AG's captive SBS supply secures margin capture against propylene price volatility. |
| Prefabricated Membrane Panel Manufacturing | Nordic offsite production reduces field labor variability and compresses project timelines. |
| Self-Adhesive Technology Scale-Up | Factory-applied adhesive layers address German applicator shortages in foundation work. |
| Cool-Roof Certification Investment | White TPO and PVC systems capture Indian state-level energy code convergence. |
| Vegetated Roofing Assembly Integration | Swiss and German green roof mandates expand multi-functional membrane procurement. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with waterproofing membrane plant managers, procurement leads at downstream construction contractors, distribution channel partners, and technical R&D directors; and secondary validation through customs and trade data, SEC 10-K filings of listed chemical conglomerates, European Chemicals Agency regulatory filings, and China MEE enforcement records. Bottom-up volume modeling triangulated against top-down construction spending allocation estimates.
Across the projection horizon, the analytical framework segmented demand by product chemistry, installation technology, application environment, and end-user cost tier. CAGRs derived from regression analysis of historical construction output, infrastructure investment flows, and regulatory adoption curves. Industry-specific forecast inputs included ECHA compliance timeline assumptions, coastal megacity water table stress indices, and skilled labor availability metrics across Central European construction corridors.
Decision-makers should treat outputs as directional under stable petrochemical feedstock pricing and sustained infrastructure investment momentum; material deviation would warrant model refresh. Forecasts embed assumptions regarding REACH enforcement continuity and MEE qualification tightening trajectories. Practitioners should keep alternative scenarios live as ECHA PAH restriction scope and India cool-roof mandate adoption velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market
Membrane Materials
Global Geomembrane Market
Membrane Materials
SBS Modified Bitumen Membrane Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
Single-Ply Membranes Market
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Specialty Breathable Membranes Market