
 Polysulfone Market | 2026-2036
Polysulfone Market Size, Share, and Industry Trends Forecast 2026-2036
Polysulfone Market Analysis
The EU Green Deal is broadening polysulfone demand across membrane-based water purification systems in European municipal utilities. Solvay S.A. anchors European supply through captive resin production and membrane-grade formulation expertise. Mitsubishi Chemical Advanced Materials dominates Asian medical-grade polysulfone sheet distribution, while Ensinger GmbH specializes in high-temperature extrusion profiles for semiconductor process equipment.
Polysulfone is an amorphous thermoplastic polymer containing aryl-sulfone linkages in its backbone, offering continuous service temperatures above 150°C and inherent hydrolytic stability for repeated steam sterilization cycles. Ultrafiltration membranes command the largest product-type volume pool due to municipal and industrial wastewater retrofit cycles, while resin pellets represent the fastest-growing format as compounders seek customized melt-flow grades for medical device injection molding. Water treatment applications retain mature, replacement-driven demand, whereas aerospace components concentrate margin pools through qualification-intensive, small-batch specifications.
REACH governs monomer and additive disclosure for European polysulfone importers, while the EPA sets maximum contaminant level targets that drive membrane replacement schedules in US municipal plants. Japan's METI promotes domestic polymer recycling infrastructure that affects post-industrial scrap recovery economics. Stakeholders must monitor regulatory divergence between EU chemical safety registration and FDA device master file requirements to anticipate compliance cost shifts.
Market Dynamics
Medical device sterilization cycles and semiconductor process temperatures are pushing material specifications toward hydrolytically stable, high-heat thermoplastics, compressing substitution windows for metals and lesser polymers.
Growth Catalysts
- EU MDR traceability mandates:Device manufacturers in Germany and France now specify membrane-grade polysulfone for instrument housings requiring repeated autoclave cycles.
- Semiconductor cluster expansion:China's Yangtze River Delta fabs are retrofitting wet process equipment with sulfone-based components for chemical resistance at 150°C continuous service.
- Membrane filtration standards:EPA maximum contaminant level targets accelerate replacement schedules for municipal ultrafiltration systems in US water treatment corridors.
Market Restraints
- Bisphenol A feedstock volatility:Polysulfone synthesis depends on BPA monomer supply subject to petrochemical price swings and environmental litigation risk.
- European supply concentration:Captive resin production at Solvay's Belgian facilities creates single-source vulnerability for membrane-grade formulations.
- Polyetherimide substitution:SABIC's Ultem grades compete in medical device housings where amber tint acceptance reduces material cost.
Strategic Opportunities
- India municipal water infrastructure:Central government Jal Jeevan Mission allocations for rural piped water create membrane demand in untreated groundwater districts.
- Hydrogen electrolyzer stacks:Anion exchange membranes using sulfone backbones are displacing perfluorinated materials in alkaline water electrolysis.
- Japan polymer recycling infrastructure:METI-funded post-industrial scrap recovery programs lower feedstock costs for compounders serving medical device injection molders.
Industry Challenges
- FDA device master file synchronization:Dual-track compliance with EU MDR substance disclosure and FDA biocompatibility testing extends qualification timelines for new resin grades.
- High-temperature extrusion capability scarcity:Qualified processors for semiconductor equipment profiles remain concentrated in southern Germany and Aichi Prefecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysulfone Market |
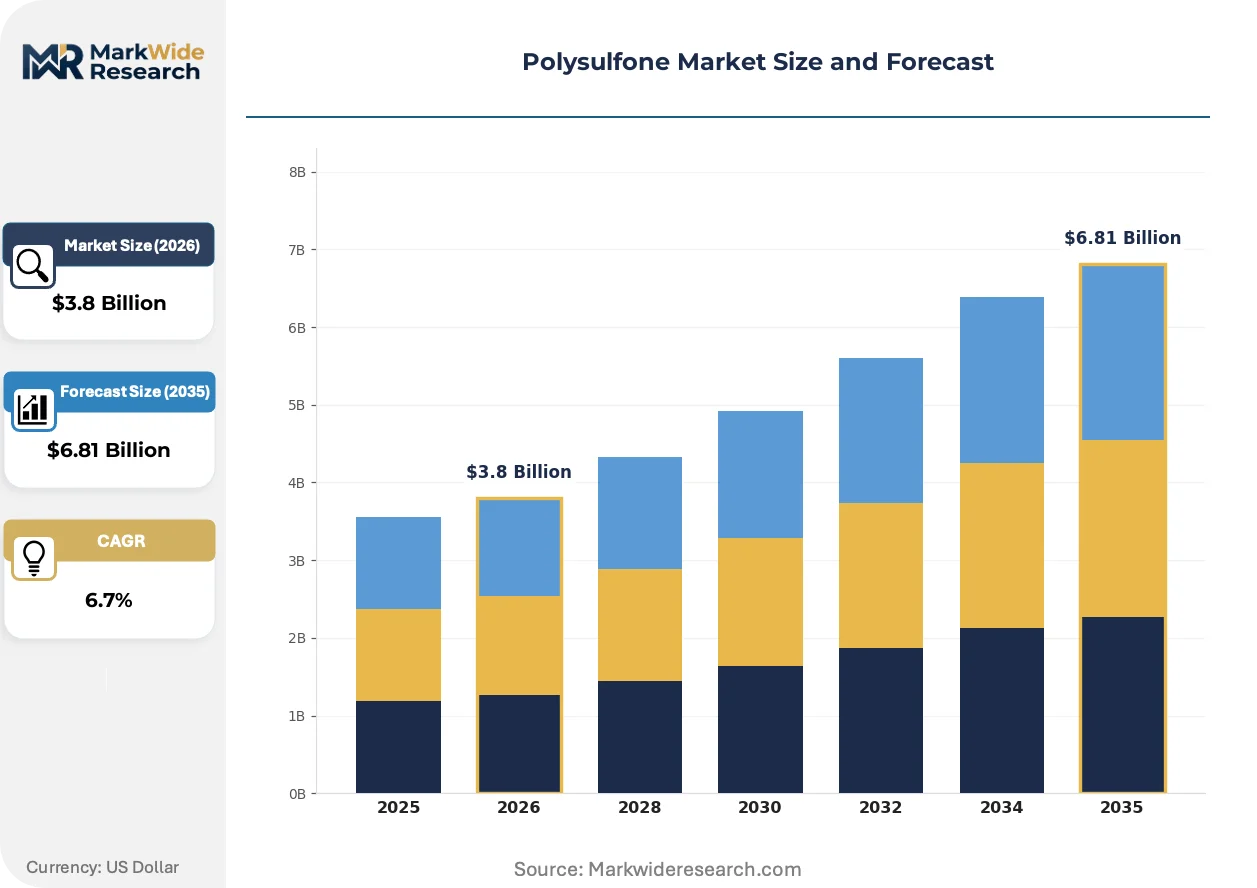
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrafiltration Membranes, Polymeric Films, Resin Pellets, Coatings Application: Water Treatment, Medical Devices, Automotive Parts, Aerospace Components End User: Semiconductors, Pharmaceutical Companies, Research Laboratories, Manufacturing Distribution Channel: Direct Sales, Online Retail, Distributors, Importers |
| Companies Covered | Sumitomo Chemical Co., Ltd., Mitsubishi Chemical Advanced Materials, Solvay S.A., RTP Company, Celanese Corporation, BASF SE, Evonik Industries AG, Ensinger GmbH, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysulfone Market Emerging Trajectories
Material science convergence with membrane engineering and medical sterilization protocols is compressing development cycles while fragmenting specification requirements across end-use verticals.
Membrane casting from sulfone-block copolymers is unifying separation performance with mechanical durability in a single formulation layer. Municipal utilities in the Netherlands and Singapore are piloting these grades for combined ultrafiltration-reverse osmosis trains. The structural consequence is collapsing the historical two-membrane-stack architecture into integrated modules, reducing footprint and capital cost for plant retrofits.
REACH Article 33 substance disclosure obligations now mandate monomer and additive reporting for all imported polysulfone articles into European customs territories. Compounders serving medical device OEMs must maintain batch-level documentation linking resin pellets to downstream component certificates. German membrane manufacturers have responded by integrating in-house analytical laboratories for supply chain verification, passing compliance costs through to municipal utility contracts.
Certification-driven procurement now separates qualified from unqualified resin grades in semiconductor wet process equipment. Original equipment manufacturers in Japan's Nagoya industrial corridor specify JIS-compliant material certificates before accepting supplier quotations, compressing vendor pools to pre-approved compounders. This behavioral shift is most visible in 300mm wafer fab expansions where process contamination liability exceeds material cost differentials by orders of magnitude.
Polysulfone Market Segmentation
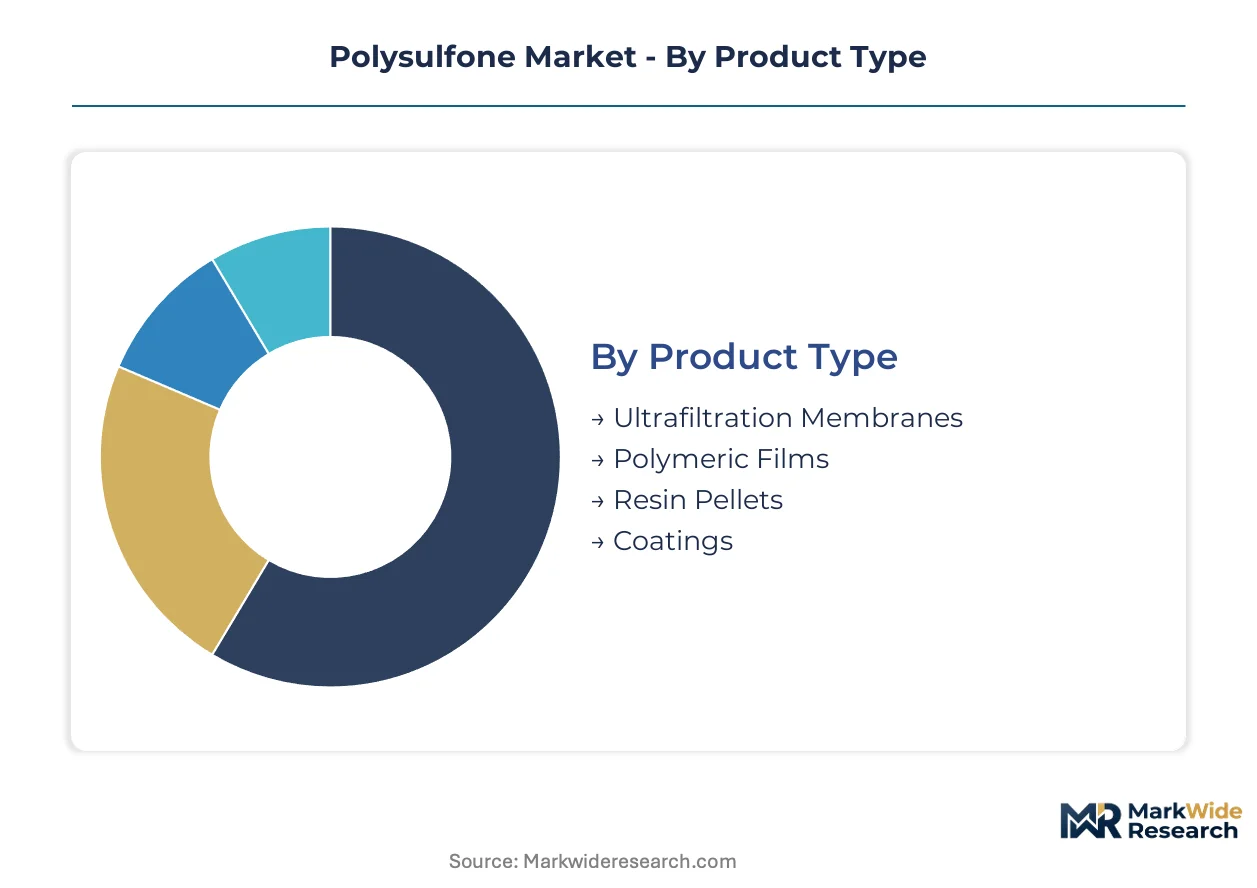
Polysulfone specification requirements fragment sharply across end-use verticals. Membrane engineers prioritize pore-size uniformity and hydrolytic stability, while medical device molders demand batch-level biocompatibility documentation. Semiconductor equipment manufacturers impose the tightest purity thresholds, creating tiered qualification barriers that reshape competitive access.
Product Type:
Standalone formats command premium pricing for immediate deployment, whereas embedded resin systems require compounder integration before value realization.
- Ultrafiltration Membranes:These asymmetric porous structures achieve molecular weight cutoffs from 1 to 100 kDa through phase-inversion casting. Municipal utilities in the Netherlands and Singapore specify sulfone-block copolymer grades for combined ultrafiltration-reverse osmosis trains, collapsing historical two-membrane-stack architectures.
- Resin Pellets:Unfilled polymer feedstock allows compounders to customize melt-flow indices for thin-wall medical device injection molding. German and Japanese medical device manufacturers are expanding adoption for sterilizable instrument housings requiring EU MDR traceability documentation.
- Polymeric Films:Cast or extruded sheet formats serve dielectric substrates and battery separator applications.
- Coatings:Solution-deposited layers provide chemical-resistant barrier protection for metal substrates in corrosive process environments.
Volume placements concentrate in Ultrafiltration Membranes; the faster expansion belongs to Resin Pellets.
Application:
Replacement-driven segments contrast with qualification-intensive niches where small-batch specifications protect margin pools.
- Water Treatment:Municipal and industrial wastewater retrofit cycles sustain mature demand for membrane replacement. EPA maximum contaminant level targets accelerate replacement schedules in US municipal plants, while China's water treatment infrastructure corridors drive new installation demand.
- Medical Devices:Repeated steam sterilization cycles at 134°C require hydrolytically stable thermoplastics for instrument housings and surgical equipment. EU MDR traceability mandates now compel German and French manufacturers to specify membrane-grade polysulfone with batch-level documentation.
- Aerospace Components:Flame-retardant grades meeting FAA smoke toxicity requirements serve aircraft interior applications.
- Automotive Parts:Under-hood thermal management components exploit continuous service temperatures above 150°C.
Revenue concentration sits with Water Treatment; Medical Devices are climbing the fastest.
End User:
Process contamination liability thresholds separate price-insensitive qualification buyers from cost-optimizing volume purchasers.
- Semiconductors:300mm wafer fabs in China's Yangtze River Delta retrofit wet process equipment with sulfone-based components for chemical resistance at 150°C continuous service. Original equipment manufacturers in Japan's Nagoya industrial corridor specify JIS-compliant material certificates before accepting quotations.
- Pharmaceutical Companies:Bioprocessing equipment and single-use systems demand extractables testing and USP Class VI certification. FDA device master file synchronization with EU MDR substance disclosure extends qualification timelines for new resin grades.
- Research Laboratories:Small-volume procurement of specialized formulations for analytical instrumentation and experimental membrane development.
- Manufacturing:Industrial compounders and converters serving diversified OEM accounts across automotive and consumer goods.
Procurement value aggregates in Semiconductors; Pharmaceutical Companies show the steepest expansion trajectory.
Distribution Channel:
Technical specification complexity determines whether direct technical partnership or intermediary logistics delivers lower total procurement cost.
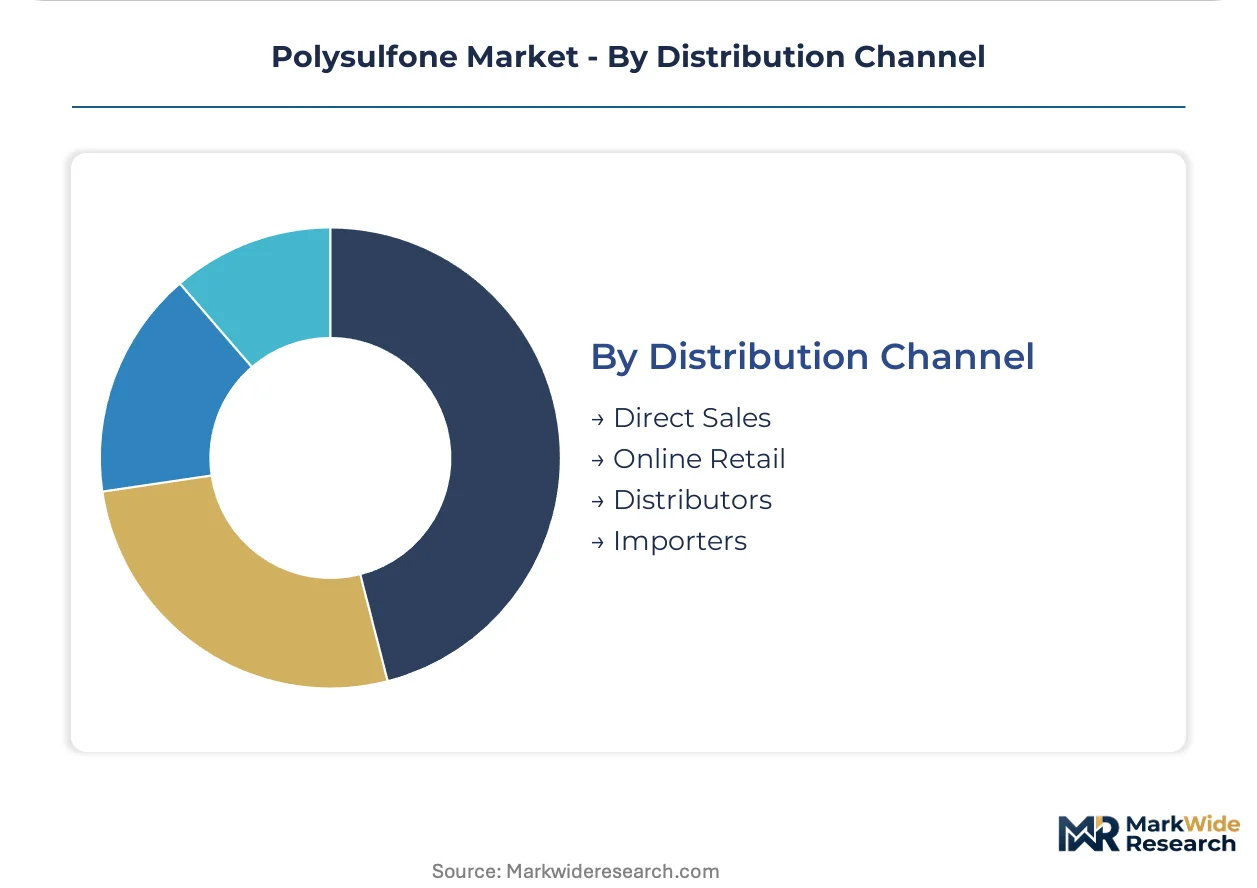
- Direct Sales:Captive resin producers and membrane-grade formulators maintain technical service relationships with municipal utilities and semiconductor OEMs. Solvay S.A. anchors European supply through direct channels for membrane-grade formulations.
- Distributors:Regional stockholding intermediaries serve medical device injection molders requiring just-in-time pellet delivery with certificate-of-analysis documentation.
- Importers:Customs territory specialists navigate REACH Article 33 substance disclosure obligations for European polysulfone articles.
- Online Retail:Catalog sales of standard grades for research quantities and prototyping applications.
Transaction volume flows through Direct Sales; Distributors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors polysulfone demand through semiconductor fabrication cluster expansion and water treatment infrastructure deployment. Germany's medical device manufacturing corridor and Japan's precision equipment zones concentrate specialized grade consumption.
United States
EPA maximum contaminant level targets accelerate ultrafiltration membrane replacement schedules across municipal water treatment plants. FDA device master file requirements govern biocompatibility documentation for medical-grade resin imports. Texas and Arizona semiconductor fabs are retrofitting wet process equipment with sulfone-based components for chemical resistance.
China
Dual carbon goals and semiconductor self-sufficiency initiatives drive domestic polysulfone consumption for electrolyzer membranes and wafer fabrication equipment. MEE water quality standards tighten discharge requirements for industrial facilities. The Yangtze River Delta and Pearl River Delta clusters host the fastest-growing concentration of membrane-grade formulation demand.
Germany
EU MDR traceability mandates compel medical device manufacturers to specify membrane-grade polysulfone with batch-level documentation. REACH Article 33 substance disclosure obligations govern monomer reporting for all imported articles. Bavaria and Baden-Württemberg concentrate high-temperature extrusion capability for semiconductor process equipment profiles.
Japan
METI-funded polymer recycling infrastructure lowers post-industrial scrap recovery costs for medical device compounders. JIS-compliant material certificates are mandatory for supplier qualification in Nagoya's semiconductor equipment corridor. Aichi Prefecture and Osaka industrial zones dominate precision-grade resin distribution for sterilizable instrument housings.
India
Jal Jeevan Mission allocations for rural piped water networks create membrane demand in untreated groundwater districts. BIS standards for polymer materials in potable water applications are tightening formulation requirements. Gujarat and Maharashtra industrial corridors are attracting compounders serving municipal utility procurement programs.
Polysulfone Market Vendor Landscape
The competitive structure tilts toward integrated resin producers with captive membrane-grade formulation capability. Belgian and Japanese chemical conglomerates anchor supply through backward integration into BPA monomer supply chains. Three archetypes dominate: diversified chemical majors with polymer divisions, specialized high-performance plastics compounders, and regional distributors with certificate-of-analysis documentation capabilities. Capacity expansion and strategic technology licensing represent the dominant competitive vectors.
Within the integrated chemical major tier, Solvay S.A. and Mitsubishi Chemical Advanced Materials exemplify producers combining resin synthesis with downstream formulation expertise. Ensinger GmbH occupies a position among specialized extrusion profile fabricators serving semiconductor equipment OEMs. These three companies represent distinct archetypes—captive resin production, Asian medical-grade distribution dominance, and high-temperature processing specialization—that collectively define competitive positioning.
| Leading Market Players |
|---|
| Sumitomo Chemical Co., Ltd. |
| Mitsubishi Chemical Advanced Materials |
| Solvay S.A. |
| RTP Company |
| Celanese Corporation |
| BASF SE |
| Evonik Industries AG |
| Ensinger GmbH |
| SABIC |
| Others |
Supply Flow & Price Mechanics
Bisphenol A spot pricing volatility cascades through polysulfone value chains, compressing margins for compounders serving medical device molders while amplifying pricing power for integrated resin producers with captive monomer supply. This feedstock-driven cost architecture stratifies procurement economics across membrane-grade, medical-grade, and semiconductor-grade tiers.
Pricing Analysis
Yield-based pricing anchors membrane procurement contracts, with municipal utilities paying premiums tied to contaminant removal throughput and membrane lifespan rather than resin weight. Pricing stratifies across membrane-grade, medical-grade, and semiconductor-grade tiers, with JIS-compliant certificates commanding substantial premiums over standard formulations. Cost compression in medical-grade pellets is intensifying because EU MDR batch-level documentation requirements raise compliance overhead for non-integrated compounders. Municipal utilities exhibit the highest price sensitivity due to public budget constraints, whereas semiconductor OEMs prioritize contamination liability mitigation over material cost differentials.
Supply Chain Analysis
Single-source vulnerability sits with Belgian resin synthesis capacity, where Solvay's captive BPA-to-pellet integration creates concentrated supply risk for European membrane manufacturers. Production gravity centers on Belgium, Japan, and China, with German extrusion specialists and Japanese medical-grade distributors completing the downstream map. Raw material flows draw from petrochemical BPA monomer streams, specialty additive packages for hydrolytic stabilization, and high-purity solvents for membrane casting. Tariff exposure on imported resin pellets into European customs territories threatens margin structures for regional compounders. Distribution runs through direct technical partnerships for membrane-grade formulations and regional stockholding intermediaries for medical device pellet supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR traceability mandates erect barrier-to-entry moats favoring integrated producers with in-house analytical laboratories and batch-level documentation systems.
For Market Incumbents: Extend qualification-intensive positioning by deepening JIS-compliant certificate portfolios for Nagoya semiconductor equipment OEMs and securing long-term offtake agreements with Yangtze River Delta fabs. Counter polyetherimide substitution threats in medical device housings through differentiated hydrolytic stability guarantees backed by accelerated aging test data. Capacity addition in Gujarat and Maharashtra industrial corridors captures Jal Jeevan Mission membrane demand before regional compounders achieve certification scale. For New Entrants and Emerging Players: Rural Indian municipal utilities represent the most penetrable buyer archetype, with untreated groundwater districts requiring cost-optimized ultrafiltration membranes outside premium European supply chains. Hydrogen electrolyzer stack manufacturers seeking anion exchange membrane alternatives to perfluorinated materials offer a second white-space target with less entrenched incumbent relationships. A technical partnership with METI-funded polymer recycling facilities in Aichi Prefecture enables post-industrial scrap feedstock cost advantages for medical-grade compounders. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized high-temperature extrusion fabricators in southern Germany with pre-qualified semiconductor equipment OEM relationships and scarce processing capabilities. Long-term viability hinges on five-to-ten year positioning around semiconductor self-sufficiency initiatives and hydrogen economy infrastructure buildouts. Monitor EPA maximum contaminant level target revisions as the inflection signal for accelerated US municipal membrane replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into BPA Monomer Supply | Captive feedstock control insulates margin compression from petrochemical price volatility. |
| Membrane-Grade Formulation Capacity Expansion | EU MDR traceability mandates concentrate demand with batch-level documentation capabilities. |
| JIS Certification Investment for Semiconductor Grades | Nagoya equipment OEMs require compliant certificates before accepting supplier quotations. |
| Post-Industrial Scrap Recovery Partnership | METI-funded infrastructure lowers feedstock costs for medical device injection molders. |
| Hydrogen Electrolyzer Membrane Development | Anion exchange sulfone backbones displace perfluorinated materials in alkaline water electrolysis. |
Methodological Framework
Independent corroboration across membrane manufacturer technical directors, medical device procurement leads, and semiconductor equipment OEM material engineers underwrites the qualitative findings in this study. Primary interviews with plant managers at Belgian and Japanese resin synthesis facilities, distribution channel partners in German medical device corridors, and regulatory affairs specialists navigating FDA-EU MDR dual-track compliance were combined with secondary validation from customs trade data, SEC chemical company filings, and REACH Article 33 disclosure databases. Bottom-up demand modeling across water treatment retrofit cycles, medical device sterilization specifications, and semiconductor wet process equipment content per fab triangulated against top-down resin production capacity assessments.
Rate-of-change decomposition across the analysis window separated volume growth from price-mix effects, with segmentation dimensions spanning grade tier, end-use vertical, and regional regulatory cluster. CAGRs were derived from installed base replacement schedules for municipal ultrafiltration systems, wafer fab expansion pipelines in China's Yangtze River Delta, and medical device master file approval trajectories. Industry-specific forecast inputs included EPA maximum contaminant level target implementation timelines and METI polymer recycling infrastructure deployment milestones.
Revisions become necessary when BPA feedstock volatility exceeds historical bands, when EPA membrane replacement mandates accelerate or defer, or when semiconductor capital expenditure cycles shift. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market
Membrane Materials
PTFE Membrane Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
Membranes Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Single-Ply Membranes Market
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Industrial Solvent Separation Membranes Market
Membrane Materials
Nanofiltration Membrane Market