
 Bitcoin Mining Servers Market | 2026-2036
Bitcoin Mining Servers Market Size, Share, and Industry Trends Forecast 2026-2036
Bitcoin Mining Servers Market Outlook
Multi-source silicon procurement is rebalancing toward vertically integrated foundry partnerships as supply volatility reshapes server economics. Bitdeer Technologies Group leverages captive foundry access to secure wafer allocations ahead of spot-market competitors. Core Scientific anchors its position through utility-scale power contracting across multiple North American interconnection zones. CleanSpark differentiates via modular site deployment that reduces infrastructure lead times for new hash rate capacity.
Bitcoin mining servers are specialized computing systems built around application-specific integrated circuits or field-programmable gate arrays, engineered to execute SHA-256 hashing algorithms at terahash-per-second throughput rates with power efficiency measured in joules per terahash. Their primary commercial purpose is to validate blockchain transactions and secure network consensus in exchange for block rewards and transaction fees. ASIC Miners dominate the product type landscape due to their unmatched hash rate density and energy efficiency compared to legacy GPU architectures. Cloud Mining Solutions represent the fastest-expanding deployment vector as capital-constrained participants seek hash rate exposure without hardware ownership. Colocation Services increasingly concentrate margin pools by offering stranded-power monetization and regulatory compliance bundled with physical infrastructure.
The EPA enforces stationary source air quality standards that constrain diesel backup generator runtime at mining facilities, while FERC interconnection queue reforms shape how quickly new server farms access bulk power. The EU Green Deal's carbon border adjustments threaten import competitiveness for hardware manufactured in carbon-intensive grids. Texas state regulators and ERCOT market administrators are revising demand-response protocols that determine whether mining loads qualify for curtailable rate structures. Stakeholders must monitor whether hash rate commoditization or power cost arbitrage becomes the decisive competitive variable.
Market Dynamics
Hash rate commoditization is compressing margins across the Bitcoin mining servers market, forcing operators to compete on power cost arbitrage rather than hardware differentiation alone. ERCOT demand-response reforms and EU carbon border adjustments are simultaneously reshaping facility economics and procurement criteria.
Growth Catalysts
- Institutional capital deployment:Pension funds and asset managers are allocating direct infrastructure investments into powered mining facilities, validating the asset class and expanding addressable demand for enterprise-grade server deployments.
- Stranded power monetization:Texas, Wyoming, and Kazakhstan host expanding mining clusters where operators capture curtailed renewable generation or underutilized grid capacity at below-market rates.
- EU Green Deal compliance pathways:Hardware manufacturers are redesigning thermal management and power delivery subsystems to meet carbon intensity thresholds for equipment imported into European markets.
Market Restraints
- Silicon supply concentration:Advanced node wafer production concentrates in Taiwan and South Korea, exposing server manufacturers to geopolitical disruption and allocation rationing during supply shocks.
- EPA stationary source enforcement:Air quality standards constrain diesel backup generator runtime at US facilities, limiting operational flexibility during grid emergencies and forcing redundant grid interconnection investments.
- Hash rate dilution mechanics:Network difficulty adjustments automatically erode individual operator rewards as aggregate compute capacity expands, creating a treadmill effect that demands continuous capital reinvestment.
Strategic Opportunities
- Modular site deployment architectures:Containerized infrastructure packages are reducing commissioning timelines from months to weeks, enabling rapid geographic repositioning toward emerging power surplus zones.
- Heat reuse integration:District heating networks in Nordic countries and greenhouse agriculture operations in North America are purchasing waste thermal output from mining facilities, creating secondary revenue streams.
- FERC interconnection queue reforms:Accelerated grid access procedures for large flexible loads are shortening the capital deployment cycle for new server farms in competitive wholesale electricity markets.
Industry Challenges
- Electrical engineering talent scarcity:Specialized expertise in high-density power distribution and immersion cooling system design commands premium compensation, constraining facility expansion timelines.
- Equipment depreciation velocity:ASIC generations become economically obsolete within 18-24 months, forcing continuous hardware refresh cycles that strain balance sheet capacity and debt servicing ratios.
- Multi-jurisdictional compliance fragmentation:Operators face divergent licensing requirements across state and national boundaries, complicating fleet standardization and increasing legal overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitcoin Mining Servers Market |
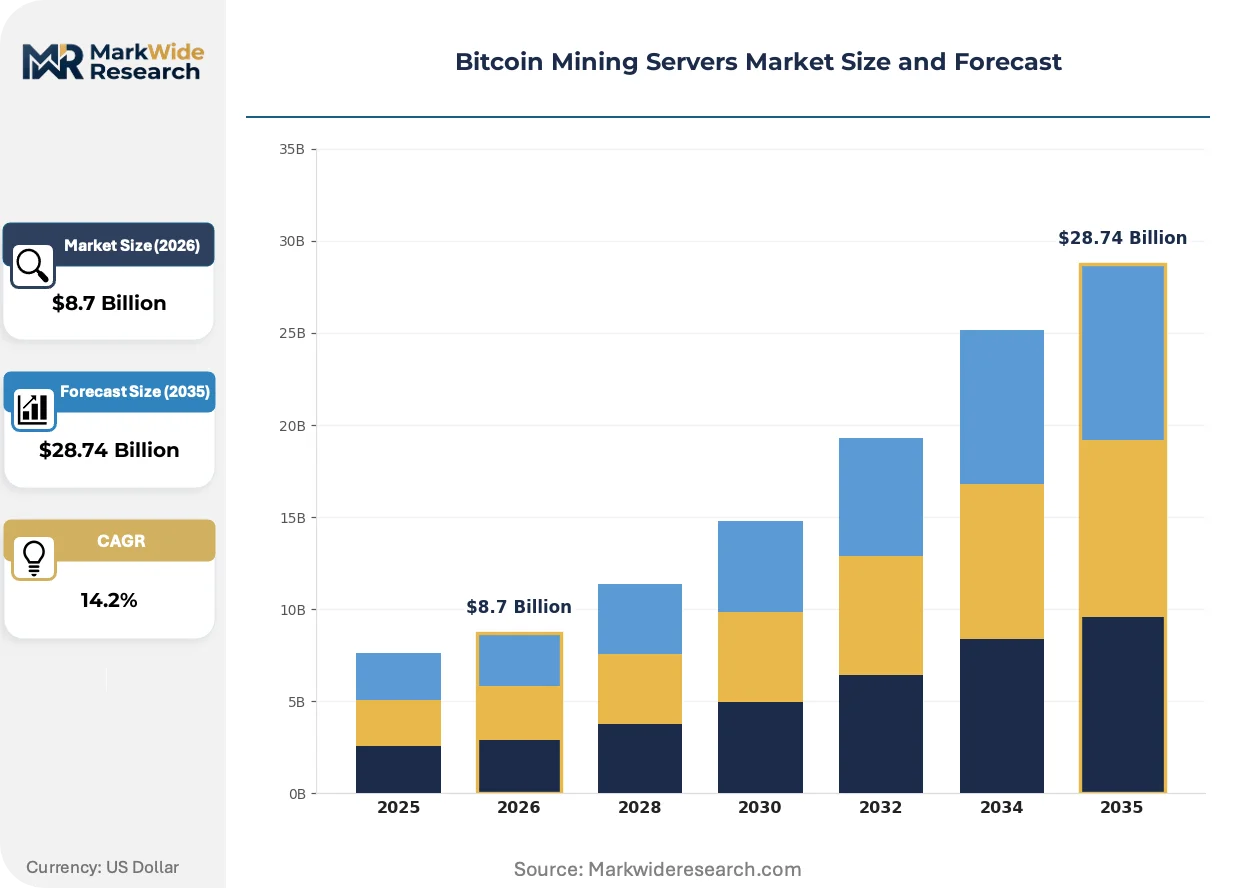
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ASIC Miners, FPGA Miners, GPU Miners, Cloud Mining Solutions Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Colocation Services End User: Individual Miners, Mining Pools, Enterprises, Data Centers Power Rating: Low Power (<1 kW), Medium Power (1-5 kW), High Power (5-10 kW), Ultra High Power (>10 kW) |
| Companies Covered | Bitdeer Technologies Group, MARA Holdings, CleanSpark, IREN Limited, Riot Platforms, Core Scientific, TeraWulf, Hut 8, Bitfarms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitcoin Mining Servers Market Strategic Shifts
Liquid immersion cooling is migrating from experimental installations to standard deployment configurations as heat density exceeds air-cooling practical limits. Regulatory pressure on carbon intensity and operational economics are jointly accelerating technology substitution cycles.
Three-phase direct liquid cooling is rewriting thermal management economics for high-density server deployments. Mining operators in Texas and Iceland are retrofitting facilities with dielectric fluid immersion systems that eliminate chiller energy consumption and extend ASIC operational lifespan. This technology is compressing total cost of ownership differentials between established and emerging mining jurisdictions by reducing the climate dependency of site selection.
The EU Green Deal's carbon border adjustment mechanism is reshaping hardware procurement criteria for equipment destined for European markets. Manufacturers must now document embedded carbon in silicon fabrication and final assembly processes to avoid tariff penalties. Mining operators in Germany and Sweden are prioritizing server purchases from foundries with verified renewable energy supply, creating procurement segmentation between carbon-compliant and conventional hardware channels.
Hash rate leasing contracts are displacing direct hardware ownership among capital-constrained participants. Institutional investors and energy companies are constructing captive mining capacity, then selling forward hash rate exposure through financialized contracts that transfer operational risk to counterparties. This model is most developed in North America, where regulatory clarity on commodity classification has enabled standardized contract terms and secondary market liquidity.
Bitcoin Mining Servers Market Segmentation
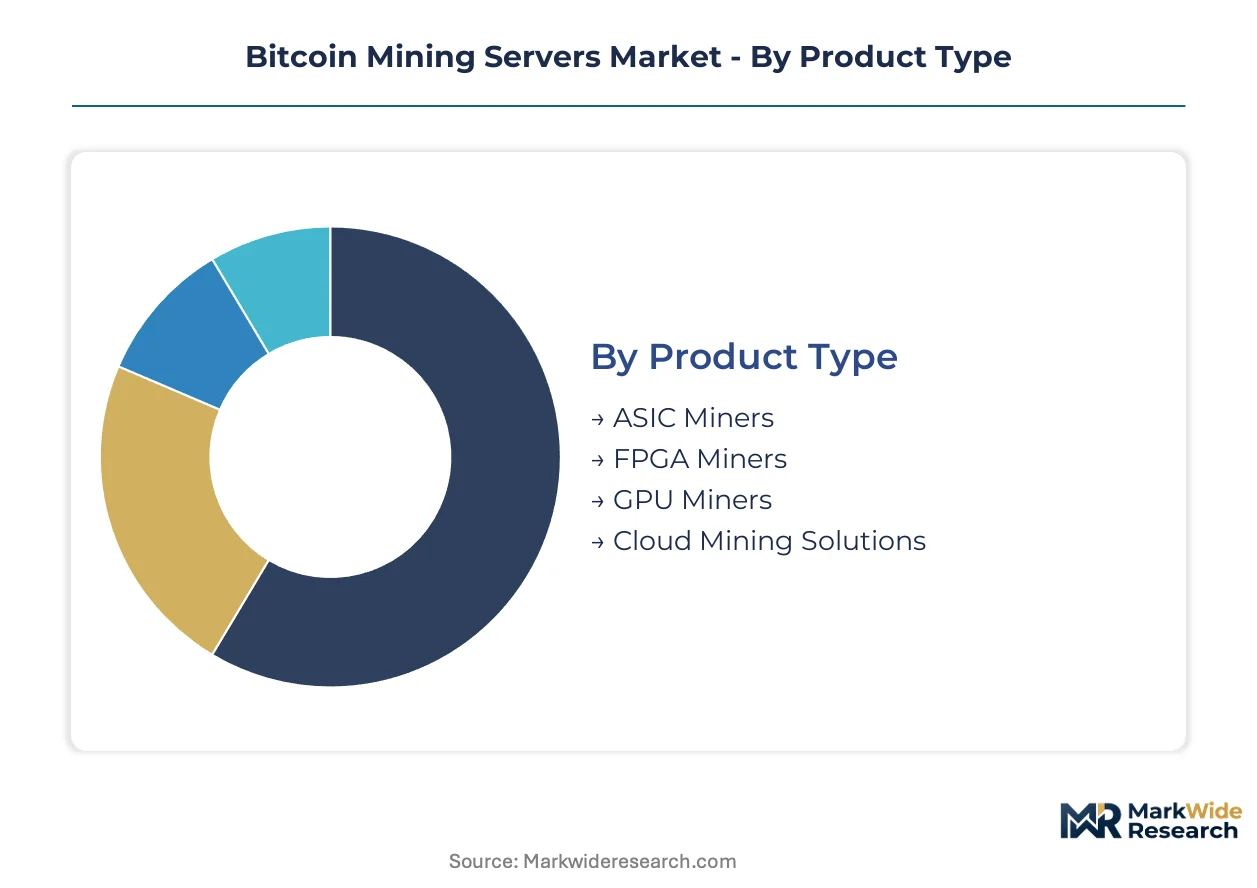
Hardware specialization and deployment economics create distinct buyer profiles across the Bitcoin mining servers market. Procurement decisions hinge on capital intensity tolerance, operational control requirements, and access to stranded power resources.
Product Type:
Capital efficiency thresholds separate buyers into performance-optimized versus flexibility-seeking segments.
- ASIC Miners:Purpose-built SHA-256 processors deliver terahash-per-second throughput with joules-per-terahash efficiency unmatched by programmable alternatives. Texas and Wyoming data centers concentrate procurement of latest-generation Bitmain and MicroBT units to maximize hash rate density per rack.
- FPGA Miners:Field-programmable gate arrays offer algorithm reconfigurability that ASICs cannot match, preserving residual value if proof-of-work consensus shifts. Research facilities and algorithmic traders in Germany and Sweden maintain small FPGA fleets for experimental mining and protocol testing.
- GPU Miners:Graphics processing units retain niche utility for multi-algorithm mining operations and secondary compute workloads. Kazakhstan operators repurposed gaming-grade GPU clusters during ASIC supply shortages.
- Cloud Mining Solutions:Hash rate leasing contracts transfer hardware depreciation risk to infrastructure owners. Capital-constrained participants in India and Brazil access exposure through standardized contracts without facility construction.
Volume sits with ASIC Miners; growth tilts toward Cloud Mining Solutions.
Deployment:
Facility ownership models reflect risk appetite and regulatory compliance burden tolerance.
- On-Premise:Self-operated server farms demand electrical engineering expertise and utility-scale interconnection negotiations. Wyoming's integrated energy producers favor captive deployment to monetize stranded gas generation directly.
- Cloud-Based:Fully abstracted hash rate access eliminates physical infrastructure management. Southeast Asian retail participants dominate this segment where capital controls complicate hardware importation.
- Hybrid Solutions:Split deployments balance control over core capacity with burst scaling through third-party pools. Canadian operators use hybrid architectures to manage FERC interconnection queue delays.
- Colocation Services:Third-party facility hosting bundles power procurement, cooling, and compliance. Iceland's geothermal-powered data centers attract European miners seeking EU Green Deal carbon intensity verification.
Revenue concentrates in Colocation Services; expansion accelerates fastest in Hybrid Solutions.
End User:
Scale economies and risk distribution mechanisms define competitive positioning across buyer types.
- Individual Miners:Solo operators with sub-megawatt deployments compete through residential renewable generation or retail rate arbitrage. Texas residential solar-plus-battery configurations sustain this segment despite network difficulty pressures.
- Mining Pools:Hash rate aggregation smooths reward variance for distributed participants. Foundry USA and Antpool dominate North American pool infrastructure, capturing fee revenue from hashrate coordination.
- Enterprises:Corporate treasury diversification strategies drive institutional procurement. Nasdaq-listed energy companies in Wyoming and Pennsylvania deploy balance sheet capacity into powered mining facilities.
- Data Centers:Hyperscale compute providers retrofit idle capacity or construct dedicated mining halls. Core Scientific's multi-site North American footprint exemplifies data center scale deployment.
Hash rate volume pools with Mining Pools; enterprise balance sheet deployment is climbing the fastest.
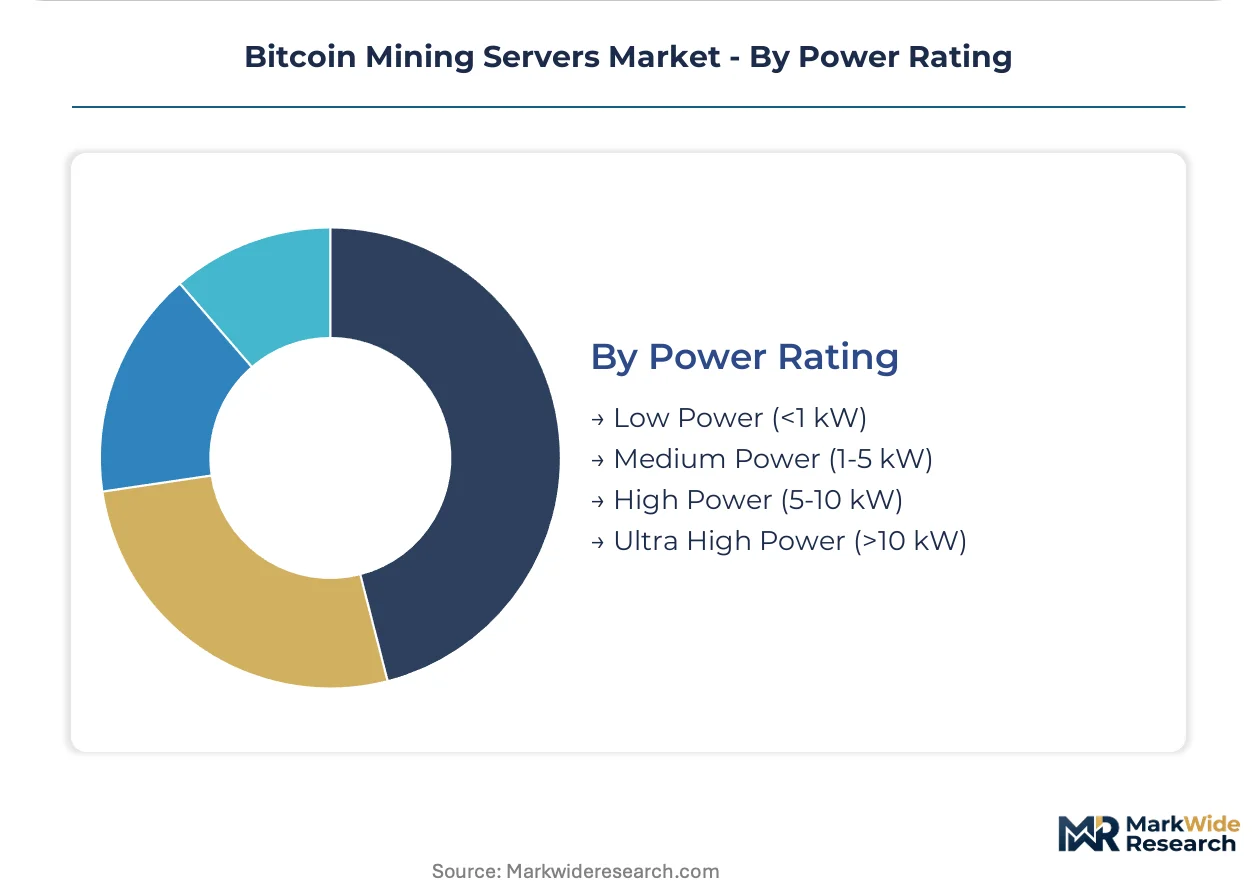
Power Rating:
Thermal management complexity and interconnection voltage class stratify procurement across wattage tiers.
- Low Power (<1 kW):Consumer-grade units operate on standard 120V/240V residential circuits without electrical infrastructure upgrades. German basement hobbyists and Indian urban miners sustain residual demand for obsolete ASIC generations in this bracket.
- Medium Power (1-5 kW):Rack-mountable systems require dedicated 208V three-phase distribution but avoid substation-level interconnection. Kazakhstan's industrial zone conversions favor this density for Soviet-era factory electrical retrofits.
- High Power (5-10 kW):Advanced immersion cooling compatibility and 480V industrial feed requirements characterize this tier. Texas ERCOT demand-response participants deploy high-power density to maximize curtailable load compensation.
- Ultra High Power (>10 kW):Next-generation monolithic systems push liquid cooling and medium-voltage interconnection boundaries. Bitfarms and Riot Platforms pilot these units in Quebec and Texas facilities with direct utility substation access.
Installed base clusters in Medium Power; Ultra High Power captures steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stranded natural gas fields in Wyoming and underutilized wind capacity in West Texas anchor North American mining infrastructure deployment. These energy-rich localities attract capital from operators seeking below-grid power rates. Geographic concentration follows power cost arbitrage rather than traditional manufacturing logic.
United States
Texas ERCOT market reforms enable demand-response participation for curtailable mining loads, reducing effective power costs. EPA stationary source enforcement limits diesel backup runtime, pushing operators toward redundant grid interconnections. Wyoming's Powder River Basin hosts utility-scale facilities monetizing stranded gas generation through direct pipeline access.
Kazakhstan
Soviet-era industrial zones in Pavlodar and Karaganda offer subsidized electricity tariffs for relocated Chinese hardware. The central bank's digital asset framework creates licensing requirements for facility operators. Almaty-region data centers concentrate medium-power deployments retrofitting former factory electrical infrastructure.
Canada
Quebec's hydroelectric surplus and Manitoba's grid stability attract immersion-cooled facilities seeking renewable verification. Provincial utility regulators cap new mining interconnections to protect residential ratepayers. Bitfarms operates multi-site footprints leveraging direct substation access in rural Quebec municipalities.
Germany
EU Green Deal carbon border adjustments impose documentation requirements on imported ASIC hardware. Foundries with verified renewable supply chains command procurement premiums from compliance-focused operators. Saxony-Anhalt's former lignite regions repurpose grid infrastructure for renewable-powered hosting facilities.
Iceland
Geothermal and hydroelectric baseload power supports near-zero carbon intensity mining operations. District heating networks purchase waste thermal output from immersion-cooled facilities, creating secondary revenue streams. Reykjanes Peninsula data centers attract European colocation demand seeking EU Green Deal verification.
Bitcoin Mining Servers Market Competitive Environment
Global majors compete with regional champions across power contracting and silicon procurement dimensions. The vendor base stratifies between vertically integrated operators with captive foundry access and pure-play hosting providers dependent on spot hardware markets. Three archetypes dominate: utility-scale power contractors, modular deployment specialists, and hash rate financialization platforms. Competitive positioning hinges on interconnection queue positioning and stranded power offtake agreements rather than manufacturing scale.
Among North American infrastructure operators, Bitdeer Technologies Group, Core Scientific, and CleanSpark occupy distinct strategic positions. Bitdeer exemplifies the vertically integrated archetype through captive foundry partnerships securing wafer allocations. Core Scientific anchors the utility-scale power contracting segment across multiple interconnection zones. CleanSpark represents modular deployment specialists compressing site commissioning timelines through containerized infrastructure packages.
| Leading Market Players |
|---|
| Bitdeer Technologies Group |
| MARA Holdings |
| CleanSpark |
| IREN Limited |
| Riot Platforms |
| Core Scientific |
| TeraWulf |
| Hut 8 |
| Bitfarms |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon border adjustment mechanisms gate qualified supply for European-bound hardware and stratify premium-tier pricing access for compliant manufacturers. The EPA's stationary source enforcement and FERC interconnection protocols simultaneously reshape procurement economics across North American deployment zones.
Pricing Analysis
Warranty and service bundling separates premium-tier server procurement from unbundled spot-market transactions. Three-tier pricing structure across premium, standard, and economy levels reflects hash rate efficiency ratings and immersion cooling compatibility. Cost compression in economy-tier ASICs is intensifying because stranded-power operators prioritize volume procurement over feature differentiation. Individual miners exhibit highest price sensitivity, while enterprise data centers absorb premium pricing for guaranteed delivery slots and extended thermal warranties.
Supply Chain Analysis
Certification and qualification gating from Taiwan Semiconductor Manufacturing Company and Samsung Foundry concentrates advanced node wafer supply for SHA-256 ASICs. Silicon wafers, power delivery subsystems, and immersion cooling fluids anchor raw material dependencies. Single-source vulnerability in 5nm and 3nm fabrication exposes server manufacturers to geopolitical disruption and allocation rationing. Distribution runs through direct foundry partnerships for vertically integrated operators and spot-market brokers for pure-play hosting providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive foundry access and utility-scale power contracting determine survival margins. Players are pursuing upstream control over wafer allocations as the decisive competitive lever.
For Market Incumbents: Acquire stranded-power offtake agreements in Wyoming and Texas to lock in below-grid electricity rates. Secure multi-year foundry allocation contracts ahead of spot-market competitors facing silicon rationing. Hash rate commoditization threatens hardware differentiation margins, making power cost arbitrage the primary defensive moat. Certification investment in EU Green Deal compliance pathways preserves European market access against carbon border adjustment penalties. For New Entrants and Emerging Players: Launch via modular containerized deployment targeting Kazakhstan's Soviet-era industrial zones with subsidized tariffs. Capital-constrained participants in Southeast Asia and Latin America represent the most penetrable segment for cloud-based hash rate leasing without hardware ownership. District heating integration partnerships in Nordic countries offer a specific go-to-market angle for waste thermal monetization. For Investors and Strategic Acquirers: FERC interconnection queue clearance acceleration is the leading indicator that capital deployment cycles are compressing for new capacity. Long-term viability hinges on operators with demonstrated power contracting execution rather than hardware inventory accumulation. Acquisition target archetype: vertically integrated mid-caps with captive foundry relationships and multi-site utility interconnections. Watch ERCOT demand-response protocol reforms as the signal for curtailable load compensation structures.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Securement | Captive wafer allocations from TSMC and Samsung insulate against supply shocks and allocation rationing. |
| Stranded-Power Monetization | Direct pipeline access to Wyoming gas fields and Texas wind curtailment secures below-market electricity rates. |
| Immersion Cooling Deployment | Dielectric fluid systems eliminate chiller consumption and extend ASIC lifespan in high-density configurations. |
| EU Carbon Compliance Certification | Verified renewable supply chains from foundries avoid Green Deal tariff penalties on European hardware imports. |
| Hash Rate Financialization Platform | Forward hash rate contracts transfer operational risk and attract institutional capital without hardware ownership. |
Study Parameters
Multi-period observation of hash rate deployment, power contracting structures, and foundry allocation patterns anchored the trend analysis, supplemented by interviews with data center operators, utility interconnection specialists, ASIC procurement directors, and immersion cooling system engineers. Secondary validation drew from FERC interconnection queue filings, EIA electricity market data, EPA stationary source enforcement records, and EU Green Deal carbon border adjustment documentation. Bottom-up facility deployment tracking and top-down market sizing triangulated volume estimates.
Segment-weighting across product type, deployment model, end user category, and power rating tier informed the analytical framework across the projection horizon. CAGRs were derived from deployment velocity assumptions tied to interconnection queue clearance rates and stranded-power offtake expansion. Hash rate commoditization mechanics and network difficulty adjustment algorithms served as industry-specific forecast inputs.
Geopolitical disruption in Taiwan Strait shipping lanes, abrupt EPA enforcement escalation, and ERCOT market rule reversals are the dominant revision risks to deployment assumptions. Forecasts reflect documented assumptions about power cost trajectories and silicon supply continuity. A model refresh is warranted upon material change in FERC interconnection reform implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Duckweed Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
Griffin Beaker Market
Others
Global Active Speaker Market
Others
PC As a Service Market
Others
Singapore Retail Market
Others
Global Digital Caliper Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
Electric Pallet Jack Truck Market
Others
Diamond Mining Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
Asia-Pacific Telecom Transformers Market
Others
Gem Faceting Machine Market
Others
Fresh Pears Market
Others
UAE Location-Based Services Market
Others
South America Orange Market