
 Global Digital Caliper Market | 2026-2036
Global Digital Caliper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Caliper Market Analysis
Bluetooth-enabled data logging is fragmenting how dimensional data flows from shop floors to quality management systems. Mitutoyo Corp. anchors premium positioning through captive sensor fabrication and calibration laboratory networks. Guilin Guanglu Measuring Instrument Co. Ltd. competes aggressively on cost-engineered 0-150 mm units for export markets. Hexagon AB extends software-hardware integration by embedding digital caliper outputs directly into its CAD-CAM quality loops.
A digital caliper is a precision linear measurement instrument employing capacitive or inductive encoded scales to display readings on an LCD screen, typically resolving to 0.01 mm or 0.0005 inches. The device eliminates parallax error inherent in mechanical vernier interpretation while enabling direct data transfer to statistical process control systems. Outside calipers dominate volume shipments for general machining applications, yet Bluetooth-enabled units represent the fastest-expanding technology segment as manufacturers pursue paperless inspection workflows. The 0-300 mm measurement range captures the broadest end-user base across automotive and electronics fabrication, while depth calipers command margin premiums in aerospace bore inspection.
FDA 21 CFR Part 820 quality system regulations and ISO 9001:2015 certification requirements compel medical device and automotive suppliers to maintain calibrated, traceable dimensional records. China's GB/T standards and Japan's JIS B 7507 specifications create divergent product certification paths that shape regional manufacturing footprints. Stakeholders must weigh captive calibration service investments against third-party laboratory partnerships as data-integrity requirements harden across regulated industries.
Market Dynamics
Bluetooth-enabled data logging is fragmenting how dimensional data flows from shop floors to quality management systems, compressing inspection cycles and forcing recalibration of vendor relationships across precision manufacturing clusters.
Growth Catalysts
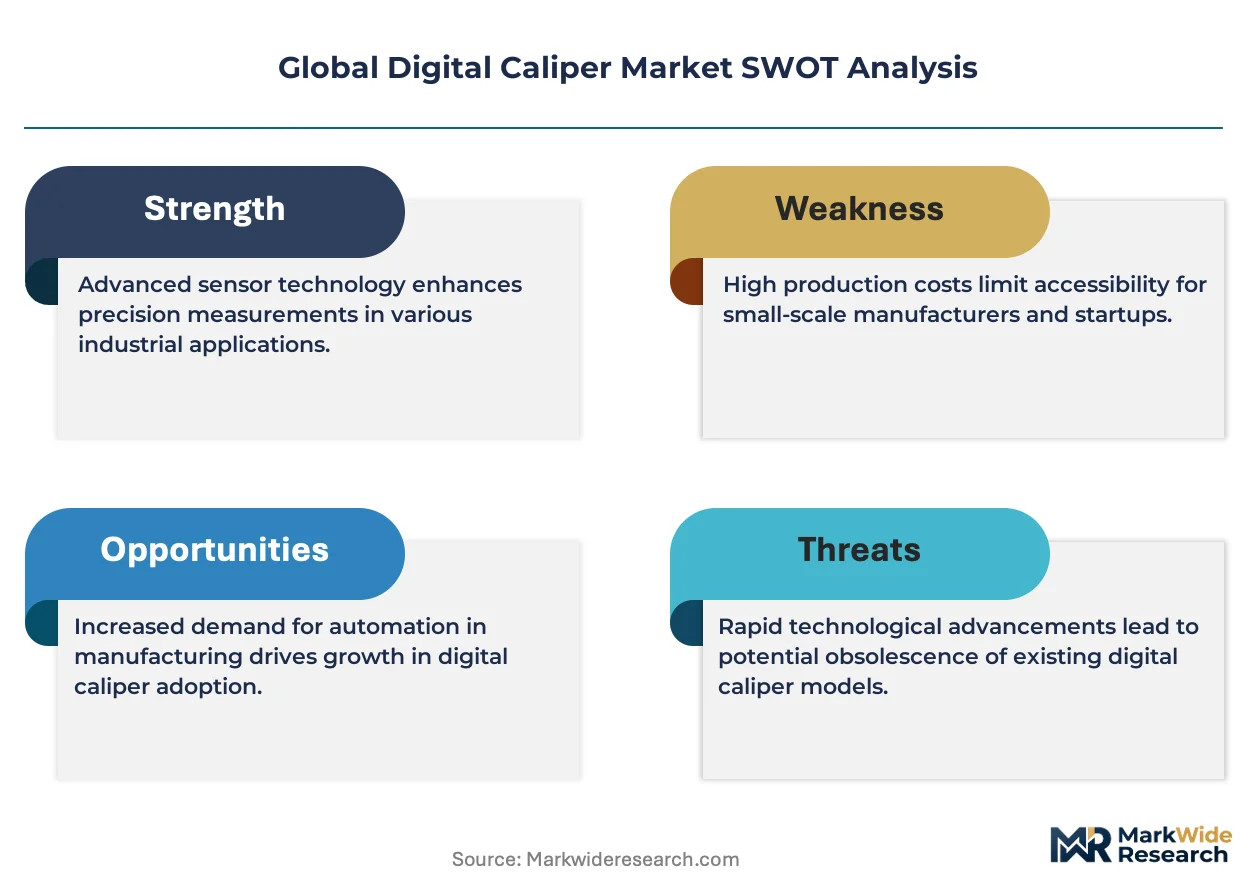
- ISO 17025 Calibration Mandates:Aerospace component manufacturers in Germany and Japan are expanding metrology budgets as third-party laboratory accreditation requirements tighten, creating pull-through demand for traceable digital instruments.
- Electronics Contract Manufacturing:Precision machining clusters across China's Guangdong province are driving replacement cycles for wireless-enabled measurement tools as paperless inspection workflows become standard.
- Capacitive Scale Encoding:Advances in inductive and capacitive sensor fabrication are reducing unit costs while maintaining 0.01 mm resolution, expanding addressable markets beyond premium industrial buyers.
Market Restraints
- Sensor Supply Concentration:Captive production of high-precision encoded scales concentrates among Japanese and German component suppliers, exposing assemblers to single-source risk during capacity constraints.
- Regulatory Divergence:China's GB/T standards and Japan's JIS B 7507 specifications create divergent product certification paths that fragment manufacturing footprints and duplicate compliance costs.
- Mechanical Vernier Substitution:Low-cost mechanical calipers retain dominant share in price-sensitive maintenance and education markets, capping penetration in developing economies.
Strategic Opportunities
- India Manufacturing Incentives:PLI scheme benefits for precision engineering and medical device production are creating fresh demand for ISO-certified metrology equipment in previously underpenetrated industrial corridors.
- CAD-CAM Integration:Direct embedding of digital caliper outputs into quality loops converges measurement hardware with manufacturing execution software, opening recurring revenue streams.
- Medical Device Traceability:FDA 21 CFR Part 820 quality system regulations compel calibrated dimensional records, creating regulatory tailwinds for Bluetooth-enabled data logging in orthopedic and surgical instrument fabrication.
Industry Challenges
- Metrology Technician Scarcity:ISO 17025 accreditation requirements for calibration laboratory personnel outpace vocational training pipeline output, extending service delivery timelines.
- Legacy System Integration:Paper-based quality management systems in tier-two automotive suppliers resist seamless data ingestion from wireless measurement tools, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Caliper Market |
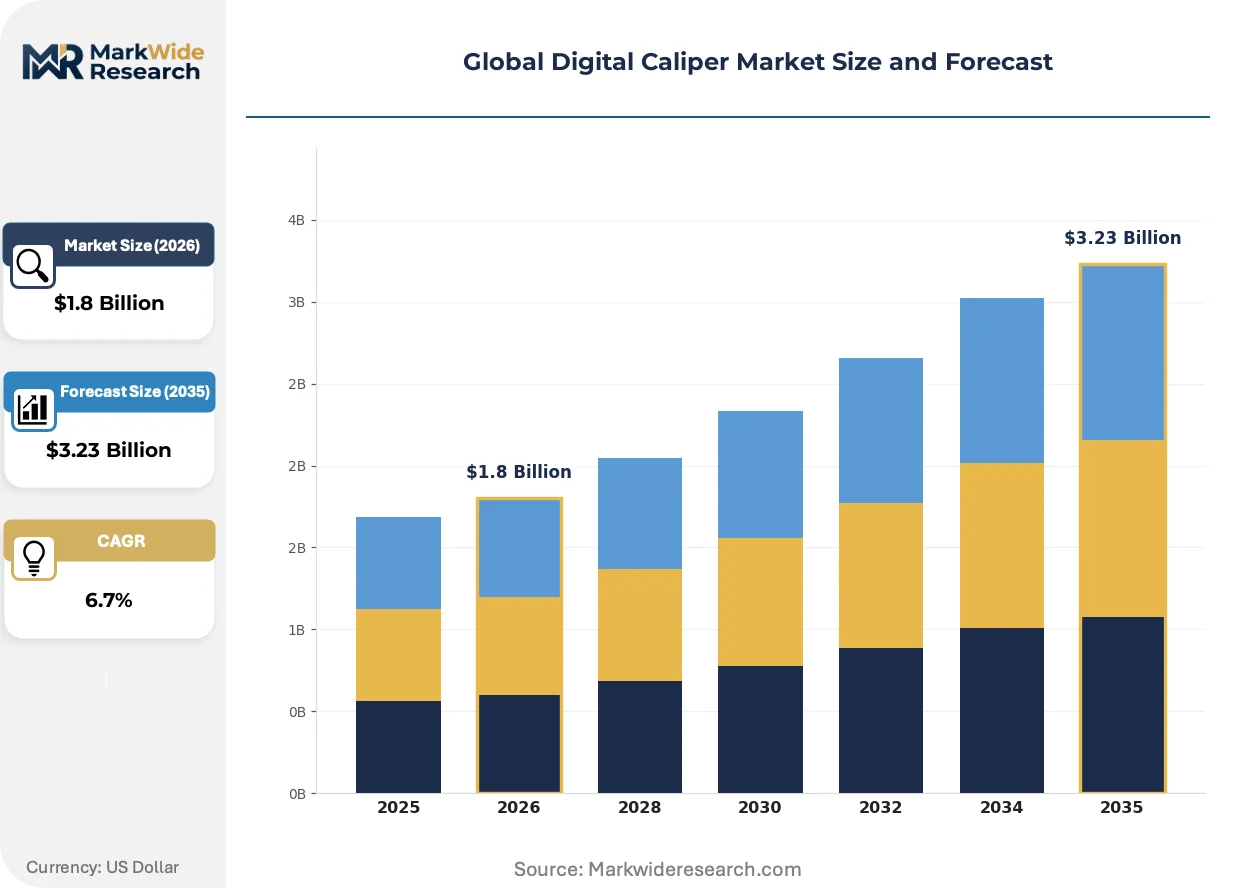
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vernier Calipers, Depth Calipers, Inside Calipers, Outside Calipers Technology: Digital, Mechanical, Electronic, Bluetooth End User: Manufacturing, Construction, Automotive, Electronics Measurement Range: 0-150 mm, 0-300 mm, 0-600 mm, 0-1000 mm |
| Companies Covered | Mitutoyo Corp., Hexagon AB, The L.S. Starrett Co., Fowler High Precision Inc., Guilin Guanglu Measuring Instrument Co. Ltd., HELIOS-PREISSER GmbH, Dorsey Metrology International, Draper Tools Ltd., Hornady, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Caliper Market Emerging Trajectories
Wireless connectivity protocols and embedded sensor intelligence are actively restructuring how dimensional inspection data circulates between production equipment and enterprise quality platforms.
Bluetooth Low Energy modules integrated directly into caliper electronics are digitizing shop-floor data capture by eliminating manual transcription errors and enabling real-time statistical process control. Tier-one automotive suppliers in the US Midwest are deploying these units at scale to satisfy NHTSA traceability requirements for safety-critical component dimensions. The technology is digitizing quality documentation workflows, compressing inspection-to-release cycles from hours to minutes.
EU MDR medical device regulations now mandate validated measurement systems with documented uncertainty budgets for implantable device manufacturing. This policy shift forces contract manufacturers to retire uncalibrated mechanical instruments and adopt digitally traceable alternatives with embedded calibration certificates. German orthopedic instrument clusters are responding fastest, integrating RFID-tagged calipers directly into their ISO 13485 quality management systems.
After-sales service unbundling is reshaping how buyers evaluate total cost of ownership, with procurement teams separately negotiating hardware acquisition, calibration contracts, and software subscriptions. Electronics fabricators in South Korea's Gyeonggi province are leading this shift, treating metrology equipment as operational technology rather than capital expenditure. The pattern is most pronounced where ISO 9001:2015 certification renewals drive recurring calibration spend into multi-year service agreements.
Global Digital Caliper Market Segmentation
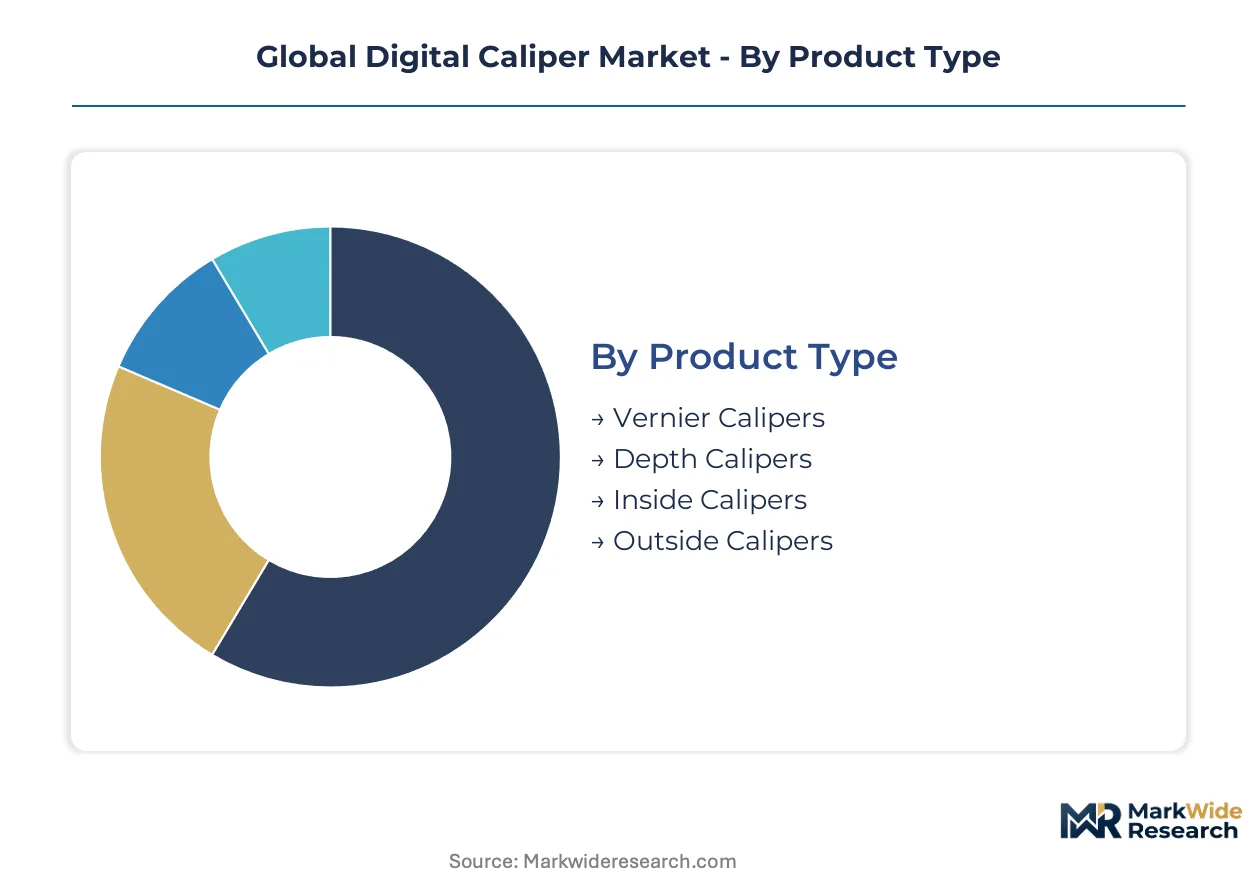
Digital caliper segmentation reveals how measurement precision requirements fragment across fabrication workflows. Product architecture, connectivity protocols, and dimensional range each create distinct purchasing criteria that shape vendor specialization.
Product Type:
Use-case spectrum spans from general machining to specialized bore inspection across industrial quality departments.
- Outside Calipers:These instruments measure external dimensions of shafts, pipes, and machined components through opposed jaw configurations. General machining applications in Germany's automotive supplier clusters drive volume procurement for ISO 9001-compliant inspection stations.
- Depth Calipers:Equipped with slender probe rods for measuring hole depths, slot recesses, and step heights, these units command margin premiums in aerospace bore inspection workflows. Japanese orthopedic instrument manufacturers specify these for EU MDR-compliant implantable device verification.
- Vernier Calipers:Hybrid mechanical-digital designs retain relevance in educational institutions and maintenance shops where battery independence matters.
- Inside Calipers:Specialized jaw geometries access internal diameters in bearing housings and cylinder bores, serving powertrain fabrication in India's PLI-supported precision engineering corridors.
The dominant share belongs to Outside Calipers, while Depth Calipers is closing the gap fastest.
Technology:
Cost tier separation runs from commodity mechanical tools to connected systems with embedded data integrity.
- Bluetooth:Wireless Low Energy modules enable direct transmission to statistical process control software, eliminating transcription errors. Tier-one automotive suppliers in the US Midwest deploy these at scale to satisfy NHTSA traceability mandates for safety-critical dimensions.
- Digital:Capacitive or inductive encoded scales with LCD readouts deliver 0.01 mm resolution without parallax error. China's Guangdong electronics contract manufacturers are driving replacement cycles as paperless inspection workflows become standard.
- Electronic:Early-generation digital displays without connectivity retain share in price-sensitive maintenance markets.
- Mechanical:Vernier-scale instruments persist in vocational training and developing economy workshops where capital constraints dominate.
Bluetooth-enabled units are expanding most quickly, while Digital calipers retain the largest installed base.
End User:
Application intensity varies from high-volume production lines to intermittent field verification.
- Manufacturing:Precision machining clusters require calibrated, traceable instruments for ISO 17025-accredited quality systems. German aerospace component producers are expanding metrology budgets as third-party laboratory requirements tighten.
- Electronics:Miniaturized component fabrication demands sub-millimeter repeatability in cleanroom environments. South Korean semiconductor packaging facilities in Gyeonggi province treat metrology equipment as operational technology with multi-year service agreements.
- Automotive:Powertrain and chassis suppliers maintain dimensional records for safety-critical assemblies under FDA 21 CFR Part 820 and ISO/TS 16949 protocols.
- Construction:Structural steel verification and MEP installation rely on durable, weather-resistant units with less stringent calibration frequency.
Manufacturing holds the dominant share, though Electronics is climbing the fastest as miniaturization tightens tolerance requirements.
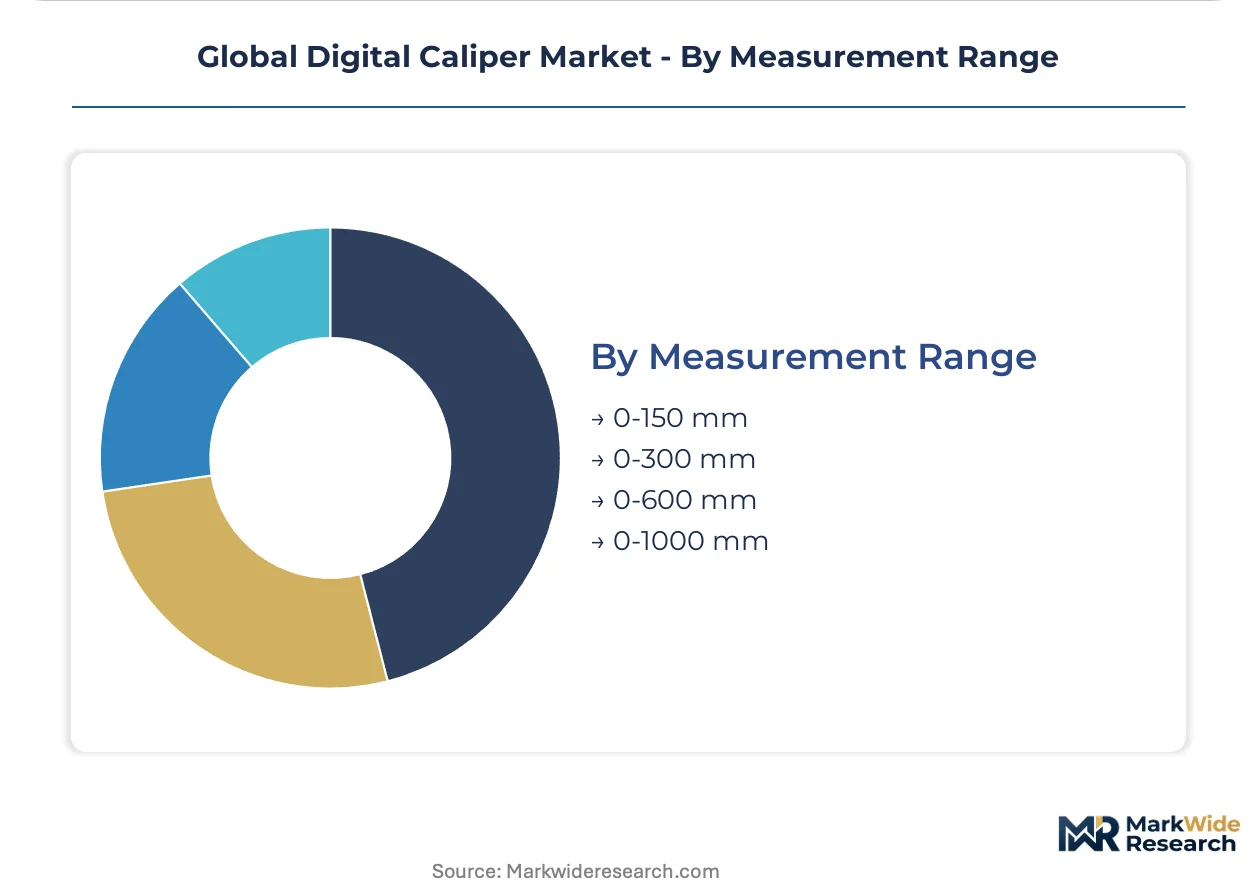
Measurement Range:
Volume concentration sits at mid-range specifications where flexibility meets cost efficiency.
- 0-300 mm:This span captures the broadest end-user base across automotive and electronics fabrication, accommodating most machined components without excessive tool length. Guilin Guanglu Measuring Instrument Co. competes aggressively on cost-engineered units for export markets in this range.
- 0-150 mm:Compact pocket-sized designs serve electronics assembly and medical device fabrication where workspace constraints dominate. Mitutoyo Corp. anchors premium positioning through captive sensor fabrication for high-precision variants.
- 0-600 mm:Extended jaw capacity addresses large-diameter shafting and structural fabrication in heavy equipment manufacturing.
- 0-1000 mm:Long-range specialty units serve wind turbine component inspection and shipbuilding applications with limited unit volumes.
The 0-300 mm range commands the dominant share, while 0-150 mm is gaining share fastest through electronics miniaturization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metrology procurement concentrates among precision engineering clusters in Germany, Japan, China, South Korea, and the United States, where ISO 17025-accredited calibration networks anchor buyer decisions.
Germany
Aerospace component manufacturers in Bavaria and Baden-Württemberg are expanding metrology budgets as EU MDR and ISO 17025 requirements tighten for implantable device verification. The KBA enforces dimensional traceability standards for automotive safety-critical assemblies. Stuttgart's precision engineering corridor drives premium instrument procurement for powertrain fabrication.
Japan
Orthopedic instrument clusters in the Kansai region specify RFID-tagged calipers for EU MDR-compliant quality systems. METI oversees JIS B 7507 standardization that shapes domestic manufacturing footprints. Nagoya's automotive supplier ecosystem maintains calibrated dimensional records under ISO/TS 16949 protocols for export markets.
China
Electronics contract manufacturers in Guangdong province are driving replacement cycles for Bluetooth-enabled measurement tools as paperless inspection workflows become standard. GB/T standards create divergent certification paths from Western regulatory frameworks. Shenzhen's precision machining clusters treat wireless metrology equipment as operational technology with multi-year service agreements.
South Korea
Semiconductor packaging facilities in Gyeonggi province demand sub-millimeter repeatability in cleanroom environments. MFDS regulations mandate validated measurement systems for medical device component suppliers. Seoul's electronics fabricators are unbundling after-sales service contracts, negotiating hardware acquisition separately from calibration and software subscriptions.
United States
Tier-one automotive suppliers in the US Midwest deploy Bluetooth-enabled calipers at scale to satisfy NHTSA traceability mandates for safety-critical dimensions. FDA 21 CFR Part 820 quality system regulations compel calibrated dimensional records in orthopedic and surgical instrument fabrication. Michigan's automotive supplier clusters compress inspection-to-release cycles through real-time statistical process control integration.
Global Digital Caliper Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Premium-tier vendors leverage captive sensor fabrication and calibration laboratory networks to defend margin positions. Mid-tier assemblers compete aggressively on cost-engineered units for export markets. Volume-tier suppliers serve price-sensitive maintenance and education segments with mechanical alternatives. Strategic moves concentrate on CAD-CAM software integration and geographic expansion through third-party laboratory partnerships.
Among Japanese precision instrument specialists, Mitutoyo Corp. anchors the premium tier through captive supply of encoded scales. Hexagon AB represents the software-hardware convergence archetype, embedding measurement outputs directly into quality management loops. Guilin Guanglu Measuring Instrument Co. Ltd. occupies a position within the cost-engineered export tier, competing aggressively on 0-150 mm and 0-300 mm units for global markets.
| Leading Market Players |
|---|
| Mitutoyo Corp. |
| Hexagon AB |
| The L.S. Starrett Co. |
| Fowler High Precision Inc. |
| Guilin Guanglu Measuring Instrument Co. Ltd. |
| HELIOS-PREISSER GmbH |
| Dorsey Metrology International |
| Draper Tools Ltd. |
| Hornady |
| Others |
Supply Flow & Price Mechanics
Japanese and German captive sensor fabrication concentrates upstream encoded scale supply, anchoring margin pools in calibration laboratory networks and ISO 17025-accredited service contracts downstream. Cost compression in China's export-oriented assembly tier feeds back into supplier selection, favoring multi-source capacitive scale procurement over single-source inductive designs.
Pricing Analysis
Cost-plus contracts with rare-earth magnet price indexation dominate Bluetooth-enabled unit procurement, protecting assemblers from neodymium volatility while passing through sensor module fluctuations. Three-tier pricing structure across premium, standard, and economy levels separates Mitutoyo's captive-fabrication tier from Guilin Guanglu's cost-engineered exports and mechanical vernier alternatives. Pricing pressure stems from South Korean electronics fabricators unbundling hardware from calibration subscriptions. Price sensitivity concentrates in China's Guangdong contract manufacturers, while German aerospace suppliers exhibit inelastic demand for EU MDR-compliant traceability.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements for Japanese encoded scale vendors serving Tier 1 automotive assemblers. Manufacturing concentrates in Japan, Germany, and China, with raw material dependencies spanning rare-earth magnets, glass-scale substrates, and lithium coin cells. Single-source vulnerability concentrates in high-precision inductive sensor fabrication, where METI-licensed Japanese suppliers control capacity. Distribution runs through industrial distributors, OEM direct procurement teams, and third-party metrology service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Digital Caliper Market sits in early-cycle recovery as ISO 17025 accreditation mandates force replacement of uncalibrated mechanical instruments across precision manufacturing clusters.
For Market Incumbents: Insulate calibration laboratory networks from margin erosion by embedding RFID-tagged instruments directly into customer ISO 13485 quality management systems. Deepen backward integration into capacitive scale fabrication to offset rare-earth price volatility threatening sensor module costs. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-supported precision engineering corridors, where ISO-certified metrology equipment demand outpaces established vendor presence. Target medical device contract manufacturers facing FDA 21 CFR Part 820 compliance deadlines with subscription-based calibration-included pricing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across Bluetooth-enabled assembly as commoditized sensor modules displace captive fabrication. Five-to-ten year viability favors software-hardware convergence plays with recurring calibration revenue streams. Monitor JIS B 7507 and GB/T regulatory harmonization progress as inflection signal for cross-border manufacturing consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | ISO 17025 accreditation creates recurring revenue moats in German aerospace clusters. |
| Bluetooth Low Energy Module Integration | NHTSA traceability mandates drive hardware refresh cycles in US Midwest automotive. |
| RFID-Tagged Instrument Deployment | EU MDR compliance forces orthopedic instrument manufacturers toward digitized quality loops. |
| Third-Party Metrology Partnership | Electronics fabricators in Gyeonggi province unbundle service contracts from hardware acquisition. |
| Capacitive Scale Fabrication Scale-Up | Cost-engineered 0-150 mm units compete for China's export-oriented contract manufacturing demand. |
Methodological Framework
A standing panel of metrology laboratory directors, precision machining procurement managers, and biomedical quality engineers provided ongoing calibration against secondary data validation. Primary interviews combined with customs trade records, JIS B 7507 certification databases, FDA 483 inspection observations, and SEC equipment supplier filings. Bottom-up shipment data triangulated against top-down industrial instrumentation spend estimates.
Scenario-bracketing framed projections across technology adoption curves, regulatory enforcement intensity, and regional manufacturing incentive programs. Segmentation dimensions spanned product architecture, connectivity protocol, measurement range, and end-use industry vertical. CAGRs derived from fitted diffusion curves applied to replacement cycle analysis and new facility equipment installation rates.
Sensitivities concentrate around ISO 17025 accreditation enforcement timelines, rare-earth magnet supply disruptions, and harmonization between China's GB/T and Japan's JIS standards. Forecasts reflect documented assumptions regarding electronics miniaturization trajectories and automotive safety-critical traceability mandates. Macroeconomic contraction, regulatory deviation, or wireless protocol obsolescence would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Linear Shaft Market
Others
India Battery E-Commerce Market
Others
Smart Home Platforms Market
Others
UK Automotive LED Lighting Market
Others
CAR T Cell Therapy Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
Deep Sea Mining Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
5G Enabled Healthcare Services Market
Others
Document Camera Market
Others
Iran Commercial Vehicles Lubricants Market
Others
ISO Cylinder Market
Others
Mine Rescue Vehicle Market
Others
Sound Reinforcement Market
Others
United States Air Furnaces Market
Others
Blockchain in BFSI Market