
 Asia-Pacific Telecom Transformers Market | 2026-2036
Asia-Pacific Telecom Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Telecom Transformers Market Analytics
Open radio access network (O-RAN) architecture is fragmenting traditional telecom transformer supply chains by decoupling hardware from proprietary software stacks. Mitsubishi Electric Corporation leverages its semiconductor foundry relationships to sustain captive production of gallium nitride components for high-frequency transformer modules. Toshiba Corporation anchors its position through integrated manufacturing of amorphous metal cores at its Yokohama facility. Hitachi Energy Ltd. competes on liquid-immersed transformer designs optimized for tropical humidity conditions across Southeast Asian installations.
Asia-Pacific telecom transformers are electromagnetic devices that step voltage levels between power distribution networks and telecommunications infrastructure, typically operating at frequencies from 50 Hz to several kHz with insulation classes rated for 105°C to 180°C thermal endurance. Their primary purpose is to deliver stable, isolated power to base stations, switching centers, and data processing facilities while suppressing harmonic distortion from non-linear loads. Smart transformers now capture expanding margin pools as telecommunication providers prioritize remote monitoring and predictive maintenance capabilities over passive standalone units. Integrated transformer assemblies lead volume shipments for 5G small cell deployments where space constraints and installation speed outweigh modular flexibility.
China's Ministry of Industry and Information Technology (MIIT) enforces GB standards for energy efficiency in telecommunications power systems, compelling design upgrades across domestic and imported equipment. Japan's Ministry of Economy, Trade and Industry (METI) promotes JIS-certified high-efficiency transformers through feed-in tariff alignment for renewable-powered base stations. India's Central Electricity Authority (CEA) mandates harmonic distortion limits that filter non-compliant transformer suppliers from grid-interconnected telecom installations. Stakeholders must weigh dual-carbon policy trajectories against capital cycle timing as governments across the region tighten efficiency benchmarks faster than equipment replacement schedules.
Market Dynamics
5G network densification across Asia-Pacific is compressing transformer replacement cycles as telecommunication providers prioritize high-efficiency units capable of handling non-linear loads from advanced base station electronics. This structural pressure is reshaping procurement specifications and supplier qualification criteria throughout the regional supply base.
Growth Catalysts
- MIIT Efficiency Mandates:China's GB standards for telecommunications power systems compel domestic and foreign manufacturers to redesign core architectures, accelerating adoption of amorphous metal and advanced ferrite materials.
- Hyperscale Data Center Construction:Coastal Chinese provinces drive demand for integrated transformer assemblies with enhanced thermal endurance ratings suited to high-density computing environments.
- O-RAN Architecture Fragmentation:Open radio access network standards decouple hardware from proprietary software stacks, creating procurement openings for specialized transformer vendors outside traditional supply relationships.
Market Restraints
- Raw Material Concentration:Amorphous metal core production depends on limited Japanese and Chinese foundry capacity, exposing buyers to allocation risk during supply shocks.
- Capital Intensity Barrier:Establishing JIS-certified or BIS-compliant manufacturing lines requires substantial fixed investment, constraining new entrant participation.
- Silicon Steel Substitution Threat:Conventional grain-oriented electrical steel retains cost advantage in price-sensitive Southeast Asian markets, limiting premium transformer penetration.
Strategic Opportunities
- Vietnam and Indonesia Infrastructure Buildouts:These underpenetrated markets present first-mover advantages for suppliers offering tropical-rated liquid-immersed designs.
- Smart Transformer Convergence:Integration of remote monitoring sensors with predictive maintenance platforms captures margin pools from telecommunication providers seeking operational visibility.
- METI Feed-in Tariff Alignment:Japan's renewable-powered base station incentives create demand for high-efficiency transformers compatible with solar and wind input variability.
Industry Challenges
- Amorphous Core Fabrication Expertise Gap:Regional manufacturers face acute shortages of metallurgical engineers capable of optimizing ribbon casting and annealing processes for telecom-grade specifications.
- Dual-Carbon Policy Timing Mismatch:India's CEA harmonic distortion limits and China's dual carbon goals tighten efficiency benchmarks faster than typical 15-20 year equipment replacement schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Telecom Transformers Market |
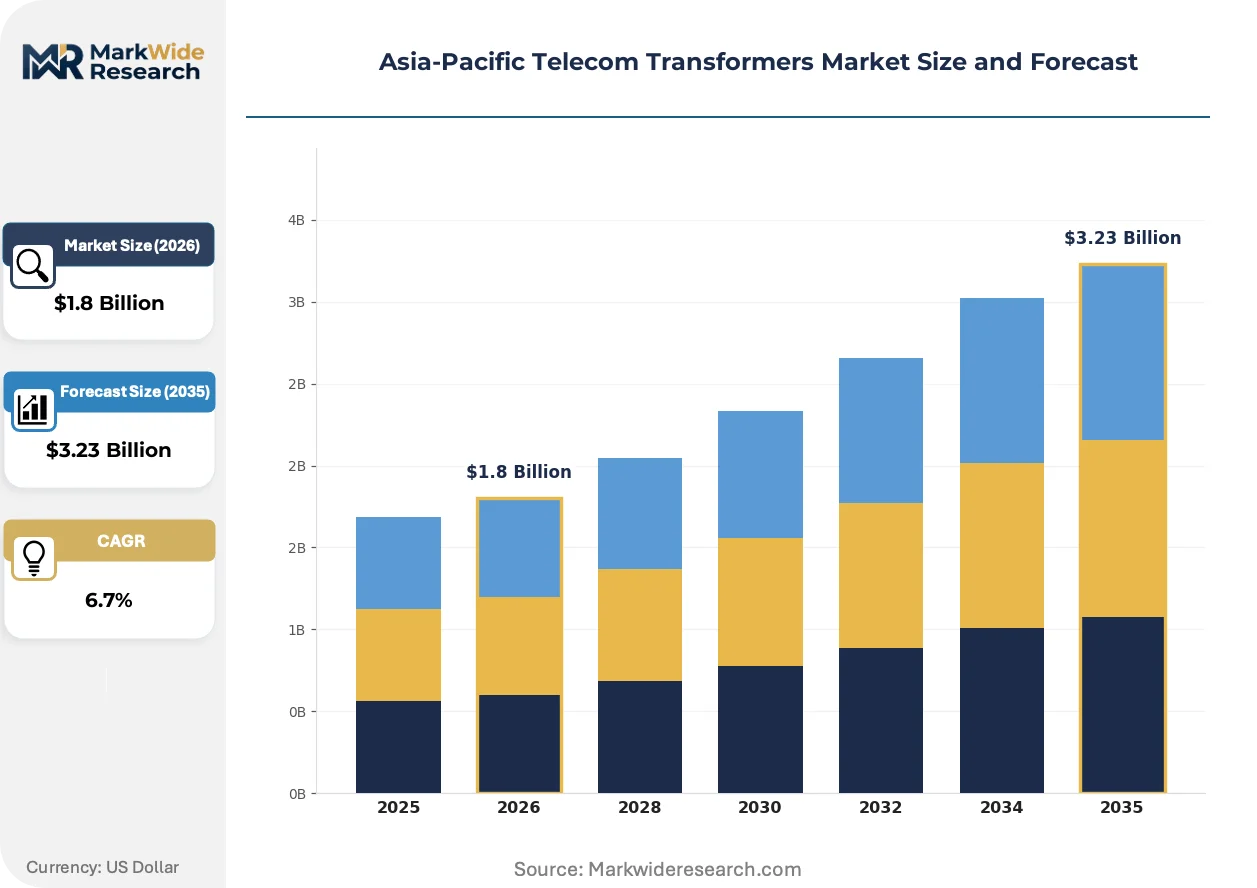
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Transformers, Integrated Transformers, Smart Transformers, Modulating Transformers Energy Source: Solar, Wind, Diesel, Grid Electricity End User: Telecommunication Providers, Internet Service Providers, Data Centers, Enterprises Distribution Channel: Direct Sales, Distributor Resellers, Online Retail, Wholesale |
| Companies Covered | Siemens Energy, Schneider Electric, Mitsubishi Electric Corporation, Eaton Corporation, General Electric, Toshiba Corporation, ABB Ltd., Fuji Electric Co., Ltd., Hitachi Energy Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Telecom Transformers Market Evolving Landscape
Telecom transformer architectures across Asia-Pacific are undergoing fundamental redesign as thermal, electromagnetic, and connectivity requirements converge. Material science advances and embedded intelligence capabilities are redefining supplier value propositions.
Amorphous metal core technology is migrating from niche medical and aerospace applications into mainstream telecommunications infrastructure. Japanese and Korean base station operators now specify amorphous designs for new 5G small cell deployments, valuing core loss reductions of 60-70% over conventional silicon steel. This migration is compressing price premiums for high-efficiency units and forcing incumbent suppliers to reconfigure foundry partnerships.
India's BIS efficiency grade mandates for power distribution equipment are tightening permissible core loss thresholds on a three-year revision cycle. Domestic manufacturers must recertify designs against progressively stricter benchmarks, while importers face technical barrier-to-trade scrutiny at customs clearance. The CEA's harmonic distortion limits compound these pressures by filtering non-compliant suppliers from grid-interconnected telecom installations.
Telecommunication providers now unbundle transformer procurement from turnkey power system contracts, establishing direct supplier relationships for critical components. This disintermediation of traditional electrical contractor channels allows operators to enforce standardized specifications across multi-vendor network deployments. The practice is most visible in China's coastal provinces where hyperscale data center operators maintain approved vendor lists with technical scorecards.
Asia-Pacific Telecom Transformers Market Segmentation
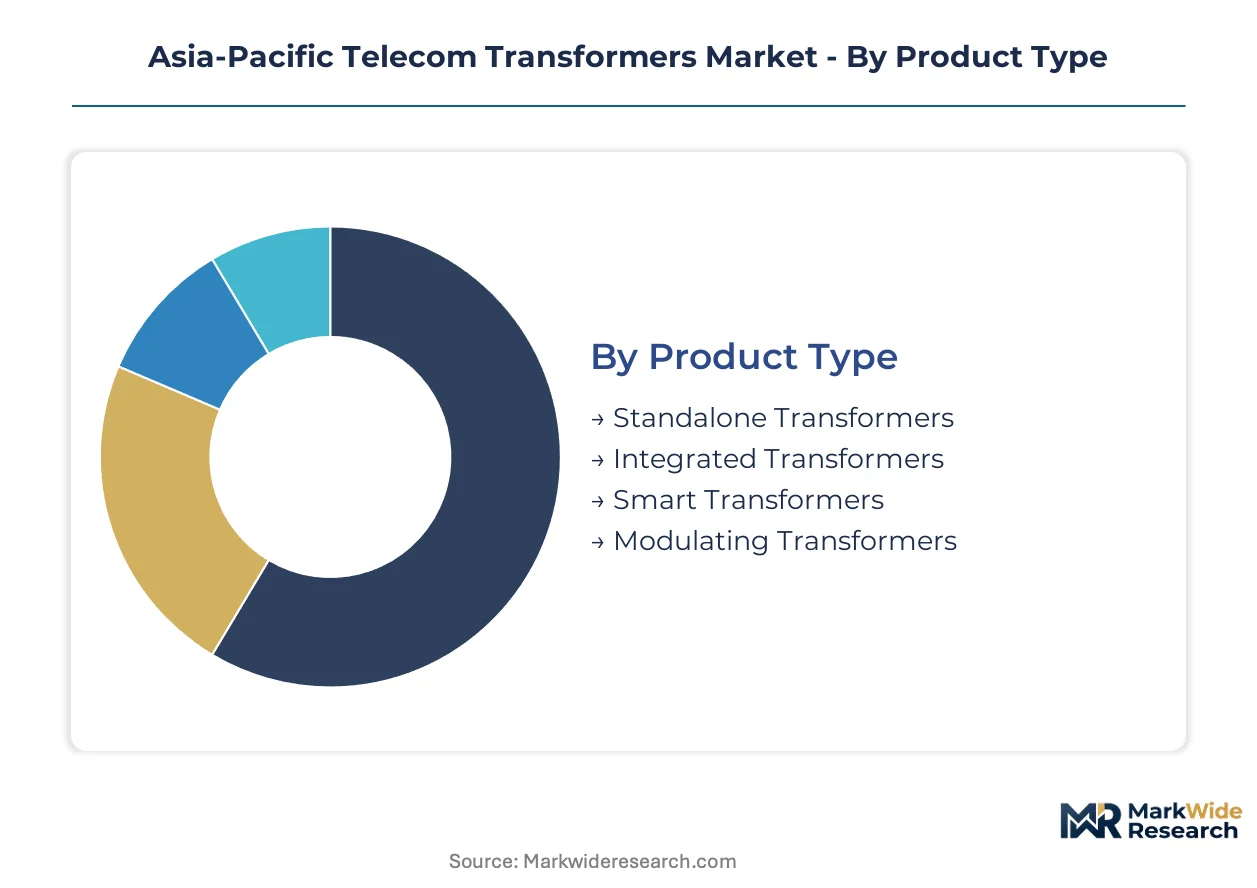
Telecom transformer procurement patterns across Asia-Pacific diverge sharply by deployment context, with 5G infrastructure buildouts, hyperscale data center construction, and renewable-powered base stations each imposing distinct technical specifications on supplier selection.
Product Type:
Cost tier stratification separates passive units from digitally-enabled transformer architectures, with premium pricing attaching to embedded monitoring capabilities and thermal endurance upgrades.
- Standalone Transformers:Conventional electromagnetic designs with fixed voltage ratios serve legacy 4G infrastructure and rural coverage extensions where capital constraints dominate procurement decisions. Demand concentrates in India's tier-3 cities and Indonesian outer islands where BIS and local utility specifications prioritize basic reliability over efficiency premiums.
- Integrated Transformers:Factory-assembled power conditioning units combine transformers with rectifiers, filters, and distribution panels into single enclosures. China's coastal hyperscale data center operators specify these for rapid deployment timelines and space-optimized footprints in Guangdong and Zhejiang provinces.
- Smart Transformers:Embedded sensor arrays enable remote temperature, load, and insulation monitoring through SCADA integration.
- Modulating Transformers:Tap-changing designs accommodate voltage variability from renewable energy inputs.
Standalone transformers hold installed capacity. Smart transformers are rotating up the share rankings.
Energy Source:
Application context determines transformer specification, with grid-interconnected installations facing stricter harmonic distortion limits than off-grid renewable deployments.
- Grid Electricity:Utility-fed installations dominate urban 5G densification projects across Japan, South Korea, and eastern China. CEA harmonic distortion mandates and MIIT efficiency standards compel amorphous core or advanced ferrite designs for all grid-connected telecom transformers in India and China.
- Solar:Photovoltaic-powered base stations require transformers with wide input voltage tolerance and anti-islanding protection. METI feed-in tariff alignment accelerates adoption across Japan's rural coverage obligations, with Hitachi Energy and Toshiba supplying tropical-rated liquid-immersed units for Southeast Asian solar-hybrid installations.
- Wind:Variable frequency inputs from small wind turbines demand robust electromagnetic shielding.
- Diesel:Backup generator integration specifies short-duration overload capacity and rapid voltage stabilization.
Grid electricity retains procurement volume leadership. Solar is gaining share fastest among renewable alternatives.
End User:
Customer type dictates specification authority, with telecommunication providers unbundling component procurement from turnkey contracts while data center operators enforce vendor standardization.
- Telecommunication Providers:Mobile network operators across China, India, and Japan now maintain approved vendor lists for critical power components, bypassing traditional electrical contractor intermediaries. O-RAN architecture fragmentation enables direct supplier relationships for high-frequency transformer modules previously locked into proprietary hardware stacks.
- Data Centers:Hyperscale operators in Singapore, Sydney, and Chinese coastal provinces specify integrated assemblies with 180°C thermal endurance ratings and predictive maintenance compatibility.
- Internet Service Providers:Fixed-line broadband infrastructure requires lower-kVA units with residential-scale noise suppression.
- Enterprises:Private 5G networks and campus installations drive small-batch demand for compact, wall-mountable designs.
Telecommunication providers command legacy procurement volume. Data centers are climbing the fastest in specification influence.
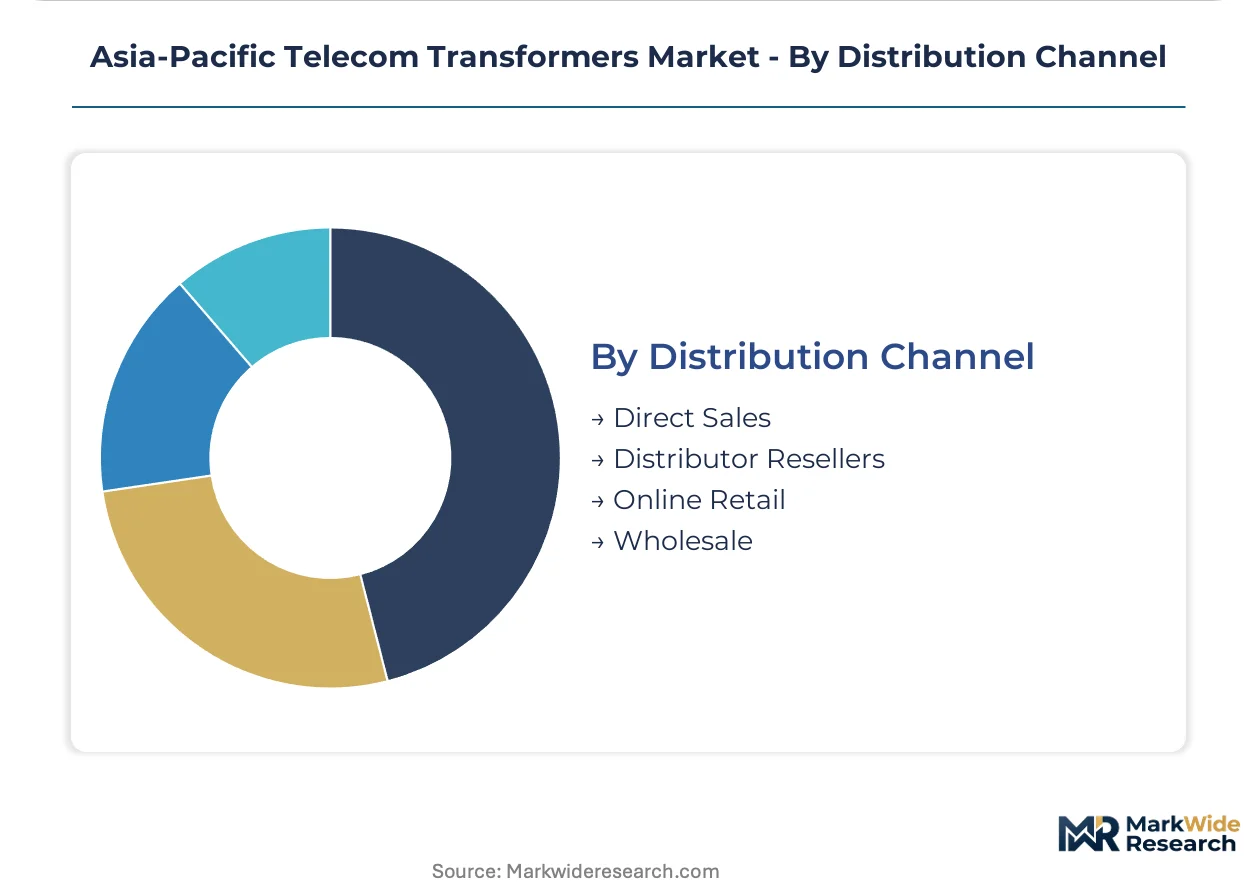
Distribution Channel:
Supply concentration shapes channel strategy, with certification requirements and technical support needs filtering available pathways by customer scale.
- Direct Sales:Manufacturer-direct relationships dominate large-scale deployments where JIS certification, BIS compliance, or MIIT registration requirements demand technical documentation and field engineering support. Mitsubishi Electric and Toshiba anchor direct channels for Japanese and Korean telecommunication providers.
- Distributor Resellers:Authorized electrical distributors serve mid-tier telecommunication providers and regional internet service providers across Southeast Asia, stocking tropical-rated inventory for rapid replacement scenarios.
- Online Retail:E-commerce platforms capture small enterprise and maintenance-replacement volume.
- Wholesale:Volume aggregators supply contractor channels for rural electrification and government-funded coverage programs.
Direct sales holds margin concentration. Distributor resellers are expanding fastest in geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecommunication providers and data center operators concentrate procurement authority in coastal provinces and capital regions where 5G densification and hyperscale construction accelerate transformer replacement cycles. Buyers in these clusters prioritize amorphous core designs and integrated assemblies over conventional silicon steel units.
China
MIIT enforces GB standards for telecommunications power systems that compel domestic and foreign manufacturers toward amorphous metal and advanced ferrite materials. Hyperscale data center construction in Guangdong and Zhejiang provinces reshapes transformer specifications toward 180°C thermal endurance ratings. The Yangtze River Delta anchors procurement volume for integrated assemblies serving rapid deployment timelines.
Japan
METI promotes JIS-certified high-efficiency transformers through feed-in tariff alignment for renewable-powered base stations. Kanto region mobile network operators maintain approved vendor lists for critical power components, bypassing traditional electrical contractor channels. Tokyo-based semiconductor foundry relationships sustain captive production of gallium nitride components for high-frequency modules.
India
BIS mandates stricter efficiency grades for power distribution equipment on a three-year revision cycle, pushing manufacturers toward amorphous core designs. CEA harmonic distortion limits filter non-compliant suppliers from grid-interconnected telecom installations. Maharashtra and Karnataka telecommunication providers unbundle transformer procurement from turnkey power system contracts.
South Korea
Base station operators specify amorphous designs for new 5G small cell deployments, valuing core loss reductions over conventional silicon steel. Seoul Capital Area data center operators enforce standardized specifications across multi-vendor network deployments. Domestic manufacturers face acute shortages of metallurgical engineers capable of optimizing ribbon casting processes.
Vietnam
Tropical-rated liquid-immersed designs from Japanese and Korean suppliers capture first-mover advantages in underpenetrated infrastructure buildouts. Ho Chi Minh City and Hanoi telecommunication providers prioritize rapid replacement inventory stocked by authorized electrical distributors. The country's national telecommunications regulator tightens efficiency benchmarks faster than typical equipment replacement schedules permit.
Asia-Pacific Telecom Transformers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where certification requirements and technical support needs filter supplier participation. The vendor base separates into integrated electrical conglomerates with captive foundry capacity, mid-scale specialists in amorphous core fabrication, and regional distributors holding tropical-rated inventory. Dominant competitive moves include backward integration into semiconductor component supply and geographic expansion through JIS-certified or BIS-compliant manufacturing partnerships.
Within the integrated conglomerate tier, Mitsubishi Electric Corporation and Toshiba Corporation occupy positions anchored by semiconductor foundry relationships and captive amorphous metal core production. Hitachi Energy Ltd. exemplifies the tropical-specialist archetype through liquid-immersed designs optimized for Southeast Asian humidity conditions. These three Japanese entities represent distinct strategic postures: foundry-integrated component supply, materials-captive manufacturing, and climate-adapted product engineering.
| Leading Market Players |
|---|
| Siemens Energy |
| Schneider Electric |
| Mitsubishi Electric Corporation |
| Eaton Corporation |
| General Electric |
| Toshiba Corporation |
| ABB Ltd. |
| Fuji Electric Co., Ltd. |
| Hitachi Energy Ltd. |
| Others |
Value Network & Pricing Analysis
Yokohama's captive amorphous metal foundry capacity anchors regional pricing power for high-efficiency telecom transformers, with Japanese and Korean suppliers commanding premium positioning against Chinese grain-oriented electrical steel competitors. This geographic concentration of advanced core manufacturing creates asymmetric cost structures that downstream buyers navigate through contract structures indexed to raw material volatility.
Pricing Analysis
Cost-plus contracts with amorphous metal ribbon indexation dominate procurement for 5G small cell deployments across Japan and South Korea. Pricing stratifies across JIS-certified premium tiers, BIS-compliant standard grades, and non-certified economy units for Southeast Asian markets. Cost compression in the economy tier intensifies as Chinese silicon steel producers expand foundry partnerships. Data center operators in Guangdong and Zhejiang provinces exhibit lowest price sensitivity, prioritizing 180°C thermal endurance and predictive maintenance compatibility over unit cost.
Supply Chain Analysis
Tokyo-based semiconductor foundries and Yokohama amorphous metal facilities hold captive capacity for gallium nitride components and ribbon-cast cores. Manufacturing draws from Japanese metallurgical expertise, Chinese silicon steel rolling capacity, and Korean ferrite processing. Single-source vulnerability concentrates in amorphous ribbon casting equipment where Hitachi Energy and Toshiba maintain proprietary annealing lines. Distribution runs through direct sales channels for MIIT-registered and JIS-certified volumes, with authorized distributors stocking tropical-rated inventory for Vietnamese and Indonesian replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
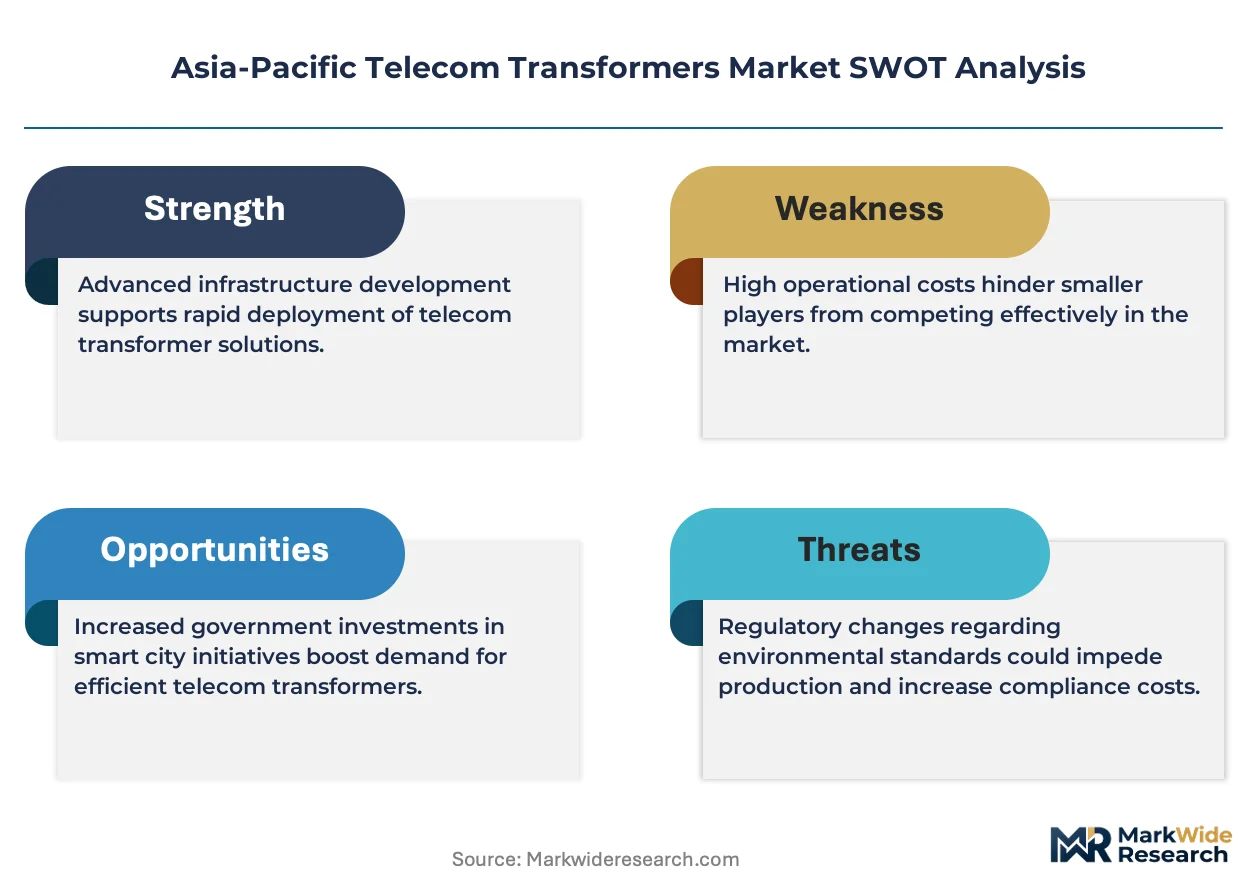
This market functions as a regulatory-entrenchment defensive moat where BIS three-year revision cycles and MIIT GB standard compliance create switching costs that lock qualified suppliers into multi-year procurement relationships.
For Market Incumbents: Entrench position by securing captive amorphous metal foundry partnerships ahead of India's next BIS efficiency grade tightening. Add JIS-certified manufacturing lines in Vietnam to intercept tropical-rated demand from Indonesian infrastructure buildouts. Threat substitution from silicon steel cost advantages in Southeast Asia demands pre-emptive localization of liquid-immersed designs. For New Entrants and Emerging Players: Vietnam's underpenetrated 5G densification programs offer first-mover positioning for suppliers with tropical humidity expertise and rapid replacement inventory. Target Ho Chi Minh City and Hanoi telecommunication providers through authorized distributor relationships rather than direct sales channels. Go-to-market leverage rests on METI-aligned renewable base station compatibility for solar-hybrid installations. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because BIS and MIIT compliance timelines lag equipment replacement schedules by 5-10 years, creating acquisition windows for distressed manufacturing assets. Target mid-scale amorphous core specialists with existing foundry relationships but incomplete geographic coverage. Monitor CEA harmonic distortion limit enforcement as inflection signal for grid-interconnected supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amorphous Metal Foundry | Captive ribbon casting capacity insulates against Japanese and Chinese allocation shocks during supply disruptions. |
| JIS-Certified Manufacturing Partnership | METI feed-in tariff alignment for renewable base stations requires certified transformer compatibility with solar input variability. |
| Smart Transformer Sensor Integration | Embedded SCADA connectivity captures margin pools from telecommunication providers prioritizing predictive maintenance platforms. |
| Tropical-Rated Liquid-Immersed Design Localization | Vietnam and Indonesia's national regulators tighten efficiency benchmarks faster than equipment replacement schedules permit. |
| O-RAN Module Specialist Acquisition | Open radio access network fragmentation decouples hardware procurement from proprietary software stacks, creating vendor openings. |
Research Methodology
A standing panel of telecom power system procurement directors, BIS certification engineers, data center facility managers, and amorphous metal foundry metallurgists provided ongoing calibration against secondary validation from MIIT GB standard filings, CEA harmonic distortion compliance databases, METI feed-in tariff registration records, and customs trade data for transformer core materials. Bottom-up demand modeling across 5G base station deployment schedules triangulated with top-down power infrastructure capex disclosures.
Scenario-bracketing around MIIT efficiency mandate enforcement timelines and BIS revision cycle cadence shaped projections across the analysis window. Segmentation dimensions modeled include product architecture tier, thermal endurance rating, grid-interconnection status, and renewable energy source compatibility. CAGRs derived from equipment replacement cycle compression rates and hyperscale data center construction permits in Guangdong and Zhejiang provinces.
Practitioners should monitor BIS draft standard pre-releases and MIIT GB update announcements for early signals of compliance threshold shifts. Forecasts reflect assumptions regarding amorphous metal price stability and foundry capacity expansion continuity. Quarterly review of CEA enforcement actions and Vietnam national telecommunications regulator efficiency benchmark proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Running Apparel Market
Others
Industrial Personal Computer Market
Others
APAC Smart Home Market
Others
Global Aircraft Lighting Systems Market
Others
Storage Dewars Market
Others
Saudi Arabia Cat Food Market
Others
Global Cosmetovigilance Market
Others
Canada Feed Additives Market
Others
Vacuum Evaporators Market
Others
Transportation Lighting Market
Others
Mini Pcs Market
Others
High-End Servers Market
Others
Calcined Petroleum Coke Market
Others
Mobile Edge Computing Market
Others
Infant Fever Stickers Market
Others
Fiber to the X (Fttx) Tester Market