
 UAE Location-Based Services Market | 2026-2036
UAE Location-Based Services Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Location-Based Services Market Insights
Market Context
Platform bundling of navigation, geofencing, and proximity marketing into unified subscription tiers is recalibrating how UAE retailers and logistics operators procure location intelligence. Google LLC leverages its mapping API ecosystem to anchor enterprise contracts across Dubai's retail sector. TomTom International BV competes through specialized fleet optimization layers designed for Gulf Cooperation Council routing constraints. HERE Technologies extends its position via high-definition mapping partnerships with autonomous vehicle testing programs in Abu Dhabi.
Technical Definition and Segment Structure
Location-based services encompass spatial computing systems that determine device or asset position through GPS satellite triangulation, RFID tag detection, Wi-Fi access point fingerprinting, or Bluetooth beacon proximity, then deliver contextual information, navigation guidance, or automated triggers to end users. The technology serves commercial purposes ranging from supply chain visibility to personalized consumer engagement in physical retail environments. GPS-enabled navigation and tracking solutions dominate service type revenue due to their embedded role in fleet management and ride-hailing platforms across the Emirates. Cloud-based deployment is expanding fastest as telecom providers and hyperscale operators build UAE-based data centers to satisfy data residency expectations. Bluetooth-powered proximity marketing retains niche status but carries above-average margins in luxury retail and hospitality verticals where micro-location precision drives conversion.
Regulatory Framework and Outlook
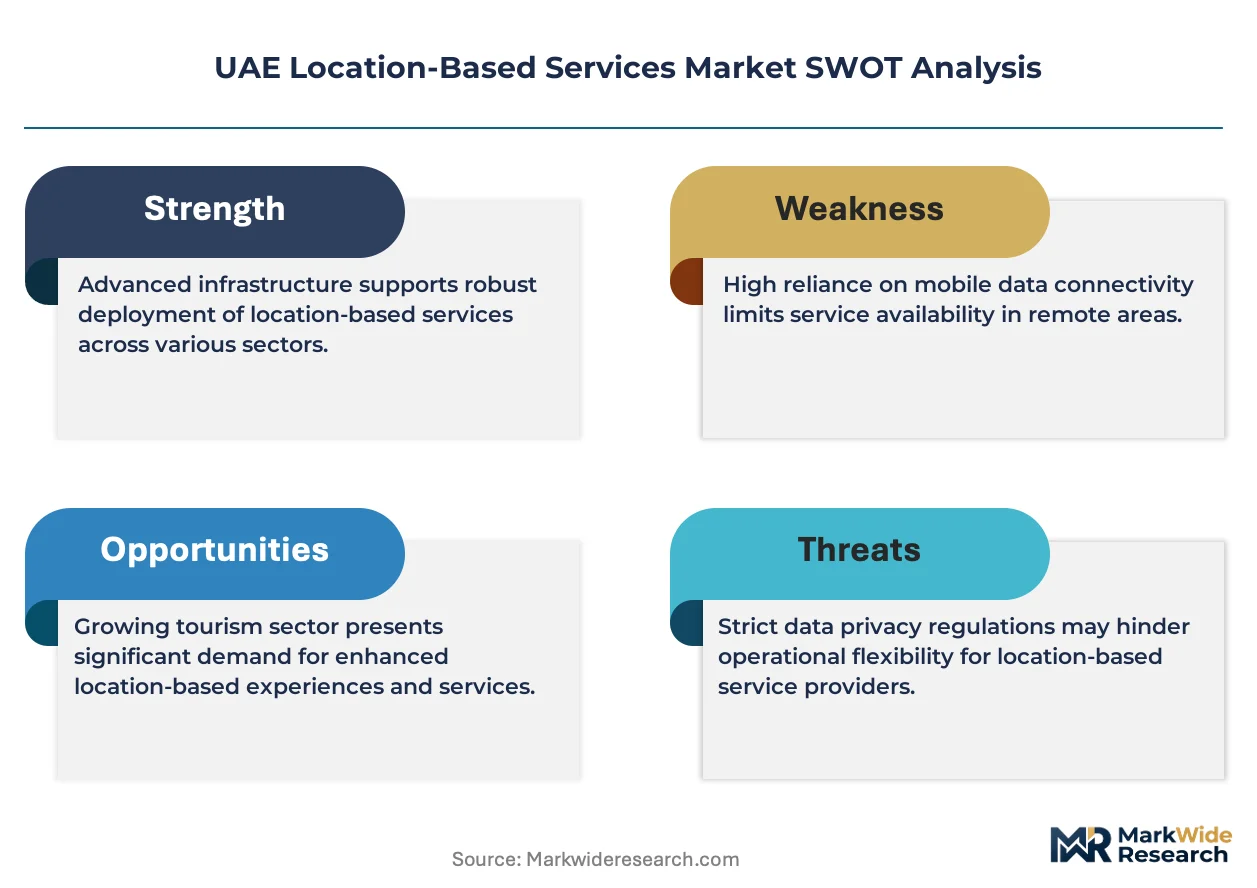
MOHAP governs health data location tracking in clinical and pharmaceutical logistics, while the Telecommunications and Digital Government Regulatory Authority manages spectrum allocation for positioning technologies and IoT networks. The UAE's Personal Data Protection Law imposes geolocation consent requirements that reshape how retailers collect and process consumer movement patterns. Stakeholders must monitor evolving federal standards on cross-border data transfer and emerging Emirate-level smart city procurement rules that increasingly mandate interoperable location data formats.
Market Dynamics
Smart city infrastructure investments across Dubai and Abu Dhabi are compressing procurement cycles for location intelligence platforms as municipal authorities mandate interoperable spatial data standards for logistics and retail operators.
Growth Catalysts
- MOHAP data governance frameworks:Clinical and pharmaceutical logistics operators must deploy compliant location tracking systems for temperature-sensitive cargo, expanding addressable demand for certified fleet visibility solutions.
- Bluetooth beacon density in luxury retail:Malls along Sheikh Zayed Road are installing micro-location infrastructure to enable proximity-triggered personalization, driving above-margin service contracts.
- Port automation mandates:Dubai's logistics corridor requirements for sub-meter container positioning are pulling through high-precision GPS and RTK correction service subscriptions.
Market Restraints
- Data residency compliance costs:The Personal Data Protection Law requires UAE-based cloud infrastructure, forcing operators to abandon lower-cost hyperscale regions and absorb 15-25% hosting premiums.
- Spectrum allocation bottlenecks:The Telecommunications and Digital Government Regulatory Authority's controlled release of IoT positioning bands limits network densification timelines for indoor navigation providers.
- Technical limitation of Wi-Fi fingerprinting:Signal instability in steel-frame warehouse environments forces fallback to more expensive UWB installations, compressing margins for mid-tier logistics contracts.
Strategic Opportunities
- Autonomous vehicle testing zones:Abu Dhabi's high-definition mapping partnerships with automotive OEMs create captive demand for centimeter-accuracy road geometry data and dynamic layer updates.
- Sharjah's underpenetrated retail corridor:Lower beacon saturation in secondary Emirates offers first-mover positioning for unified navigation and loyalty platform bundling.
- Convergence of 5G positioning and AI routing:Telecom operators are piloting network-based location services that bypass device GPS dependency, opening subscription models for asset-light fleet operators.
Industry Challenges
- Geospatial data science talent scarcity:The shortage of engineers skilled in sensor fusion algorithms and RTK network management is extending implementation timelines for sub-meter accuracy deployments.
- Integration complexity with legacy WMS:Warehouse management systems lacking API-native architectures require expensive middleware development to ingest real-time location feeds, delaying ROI realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Location-Based Services Market |
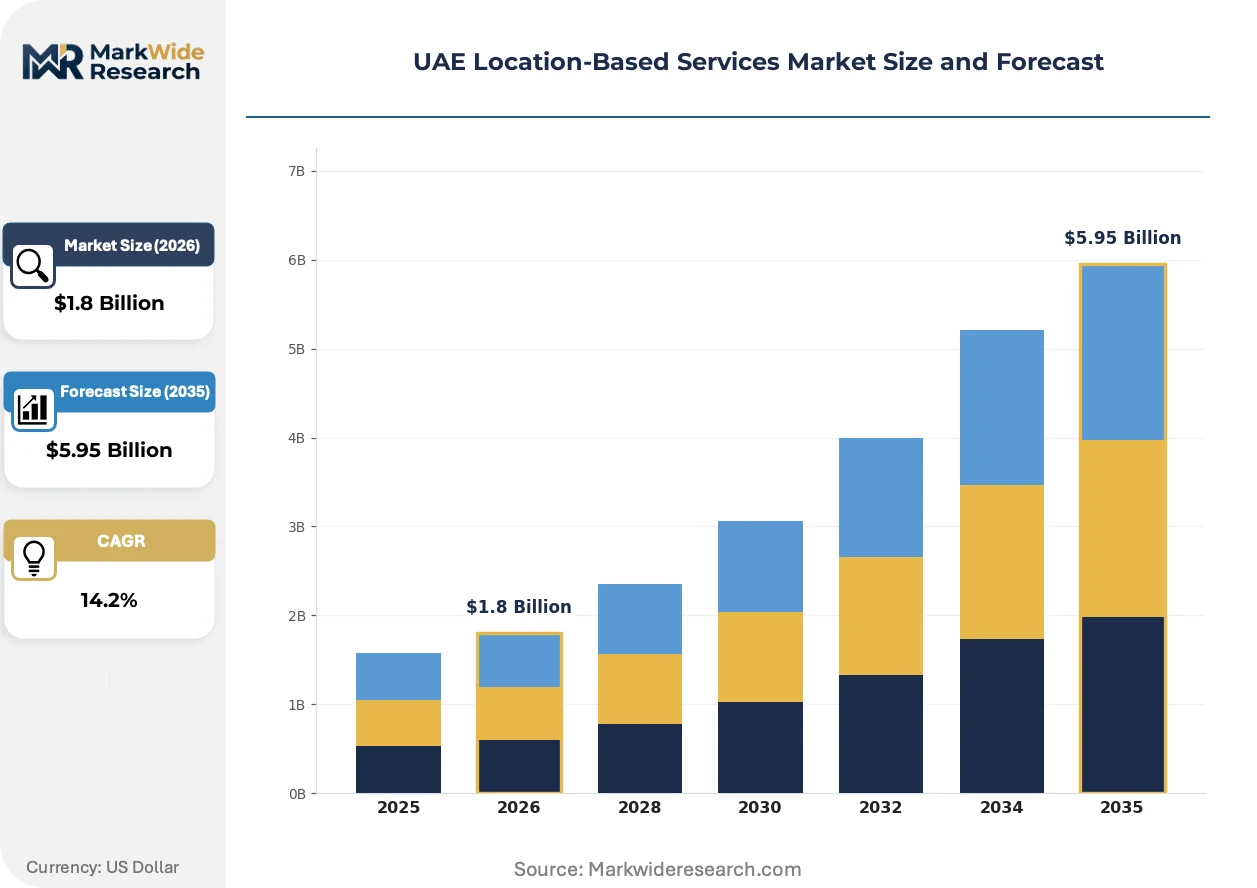
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Navigation, Tracking, Geofencing, Proximity Marketing Technology: GPS, RFID, Wi-Fi, Bluetooth End User: Retailers, Logistics, Tourism, Transportation Deployment: Cloud-Based, On-Premise, Hybrid, Mobile |
| Companies Covered | Google LLC, Location Solutions Telemetics LLC, TomTom International BV, GapMaps, ALE International, Cisco Systems Inc., Esri, Zebra Technologies Corp, HERE Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Location-Based Services Market Trends and Innovations
Edge computing architectures are redistributing location processing from centralized clouds to on-premise gateways, enabling millisecond-latency geofencing triggers for time-critical logistics operations while reducing data transfer volumes subject to residency compliance.
Ultra-wideband chipsets are decentralizing indoor positioning infrastructure ownership. Retail and hospitality operators in Dubai Mall and Yas Island entertainment districts are deploying private UWB anchor networks rather than subscribing to carrier-managed beacon services. This shift compresses recurring platform fees while transferring hardware refresh burdens to facility owners.
The Personal Data Protection Law's geolocation consent requirements are restructuring consumer data collection architectures. Retail chains must now deploy explicit opt-in interfaces at store entry points, with MOHAP auditing compliance through mystery shopper programs. Luxury brands with established loyalty relationships are absorbing this friction more readily than mass-market operators dependent on passive footfall analytics.
Subscription unbundling is fragmenting buyer relationships. Large logistics operators in Jebel Ali Free Zone are negotiating direct contracts with RTK correction network providers while sourcing navigation software from separate vendors, displacing the bundled platform model that dominated procurement through 2024. This pattern is most visible among fleet operators exceeding 500 vehicles with in-house IT integration capabilities.
UAE Location-Based Services Market Segmentation
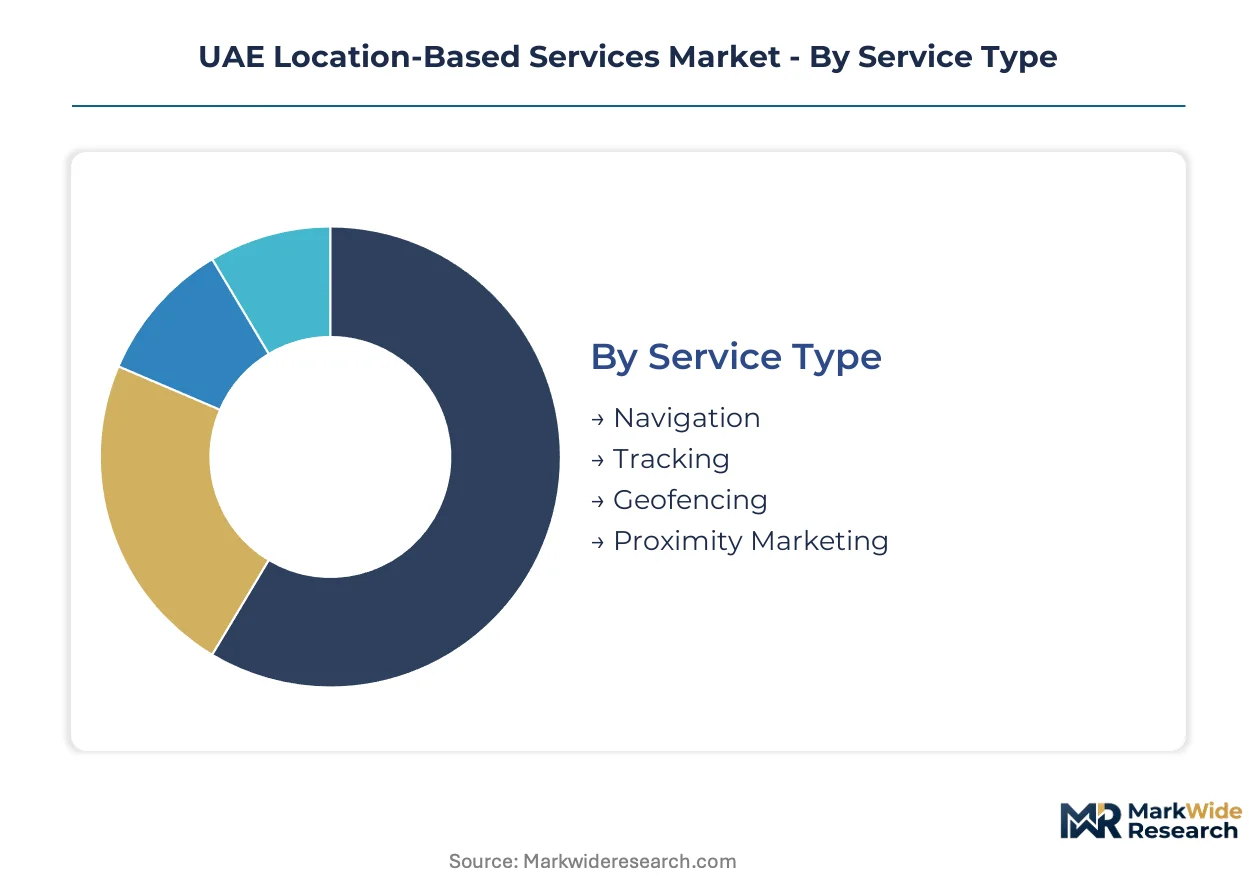
Segmentation in the UAE location-based services market reveals how procurement priorities diverge between precision-dependent logistics operators and engagement-focused retail chains. Upgrade cycles vary dramatically across technology layers, with GPS hardware refreshing every 3-4 years while cloud deployment architectures evolve continuously.
Service Type:
Replacement cycles for location intelligence platforms are compressing as Dubai's smart city mandates force interoperability upgrades across installed bases.
- Navigation:Turn-by-turn routing algorithms integrate real-time traffic feeds from Dubai's RTA infrastructure and Abu Dhabi's integrated transport systems. Fleet operators in Jebel Ali Free Zone demand quarterly map layer updates to accommodate new road geometries from continuous construction activity.
- Tracking:Continuous position monitoring for high-value cargo leverages cellular triangulation backup when GPS signals degrade in Dubai's dense urban canyons. Pharmaceutical distributors under MOHAP jurisdiction require temperature-correlated location logs with audit-ready timestamp granularity.
- Geofencing:Virtual perimeter triggers automate compliance checkpoints for cross-border shipments entering UAE free zones.
- Proximity Marketing:Beacon-triggered promotions in Dubai Mall and Yas Island venues capture micro-moment purchase intent through personalized offer delivery.
Navigation sits at the top of the volume ranking, with Geofencing climbing the fastest as automated compliance workflows expand across logistics corridors.
Technology:
Cost tiers separate satellite-dependent outdoor positioning from infrastructure-heavy indoor alternatives, with hybrid deployments commanding premium pricing.
- GPS:Satellite triangulation delivers 3-5 meter accuracy for fleet management and ride-hailing platforms across Emirates road networks. Dubai's logistics corridor operators are upgrading to RTK-corrected GPS for sub-meter container positioning at Jebel Ali Port.
- Bluetooth:Low-energy beacon networks enable 1-3 meter proximity detection for luxury retail personalization in Sheikh Zayed Road malls. Deployment density in Dubai Mall exceeds 500 beacons per floor, with hardware refresh cycles accelerating to 18 months.
- RFID:Passive tag systems track asset movement through warehouse chokepoints without battery maintenance burdens.
- Wi-Fi:Access point fingerprinting provides coarse indoor positioning where beacon infrastructure remains uneconomical.
GPS dominates current spending, though Bluetooth is gaining share fastest as hospitality and retail verticals densify micro-location infrastructure.
End User:
Application intensity varies by sector, with logistics operators measuring ROI through fuel savings and retailers through conversion lift metrics.
- Logistics:Fleet visibility platforms integrate route optimization, driver behavior scoring, and predictive maintenance alerts for UAE-based 3PL providers. Last-mile delivery platforms in Dubai require sub-30-second location refresh rates to meet customer arrival time expectations.
- Retailers:Unified commerce platforms merge online browsing history with in-store movement patterns to trigger personalized promotions. Luxury brands in Abu Dhabi's Galleria Mall deploy VIP recognition systems that alert staff when high-value customers enter beacon zones.
- Transportation:Public transit operators use passenger flow analytics to optimize bus frequency on high-demand corridors.
- Tourism:Cultural sites and entertainment venues deploy multilingual audio guides triggered by geofenced entry points.
Logistics commands the largest deployment base, while Retailers show the steepest expansion trajectory as unified commerce investments accelerate.
Deployment:
Customer type separates enterprise operators with integration teams from mid-market buyers preferring turnkey SaaS subscriptions.
- Cloud-Based:Hyperscale data centers in Dubai and Abu Dhabi satisfy data residency requirements under the Personal Data Protection Law. Telecom operators Etisalat and du are launching managed location platforms with 99.99% SLA guarantees for critical logistics workloads.
- Hybrid:Edge gateways process sensitive location data on-premise while pushing anonymized analytics to cloud dashboards. This architecture appeals to healthcare logistics operators handling MOHAP-regulated patient data alongside commercial fleet operations.
- On-Premise:Air-gapped installations serve defense and critical infrastructure operators with classified positioning requirements.
- Mobile:Smartphone-native SDKs enable rapid deployment for trial programs without dedicated hardware investment.
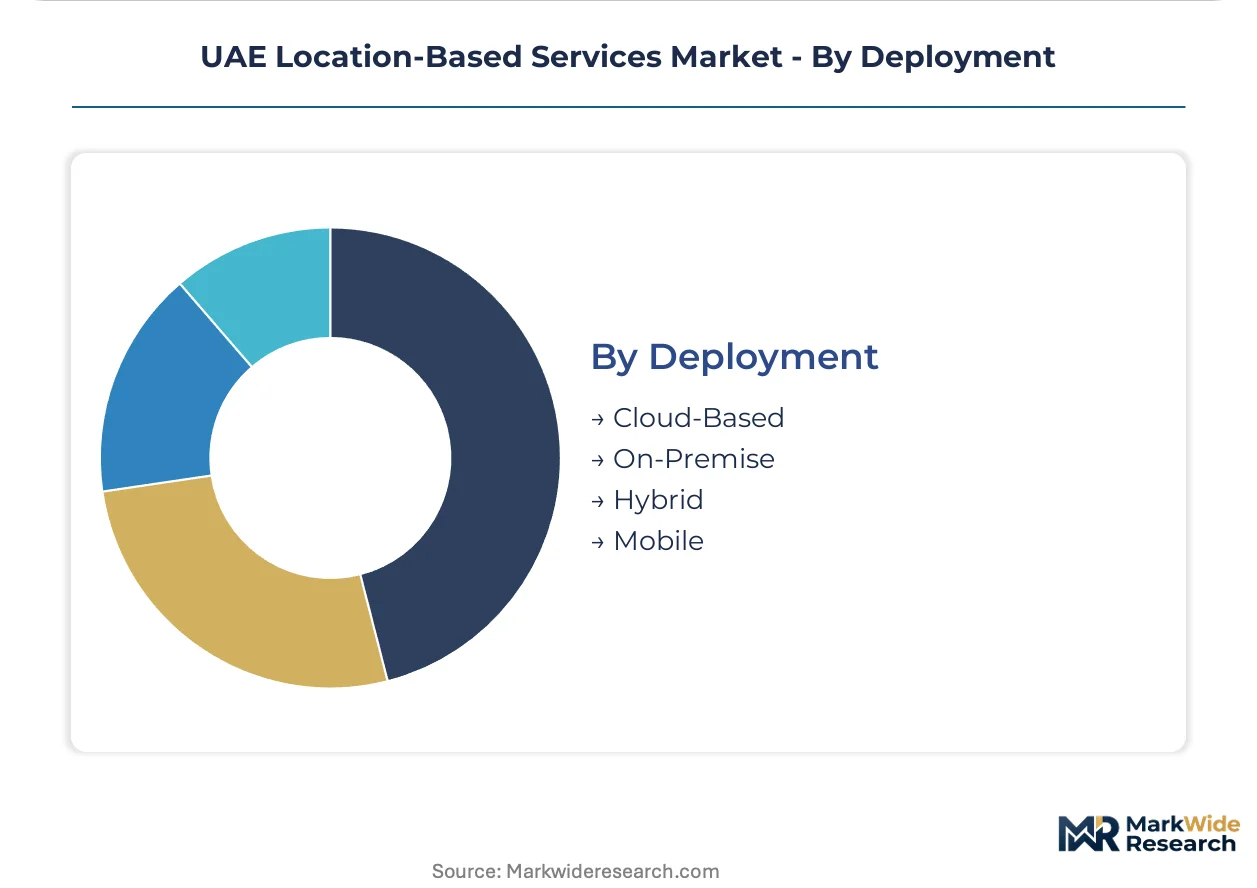
Cloud-Based deployments lead current adoption, with Hybrid architectures expanding most quickly as edge computing investments mature across UAE data center footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Location-based services first achieved commercial scale through GPS navigation deployments in North American and European automotive fleets during the 1990s, with the UAE emerging as a concentrated adoption hub following Dubai's 2014 smart city mandate and subsequent infrastructure digitization programs.
Dubai
Jebel Ali Port automation drives sub-meter GPS correction service demand among container logistics operators. The Telecommunications and Digital Government Regulatory Authority allocates dedicated IoT positioning spectrum for port infrastructure. Dubai South's logistics corridor hosts dense deployments of RTK-enabled fleet management platforms serving last-mile delivery networks.
Abu Dhabi
Autonomous vehicle testing zones generate captive demand for high-definition mapping partnerships with automotive OEMs. MOHAP data governance frameworks mandate location tracking compliance for pharmaceutical cold chain distributors. Masdar City's integrated transport systems require continuous location intelligence for electric shuttle fleet optimization.
Sharjah
Underpenetrated retail corridors offer first-mover positioning for unified navigation and loyalty platform bundling. The Personal Data Protection Law's geolocation consent requirements reshape consumer data collection architectures for emerging mall operators. Sharjah Research Technology and Innovation Park anchors logistics technology pilot programs.
Northern Emirates
Ras Al Khaimah's tourism infrastructure investments deploy multilingual geofenced audio guides at cultural heritage sites. Ajman's growing pharmaceutical manufacturing base requires MOHAP-compliant temperature-correlated location tracking for export cargo. Fujairah's port expansion projects pull through container positioning systems for transshipment operations.
UAE Location-Based Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across precision tiering, with sub-meter accuracy providers commanding 40-60% pricing premiums over standard GPS navigation vendors. The vendor base concentrates around three strategic archetypes: hyperscale mapping platform operators, specialized fleet optimization layer providers, and hardware-integrated positioning system vendors. Dominant competitive moves include high-definition mapping partnerships with autonomous vehicle programs and edge computing infrastructure investments to satisfy data residency requirements.
Within the hyperscale platform tier, Google LLC and HERE Technologies anchor enterprise contract negotiations across Dubai's retail and logistics sectors. TomTom International BV occupies a specialized position through fleet optimization layers designed for Gulf Cooperation Council routing constraints. These three entities exemplify the divergence between bundled subscription models and unbundled procurement patterns now emerging among large fleet operators with in-house integration capabilities.
| Leading Market Players |
|---|
| Google LLC |
| Location Solutions Telemetics LLC |
| TomTom International BV |
| GapMaps |
| ALE International |
| Cisco Systems Inc. |
| Esri |
| Zebra Technologies Corp |
| HERE Technologies |
| Others |
Pricing and Supply Chain Analysis
Captive cloud infrastructure investments by Etisalat and du anchor supply positioning for UAE-based location services while simultaneously constraining pricing flexibility for mid-tier logistics operators facing Personal Data Protection Law compliance premiums. Horizontal partnerships between RTK correction network providers and hyperscale mapping platforms concentrate procurement leverage among fleet operators exceeding 500 vehicles, fragmenting buyer power across the remaining long tail.
Pricing Analysis
Subscription bundling across navigation, geofencing, and proximity marketing tiers dominates enterprise procurement in Dubai's logistics corridor. Price differentiation rests on accuracy certification—sub-meter RTK-corrected GPS commands substantial premiums over standard 3-5 meter satellite positioning—and data residency guarantees under MOHAP frameworks. Cost compression in mid-tier cloud deployments is intensifying because hyperscale operators must absorb 15-25% hosting premiums for UAE-based infrastructure. Mass-market retailers dependent on passive footfall analytics exhibit highest price sensitivity; luxury hospitality operators with established loyalty programs absorb compliance friction more readily.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale fleet operator demand while telecom-managed platforms serve mid-market buyers lacking in-house integration teams. Hardware supply concentrates in Taiwan for UWB chipsets, South Korea for cellular positioning modules, and the Netherlands for specialized RTK base station equipment. Component dependencies include high-precision GNSS receivers, edge computing gateways, and Bluetooth Low Energy beacon arrays. Single-source vulnerability runs through Taiwan Semiconductor's advanced node production for positioning system-on-chips. Distribution runs through Etisalat and du's managed service portfolios, supplemented by direct vendor relationships with Jebel Ali Free Zone logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE location-based services market functions as a regulatory compounder where MOHAP data governance frameworks and Personal Data Protection Law mandates continuously expand compliant solution demand across pharmaceutical logistics and retail verticals.
For Market Incumbents: Anchor defensive positioning through high-definition mapping partnerships with Abu Dhabi autonomous vehicle testing programs, locking in multi-year data refresh commitments. Deepen backward integration into edge computing gateway manufacturing to capture hardware margins currently leaking to Taiwanese suppliers. Certification investment in MOHAP-audited temperature-correlated tracking systems creates switching costs against emerging cloud-native entrants.
For New Entrants and Emerging Players: Launch via Sharjah's underpenetrated retail corridor where beacon saturation lags Dubai Mall and Yas Island benchmarks by 60-70%. Target unified navigation-loyalty platform bundling for mid-tier mall operators lacking IT integration capabilities. White-space concentration in hybrid cloud-edge deployments for healthcare logistics operators handling both MOHAP-regulated patient data and commercial fleet operations offers lowest competitive density.
For Investors and Strategic Acquirers: Roll-up economics work for specialized RTK correction network providers because subscription unbundling among large fleet operators fragments procurement relationships and creates captive customer bases. Five-to-ten year viability hinges on 5G positioning convergence displacing device-dependent GPS architectures. Acquisition target archetype: sub-meter accuracy specialists with existing MOHAP certifications and Jebel Ali Port reference deployments. Watch telecom operator capex disclosures for network-based location service pilots as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Definition Mapping Partnership | Abu Dhabi autonomous vehicle testing zones create captive demand for centimeter-accuracy road geometry data. |
| Edge Computing Infrastructure Investment | On-premise gateway deployments satisfy Personal Data Protection Law residency requirements while reducing latency. |
| MOHAP Certification Acquisition | Audit-ready temperature-correlated tracking systems expand addressable market in pharmaceutical cold chain logistics. |
| 5G Positioning Pilot Program | Telecom operator network-based location services bypass device GPS dependency for asset-light fleet operators. |
| Sharjah Retail Corridor Expansion | First-mover positioning in underpenetrated mall infrastructure captures unified commerce platform bundling opportunities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors at Jebel Ali Free Zone 3PL providers, MOHAP compliance officers, retail technology procurement leads at Dubai Mall anchor tenants, and RTK network engineering specialists. Secondary validation drew from Telecommunications and Digital Government Regulatory Authority spectrum allocation filings, Dubai South logistics corridor infrastructure disclosures, hyperscale data center capex announcements by Etisalat and du, and smart city procurement documentation from Dubai's Roads and Transport Authority. Bottom-up service provider revenue estimates triangulated against top-down addressable market calculations across logistics, retail, and transportation verticals.
Segment-weighting approaches distributed value projections across service type, technology layer, end-user vertical, and deployment architecture dimensions. Navigation, tracking, geofencing, and proximity marketing service categories carried differential growth assumptions based on smart city mandate enforcement timelines. Cloud-based, hybrid, on-premise, and mobile deployment models reflected data residency compliance cost differentials under Personal Data Protection Law frameworks. CAGRs derived from elasticity modeling against infrastructure investment cycles and regulatory compliance deadline clustering. Industry-specific inputs included port automation procurement schedules, pharmaceutical cold chain expansion plans, and autonomous vehicle testing zone mapping refresh requirements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under spectrum allocation delays by the Telecommunications and Digital Government Regulatory Authority or accelerated 5G positioning substitution effects. Periodic stress-testing of base assumptions is recommended, particularly around MOHAP audit enforcement intensity and hyperscale cloud infrastructure commissioning timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Military 4D Printing Market
Others
Internet Protocol Television (IPTV) Market
Others
Conditional Access System (CAS) Market
Others
Bicycle Panniers Market
Others
China 3D Printing Construction Market
Others
Liquid Density Meters Market
Others
Military 4D Printing Market
Others
Japan Indoor LBS Market
Others
Europe Electric Forklift Market
Others
Global Food Fiber Market
Others
Mobile Computer Market
Others
Diamond Mining Market
Others
Egg and Egg Products Market
Others
Server Market
Others
Bitcoin Mining Hardware Market
Others
Nyerereite Market