
 Middle East and Africa Electric Vehicle Battery Electrolyte Market | 2026-2036
Middle East and Africa Electric Vehicle Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Electric Vehicle Battery Electrolyte Market Insights
Saudi Arabia's giga-scale battery manufacturing investments are reshaping regional electrolyte sourcing dynamics. BASF SE leverages its integrated chemical platform to anchor polymer electrolyte supply chains across the Gulf. Mitsubishi Chemical Group Corporation dominates high-purity lithium salt production for liquid electrolyte formulations. Dubi Chem specializes in regional distribution, controlling import logistics for cell manufacturers in Dubai Industrial City.
Electric vehicle battery electrolyte comprises ion-conducting media—typically lithium hexafluorophosphate dissolved in carbonate solvents for liquid systems, or ceramic-polymer composites for solid-state architectures—that enable lithium-ion transport between anode and cathode during charge and discharge cycles. Liquid electrolytes currently occupy the largest volume share due to established manufacturing scale and compatibility with existing cell formats, though solid electrolytes are gaining structural attention as OEMs target higher energy density thresholds. Passenger cars represent the dominant application segment, while energy storage systems are registering the fastest trajectory as grid-scale battery deployments accelerate across Morocco and Jordan.
Saudi Arabia's dual carbon goals and the UAE's national electric vehicle policy are tightening product standards for thermal stability and flammability, compelling electrolyte suppliers to reformulate additive packages. South Africa's NRCS certification requirements and Egypt's industrial chemical registration protocols further fragment market access procedures across the continent. Stakeholders must monitor how solid-state pilot lines in the UAE and sodium-ion commercialization in North Africa redistribute chemical composition demand before committing to capacity configurations.
Market Dynamics
Electrolyte formulation chemistry is pivoting toward flame-retardant additive packages as Saudi Arabia's dual carbon goals and the UAE's national electric vehicle policy harden thermal stability mandates across the Gulf. This regulatory compression is forcing suppliers to requalify product lines for stricter flammability thresholds.
Growth Catalysts
- Dubai's electric taxi mandates:Fleet electrification targets in the emirate are generating concentrated offtake for high-volume liquid electrolyte contracts. Procurement volumes from taxi operators are pulling forward manufacturing scale.
- Solid-state pilot investments:Abu Dhabi's battery assembly investments are creating demand pull for ceramic-polymer composite electrolyte development. Local cell manufacturers are qualifying next-generation formulations.
- South Africa's renewable energy procurement:Grid-scale battery storage programs are accelerating demand for energy storage system electrolytes. Industrial chemical registration protocols are streamlining import pathways for qualified suppliers.
Market Restraints
- Lithium salt import dependency:High-purity lithium hexafluorophosphate supply concentrates in East Asian chemical processors. Regional cell manufacturers face input cost volatility from currency and freight exposure.
- Carbonate solvent supply fragmentation:Ethylene carbonate and dimethyl carbonate sourcing lacks regional production capacity. Electrolyte blenders absorb working capital strain from extended inventory cycles.
- Sodium-ion chemistry substitution:North African battery projects are piloting sodium-ion cells that eliminate lithium salt electrolytes entirely. This chemistry pivot threatens demand displacement for conventional formulations.
Strategic Opportunities
- Morocco grid-scale storage:Renewable integration targets are creating demand for long-duration battery chemistries with tailored electrolyte specifications. Local industrial zones offer tariff advantages for blending operations.
- Jordan energy storage deployment:Solar-wind hybrid projects are procuring battery systems with specialized electrolyte thermal profiles. The market remains underpenetrated by regional suppliers.
- Egypt industrial chemical registration reform:Streamlined import protocols are reducing time-to-market for electrolyte additive packages. Early entrants are securing preferred supplier status with local cell assemblers.
Industry Challenges
- Electrochemist talent scarcity:Formulation expertise for solid-state interface engineering remains concentrated in East Asian and European research centers. Regional universities lack specialized battery chemistry programs.
- Multi-jurisdiction certification complexity:Saudi SFDA chemical safety assessments, UAE MOHAP industrial registrations, and South Africa NRCS certification requirements create overlapping compliance timelines. Product launch schedules extend across sequential approval stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Electric Vehicle Battery Electrolyte Market |
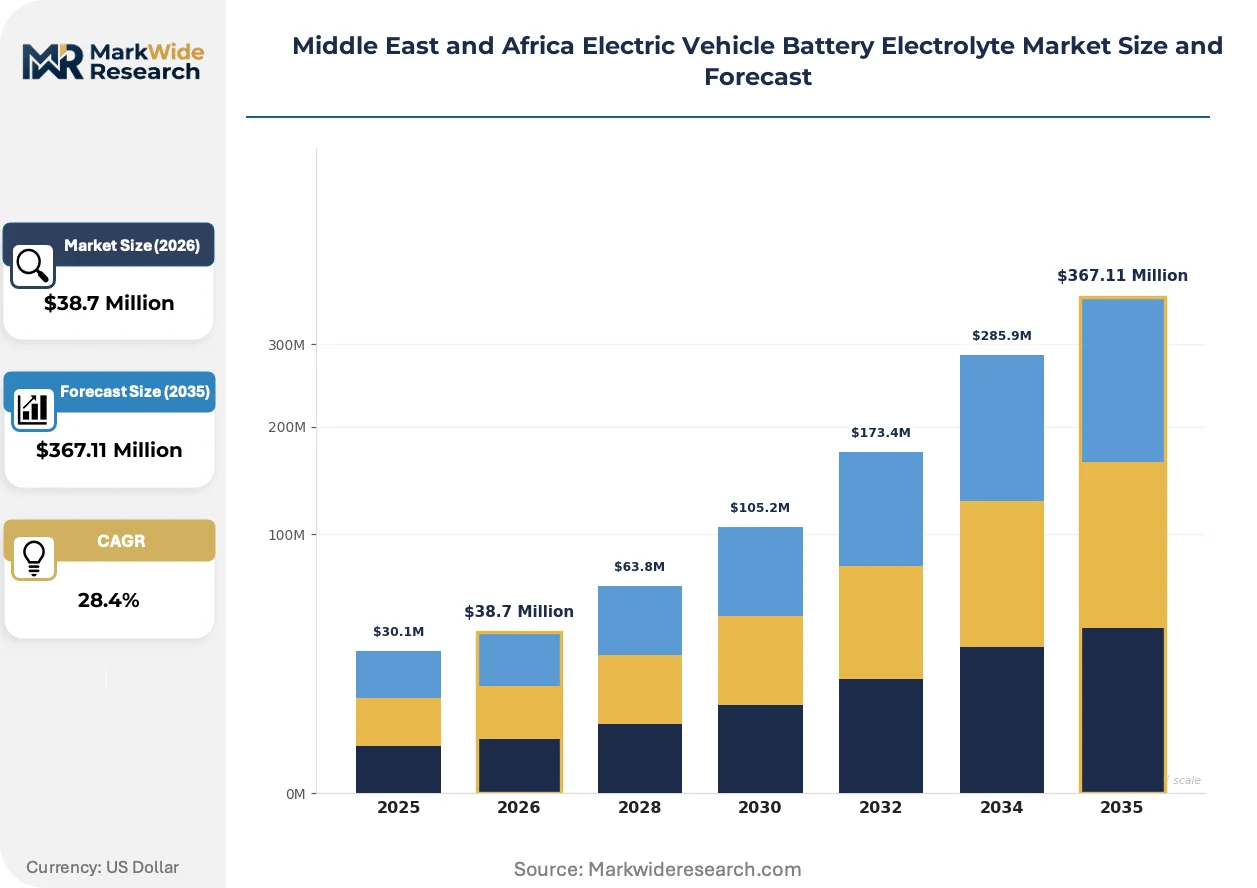
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $367.11 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Electrolytes, Solid Electrolytes, Gel Electrolytes, Polymer Electrolytes Application: Passenger Cars, Commercial Vehicles, E-Bikes, Energy Storage Systems Chemical Composition: Lithium Ion, Sodium Ion, Hybrid, Others Distribution Channel: Direct Sales, Online Sales, Retail Stores, Distributors |
| Companies Covered | Dubi Chem, Oasis Chemical Materials Trading Co, Targray Technology International, Inc., Andrea FZCO, Rekoser, Middle East Battery Company, BASF SE, Mitsubishi Chemical Group Corporation, SGL Carbon, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Electric Vehicle Battery Electrolyte Market Trends and Innovations
Electrolyte technology trajectories are diverging between incremental liquid formulation refinement and disruptive solid-state architecture development. This bifurcation is fragmenting R&D investment patterns and supplier capability requirements across the region.
Solid-state ceramic-polymer composite electrolytes are virtualizing conventional liquid electrolyte demand structures in the UAE's pilot manufacturing lines. Abu Dhabi-based cell assemblers are integrating these materials into prototype pouch cells for electric bus applications. The technology is virtualizing established supply relationships by requiring direct partnerships with ceramic powder processors rather than traditional chemical distributors.
Saudi Arabia's dual carbon goals are tightening product standards for thermal runaway propagation resistance. Electrolyte suppliers must now submit additive packages for accelerated aging validation under Gulf-standard climate conditions. Passenger car OEMs in the Kingdom are prioritizing formulations with phosphate-based flame retardants over conventional carbonate blends.
Fleet operators across Dubai and Riyadh are consolidating electrolyte procurement through long-term supply agreements with cell manufacturers rather than independent chemical distributors. This channel compression is marginalizing regional trading houses that historically controlled import logistics. The shift is most visible in electric commercial vehicle segments where total cost of ownership calculations favor captive supply arrangements over spot market purchasing.
Middle East and Africa Electric Vehicle Battery Electrolyte Market Segmentation
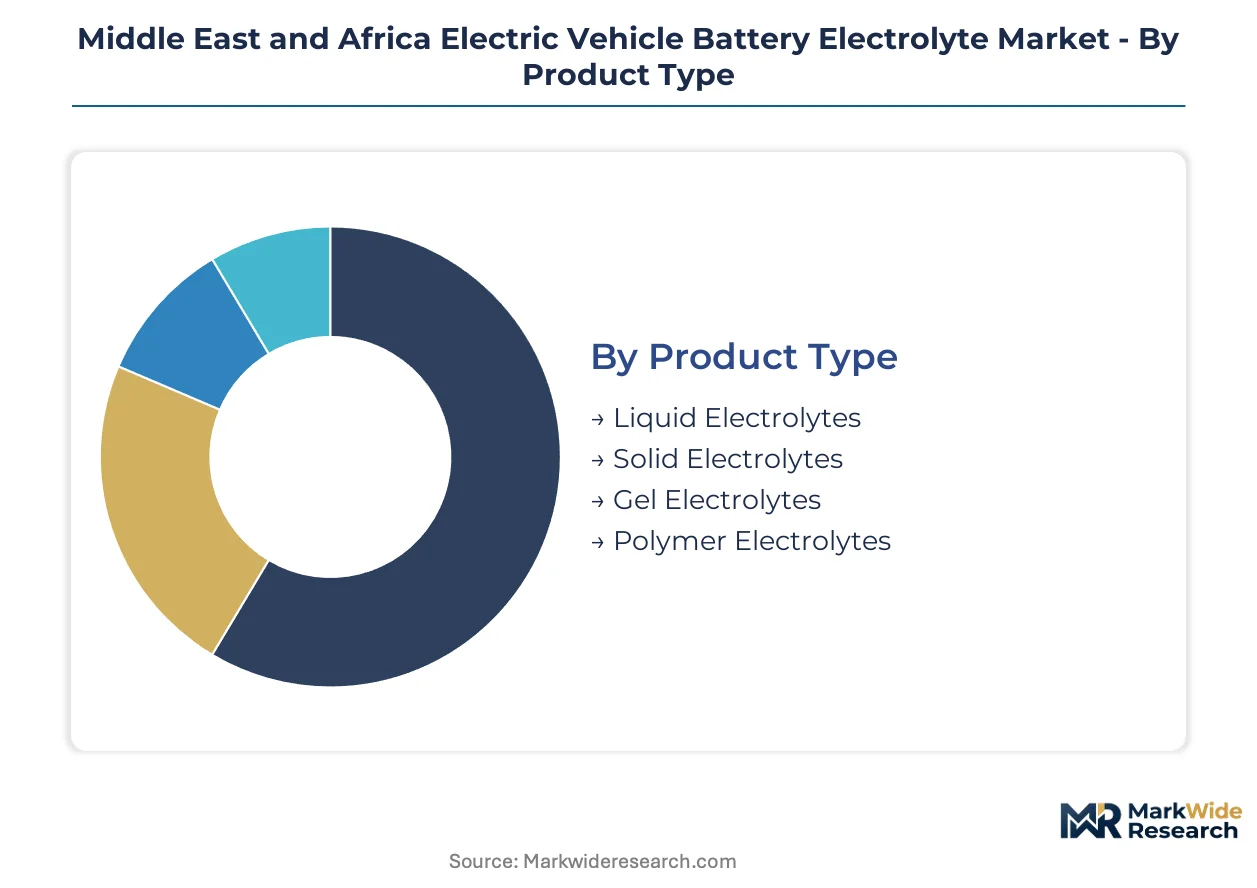
Electrolyte procurement cycles vary dramatically across product types and applications in the Middle East and Africa. Fleet electrification mandates in Dubai and Riyadh are compressing contract timelines for high-volume segments while solid-state pilot programs extend qualification periods.
Product Type:
Cycle times range from immediate spot-market availability for mature liquid formulations to multi-year qualification windows for solid-state materials. Procurement velocity directly correlates with manufacturing maturity and regional blending capacity.
- Liquid Electrolytes:Lithium hexafluorophosphate dissolved in carbonate solvents remains the workhorse formulation. Dubai's electric taxi fleets and Saudi commercial vehicle operators are pulling forward large-volume contracts with 6-12 month procurement cycles. SFDA thermal stability mandates are forcing additive reformulations that extend requalification timelines.
- Solid Electrolytes:Ceramic-polymer composites eliminate flammability risks but require interface engineering expertise. Abu Dhabi's battery assembly investments are creating concentrated demand for pilot-scale supply, though electrochemist scarcity across the Gulf stretches development cycles to 24-36 months.
- Gel Electrolytes:Semi-solid matrices offer intermediate thermal profiles for e-bike and light commercial applications. Moroccan industrial zones are evaluating localized blending operations.
- Polymer Electrolytes:Dry polymer membranes suit pouch cell architectures. UAE MOHAP industrial registrations are streamlining import pathways for specialized grades.
Liquid electrolytes anchor the volume base while solid electrolytes gain share at the steepest rate.
Application:
Cost tier stratification separates premium passenger car specifications from economy-grade energy storage formulations. OEM procurement power concentrates in fleet segments with captive supply arrangements.
- Passenger Cars:Premium formulations with phosphate-based flame retardants dominate Saudi and UAE OEM requirements. Saudi Arabia's dual carbon goals are tightening thermal runaway propagation standards beyond conventional carbonate blends.
- Commercial Vehicles:Electric bus operators in Dubai and Riyadh are consolidating procurement through direct cell manufacturer partnerships. Total cost of ownership calculations favor long-term supply agreements over distributor channels.
- E-Bikes:Price-sensitive demand concentrates in North African urban mobility markets. Egypt's industrial chemical registration reforms are reducing import friction for economy-grade electrolyte packages.
- Energy Storage Systems:Grid-scale deployments across Morocco and Jordan are expanding most quickly. Long-duration battery chemistries require tailored electrolyte thermal profiles that differ from automotive specifications.
Commercial vehicles generate the highest contract values while energy storage systems are climbing the fastest.
Chemical Composition:
Supply concentration for lithium salts in East Asian processors creates input cost volatility that sodium-ion alternatives are exploiting. Chemistry selection increasingly reflects raw material security rather than pure performance optimization.
- Lithium Ion:Established supply chains and cell manufacturing compatibility sustain dominance. Currency exposure on hexafluorophosphate imports remains a structural cost pressure for regional blenders.
- Sodium Ion:Eliminates lithium dependency entirely. North African battery projects are piloting cells with alternative electrolyte formulations that bypass conventional salt supply chains.
- Hybrid:Dual-chemistry architectures balance performance and cost. South Africa's renewable energy procurement programs are evaluating mixed compositions for grid storage.
- Others:Experimental chemistries including potassium-ion and aluminum-ion remain pre-commercial. Regional universities lack specialized battery chemistry programs to advance local development.
Lithium ion retains the installed base while sodium ion is expanding most quickly in new project development.
Distribution Channel:
Customer type fragmentation separates institutional fleet procurement from fragmented retail demand. Channel compression is marginalizing traditional trading houses as direct manufacturer relationships deepen.
- Direct Sales:Cell manufacturers and large fleet operators negotiate multi-year supply agreements. Dubai Industrial City assemblers are locking in electrolyte volumes through captive arrangements.
- Distributors:Regional trading houses historically controlled import logistics. Channel compression is restricting their role to smaller blenders without direct supplier relationships.
- Online Sales:Digital procurement platforms serve aftermarket and research quantities. South Africa NRCS certification requirements add compliance complexity to cross-border transactions.
- Retail Stores:Limited to specialty chemical suppliers serving R&D and pilot-scale buyers. Physical presence concentrates in Jeddah and Johannesburg industrial districts.
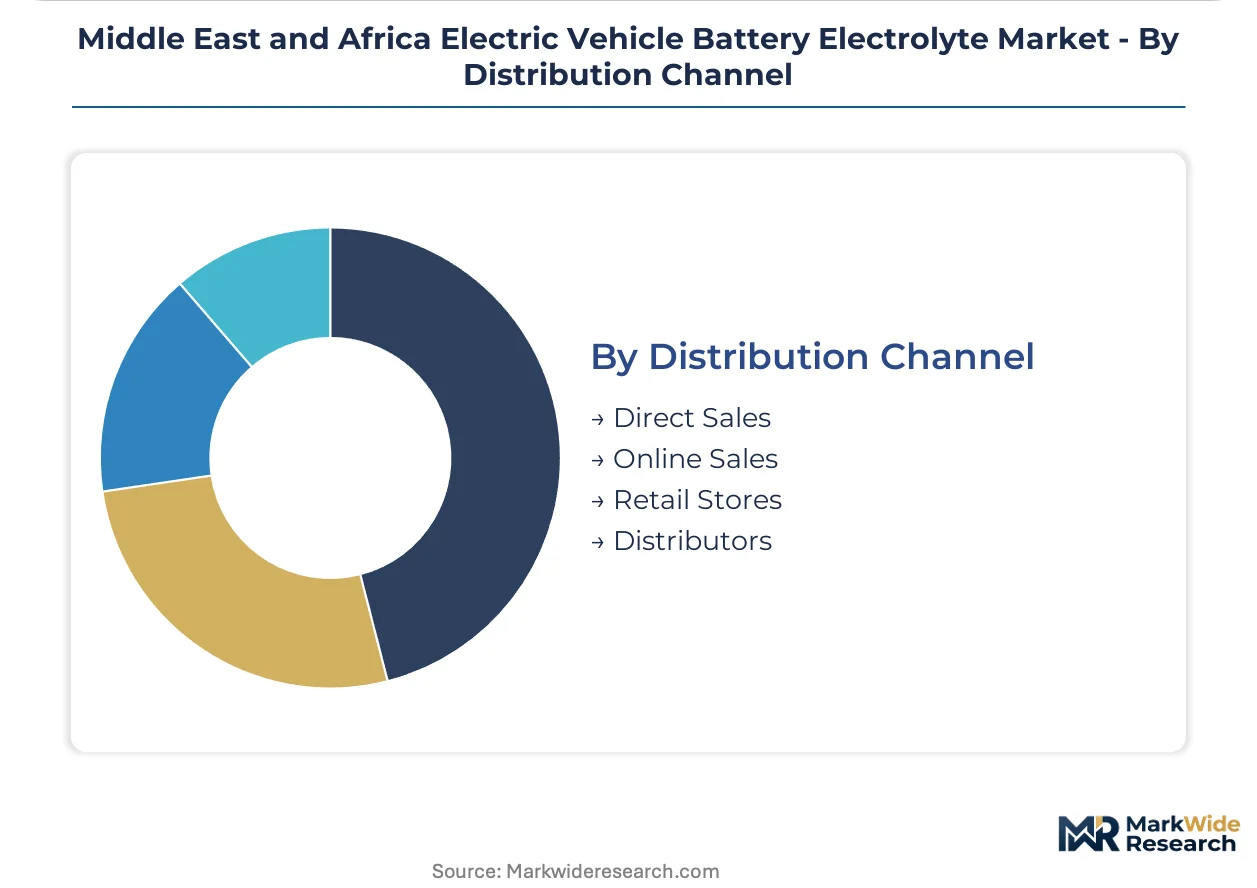
Direct sales command the contract value while distributor influence is contracting fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrolyte blending capacity concentrates in Gulf industrial zones where petrochemical feedstock access and port logistics converge. Saudi Arabia and the UAE anchor regional supply, while North African markets pivot toward sodium-ion alternatives that bypass lithium import dependencies.
Saudi Arabia
Domestic giga-scale battery manufacturing investments are pulling electrolyte formulation demand toward localized production. SFDA thermal stability mandates are tightening additive package requirements for electric commercial vehicles. NEOM's advanced manufacturing zone is attracting polymer electrolyte pilot lines from European chemical groups.
United Arab Emirates
Dubai's electric taxi fleet mandates are generating concentrated offtake for high-volume liquid electrolyte contracts. MOHAP industrial registrations are streamlining import pathways for specialized electrolyte grades. Abu Dhabi's battery assembly investments in Khalifa Industrial Zone are creating demand pull for solid-state ceramic-polymer composite development.
South Africa
Renewable energy procurement programs are accelerating grid-scale battery storage deployments with tailored electrolyte specifications. NRCS certification requirements are fragmenting market access timelines for imported additive packages. Industrial zones around Johannesburg are evaluating localized blending operations to reduce working capital strain from extended inventory cycles.
Morocco
Renewable integration targets are creating demand for long-duration battery chemistries with specialized thermal profiles. The country's national industrial chemical regulator is streamlining registration protocols for qualified suppliers. Tangier Med industrial zone offers tariff advantages for electrolyte blending operations serving European battery assemblers.
Egypt
Urban e-mobility markets are driving price-sensitive demand for economy-grade electrolyte formulations. Industrial chemical registration reforms are reducing time-to-market for additive packages. Cairo's industrial districts are consolidating procurement relationships with regional trading houses that control Red Sea import logistics.
Middle East and Africa Electric Vehicle Battery Electrolyte Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in salt and solvent production. The vendor base spans integrated chemical conglomerates with captive lithium salt supply, regional distributors controlling import logistics, and emerging local blenders serving fleet electrification mandates. Three archetypes dominate: Gulf-based petrochemical platforms with backward integration into carbonate solvents, East Asian lithium salt specialists with purity-grade advantages, and regional trading houses with customs clearance expertise. Competitive intensity centers on qualification speed for evolving thermal stability mandates and captive supply arrangements with cell manufacturers.
Among the integrated chemical platforms, BASF SE and Mitsubishi Chemical Group Corporation anchor the high-purity input tier. Dubi Chem occupies a position within the regional distribution archetype, controlling import logistics for cell manufacturers in Dubai Industrial City. These three exemplify the supply chain configuration where European and East Asian upstream specialists feed Gulf-based blending and distribution operations.
| Leading Market Players |
|---|
| Dubi Chem |
| Oasis Chemical Materials Trading Co |
| Targray Technology International, Inc. |
| Andrea FZCO |
| Rekoser |
| Middle East Battery Company |
| BASF SE |
| Mitsubishi Chemical Group Corporation |
| SGL Carbon |
| Others |
Pricing and Supply Chain Analysis
East Asian lithium hexafluorophosphate processors anchor input costs for Middle East and Africa electrolyte blenders, concentrating margin pools with carbonate solvent traders and regional distributors who control Red Sea and Gulf port logistics. SFDA thermal stability mandates and MOHAP industrial registration fees compound landed costs, pushing pricing power toward integrated chemical platforms with captive salt supply.
Pricing Analysis
SFDA thermal stability mandates dictate the pricing tier structure across the Gulf, separating phosphate-based flame-retardant formulations from conventional carbonate blends. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with Dubai electric taxi fleets absorbing premium tiers while North African e-bike markets gravitate toward economy grades. Cost compression in standard-tier liquid electrolytes is intensifying because currency exposure on East Asian lithium salt imports feeds directly into blender margins. Fleet operators in Riyadh and Dubai exhibit the lowest price sensitivity due to captive supply arrangements, whereas Egyptian urban mobility distributors face acute cost pressure.
Supply Chain Analysis
Tariff exposure between East Asian chemical processors and Gulf blending facilities dominates working capital strain for regional electrolyte distributors. Supply concentrates in China, South Korea, and Japan for high-purity lithium hexafluorophosphate, while carbonate solvents draw from German and Japanese petrochemical complexes. Single-source vulnerability on lithium salt purification creates input cost volatility that sodium-ion pilot projects in Morocco and Egypt are exploiting. Distribution runs through Dubai Industrial City assemblers and Jeddah-based trading houses with customs clearance expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
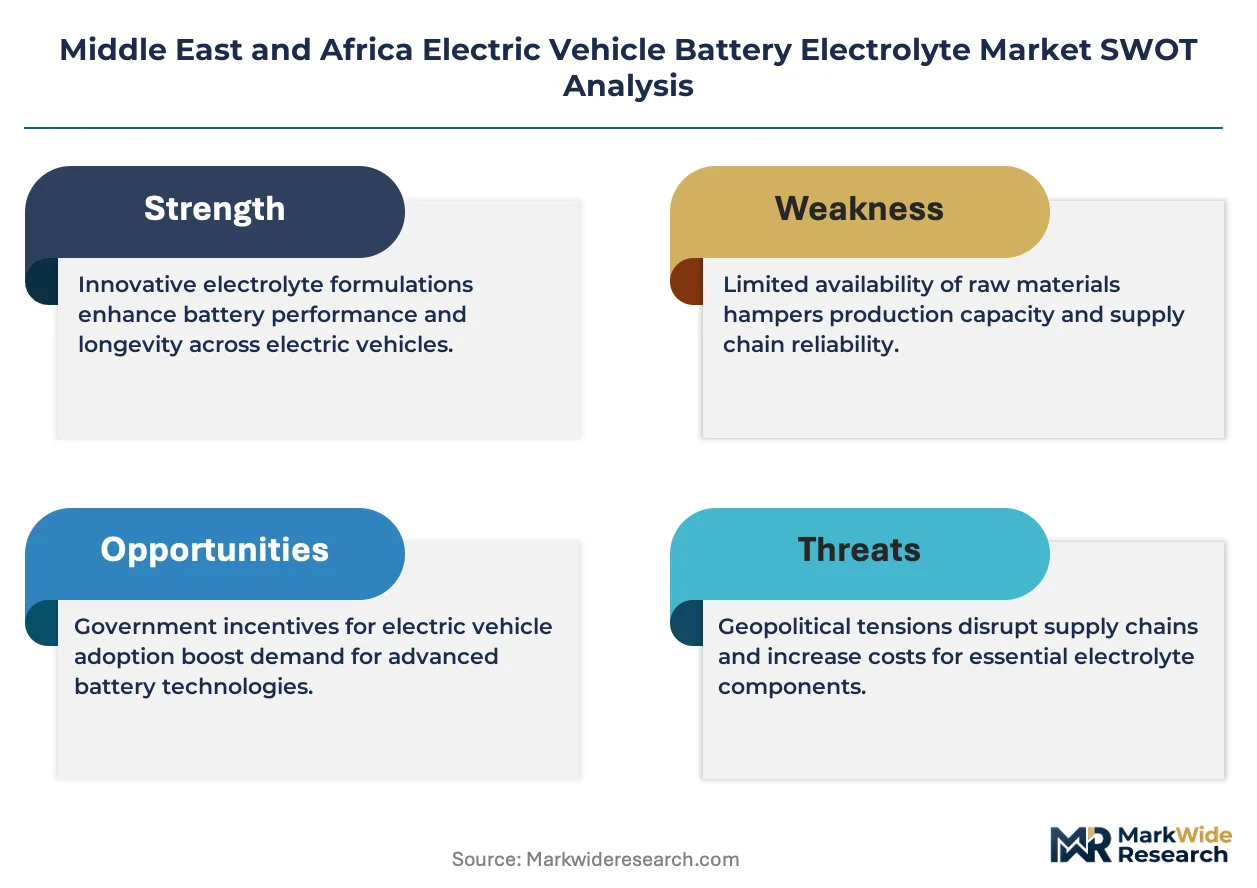
Sodium-ion chemistry substitution threatens conventional lithium salt electrolyte demand across North African battery projects, forcing incumbents to defend formulation relevance while new entrants probe white-space opportunities in solid-state pilot supply.
For Market Incumbents: Pre-empt sodium-ion displacement by locking long-term offtake with Abu Dhabi solid-state pilot lines and securing backward integration into carbonate solvent production via Saudi petrochemical partnerships. SFDA additive requalification timelines favor incumbents with existing certification infrastructure. For New Entrants and Emerging Players: Grid-scale energy storage deployments in Morocco and Jordan represent the most penetrable entry point for specialized thermal-profile electrolyte formulations, with Tangier Med tariff advantages enabling cost-competitive blending operations against Gulf incumbents. Direct technical partnerships with European ceramic powder processors bypass established distributor channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state ceramic-polymer composite development, favoring acquisition targets with interface engineering expertise and existing MOHAP registration pathways. Long-term viability hinges on qualification speed for evolving thermal stability mandates rather than scale alone. Monitor sodium-ion commercialization timelines in North Africa as the critical demand displacement signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbonate Solvents | Saudi petrochemical platforms secure feedstock cost advantages against East Asian import dependency. |
| Solid-State Electrolyte Pilot Scale-Up | Abu Dhabi battery assemblers create first-mover qualification relationships with ceramic powder specialists. |
| Long-Term Fleet Supply Agreements | Dubai electric taxi operators compress procurement channels and marginalize independent distributors. |
| Morocco Blending Facility Localization | Tangier Med tariff advantages enable cost-competitive supply to European and regional battery assemblers. |
| Sodium-Ion Electrolyte Formulation Development | North African projects eliminate lithium salt import exposure and bypass East Asian supply concentration. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with electrolyte plant managers, procurement leads at Dubai Industrial City cell assemblers, and SFDA regulatory affairs specialists; and secondary validation through customs trade data, Gulf petrochemical sector reports, and SEC filings from integrated chemical conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and chemical composition segments.
Forecast inputs considered procurement cycle compression from Dubai fleet electrification mandates, solid-state qualification timeline extensions, and sodium-ion chemistry substitution trajectories across the projection horizon. Segmentation dimensions modeled include electrolyte formulation type, end-use vehicle class, thermal stability certification tier, and regional production hub access. CAGRs derived from volume-weighted growth rates applied to each segment's base-year penetration and projected offtake from named national policy targets.
Practitioners should monitor sodium-ion commercialization timelines, SFDA additive package requalification delays, and East Asian lithium salt pricing volatility for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Sports and Fitness Wears Market
Others
Fresh Pears Market
Others
Global Microcontroller Embedded Systems Market
Others
Europe Virtual Reality Gaming Market
Others
Allogeneic Human Chondrocyte Market
Others
Metal Ore Mining Market
Others
Fiberglass Storage Tanks Market
Others
Mobile MRI Services Market
Others
Czech Republic Market
Others
Smart-Connected Power Plug Socket Market
Others
Global Geotechnical Instrumentation and Monitoring Market
Others
Flexographic Printing Plate Market
Others
Rotary Dial Machine Market
Others
Level Measuring Instrument Market
Others
Tripod Market
Others
Architectural Fabrics Market