
 PC As a Service Market | 2026-2036
PC As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
PC As a Service Market Intelligence
Cloud-native endpoint management is reshaping how enterprises provision, secure, and retire computing devices across distributed workforces. HP Inc leverages its integrated Device-as-a-Service platform to control hardware lifecycles from factory to recycling. Dell Technologies anchors its competitive position through direct supply chain scale and configurable subscription terms for large enterprises. Lenovo Group competes aggressively on price-performance in the workstation and thin client tiers, particularly in Asia-Pacific manufacturing hubs.
PC as a Service bundles hardware acquisition, deployment, support, and end-of-life management into recurring contractual arrangements, typically spanning three to five years with specified service-level agreements for uptime and response. The model shifts capital expenditure to operational expenditure while embedding remote monitoring, security patching, and asset tracking. Subscription service models now dominate enterprise procurement as CFOs prioritize balance sheet flexibility, while cloud-based deployment modes capture the fastest expansion as hybrid work architectures persist. Managed services represent the deepest margin pool, integrating help desk, field service, and compliance reporting into unified offerings.
The U.S. Environmental Protection Agency and the EU REACH framework impose material disclosure and e-waste recovery obligations that elevate compliance costs for hardware providers. Japan's METI enforces energy efficiency standards that filter into procurement specifications for government and educational buyers. India's BIS certification requirements for imported electronics create market access friction that local assemblers exploit. Stakeholders must weigh circular economy mandates against total cost of ownership claims when structuring multi-year service agreements.
Market Dynamics
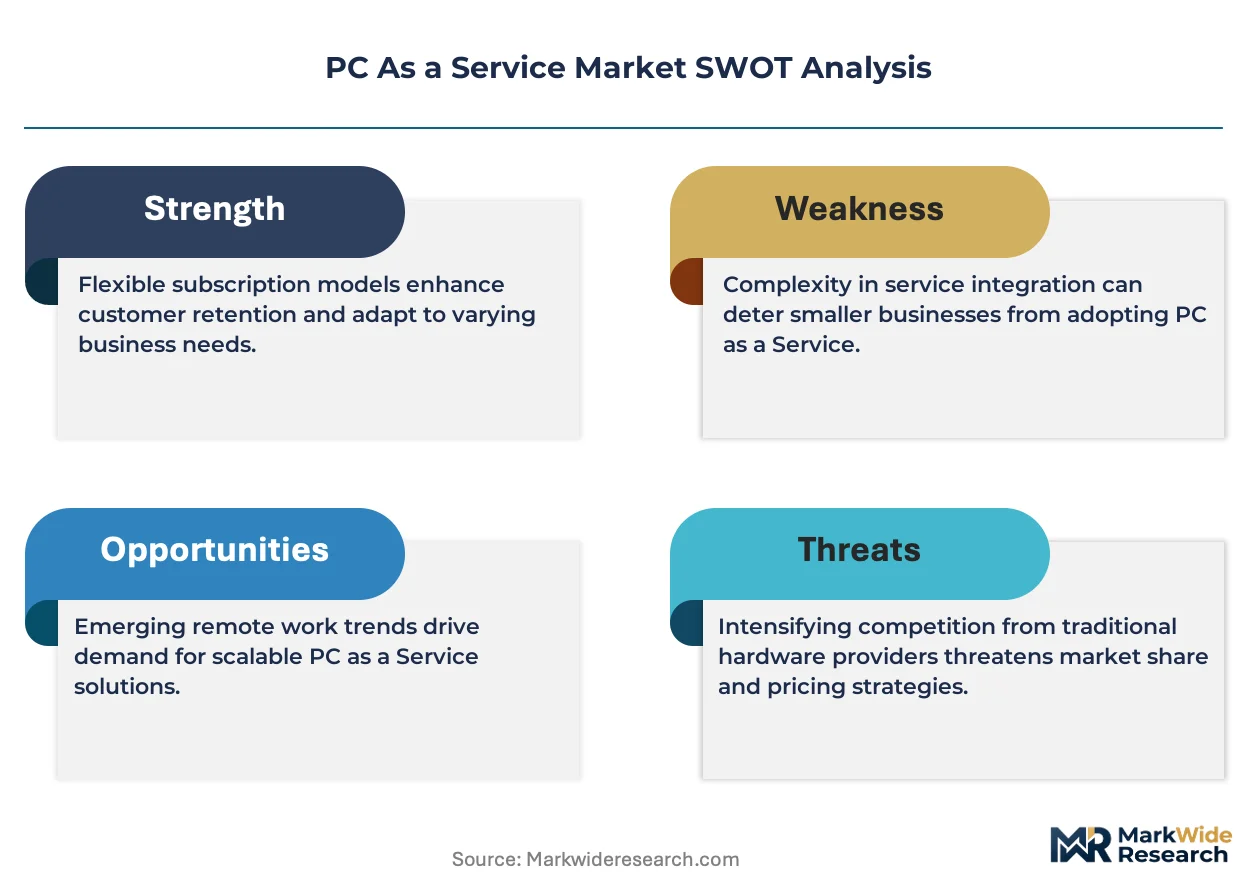
Cloud-native endpoint management platforms are compressing hardware refresh cycles while embedding security and compliance directly into subscription contracts, fundamentally restructuring how enterprises acquire and retire computing assets.
Growth Catalysts
- EU Green Deal circular mandates:Take-back and refurbishment obligations are accelerating OEM investment in reverse logistics infrastructure, creating captive refurbishment capacity that lowers per-unit service delivery costs.
- Healthcare endpoint expansion:Clinical fleet management requirements are pulling device-as-a-service into hospital procurement specifications, with HIPAA-compliant remote monitoring becoming a standard contract inclusion.
- Thin client manufacturing hubs:Asia-Pacific production concentration is enabling just-in-time configuration and faster deployment velocity for distributed enterprise customers.
Market Restraints
- Semiconductor input volatility:Memory and processor pricing swings compress hardware margin buffers within fixed subscription terms, exposing providers to cost absorption pressure.
- Single-source firmware dependencies:BIOS and management engine concentration with Intel and AMD creates supply vulnerability that multi-OEM strategies cannot fully mitigate.
- India BIS certification friction:Import electronics testing requirements delay market entry for foreign assemblers, favoring domestic contract manufacturers with established compliance pathways.
Strategic Opportunities
- Japan METI efficiency procurement:Government and educational buying specifications are mandating energy performance thresholds that subscription models can guarantee through active fleet optimization.
- Edge AI workstation convergence:On-device inference requirements are collapsing the distinction between standard endpoints and specialized compute, expanding addressable hardware tiers.
- Direct-to-employer channel bypass:Bypassing traditional IT resellers through OEM-managed marketplaces is capturing mid-market buyers seeking simplified contract administration.
Industry Challenges
- Firmware security patching velocity:The gap between vulnerability disclosure and managed deployment across distributed fleets strains SLA commitments and incident response protocols.
- Legacy endpoint integration:Hybrid environments mixing subscription and owned assets create configuration management complexity that unified monitoring platforms struggle to resolve.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PC As a Service Market |
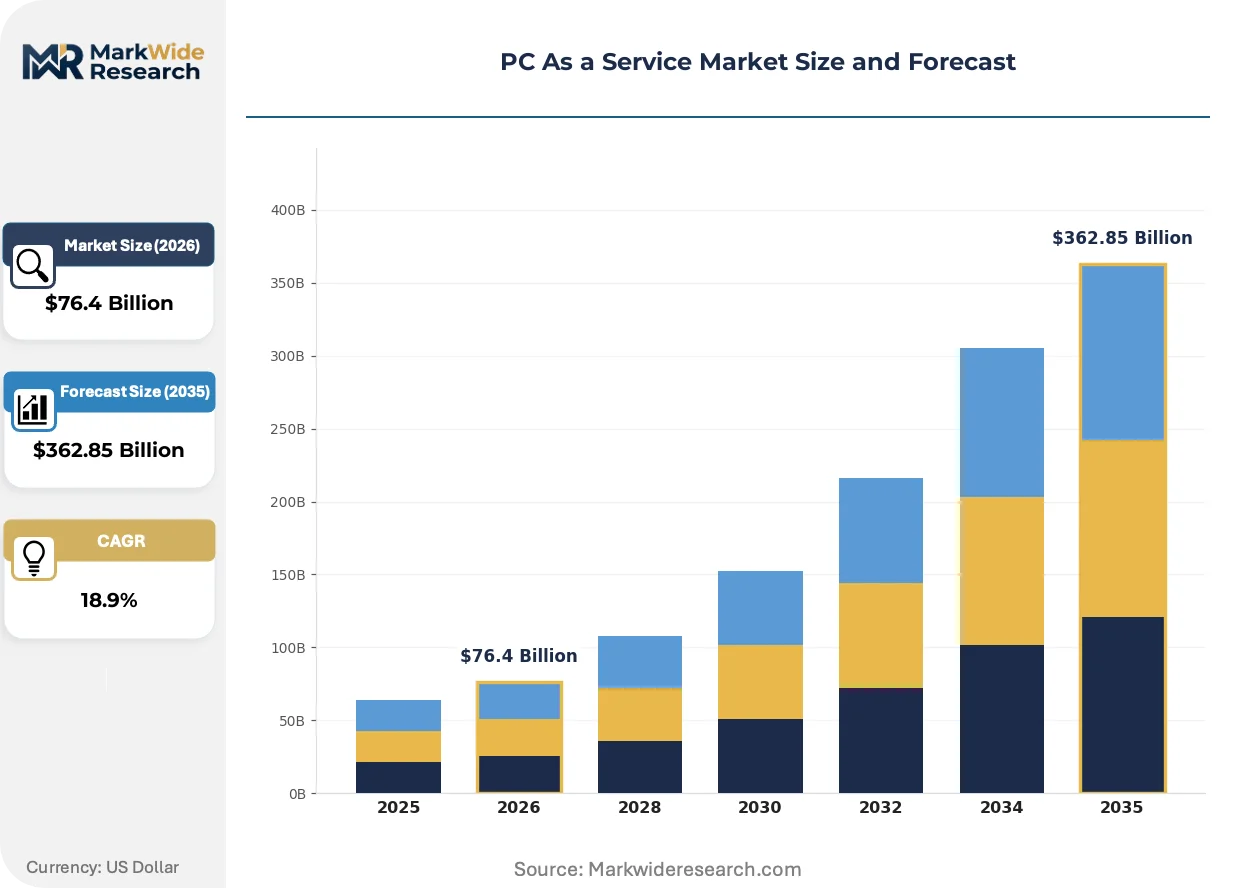
| Market Size in 2026 | $76.4 Billion |
| Market Size in 2035 | $362.85 Billion |
| CAGR (2026 – 2036) | 18.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Model: Subscription, Lease, Pay-As-You-Go, Managed Services Device Type: Desktop, Laptop, Workstation, Thin Client, All-in-One Customer Type: Small & Medium Businesses, Large Enterprises, Government Agencies, Educational Institutions Deployment Mode: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | HP Inc, Dell Technologies, Lenovo Group, Microsoft Corporation, CompuCom Systems, SHI International, Intel Corporation, Capgemini, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PC As a Service Market Strategic Shifts & Innovations
Zero-touch provisioning and automated endpoint remediation are compressing deployment timelines from weeks to hours, while regulatory pressure on embodied carbon is forcing hardware lifecycle transparency into contract negotiations.
Zero Trust network architecture is collapsing traditional perimeter-based security models into continuous device verification protocols. Healthcare systems and financial services are adopting hardware-backed attestation at the fastest clip. This collapse is eliminating the distinction between managed and unmanaged endpoints, requiring every device to carry embedded security agents as standard.
The EU CSRD sustainability disclosure rules are mandating Scope 3 emissions reporting that captures hardware supply chains. OEMs must now document refurbishment rates and recycled content percentages to maintain enterprise eligibility. German and French public sector tenders are incorporating these disclosures as weighted scoring criteria, effectively screening out non-compliant providers.
Subscription billing granularity is shifting from per-device to per-user models that accommodate fluid device switching. Knowledge workers in technology and professional services are driving this preference, valuing flexibility over fixed hardware assignment. United States enterprise procurement teams are negotiating these terms most aggressively, using competitive RFPs to force contract structure innovation.
PC As a Service Market Segmentation
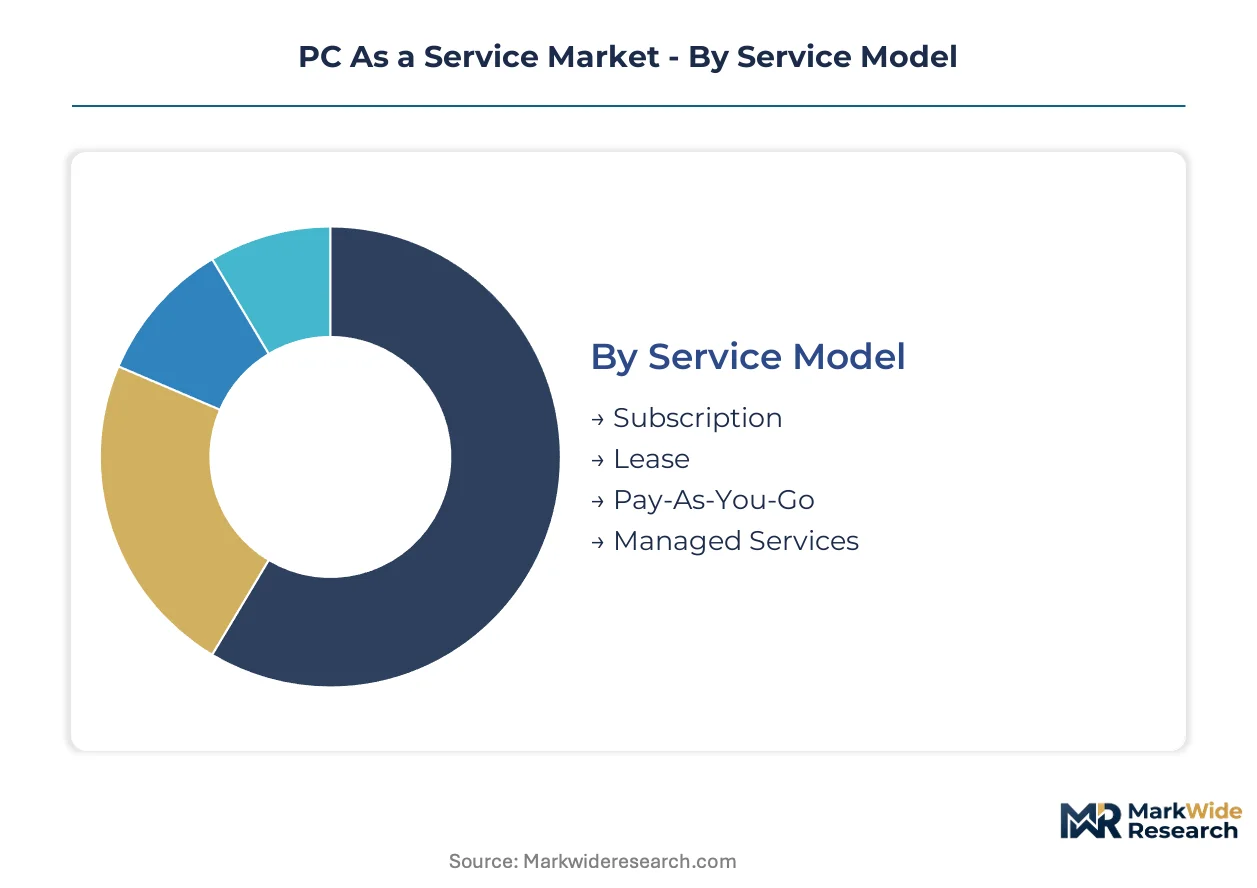
PC as a Service segmentation reveals how procurement flexibility, device specialization, and infrastructure topology create distinct commercial pockets with diverging margin profiles and contract complexity. Understanding these divisions enables providers to align subscription terms, service-level agreements, and refresh cycles with customer operational realities.
Service Model:
Mature contractual structures dominate enterprise procurement, while emerging consumption-based arrangements are capturing mid-market buyers seeking variable cost alignment.
- Subscription:Fixed-term contracts bundle hardware, support, and lifecycle management into predictable monthly fees. Large enterprises in Germany and the United States negotiate these terms most aggressively, using multi-year commitments to extract configuration flexibility and dedicated account management.
- Managed Services:Comprehensive offerings integrate help desk, field service, compliance reporting, and security operations into unified delivery. Healthcare systems expanding clinical endpoint fleets favor this model for HIPAA-aligned remote monitoring and incident response guarantees.
- Lease:Traditional financing structures separate hardware title from operational service, appealing to public sector buyers with capital budget constraints and strict asset ownership rules.
- Pay-As-You-Go:Metered consumption models charge by active usage hours or compute cycles, attracting project-based professional services firms with fluctuating workforce sizes.
Subscription retains volume leadership; Managed Services holds the steepest expansion curve.
Device Type:
Cost tier differentiation separates standardized endpoint categories from specialized compute tiers commanding premium service fees.
- Laptop:Mobile form factors comprise the majority of deployed units under PCaaS contracts, with thin-and-light configurations dominating knowledge worker allocations. Japanese enterprises prioritize energy efficiency certifications from METI when specifying fleet standards.
- Workstation:High-performance configurations support CAD, media production, and data science workloads requiring dedicated GPU resources and extended warranty terms. Asia-Pacific manufacturing hubs concentrate demand for these tiers as engineering centers expand.
- Desktop:Fixed-location deployments persist in call centers, back-office operations, and regulated environments requiring physical security controls.
- Thin Client:Minimal local processing devices reduce attack surface and simplify endpoint management, gaining traction in financial services and government agencies with strict data residency requirements.
- All-in-One:Integrated display and compute units address space-constrained deployments in healthcare reception areas and educational computer labs.
Laptop maintains installed base dominance; Workstation is climbing the fastest as edge AI inference requirements expand addressable hardware tiers.
Customer Type:
Volume concentration varies sharply across organizational scale, with procurement sophistication and contract negotiation leverage determining service customization depth.
- Large Enterprises:Multi-thousand-seat deployments command dedicated technical account managers, custom imaging, and global logistics coordination. These buyers consolidate vendor relationships to reduce procurement fragmentation across operating regions.
- Government Agencies:Public sector tenders incorporate EU Green Deal circular economy mandates and national energy efficiency standards as weighted scoring criteria, screening out providers lacking documented refurbishment rates.
- Small & Medium Businesses:Simplified contract administration and rapid deployment velocity outweigh deep customization needs, making direct-to-employer OEM marketplaces an attractive channel bypass.
- Educational Institutions:Seasonal demand patterns and budget cycle alignment require flexible term structures, with K-12 and higher education segments showing diverging device durability and software licensing requirements.
Large Enterprises capture the deepest per-contract value; Government Agencies are gaining share fastest as circular procurement mandates expand.
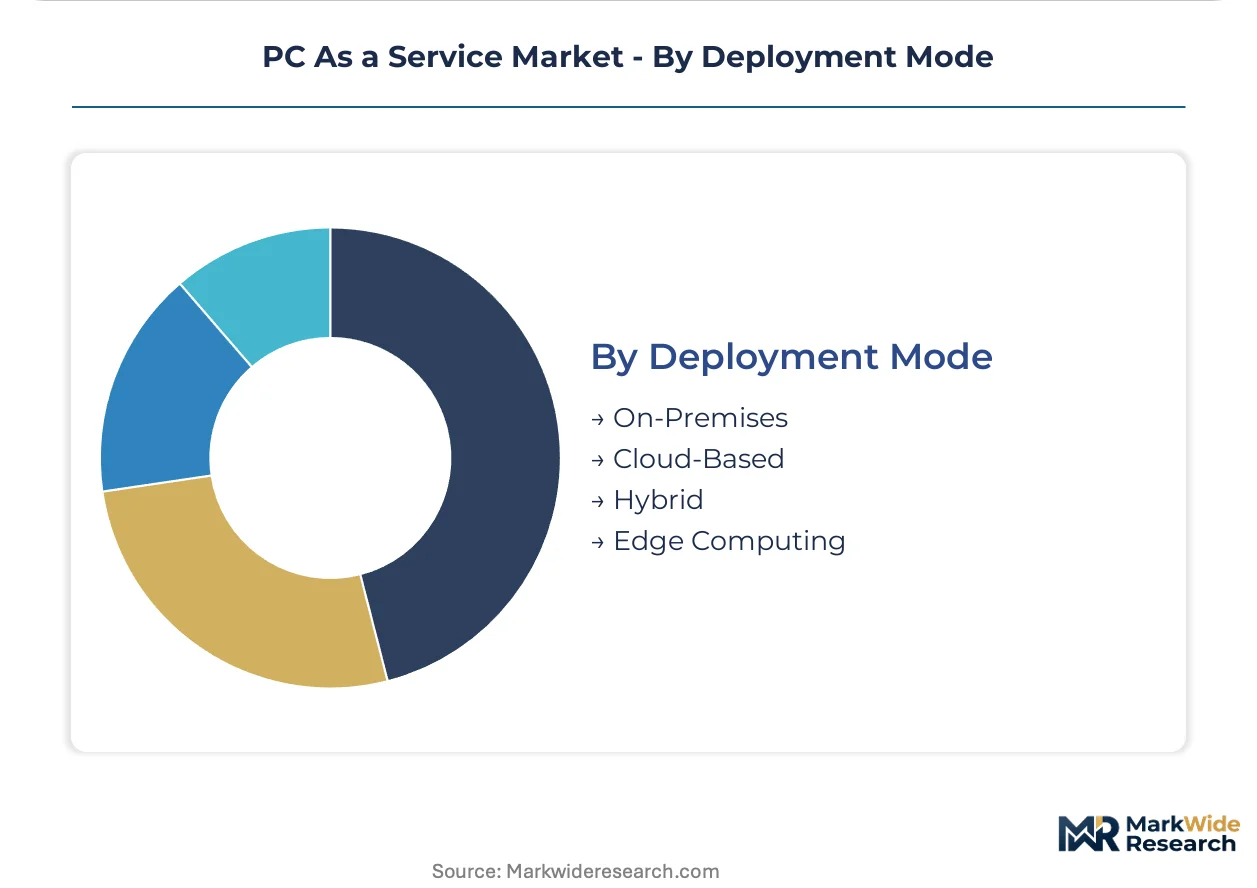
Deployment Mode:
Application topology determines infrastructure investment allocation, with cloud-native architectures displacing traditional on-premises management platforms.
- Cloud-Based:Centralized endpoint management platforms enable zero-touch provisioning, automated remediation, and continuous security patching across distributed workforces. This mode captures the fastest expansion as hybrid work architectures persist.
- Hybrid:Mixed environments combining cloud orchestration with local identity and policy enforcement address regulated industries with data sovereignty requirements.
- On-Premises:Air-gapped or locally managed deployments persist in defense, critical infrastructure, and certain healthcare settings where external connectivity introduces unacceptable risk exposure.
- Edge Computing:Localized processing at branch offices, manufacturing floors, and retail locations reduces latency for time-sensitive applications while maintaining centralized policy governance.
Cloud-Based leads new contract acquisition; Edge Computing shows the steepest trajectory as operational technology convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in Germany, the United States, and Japan are consolidating vendor relationships to reduce fragmentation across distributed workforces. Healthcare systems and government agencies in these markets are embedding circular economy mandates into multi-year service agreements. Regulatory pressure on embodied carbon and e-waste recovery is reshaping contract structures in each jurisdiction.
United States
Large enterprises in financial services and technology sectors are driving subscription contract volume, with CFOs prioritizing balance sheet flexibility over capital ownership. The EPA imposes material disclosure and e-waste recovery obligations that elevate compliance costs for hardware providers. The Greater Boston and Pacific Northwest technology corridors concentrate demand for zero-touch provisioning and automated endpoint remediation.
Germany
Industrial manufacturing headquarters and automotive engineering centers are expanding workstation-as-a-service deployments for CAD and simulation workloads. The EU Green Deal and national circular economy mandates require documented refurbishment rates and recycled content percentages in public tenders. The Bavaria and Baden-Württemberg regions host dense clusters of Mittelstand firms consolidating device procurement through OEM-managed marketplaces.
Japan
Government agencies and educational institutions are mandating energy efficiency thresholds through METI procurement specifications that subscription models guarantee via active fleet optimization. The country's national electronics regulator enforces standards that filter into specifications for institutional buyers. The Kanto region around Tokyo and the Kansai region centered on Osaka concentrate enterprise IT decision-making and vendor relationship consolidation.
India
Domestic contract manufacturers with established BIS certification pathways are capturing share from foreign assemblers delayed by import electronics testing requirements. The Bureau of Indian Standards creates market access friction that local players exploit for government and educational contracts. The Karnataka and Maharashtra technology corridors are emerging as thin client configuration hubs serving Asia-Pacific distributed enterprise customers.
United Kingdom
Professional services firms and hybrid-work technology companies are negotiating per-user billing models that accommodate fluid device switching across knowledge worker populations. The UK Information Commissioner's Office and national data protection frameworks influence security specifications in subscription contracts. The London-Southeast corridor dominates procurement decision-making for multinational enterprises with EMEA headquarters.
PC As a Service Market Key Industry Players
Channel-controlling players compete with product-specialist players for procurement relationship ownership across enterprise segments. The market structure tilts toward consolidated vendor relationships at the large enterprise tier while fragmenting across mid-market resellers and regional system integrators. Three archetypes dominate: integrated OEM platforms with captive lifecycle services, IT services conglomerates with hardware-agnostic managed offerings, and pure-play device financiers with refurbishment specialization. Competitive moves concentrate on direct marketplace development to bypass traditional reseller channels and on reverse logistics infrastructure investment to satisfy circular economy compliance.
Within the integrated OEM tier, HP Inc, Dell Technologies, and Lenovo Group exemplify distinct geographic and segment positioning strategies. HP Inc anchors the North American enterprise segment through subscription bundling that embeds security and compliance directly into contractual terms. Dell Technologies represents scale-driven supply chain leverage with configurable terms for multi-thousand-seat deployments. Lenovo Group occupies the price-performance position in workstation and thin client tiers, particularly across Asia-Pacific manufacturing and engineering centers.
| Leading Market Players |
|---|
| HP Inc |
| Dell Technologies |
| Lenovo Group |
| Microsoft Corporation |
| CompuCom Systems |
| SHI International |
| Intel Corporation |
| Capgemini |
| Cisco Systems |
| Others |
Cost & Logistics Intelligence
The Karnataka and Maharashtra technology corridors concentrate thin client configuration capacity, feeding downstream pricing power to OEMs managing Asia-Pacific distributed enterprise deployments. Contract manufacturers with established BIS certification pathways capture margin premiums that foreign assemblers forfeit to import testing delays.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate three-to-five-year subscription agreements, exposing providers to memory and processor pricing swings. Price differentiation rests on configuration flexibility and dedicated account management tiers, with large enterprises in Germany and the United States extracting the steepest concessions. Margins are tightening due to fixed subscription terms absorbing input volatility. Small and medium businesses show highest price sensitivity, prioritizing simplified administration over customization depth.
Supply Chain Analysis
Export controls on advanced chip fabrication equipment limit foundry capacity expansion in Taiwan and South Korea, concentrating processor supply risk. The chain draws from Malaysia and Vietnam for final assembly, with BIOS and management engine dependencies creating single-source vulnerability with Intel and AMD. Tariff exposure runs through shifting trade corridors. Distribution feeds from OEM-managed marketplaces bypassing traditional IT reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in reverse logistics infrastructure and circular economy compliance documentation separates viable multi-year service providers from commodity hardware vendors. Captive refurbishment capacity and documented recovery rates now determine enterprise eligibility in German and French public tenders.
For Market Incumbents: Pre-empt margin compression by building captive refurbishment facilities in the EU to satisfy Green Deal take-back mandates. Secure multi-source firmware agreements to reduce Intel and AMD concentration risk. Channel control through direct marketplaces defends against reseller disintermediation.
For New Entrants and Emerging Players: Pursue mid-market buyers in the United Kingdom seeking per-user billing flexibility for fluid device switching. India's government and educational contracts offer penetrable white-space given BIS friction delaying foreign entry. Lead with rapid deployment velocity through zero-touch provisioning.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription models embed hardware lifecycles into sticky contractual relationships. Target device financiers with refurbishment specialization and established OEM partnerships. Watch for inflection when METI efficiency specifications expand beyond Japan into broader Asia-Pacific procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Reverse Logistics Infrastructure Buildout | Captive refurbishment capacity satisfies EU Green Deal circular economy mandates and lowers per-unit service delivery costs. |
| Direct-to-Employer Marketplace Launch | Bypassing traditional IT resellers captures mid-market buyers prioritizing simplified contract administration over customization. |
| Multi-Source Firmware Diversification | Reducing Intel and AMD concentration mitigates single-source vulnerability that multi-OEM strategies cannot fully address. |
| Per-User Billing Model Introduction | Fluid device switching terms attract United States knowledge workers in technology and professional services segments. |
| HIPAA-Aligned Remote Monitoring Integration | Healthcare systems expanding clinical endpoint fleets require compliant incident response guarantees in managed service tiers. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with IT procurement officers, managed services directors, OEM technical account managers, and hospital biomedical engineers; and secondary validation through SEC 10-K filings, hyperscaler capex disclosures, EU tender databases, and BIS certification records. Bottom-up contract volume estimates triangulated against top-down hardware shipment allocations.
Forecast inputs span service model, device type, customer scale, and deployment topology across the projection horizon. CAGRs derive from segment-level growth trajectories weighted by installed base migration patterns and refresh cycle compression. Endpoint security patching velocity and circular economy compliance thresholds factor as industry-specific demand modifiers.
Sensitivities concentrate around semiconductor input volatility, firmware security disclosure gaps, and regulatory expansion of Scope 3 emissions reporting. Forecasts embed assumptions on hybrid work persistence and healthcare endpoint digitization. Material shifts in export control regimes or circular mandate enforcement timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Thermally Conductive Grease Market
Others
Sports Events Market
Others
Retail Media Platform Market
Others
PCB Laminate Market
Others
Rugged Devices Market
Others
Global Digital Caliper Market
Others
Lepidolite Market
Others
Air Separation Module Kit Market
Others
Middle East and Africa Home Care Packaging Market
Others
Storage Dewar and Dry Shipper Market
Others
Fabric Based Computing Market
Others
Digital Mortgage Software Market
Others
Solid White Films Market
Others
Europe Military 4D Printing Market
Others
Video Encoder Market
Others
3D Printing Construction Market