
 Bitcoin Market | 2026-2036
Bitcoin Market Size, Share, and Industry Trends Forecast 2026-2036
Bitcoin Market Intelligence
Staking-as-a-service and custody subscription models are expanding the recurring-revenue layer of the Bitcoin ecosystem. Strategy leverages its convertible-debt-funded accumulation strategy to anchor corporate treasury demand. Coinbase Global sustains institutional-grade custody infrastructure that dominates US onshore flows. BlackRock iShares Bitcoin Trust competes through ETF wrapper innovation that channels retirement-account capital.
Bitcoin is a proof-of-work digital asset secured by the SHA-256 hashing algorithm, with a fixed supply cap of 21 million coins and a programmatic issuance schedule halving every 210,000 blocks. Its primary commercial purpose is to serve as a non-sovereign store of value and settlement layer for high-value transfers outside traditional banking rails. Exchange-based transaction flows occupy the deepest liquidity pools and tightest spreads, while institutional user types command the fastest-growing allocation segment as pension and endowment boards revise investment mandates. Miners and wallet-transfer channels remain structurally important but carry thinner margin profiles due to operational intensity and fee compression.
The SEC regulates spot Bitcoin ETF disclosures and broker-dealer custody arrangements under the Investment Company Act of 1940, while FinCEN enforces anti-money-laundering compliance across US exchanges and payment processors. The EU's MiCA framework establishes reserve-backing and transparency obligations for crypto-asset service providers operating across member states. Stakeholders must monitor how jurisdictional arbitrage between US enforcement actions and European licensing regimes reshapes exchange location decisions and custody infrastructure deployment.
Market Dynamics
The Bitcoin market currently pivots on institutional treasury adoption accelerating among publicly traded companies, reshaping demand composition from retail speculation toward balance-sheet-grade allocation mandates.
Growth Catalysts
- Spot ETF regulatory clarity:The SEC's evolving approval framework for exchange-traded products is channeling retirement-account capital into compliant wrappers, expanding addressable investor pools beyond direct custody.
- Convertible debt instruments:Corporate treasury strategies employing fixed-income securities to fund accumulation are creating synthetic demand floors that persist through price volatility cycles.
- Staking-as-a-service expansion:Recurring-revenue custody models are electrifying infrastructure economics, incentivizing provider investment in cold-storage and insurance-backed solutions.
Market Restraints
- Energy input cost volatility:Proof-of-work mining operations face margin compression from regional electricity price swings, particularly in jurisdictions with carbon-intensive grid mixes.
- Geographic supply concentration:Hashing power clusters in specific provincial jurisdictions create systemic risk from localized enforcement actions or infrastructure failures.
- Technical throughput limitations:Base-layer transaction capacity constraints restrict settlement velocity for high-frequency use cases, pushing activity toward custodial intermediation.
Strategic Opportunities
- Underpenetrated sovereign wealth:Middle Eastern and Southeast Asian state investment vehicles remain below strategic allocation thresholds for non-sovereign store-of-value assets.
- Layer-2 payment integration:Lightning Network convergence with point-of-sale terminals is enabling merchant settlement rails outside card-network infrastructure.
- EU MiCA licensing tailwind:Reserve-backing and transparency obligations for crypto-asset service providers are creating first-mover advantages for compliant custodians entering continental markets.
Industry Challenges
- Qualified custody talent scarcity:Institutional-grade key-management and insurance-structuring expertise remains concentrated among a limited pool of specialists.
- Audit and attestation complexity:Proof-of-reserve verification standards lack harmonization across jurisdictions, complicating institutional due diligence workflows.
- Legacy system integration friction:Treasury management platforms require custom API development to accommodate blockchain-native settlement finality conventions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitcoin Market |
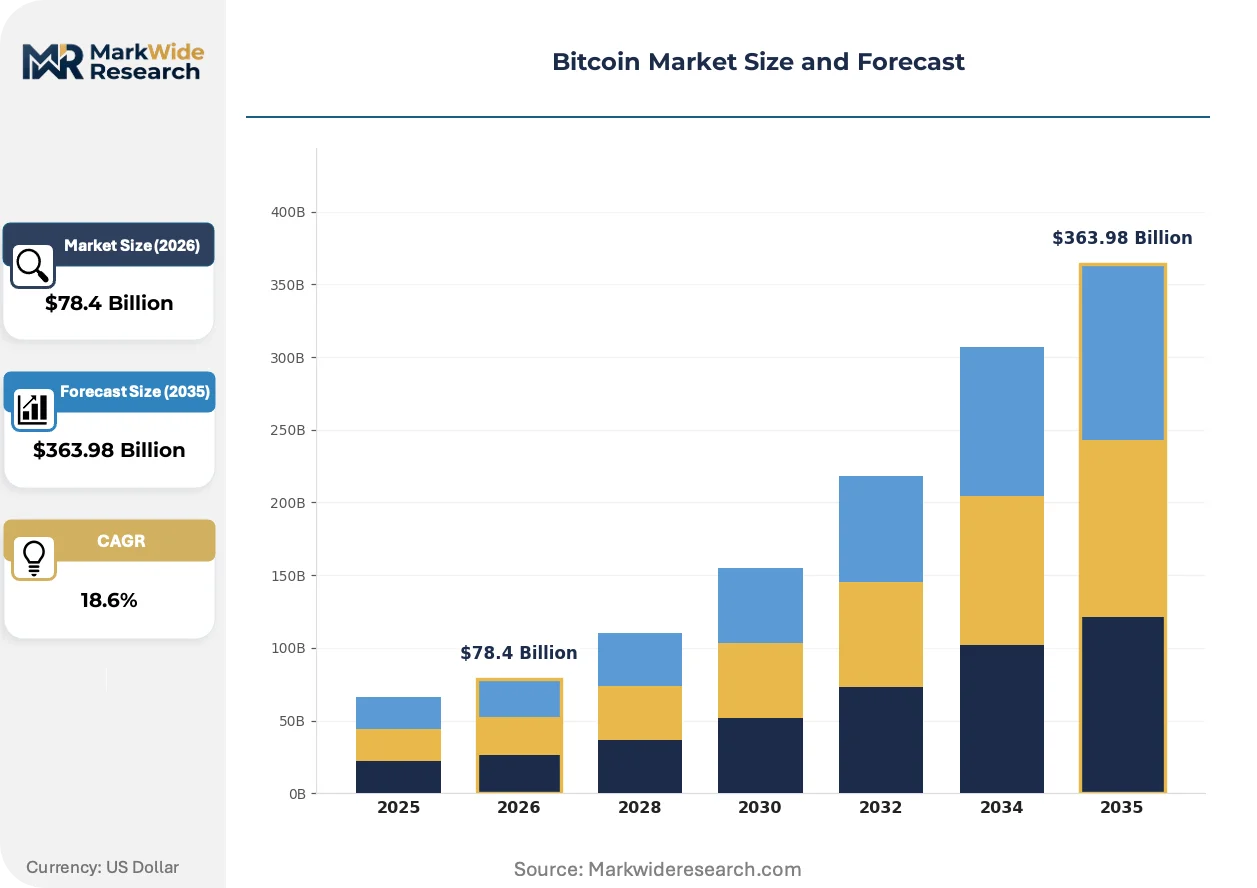
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $363.98 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transaction Type: Peer-to-Peer, OTC, Exchange, Wallet Transfer Investment Phase: Seed, Venture, Growth, Exit User Type: Individual Investors, Institutions, Traders, Miners Technology Adoption: Blockchain, Payment Gateways, Smart Contracts, Decentralized Finance |
| Companies Covered | Strategy, BlackRock iShares Bitcoin Trust, Coinbase Global, Binance, MARA Holdings, Grayscale, Fidelity, Tether Holdings, Galaxy Digital Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitcoin Market Strategic Shifts & Innovations
Institutional infrastructure maturation is compressing the gap between traditional asset servicing and digital-native custody, reshaping competitive requirements around regulatory compliance and insurance-backed security.
Taproot script enhancements and Schnorr signature aggregation are electrifying multisignature wallet efficiency, reducing on-chain footprint for complex custody arrangements. Pension and endowment fiduciaries are mandating these upgrades for new allocations. The structural consequence is elevating technical sophistication barriers for infrastructure providers while compressing operational cost differentials between tier-one and tier-two custodians.
FinCEN's enforcement priorities for anti-money-laundering compliance across US exchanges and payment processors are intensifying know-your-customer data requirements. Industrial consequence includes elevated compliance staffing ratios and transaction monitoring system investments. Retail-facing platforms are responding by restricting service availability in higher-risk jurisdictional subsets.
Treasury procurement of Bitcoin exposure is rotating from direct spot accumulation toward derivative-structured products with embedded downside protection. Corporate finance teams are displacing speculative position-taking with balance-sheet-hedging instruments. This behavioral shift is most visible among technology sector issuers with substantial offshore cash positions seeking non-fiat denomination.
Bitcoin Market Segmentation
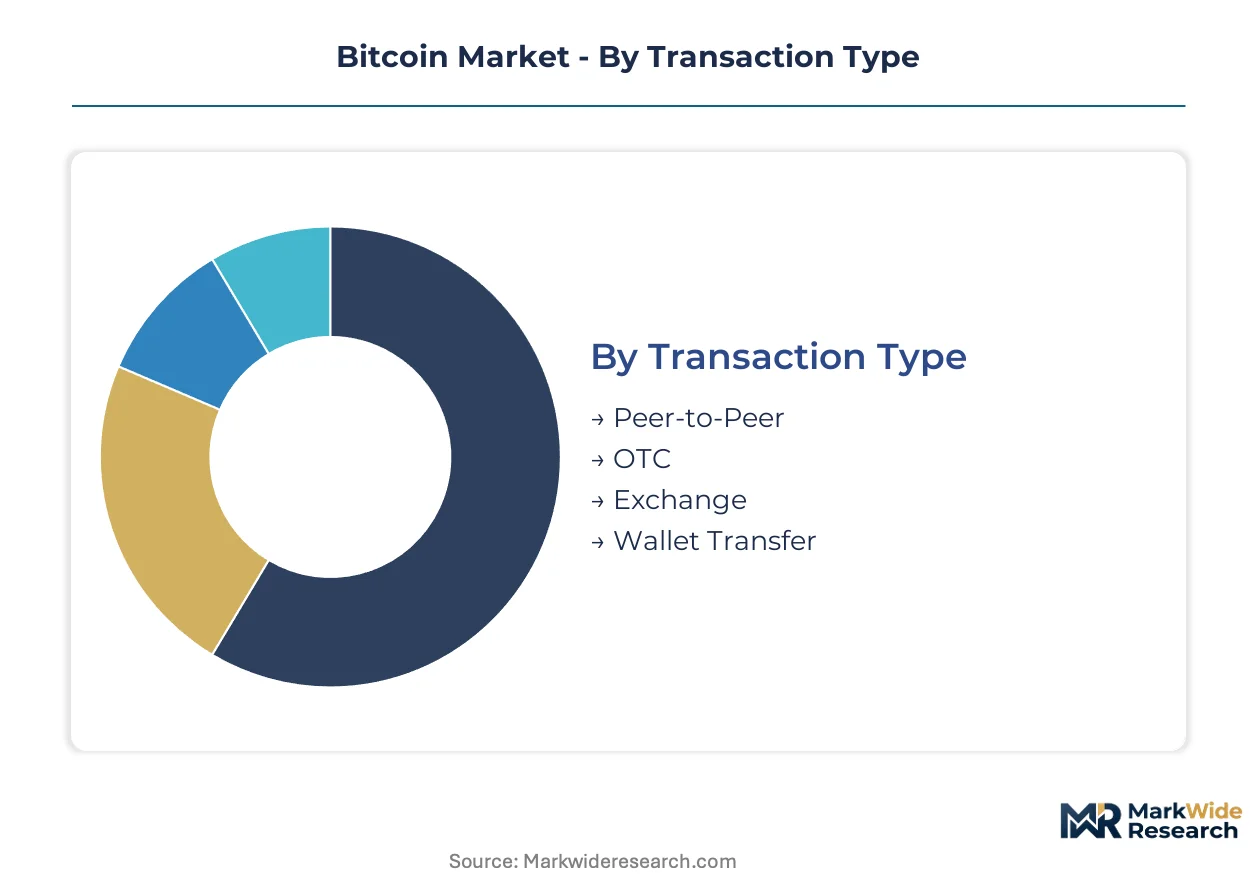
Segmentation in the Bitcoin market reveals how capital formation, settlement velocity, and custody infrastructure concentrate across distinct behavioral clusters. Each dimension exposes different margin profiles, regulatory touchpoints, and technology dependencies that shape provider strategy.
Transaction Type:
Settlement finality requirements and counterparty risk tolerance determine channel selection among Bitcoin market participants.
- Exchange:Centralized order books aggregate the deepest liquidity pools and tightest bid-ask spreads. Demand concentrates in United States venues where SEC-registered broker-dealers offer qualified custody and FinCEN-compliant AML programs. Institutional treasuries favor these channels for balance-sheet allocation due to insurance-backed cold storage and same-day settlement rails.
- OTC:Bilateral negotiated blocks execute large notional transfers without market impact. Demand clusters among publicly traded companies executing convertible-debt-funded accumulation strategies, particularly those seeking to minimize slippage on multi-million-dollar entries. Relationship-based pricing and post-trade settlement flexibility anchor this segment's value proposition.
- Peer-to-Peer:Direct wallet-to-wallet settlement outside intermediary custody. Individual remittance corridors in emerging markets drive volume, attracted by bypassing correspondent banking delays and capital controls.
- Wallet Transfer:On-chain settlement between self-custodied addresses. Miners and long-term holders dominate flows, prioritizing finality assurance over execution speed.
Volume sits with Exchange; growth tilts toward OTC.
Investment Phase:
Risk-return profiles and liquidity horizons segment capital deployment across the Bitcoin ecosystem's maturity spectrum.
- Growth:Expansion-stage infrastructure providers scaling custody technology and compliance staffing attract the largest capital commitments. Pension and endowment fiduciaries mandate these positions for their balance-sheet-grade security frameworks and regulatory licensure across multiple jurisdictions.
- Venture:Early-stage protocol development and mining hardware innovation command technical due diligence intensity. Specialist funds concentrate deployment in Lightning Network payment routing and energy-efficient ASIC design.
- Seed:Pre-product teams building novel key-management or insurance-structuring solutions. Angel syndicates and operator-led funds dominate this layer.
- Exit:Secondary transactions and strategic acquisitions realize returns for early Bitcoin ecosystem investors. SPAC combinations and private equity buyouts channel liquidity to limited partners.
Capital deployment concentrates in Growth; steepest expansion trajectory appears in Venture as infrastructure gaps attract technical specialists.
User Type:
Regulatory sophistication and operational scale differentiate service requirements across participant categories.
- Institutions:Pension funds, endowments, and corporate treasuries mandate qualified custody, SOC-2 attestation, and board-level investment policy compliance. United States entities dominate this segment under SEC and FinCEN frameworks.
- Individual Investors:Retail accumulation through dollar-cost averaging and retirement-account wrappers. ETF access channels and mobile-first custody apps serve this base.
- Traders:High-frequency participants exploiting derivatives basis and spot-futures arbitrage. Margin requirements and real-time risk systems define platform selection.
- Miners:Proof-of-work operators securing the network through SHA-256 hashing. Energy procurement contracts and hardware depreciation schedules govern economics.
Revenue per user peaks with Institutions; user count expands fastest among Individual Investors accessing regulated wrappers.
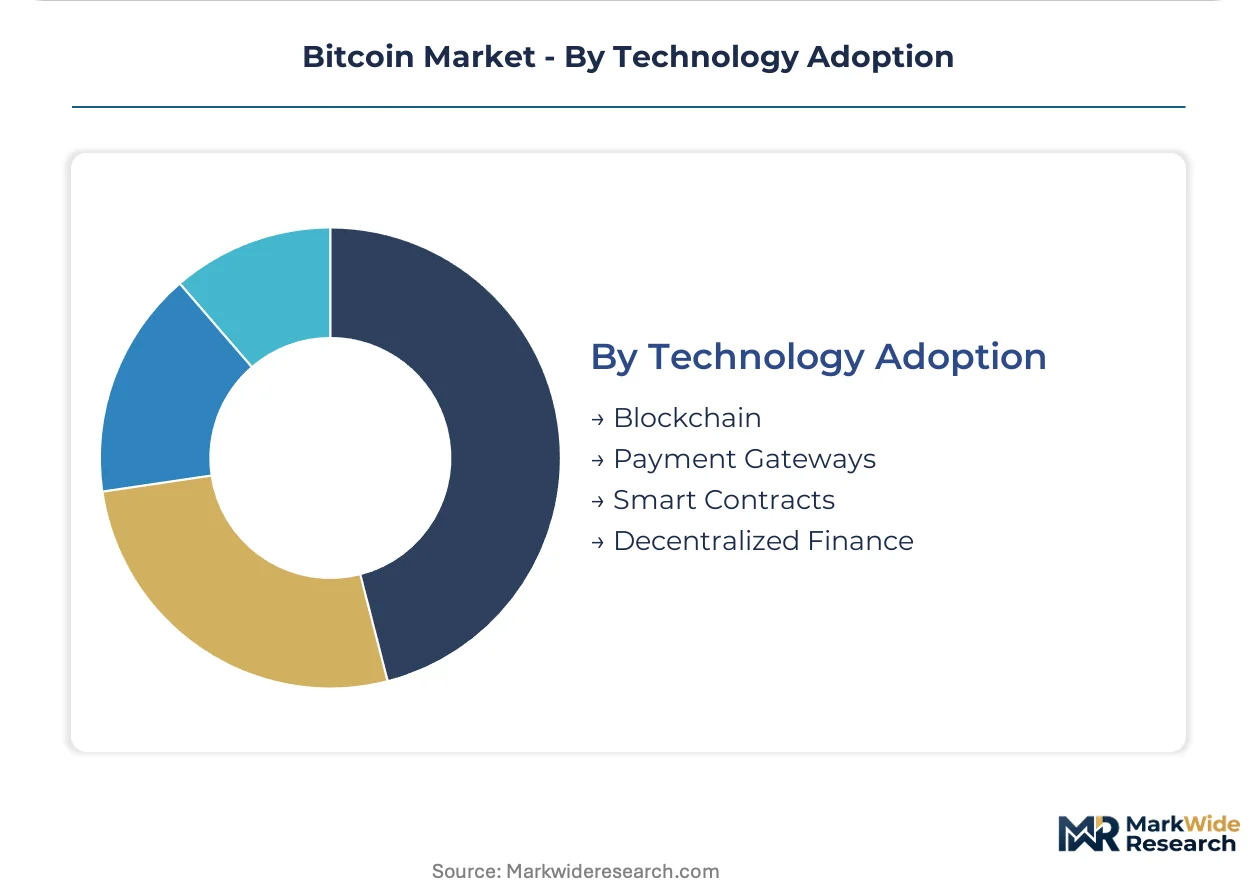
Technology Adoption:
Stack maturity and interoperability requirements shape procurement decisions for Bitcoin infrastructure.
- Blockchain:Base-layer settlement and timestamping functions. All other segments depend on this foundational infrastructure for finality assurance.
- Payment Gateways:Merchant acceptance rails converting Bitcoin to fiat at point-of-sale. Lightning Network integration drives adoption in retail and e-commerce verticals.
- Smart Contracts:Programmable escrow and multi-signature coordination. Institutional custody arrangements leverage these for policy-enforced spending controls.
- Decentralized Finance:Bitcoin-collateralized lending and synthetic exposure products. Regulatory uncertainty constrains United States deployment while European MiCA licensing enables continental expansion.
Deployment maturity centers on Blockchain; innovation investment flows fastest into Payment Gateways bridging traditional commerce rails.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hashing power concentrates in provincial Chinese jurisdictions while institutional capital formation clusters in US financial centers. Demand-side deployment tilts toward North American and European treasury desks. Regulatory arbitrage between SEC enforcement patterns and EU licensing regimes reshapes custody infrastructure geography.
United States
Corporate treasury accumulation and spot ETF flows anchor institutional demand. SEC disclosure requirements under the Investment Company Act of 1940 govern broker-dealer custody arrangements. New York and Chicago financial districts concentrate qualified custodians serving pension and endowment fiduciaries.
China
Mining hardware manufacturing and hashing power aggregation dominate supply-side activity. Provincial energy pricing policies and carbon reduction targets under dual carbon goals drive facility relocation. Sichuan and Xinjiang regions host concentration of proof-of-work operations despite periodic enforcement actions.
Germany
Institutional custody demand from Mittelstand treasury desks and family offices expands addressable pools. BaFin crypto custody licensing requirements establish compliance baselines for euro-denominated services. Frankfurt financial cluster anchors MiCA-aligned infrastructure deployment for continental European access.
Switzerland
Private banking integration of Bitcoin allocation into wealth management mandates attracts ultra-high-net-worth flows. FINMA guidance on crypto-asset custody and anti-money-laundering frameworks provides regulatory clarity. Zug and Zurich cantons concentrate blockchain-native financial infrastructure providers.
Japan
Retail accumulation through exchange-traded products and corporate treasury experimentation drive demand composition. FSA registration requirements for crypto-asset exchanges enforce segregation and cold-storage standards. Tokyo financial district hosts licensed custodians serving institutional mandates under METI policy coordination.
Bitcoin Market Key Industry Players
Capital-heavy mining operators compete with asset-light infrastructure providers across divergent margin structures. The vendor base stratifies between vertically integrated hash-rate aggregators, custody-technology licensors, and regulated financial intermediaries. Three archetypes dominate: treasury-accumulation strategists, ETF-wrapper sponsors, and exchange-custody hybrids. Competitive intensity centers on regulatory licensure acquisition and insurance-backed security frameworks rather than price-based rivalry.
Among treasury-focused accumulators, Strategy exemplifies convertible-debt-funded acquisition models. BlackRock iShares Bitcoin Trust occupies the regulated-wrapper archetype for retirement-account access. Coinbase Global anchors the custody-exchange hybrid tier serving US institutional flows. These three entities represent distinct competitive vectors rather than direct substitutes, each capturing value at different points in the capital-formation chain.
| Leading Market Players |
|---|
| Strategy |
| BlackRock iShares Bitcoin Trust |
| Coinbase Global |
| Binance |
| MARA Holdings |
| Grayscale |
| Fidelity |
| Tether Holdings |
| Galaxy Digital Holdings |
| Others |
Cost & Logistics Intelligence
Carbon neutrality mandates under China's dual carbon goals and the EU's CSRD disclosure requirements gate qualified mining hardware supply and premium-tier custody pricing access. Institutional buyers demanding renewable-attested hashing power and audited reserve backing face contracted supply pools that sustain pricing premiums across compliant infrastructure tiers.
Pricing Analysis
Margin tightening in institutional custody reflects SOC-2 attestation costs and insurance premium escalation. Three-tier pricing structure across premium, standard, and economy levels separates fully audited qualified custodians from exchange-hosted wallets and self-custody solutions. Price differentiation centers on certification level and geographic delivery cost for cold-storage facilities. Cost-down pressure on retail-facing platforms accelerates because of FinCEN compliance staffing ratios. Corporate treasuries exhibit least price sensitivity; retail accumulators through mobile apps demonstrate highest elasticity.
Supply Chain Analysis
ASIC hardware supply rests on Taiwanese semiconductor foundries and Chinese packaging facilities. Mining equipment draws from TSMC wafer allocations, Samsung memory components, and Bitmain design houses. Logistics chokepoints through Shenzhen port clusters and Taiwan Strait shipping lanes concentrate fulfillment risk. Distribution runs through direct manufacturer relationships for large-scale miners and authorized reseller networks for mid-tier operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where SEC qualified custody requirements under the Investment Company Act of 1940 erect barrier-to-entry moats for compliant infrastructure providers.
For Market Incumbents: Anticipate margin compression from MiCA-licensed European entrants by deepening insurance-backed security frameworks and accelerating Taproot-enabled multisignature efficiency upgrades. Convertible-debt-funded accumulators threaten to crowd direct spot demand; anchor relationship pricing for corporate treasury clients through embedded downside-structured products. For New Entrants and Emerging Players: The premium-to-economy custody price gap in Southeast Asian family office segments offers white-space penetration. Target underlicensed jurisdictions where BaFin and FINMA frameworks have not yet captured Mittelstand treasury demand. Lightning Network payment gateway integration provides the most penetrable go-to-market angle for merchant settlement rails. For Investors and Strategic Acquirers: Spot ETF approval velocity is the leading indicator that retirement-account capital formation is accelerating. Long-term viability over the coming decade depends on regulatory licensure durability rather than hardware scale. Acquire custody-technology licensors with MiCA pre-authorization status. Watch FinCEN enforcement action intensity as the signal for compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Licensure Acquisition | MiCA pre-authorization enables continental European custody market access before competitors. |
| Insurance-Backed Security Framework | Lloyd's of London coverage differentiates qualified custodians for pension fiduciary mandates. |
| Lightning Network Integration | Point-of-sale terminal convergence captures merchant settlement volume outside card networks. |
| Convertible Debt Structuring | Fixed-income funded accumulation creates synthetic demand floors through volatility cycles. |
| Renewable Energy Attestation | Carbon-neutral hashing power sourcing satisfies ESG screening for institutional allocators. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with mining facility operators, custody technology architects, and corporate treasury officers combined with SEC disclosure documents, FinCEN enforcement releases, and EU MiCA draft regulations. Bottom-up transaction volume estimates and top-down capital formation aggregates underwent triangulation validation.
Granularity-level modeling captured transaction type, investment phase, user category, and technology adoption stack across the projection horizon. CAGRs derived from regression against institutional allocation mandate velocity and ETF wrapper penetration curves. Hashing power geographic distribution and renewable energy mix assumptions informed supply-side projections throughout the forecast period.
Inputs from exchange volume aggregators and mining pool operators were available through the study window; gaps in self-custodied wallet transaction data introduce uncertainty bands around peer-to-peer settlement estimates. Forecasts reflect assumptions regarding regulatory approval timelines and enforcement intensity. Hashing power relocation patterns and electricity price volatility constitute primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Virtual Currency Market
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Crypto Art Market
Digital Assets and Cryptocurrency Finance
Digital Asset Transaction Market
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
Crypto Automated Teller Machine Market
Digital Assets and Cryptocurrency Finance
Global Non-Fungible Tokens Market
Digital Assets and Cryptocurrency Finance
United States Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Europe Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market
Digital Assets and Cryptocurrency Finance
Global Blockchain in Supply Chain Finance Market
Digital Assets and Cryptocurrency Finance
Global Bitcoin and Cryptocurrency Wallets Market
Digital Assets and Cryptocurrency Finance
Digital Asset Trading Platform Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market