
 Duckweed Market | 2026-2036
Duckweed Market Size, Share, and Industry Trends Forecast 2026-2036
Duckweed Market Analysis
Soy protein concentrate is expanding its addressable cost base as duckweed-derived RuBisCO protein achieves comparable emulsification properties at lower input water intensity. Plantible Foods leverages closed-loop aquaponic architecture to control cultivation variables across its Texas operations. Hinoman Ltd. anchors its competitive position through vertically integrated photobioreactor deployment in Israel. Parabel USA differentiates via patent-protected mechanical dewatering that preserves functional protein fractions.
Duckweed denotes minute free-floating aquatic plants of the Lemnaceae family, typically containing 35-45% crude protein by dry weight with amino acid profiles approaching WHO/FAO reference standards for human nutrition. The organism doubles biomass within 24-48 hours under controlled light and nutrient conditions, enabling continuous harvest cycles that outpace terrestrial crop protein yields per hectare. Wolffia globosa dominates high-protein ingredient pipelines due to its minimal fiber content and neutral flavor matrix. Feed applications sustain the largest volume allocation, though wastewater treatment configurations are attracting capital as nutrient recovery mandates tighten. Direct sales channels control bulk procurement relationships with aquafeed compounders, while online retail extends access to specialty aquarist and research segments.
The EU Green Deal protein strategy and REACH bio-based material classifications are redirecting formulation R&D toward certified aquatic biomass inputs. FDA GRAS self-determination pathways and USDA organic aquaculture standards govern U.S. market entry, with EPA Clean Water Act nutrient credit mechanisms incentivizing cultivation-for-remediation business models. Stakeholders must monitor regulatory convergence between novel food approvals and carbon accounting methodologies to time capacity investments.
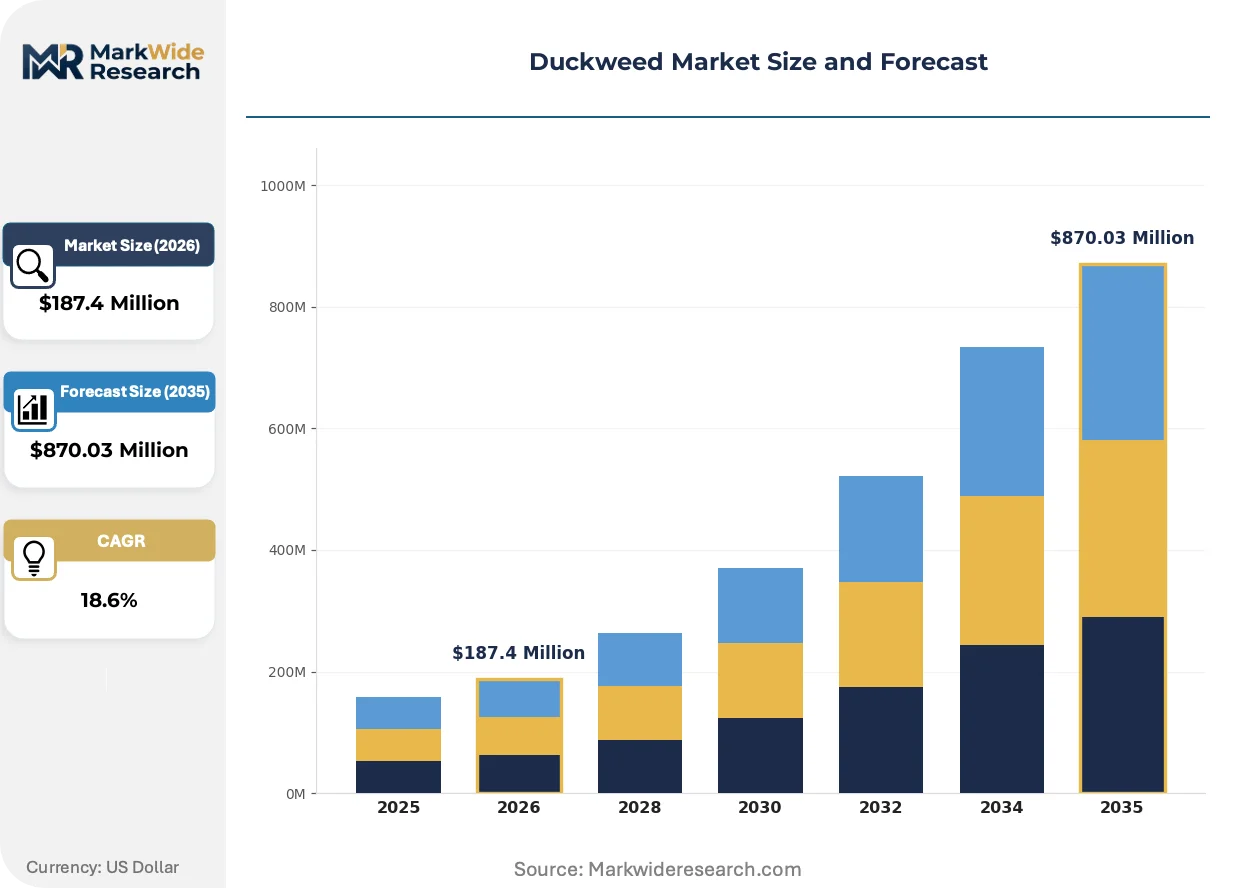
Market Dynamics
The EU Green Deal's protein autonomy mandates are compressing investment timelines for alternative aquatic biomass, redirecting aquafeed formulation R&D from terrestrial soy toward high-yielding duckweed cultivars with superior amino acid density.
Growth Catalysts
- Fishmeal price volatility:Aquaculture feed compounders in Southeast Asia are accelerating duckweed inclusion trials as Peruvian anchovy quotas tighten. Formulators seek protein inputs uncorrelated with marine capture fluctuations.
- REACH bio-based classifications:ECHA's updated material categories incentivize aquatic biomass in EU cosmetic and packaging applications. Certification pathways now favor Lemnaceae-derived ingredients over petroleum alternatives.
- Photobioreactor automation:Closed-loop cultivation systems with real-time nutrient monitoring are collapsing harvest cycle variability. Israeli and Dutch operators deploy sensor arrays that stabilize protein content within narrow specification bands.
Market Restraints
- Input cost concentration:Phosphorus and nitrogen feedstock costs track volatile natural gas pricing, squeezing margins for non-integrated cultivators dependent on commodity chemical suppliers.
- Regulatory fragmentation:Novel food approval timelines diverge sharply between FDA GRAS self-determination pathways and EFSA full-authorization requirements, delaying cross-Atlantic product launches by 18-36 months.
- Substitute protein advancement:Precision-fermented whey and single-cell algae from Perfect Day and Corbion are capturing premium positioning in sports nutrition, constraining duckweed's addressable market at the high-value end.
Strategic Opportunities
- Carbon credit stacking:EPA Clean Water Act nutrient credit mechanisms enable dual-revenue streams from wastewater remediation operations. Cultivators in Texas and Florida monetize phosphorus recovery alongside biomass sales.
- India aquaculture expansion:MPEDA's shrimp production targets and FSSAI's emerging novel food framework create first-mover advantages for protein ingredient suppliers establishing local cultivation partnerships.
- Hybrid aquaponic integration:Convergence of hydroponic vegetable production with duckweed cultivation is reducing system-level water intensity. Dutch greenhouse operators pilot combined facilities serving retail and feed channels simultaneously.
Industry Challenges
- Downstream processing bottlenecks:Mechanical dewatering equipment capable of preserving functional protein fractions remains concentrated among specialized Israeli and US engineering firms, creating equipment procurement queues.
- Novel food dossier complexity:EFSA's requirement for 90-day toxicology studies and compositional equivalence data demands capital reserves that strain early-stage cultivators without pharmaceutical partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duckweed Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lemna minor, Wolffia globosa, Spirodela polyrhiza, Landoltia punctata Application: Aquaculture, Wastewater Treatment, Feed, Biofuel Production Distribution Channel: Direct Sales, Online Retail, Wholesale, Export End User: Agriculture, Environmental Agencies, Research Institutions, Aquarists |
| Companies Covered | Plantible Foods, Parabel USA, Cargill, Barentz Bio Healthife, GreenOnyx, Archer Daniels Midland (ADM), Hinoman Ltd., LemnaPro, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duckweed Market Emerging Trajectories
Photobioreactor engineering and automated harvesting systems are collapsing the cost gap between aquatic and terrestrial protein production, while regulatory frameworks increasingly recognize biomass cultivation as a qualifying carbon removal activity.
Closed-loop aquaponic architecture is consolidating competitive advantage for operators achieving continuous harvest cycles. Texas-based facilities deploy integrated sensor networks that synchronize light, temperature, and nutrient delivery. Aquafeed compounders in the Netherlands and Israel now specify protein concentrates from controlled-environment cultivation over open-pond alternatives. This technology is consolidating procurement relationships around cultivators with demonstrated batch-to-batch consistency.
EU Green Deal protein autonomy targets are mandating public procurement preference for domestically produced alternative proteins. Member state agricultural ministries are redirecting CAP innovation funds toward aquatic biomass demonstration projects. Dutch and Danish aquafeed manufacturers face binding inclusion targets for EU-sourced ingredients by 2030, accelerating local cultivation partnerships.
Compound feed buyers are consolidating procurement around vertically integrated suppliers with certified carbon accounting. Large salmon and shrimp producers in Norway and Vietnam now require scope 3 emissions documentation from ingredient vendors. This specification shift favors duckweed operators with validated life-cycle assessments over commodity traders lacking cultivation traceability.
Duckweed Market Segmentation
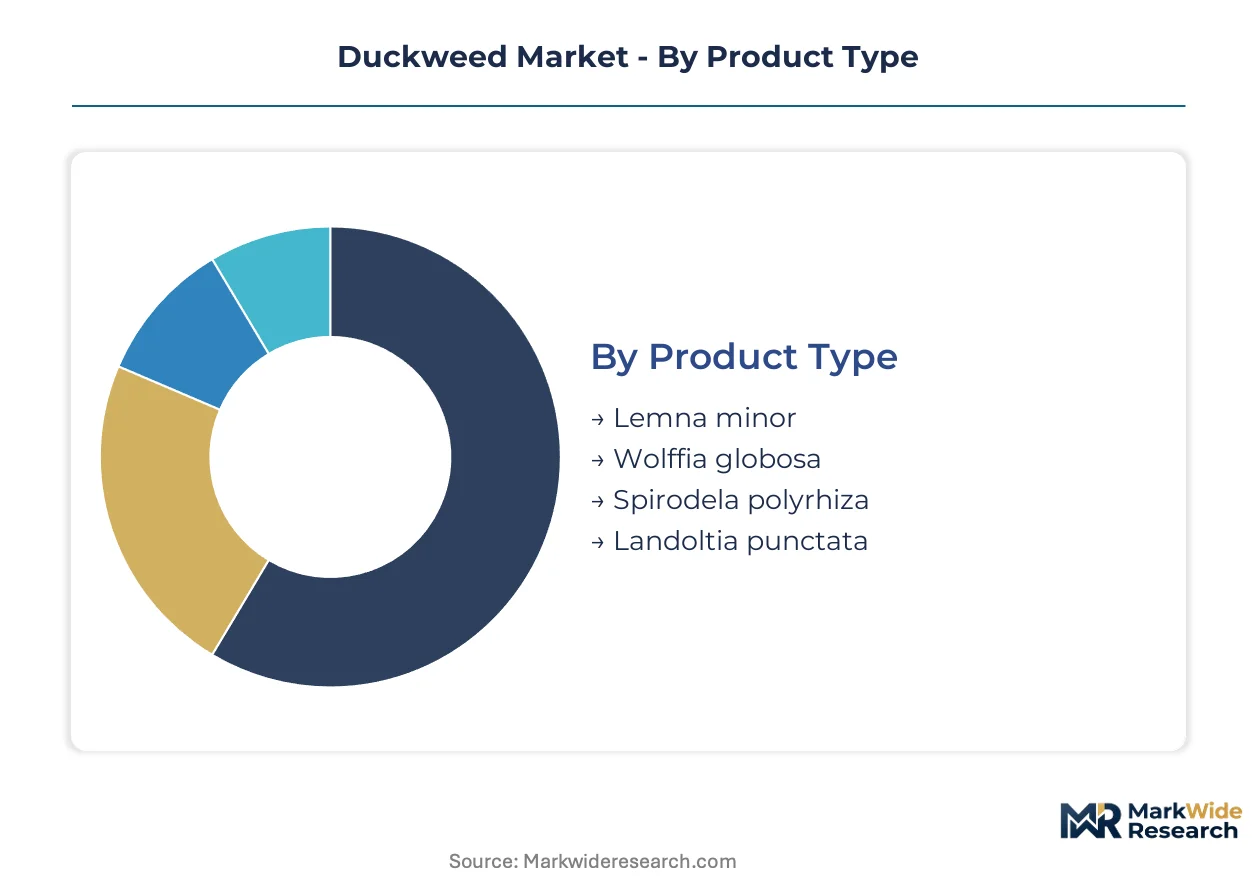
Segmentation in duckweed markets reveals how protein concentration, cultivation system requirements, and regulatory pathways fragment commercial opportunity. Suppliers align product development with specific end-use specifications rather than pursuing undifferentiated biomass sales.
Product Type:
Supply concentration in high-protein cultivars is reshaping competitive positioning among species specialists.
- Wolffia globosa:Minimal fiber content and neutral flavor matrix enable food-grade protein concentrate production. Dutch food-tech clusters and Israeli photobioreactor operators prioritize this species for human nutrition applications due to its WHO/FAO-aligned amino acid profile.
- Lemna minor:Established feed-grade biomass with documented digestibility in carp and tilapia diets. Southeast Asian aquafeed compounders in Vietnam and Thailand source this cultivar for cost-sensitive inclusion trials displacing fishmeal.
- Spirodela polyrhiza:Higher starch content suits bioethanol fermentation pathways. US Gulf Coast operators target this species for integrated biorefinery configurations.
- Landoltia punctata:Rapid colonization properties serve phytoremediation contractors. Florida and Texas wastewater treatment facilities deploy this species for nutrient credit generation.
Wolffia globosa absorbs the bulk of installed capacity; Landoltia punctata is expanding most quickly.
Application:
Cost tier differentiation separates commodity feed inclusion from premium functional ingredients.
- Aquaculture:Protein concentrates and whole biomass meals replace fishmeal in salmon, shrimp, and carp diets. Norwegian and Vietnamese producers now require scope 3 emissions documentation, favoring certified duckweed suppliers over commodity traders.
- Wastewater Treatment:Nutrient recovery mandates under EPA Clean Water Act and EU Urban Wastewater Treatment Directive create dual-revenue cultivation models. Texas operators monetize phosphorus credits alongside biomass sales.
- Feed:Poultry and livestock inclusion trials accelerate as soy protein concentrate prices fluctuate. Dutch compounders test duckweed in layer hen diets for omega-3 enrichment.
- Biofuel Production:Starch-to-ethanol pathways remain pre-commercial. Israeli pilot facilities explore lipid extraction for renewable diesel co-products.
Aquaculture commands the dominant revenue share; wastewater treatment is climbing the fastest.
Distribution Channel:
Customer type determines channel economics, with bulk procurement relationships controlling margin capture.
- Direct Sales:Long-term supply agreements with aquafeed compounders and integrators. Dutch and Israeli operators secure multi-year contracts specifying protein content and carbon intensity thresholds.
- Wholesale:Aggregators serve mid-scale aquaculture operations and regional feed mills. Southeast Asian traders consolidate smallholder production for export to European compounders.
- Online Retail:Specialty aquarist and research laboratory segments. US-based suppliers target home aquarium enthusiasts and university biology departments.
- Export:Cross-border shipments of dried biomass and protein concentrates. Indian operators pursue FSSAI novel food framework alignment for EU and Middle East market entry.
Direct sales absorbs the bulk of installed capacity; export channels are expanding most quickly.
End User:
Application maturity varies sharply across user categories, with regulatory readiness dictating adoption timelines.
- Agriculture:Commercial aquaculture and livestock operations drive volume demand. Vietnamese shrimp producers and Norwegian salmon integrators specify certified sustainable ingredients.
- Environmental Agencies:Municipal utilities and watershed districts deploy cultivation-for-remediation. Florida DEP and Texas Commission on Environmental Quality pilot nutrient credit trading mechanisms.
- Research Institutions:Universities and government laboratories advance cultivar optimization. Wageningen University and Ben-Gurion University of the Negev lead photobioreactor engineering programs.
- Aquarists:Hobbyist and ornamental fish markets represent niche volume. Online retailers serve this segment with live culture shipments.
Agriculture absorbs the bulk of installed capacity; environmental agencies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in controlled-environment agriculture clusters where food-tech incubators overlap with aquafeed manufacturing infrastructure. The Netherlands anchors procurement relationships through greenhouse-integrated cultivation pilots. Investment timelines compress where protein autonomy mandates intersect with established compounder networks.
Netherlands
Wageningen University research partnerships and greenhouse operator consortiums drive cultivar optimization for aquafeed inclusion. The EU Green Deal protein autonomy targets redirect CAP innovation funds toward aquatic biomass demonstration projects. Dutch compounders in the Randstad region pilot multi-year supply agreements specifying protein content thresholds and scope 3 emissions documentation.
Israel
Photobioreactor engineering expertise and water-scarcity adaptation create competitive advantage in high-value protein concentrate production. Ben-Gurion University of the Negev leads automated harvesting system development with commercialization support from the Israel Innovation Authority. Operators in the Negev Desert deploy sensor arrays stabilizing batch-to-batch consistency for export to European compounders.
United States
EPA Clean Water Act nutrient credit mechanisms incentivize cultivation-for-remediation business models in phosphorus-impaired watersheds. Texas and Florida operators monetize dual-revenue streams from wastewater treatment alongside biomass sales. The USDA organic aquaculture standards and FDA GRAS self-determination pathways govern market entry for human nutrition applications.
India
MPEDA shrimp production targets and FSSAI's emerging novel food framework create first-mover advantages for protein ingredient suppliers. Andhra Pradesh and Gujarat aquaculture belts seek certified sustainable inputs displacing fishmeal in formulated diets. Local cultivation partnerships target alignment with EU import requirements for cross-border concentrate shipments.
Vietnam
Catfish and shrimp export quotas to European markets drive specification shifts toward scope 3-documented ingredients. Mekong Delta integrators trial duckweed inclusion rates in commercial diets as Peruvian anchovy price volatility disrupts traditional formulation economics. The Ministry of Agriculture and Rural Development supports demonstration projects linking smallholder cultivators to compounder procurement networks.
Duckweed Market Vendor Landscape
Capacity expansion dominates the current landscape as operators deploy photobioreactor automation to collapse harvest cycle variability. The vendor base stratifies across three tiers: vertically integrated cultivators with proprietary cultivation architecture, ingredient aggregators serving mid-scale compounders, and research-stage specialists pursuing novel food authorizations. Israeli and Dutch operators anchor the premium tier through controlled-environment consistency. Competitive moves concentrate on backward integration into phosphorus recovery infrastructure and technology licensing agreements transferring cultivation protocols to new geographies.
Among North American cultivators, Plantible Foods exemplifies closed-loop aquaponic architecture deployment, while Parabel USA occupies a position within patent-protected mechanical processing specialists. Hinoman Ltd. represents the Israeli photobioreactor engineering archetype with integrated cultivation and concentrate production. These three entities anchor procurement relationships with aquafeed compounders requiring documented carbon intensity and batch-to-batch protein specification compliance.
| Leading Market Players |
|---|
| Plantible Foods |
| Parabel USA |
| Cargill |
| Barentz Bio Healthife |
| GreenOnyx |
| Archer Daniels Midland (ADM) |
| Hinoman Ltd. |
| LemnaPro |
| DSM-Firmenich |
| Others |
Supply Flow & Price Mechanics
Aquafeed compounder procurement concentration in the Netherlands and Israel anchors contract-based long-term offtake pricing with protein content and carbon intensity specifications. Dutch greenhouse operators and Israeli photobioreactor cultivators capture margin premiums through batch-to-batch consistency guarantees that commodity open-pond suppliers cannot match.
Pricing Analysis
Volume allocations concentrate in economy-tier whole biomass meals for Southeast Asian aquafeed trials, while margin capture concentrates in premium-tier protein concentrates for European human nutrition applications. Price differentiation rests on certification grade (EU organic, FDA GRAS self-determination status) and cultivation system traceability. Cost compression in feed-grade biomass is intensifying as Peruvian anchovy price volatility accelerates fishmeal substitution trials. Contract feed compounders in Vietnam and Norway exhibit lowest price sensitivity due to scope 3 emissions documentation requirements, while smallholder cultivators in India face highest sensitivity to phosphorus input cost fluctuations.
Supply Chain Analysis
EU Green Deal domestic-content mandates for protein autonomy are redirecting compounder procurement toward certified European cultivators and select Israeli operators with validated carbon accounting. Geographic supply concentration centers on the Netherlands, Israel, and Texas, with emerging capacity in Andhra Pradesh and Gujarat. Raw material dependencies draw from phosphorus recovery infrastructure, nitrogen feedstock, and photobioreactor automation equipment. Single-source vulnerability in mechanical dewatering technology—concentrated among specialized Israeli and US engineering firms—creates equipment procurement queues. Distribution runs through direct sales channels controlling multi-year supply agreements with aquafeed compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photobioreactor engineering capacity bottlenecks prop pricing premiums for controlled-environment cultivators with demonstrated batch consistency. Supply constraints in automated harvesting equipment extend lead times for new entrants seeking premium tier positioning.
For Market Incumbents: To counter precision-fermented whey and single-cell algae substitutes from Perfect Day and Corbion, incumbents must deepen backward integration into phosphorus recovery infrastructure and secure exclusive equipment licensing agreements with Israeli photobioreactor engineering specialists. Capacity addition in Texas and Florida EPA Clean Water Act nutrient credit zones reinforces dual-revenue model defensibility.
For New Entrants and Emerging Players: The premium-economy price-point gap in Indian aquaculture feed applications offers first-mover positioning before FSSAI novel food framework maturation. White-space targets include Andhra Pradesh shrimp producer partnerships and Gujarat carp integrator trials. A cultivation-for-remediation go-to-market angle leveraging state-level nutrient credit mechanisms enables revenue diversification during novel food dossier preparation.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated operators with proprietary photobioreactor architecture and validated EU organic certification. Long-term viability hinges on regulatory convergence between novel food approvals and carbon accounting methodologies. Acquisition target archetype: Israeli or Dutch cultivators with demonstrated batch-to-batch protein specification compliance and existing compounder procurement relationships. The signal to monitor is EFSA authorization timeline compression for Lemnaceae-derived ingredients.
| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Automation Scale-Up | Collapses harvest cycle variability for Israeli and Dutch operators serving EU compounders. |
| Phosphorus Recovery Infrastructure | Captures EPA Clean Water Act nutrient credits alongside biomass sales in Texas watersheds. |
| EFSA Novel Food Dossier Submission | Unlocks premium human nutrition positioning ahead of regulatory pathway divergence. |
| Indian Cultivation Partnership | Aligns with MPEDA shrimp targets and FSSAI framework emergence for export market entry. |
| Carbon Accounting Certification | Satisfies Norwegian and Vietnamese salmon integrator scope 3 emissions documentation requirements. |
Methodological Framework
Multi-period observation of fishmeal price volatility, Peruvian anchovy quota fluctuations, and EU Green Deal protein autonomy fund disbursements anchored the trend analysis, supplemented by interviews with aquafeed formulation directors, photobioreactor engineering specialists, regulatory affairs leads at novel food applicants, and wastewater treatment facility procurement officers. Secondary validation drew from EPA Clean Water Act nutrient credit registries, EFSA novel food authorization databases, FSSAI emerging framework disclosures, and EU CAP innovation fund allocation records. Bottom-up cultivation capacity estimates triangulated against top-down aquafeed protein demand projections.
Input-output matrix modeling connected species-specific protein yields to end-use application requirements across the projection horizon. Segmentation dimensions included Wolffia globosa versus Lemna minor cultivar selection, aquaculture versus wastewater treatment versus human nutrition application tiers, and direct sales versus wholesale versus export channel structures. CAGRs derived from slope analysis of installed photobioreactor capacity against compounder procurement specification shifts. Industry-specific forecast inputs incorporated EFSA authorization timeline assumptions and EPA nutrient credit pricing trajectories.
Underlying measurement precision varies by segment; controlled-environment cultivation data carries tighter precision than open-pond smallholder production estimates. Forecasts reflect assumptions regarding regulatory convergence timelines and fishmeal price correlation persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Folding Mobile Phone Market
Others
Channel-In-A-Box (Ciab) Market
Others
Europe Polycarbonate Sheets Market
Others
North America Medical Simulation Market
Others
8K Technology Market
Others
Europe Street Lighting Market
Others
Global Military Wearable Sensors Market
Others
Photo Booth/Kiosk Market
Others
United States Bean Bags Market
Others
Global Military Lighting Market
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Australia Content Services Platform Market
Others
Global Simulation in Healthcare Market
Others
Prunes Market
Others
Air Separation Plant Market
Others
Hopper Dryers Market