
 Bipolar Disorder Therapeutics Market | 2026-2036
Bipolar Disorder Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Bipolar Disorder Therapeutics Market Analysis
A shift from single-source API procurement to multi-source active pharmaceutical ingredient agreements is realigning supply security for bipolar disorder therapeutics. Johnson & Johnson leverages its long-acting injectable platform to sustain formulary dominance across hospital and clinic channels. Eli Lilly and Company anchors its position through specialized R&D in mood disorder neuroscience. AbbVie competes via backward integration into generic anticonvulsant production, controlling cost structures for maintenance therapy portfolios.
Bipolar disorder therapeutics comprise pharmacological agents designed to modulate neurotransmitter systems—principally dopamine, serotonin, and glutamate pathways—to stabilize mood oscillations between manic and depressive poles. These compounds are formulated as small molecules, biologics, and extended-release depot formulations for chronic administration in psychiatric care. Antipsychotics occupy the largest revenue pool within product type segmentation, driven by second-generation agent prescribing in acute manic episodes. Injectable delivery mode represents the fastest-expanding structural category, as healthcare systems prioritize adherence monitoring and reduced relapse rates. Maintenance treatment within therapy area segmentation concentrates margin pools, reflecting the chronic relapsing nature of bipolar I and II disorders.
The FDA governs new drug approvals and post-market surveillance for bipolar therapeutics through its Division of Psychiatry Products, while the DEA schedules controlled substances including certain mood stabilizers and anticonvulsants. EMA's centralized marketing authorization procedure shapes parallel demand patterns across European member states, particularly for generic substitution policies. Stakeholders must monitor evolving pharmacovigilance requirements for suicidality risk labeling and the integration of digital therapeutics into combination treatment protocols.
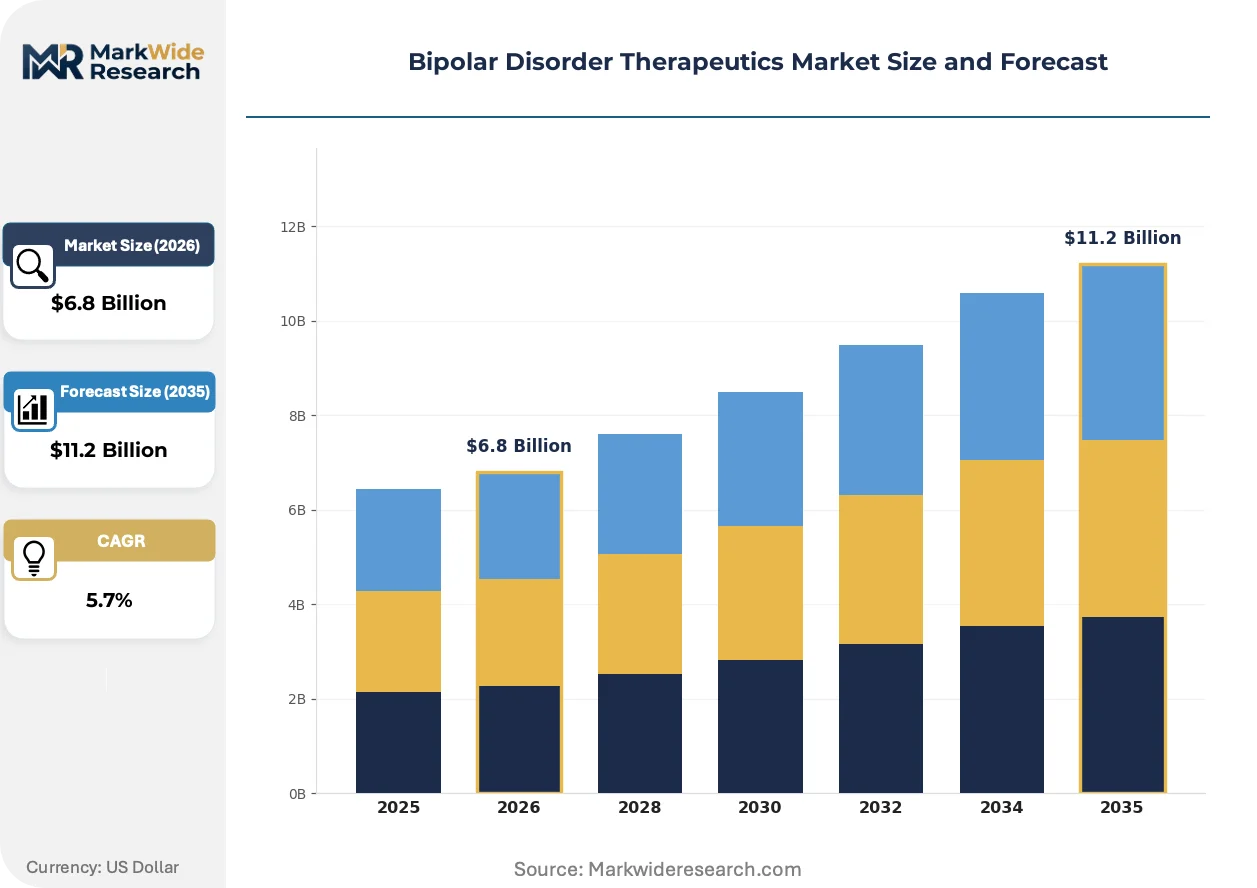
Market Dynamics
Hospital-based psychiatric units are consolidating formulary decisions around long-acting injectable antipsychotics, compressing prescribing autonomy for individual clinicians and concentrating procurement authority within pharmacy and therapeutics committees.
Growth Catalysts
- Medicare Part D expansion:Broader coverage for bipolar maintenance therapy under commercial and federal payer frameworks is pulling demand toward outpatient chronic care models in the United States.
- Digital therapeutics integration:FDA breakthrough device designations for adjunctive digital interventions are creating parallel reimbursement pathways alongside pharmacological treatment.
- Multi-source API contracting:Supply security agreements spanning three or more active pharmaceutical ingredient suppliers are reducing stockout risk for mood stabilizer production.
Market Restraints
- Lithium carbonate supply concentration:Chilean and Australian brine extraction operations control over seventy percent of raw material for first-line mood stabilization, exposing formulators to geopolitical and climate-linked disruption.
- EMA pharmacovigilance tightening:Enhanced suicidality risk labeling requirements for anticonvulsant-class mood stabilizers are extending regulatory review timelines and constraining label expansion opportunities.
- Generic antipsychotic substitution:Bioequivalence-driven pharmacy-level substitution of oral second-generation antipsychotics is compressing branded maintenance therapy margins.
Strategic Opportunities
- Depot formulation expansion:Three-month and six-month extended-release injectable platforms address adherence gaps in bipolar I maintenance populations previously managed with monthly injections.
- EMA centralized pediatric indications:PIP-compliant development pathways for adolescent bipolar disorder are opening exclusivity extensions and orphan-like market protection in European member states.
- Telepsychiatry channel integration:Direct-to-patient medication management platforms are capturing prescription flow from traditional office-based psychiatric practices.
Industry Challenges
- Psychopharmacology trial recruitment:Stringent DSM-5 diagnostic confirmation and mood episode stability requirements are slowing enrollment velocity for maintenance-phase studies.
- Legacy EHR interoperability:Proprietary data architectures in hospital psychiatric units are blocking seamless integration of digital therapeutic outcome tracking with pharmacy dispensing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bipolar Disorder Therapeutics Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antipsychotics, Mood Stabilizers, Antidepressants, Anticonvulsants Delivery Mode: Injectable, Oral, Transdermal, Intranasal End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Therapy Area: Manic Episodes, Depressive Episodes, Mixed Episodes, Maintenance Treatment |
| Companies Covered | Johnson & Johnson, Eli Lilly and Company, AbbVie, Pfizer, GSK, Bristol-Myers Squibb, Otsuka Pharmaceutical, Intra-Cellular Therapies, Lundbeck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bipolar Disorder Therapeutics Market Emerging Trajectories
Neuroscience-driven drug discovery platforms are converging with real-world evidence generation systems, compressing the traditional gap between mechanistic hypothesis and clinical validation in mood disorder therapeutics.
Pharmacogenomic testing for CYP2D6 and CYP2C19 metabolic phenotypes is converging with antipsychotic prescribing workflows. Academic medical centers and large integrated delivery networks are embedding combinatorial pharmacogenomic panels into pre-prescription decision support. This convergence is compressing trial-and-error titration periods and reducing emergency department encounters for adverse metabolic events.
FDA's accelerated approval pathway for novel mood stabilizers is requiring surrogate endpoint validation through digital biomarker platforms. Sponsors must now demonstrate correlation between wearable-derived sleep-wake cycle metrics and subsequent manic episode reduction. This regulatory architecture is favoring development programs that integrate actigraphy and smartphone-based ecological momentary assessment from Phase II initiation.
Specialty pharmacy distribution is displacing traditional retail channels for long-acting injectable antipsychotics. Payer-mandated hub models require patient enrollment in adherence monitoring programs prior to dispensation. This channel shift is most visible in United States commercial insurance frameworks, where pharmacy benefit managers are extracting rebates tied to injection compliance documentation.
Bipolar Disorder Therapeutics Market Segmentation
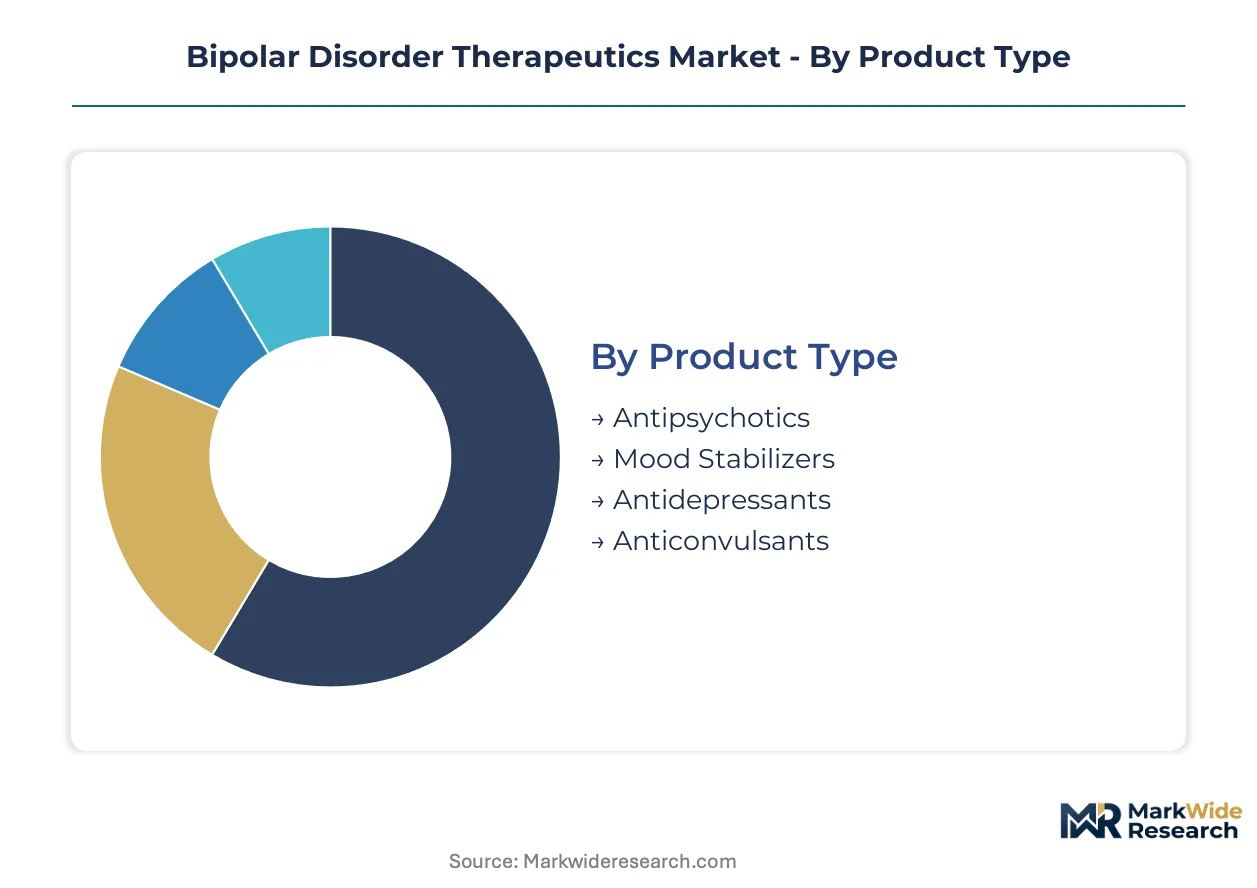
Segmentation in bipolar disorder therapeutics reveals how formulation technology, care setting economics, and episode-specific clinical protocols fragment procurement decisions across psychiatric care networks. Understanding these divides exposes where pricing power concentrates and where generic substitution erodes margin.
Product Type:
Supply concentration for active pharmaceutical ingredients varies sharply across pharmacological classes, with some segments dependent on single-source extraction while others enjoy multi-continent manufacturing redundancy.
- Antipsychotics:Second-generation agents targeting dopamine D2 and serotonin 5-HT2A receptors dominate acute manic episode management. Hospital formulary committees in the United States concentrate procurement authority around long-acting injectable versions, compressing prescribing autonomy for individual clinicians.
- Mood Stabilizers:Lithium carbonate and lamotrigine modulate glutamate and GABA signaling to prevent episode recurrence. Chilean and Australian brine extraction operations control over seventy percent of lithium raw material, exposing formulators to geopolitical and climate-linked disruption.
- Antidepressants:Selective serotonin reuptake inhibitors and related compounds require cautious deployment in bipolar populations due to mania induction risk. FDA's Division of Psychiatry Products mandates specific suicidality risk labeling that constrains promotional claims.
- Anticonvulsants:Valproate and carbamazepine derivatives serve dual indications in seizure and mood disorders. EMA pharmacovigilance tightening around teratogenicity and hepatic toxicity has extended regulatory review timelines across European member states.
Today's leader: Antipsychotics. Tomorrow's challenger: Mood Stabilizers.
Delivery Mode:
Cost tier stratification separates premium-priced depot formulations from commoditized oral generics, with reimbursement frameworks determining accessible therapy levels for insured and uninsured populations.
- Injectable:Extended-release depot formulations spanning one-month to six-month dosing intervals address adherence gaps in bipolar I maintenance populations. Specialty pharmacy distribution channels in United States commercial insurance frameworks mandate hub-based adherence monitoring prior to dispensation.
- Oral:Immediate-release and extended-release tablets dominate first-line prescribing in outpatient psychiatric practices. Bioequivalence-driven pharmacy-level substitution compresses branded maintenance therapy margins across Medicare Part D formularies.
- Transdermal:Patch-based delivery systems offer steady-state plasma concentrations with reduced gastrointestinal adverse events. Manufacturing complexity and limited approved indications restrict penetration to niche populations with oral intolerance.
- Intranasal:Rapid-acting formulations targeting acute agitation and breakthrough episodes leverage nasal mucosa absorption kinetics. DEA scheduling requirements for controlled substances impose distribution restrictions that limit retail pharmacy stocking.
Injectable platforms command premium pricing. Oral formulations face steepest margin compression.
End User:
Volume concentration in institutional settings creates procurement leverage that individual practitioners cannot replicate, shifting margin capture toward centralized pharmacy and therapeutics committees.
- Hospitals:Inpatient psychiatric units and emergency departments manage acute manic and mixed episodes requiring rapid behavioral stabilization. Consolidated formulary decisions around long-acting injectable antipsychotics concentrate purchasing authority within pharmacy departments.
- Clinics:Outpatient psychiatric practices and community mental health centers handle maintenance-phase prescribing and medication management. Telepsychiatry channel integration is capturing prescription flow from traditional office-based practices.
- Homecare:Visiting nurse services administer long-acting injectables to patients with transportation barriers or severe functional impairment. Payer-mandated documentation requirements for injection compliance extract rebates tied to adherence metrics.
- Rehabilitation Centers:Residential and day-treatment programs focus on psychosocial rehabilitation for patients with recurrent hospitalization histories. Limited on-site pharmacy infrastructure drives reliance on external specialty pharmacy networks.
Hospital procurement dominates acute episode revenue. Homecare represents the fastest-climbing trajectory for maintenance therapy administration.
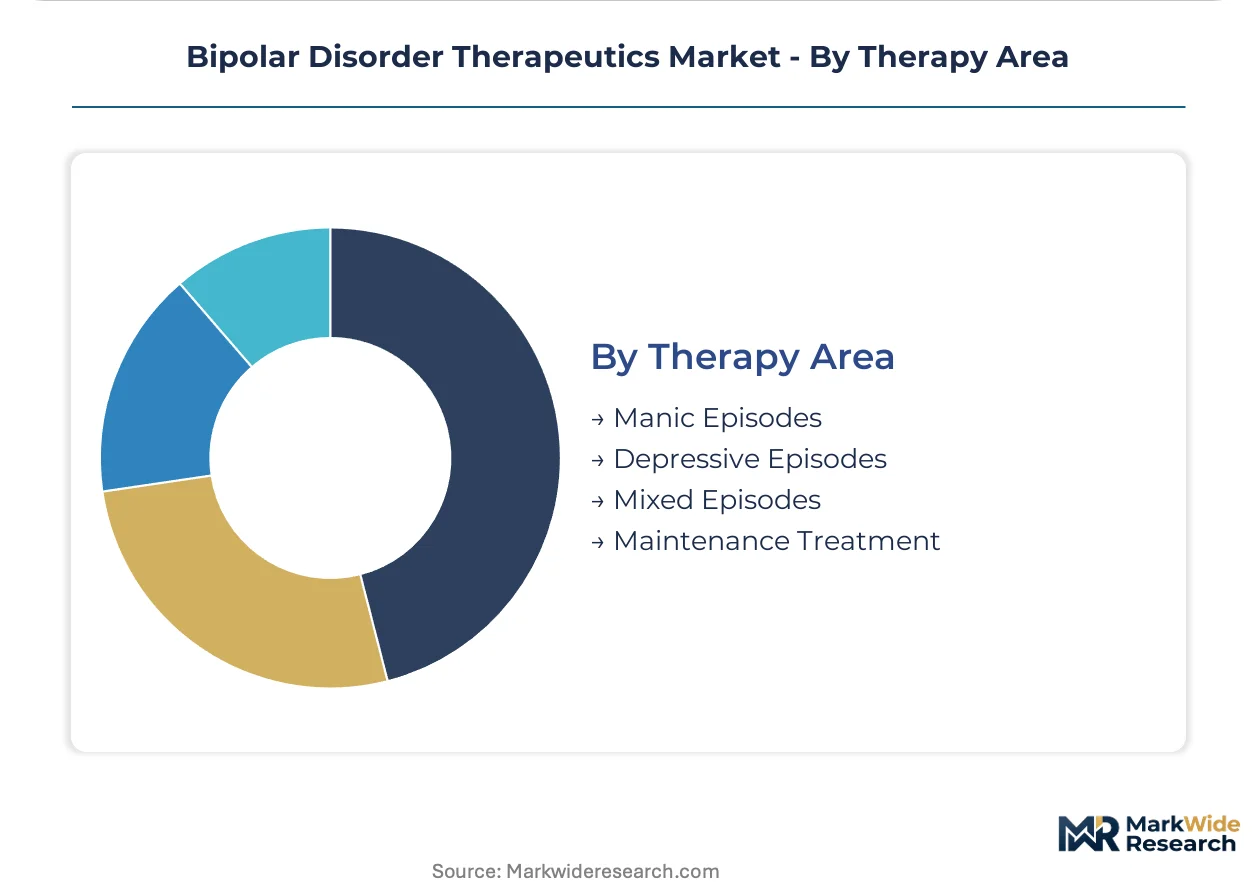
Therapy Area:
Margin maturity diverges between acute intervention markets with generic saturation and chronic maintenance segments where long-acting formulations sustain pricing power through adherence-linked outcomes contracts.
- Maintenance Treatment:Long-term pharmacological prophylaxis against manic and depressive episode recurrence constitutes the largest revenue pool. The chronic relapsing nature of bipolar I and II disorders concentrates margin in formulations demonstrating reduced hospitalization rates.
- Manic Episodes:Acute behavioral stabilization requires rapid-acting antipsychotics and benzodiazepine adjuncts in emergency and inpatient settings. Generic availability of oral second-generation antipsychotics has compressed branded pricing in this indication.
- Depressive Episodes:Bipolar depression presents distinct therapeutic challenges from unipolar depression, with FDA-approved options limited to specific antipsychotic and anticonvulsant combinations. Lurasidone and cariprazine hold indication-specific exclusivity in this underserved segment.
- Mixed Episodes:Simultaneous manic and depressive symptomatology requires careful pharmacological selection to avoid mood state exacerbation. Diagnostic complexity under DSM-5 criteria creates enrollment challenges for clinical trials targeting this population.
Maintenance Treatment anchors revenue stability. Bipolar depression offers the steepest expansion trajectory for novel mechanism agents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Massachusetts biotech corridor concentrates psychiatric drug development infrastructure, with FDA's Division of Psychiatry Products headquartered in Silver Spring anchoring regulatory precedent for mood disorder therapeutics worldwide.
United States
Medicare Part D expansion for bipolar maintenance therapy and commercial payer coverage broadening are pulling demand toward outpatient chronic care models. FDA accelerated approval pathways for novel mood stabilizers are reshaping clinical trial design and commercialization timelines. The Boston-Cambridge cluster hosts Intra-Cellular Therapies and multiple neuroscience-focused biotechs developing next-generation antipsychotics.
Germany
EMA centralized marketing authorization procedures shape parallel demand patterns across European member states, particularly for generic substitution policies. Federal Institute for Drugs and Medical Devices (BfArM) pharmacovigilance requirements for suicidality risk labeling influence continental regulatory standards. The Rhine-Main pharmaceutical manufacturing belt, centered on Frankfurt and Darmstadt, hosts production facilities for mood stabilizer active pharmaceutical ingredients.
Japan
PMDA streamlined review pathways for psychiatric indications are accelerating market entry for novel antipsychotic formulations. Ministry of Health, Labour and Welfare reimbursement listings for long-acting injectables are expanding hospital formulary adoption. The Kansai region around Osaka anchors domestic pharmaceutical manufacturing, with Otsuka Pharmaceutical headquartered there driving regional R&D concentration in mood disorder therapeutics.
United Kingdom
NHS England specialized commissioning frameworks for severe mental illness are consolidating procurement authority for bipolar maintenance therapies. MHRA post-Brexit regulatory autonomy is diverging from EMA centralized procedures on pharmacogenomic labeling requirements. The Golden Triangle between London, Cambridge, and Oxford concentrates academic psychiatry research and early-phase clinical trial infrastructure.
India
CDSCO accelerated approval tracks for psychiatric generics are expanding domestic manufacturing capacity for mood stabilizer APIs. Production-linked incentive schemes for active pharmaceutical ingredients are reducing import dependence on Chinese and European suppliers. The Hyderabad-Visakhapatnam pharmaceutical corridor is emerging as a contract manufacturing hub for anticonvulsant-class mood stabilizers.
Bipolar Disorder Therapeutics Market Vendor Landscape
Global majors compete with regional champions across regulatory sophistication and formulation technology, with hospital formulary consolidation favoring players with integrated long-acting injectable platforms. Market structure tiers between diversified pharmaceutical conglomerates with psychiatric portfolios and specialized neuroscience biotechs focused on mechanism-driven discovery. Three archetypes dominate: large-cap integrated players with depot formulation expertise, mid-cap specialists in mood disorder mechanisms, and generic manufacturers with backward-integrated API control. Competitive intensity centers on M&A activity targeting digital therapeutic adjacencies and strategic partnerships bridging pharmacogenomic testing with prescribing workflows.
Within the diversified pharmaceutical tier, Johnson & Johnson and Eli Lilly and Company exemplify contrasting strategic positions—one leveraging long-acting injectable infrastructure across hospital and clinic channels, the other anchoring through specialized R&D in mood disorder neuroscience. AbbVie occupies a distinct archetype through upstream control over generic anticonvulsant production, enabling cost structure management for maintenance therapy portfolios. These three represent the dominant competitive vectors shaping formulary access and pricing dynamics.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Eli Lilly and Company |
| AbbVie |
| Pfizer |
| GSK |
| Bristol-Myers Squibb |
| Otsuka Pharmaceutical |
| Intra-Cellular Therapies |
| Lundbeck |
| Others |
Supply Flow & Price Mechanics
FDA's accelerated approval pathway for novel mood stabilizers gates qualified supply access and premium-tier pricing power, as sponsors must demonstrate digital biomarker correlation to secure favorable reimbursement positioning against generic oral alternatives.
Pricing Analysis
Input-cost pass-through from Chilean and Australian lithium brine extraction operations drives pricing volatility for first-line mood stabilizer portfolios. Three-tier pricing structure across premium depot injectables, standard extended-release oral formulations, and economy generic tablets reflects adherence-monitoring bundling and FDA breakthrough designation status. Pricing pressure stems from bioequivalence-driven pharmacy substitution of oral second-generation antipsychotics under Medicare Part D formularies. Hospital procurement committees exhibit lowest price sensitivity due to outcomes-based contracts linking reduced readmission rates to formulary premium acceptance.
Supply Chain Analysis
Single-source vulnerability sits with Chilean and Australian brine extraction operations controlling over seventy percent of lithium carbonate raw material for mood stabilizer production. Active pharmaceutical ingredient manufacturing draws from India, China, and the United States for antipsychotic and anticonvulsant synthesis. Lithium carbonate, lamotrigine intermediates, and long-acting injectable polymer matrices constitute critical input dependencies. Tariff exposure on Chinese-sourced anticonvulsant precursors threatens cost structure stability for generic maintenance therapy portfolios. Distribution runs through specialty pharmacy hub models mandating adherence documentation prior to long-acting injectable dispensation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
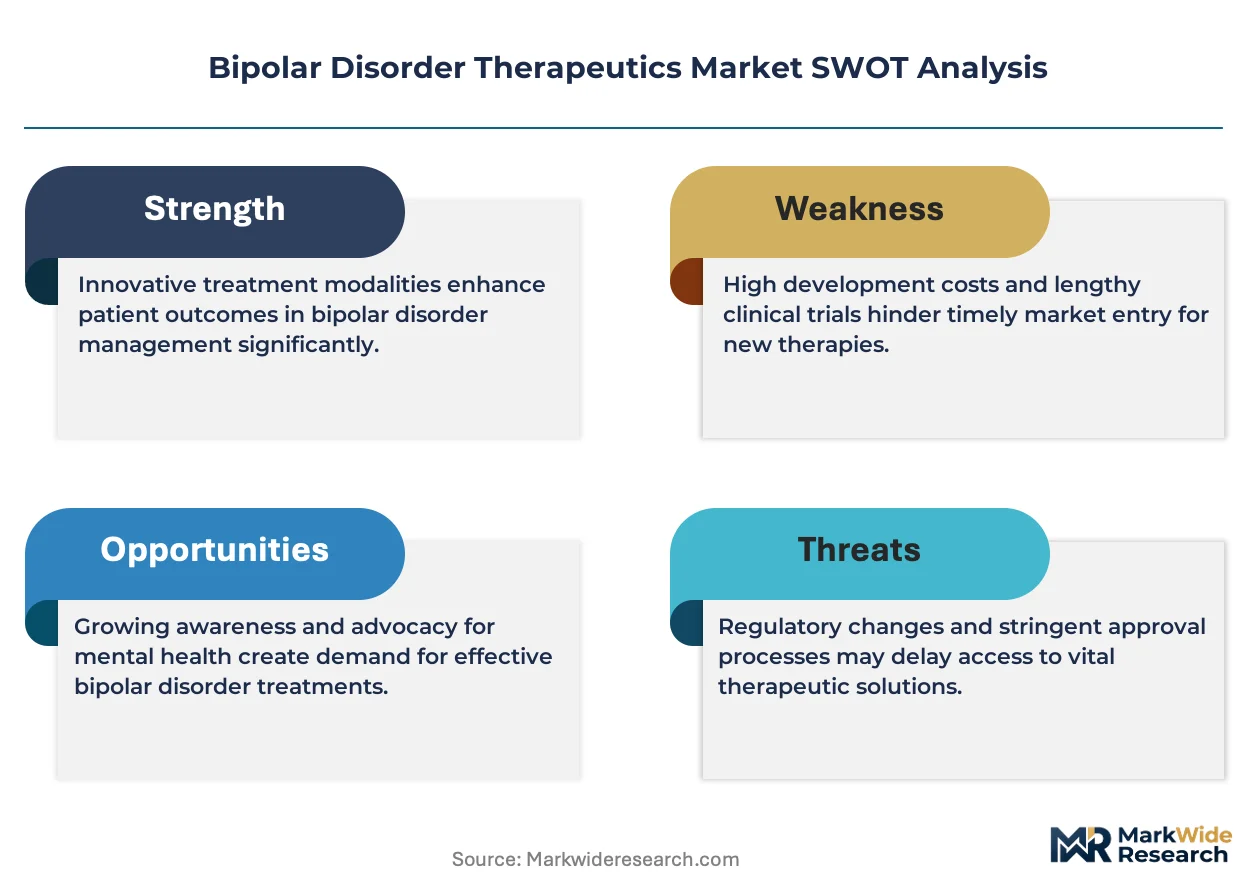
Bipolar disorder therapeutics present a margin-expansion story anchored by depot formulation premiumization and multi-source API contracting that compresses input cost volatility for maintenance therapy portfolios.
For Market Incumbents: Hedge against generic antipsychotic substitution by deepening backward integration into lithium extraction partnerships and securing DEA quota allocations for controlled intranasal formulations. Prioritize pharmacogenomic testing alliances that embed CYP2D6 screening into pre-prescription workflows, locking in prescriber loyalty through reduced adverse event liability. For New Entrants and Emerging Players: Capture the bipolar depression indication gap where lurasidone and cariprazine hold limited competition, leveraging FDA breakthrough device designation pathways for adjunctive digital therapeutic combinations. Target adolescent populations through PIP-compliant European development tracks that open exclusivity extensions and orphan-like market protection. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap neuroscience biotechs with Phase II mood stabilizer assets lacking depot formulation infrastructure. Long-term viability hinges on successful integration of real-world evidence generation systems with wearable-derived digital biomarker platforms. Watch for FDA Division of Psychiatry Products guidance revisions on surrogate endpoint acceptance as the primary inflection signal for accelerated approval pathway utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Formulation Expansion | Three-month and six-month injectable platforms address adherence gaps in bipolar I maintenance populations. |
| Pharmacogenomic Testing Integration | CYP2D6 and CYP2C19 metabolic phenotype panels compress trial-and-error titration periods in academic medical centers. |
| Digital Therapeutic Adjacency | FDA breakthrough device designations for adjunctive interventions create parallel reimbursement pathways alongside pharmacological treatment. |
| Multi-Source API Contracting | Supply security agreements spanning three or more active pharmaceutical ingredient suppliers reduce stockout risk for mood stabilizer production. |
| Telepsychiatry Channel Integration | Direct-to-patient medication management platforms capture prescription flow from traditional office-based psychiatric practices. |
Methodological Framework
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchored qualitative grounding, cross-referenced against FDA filings, EMA submissions, ClinicalTrials.gov entries, and formulary databases. Secondary validation drew from SEC 10-K pharmaceutical disclosures, CMS Medicare Part D utilization data, and patent landscape analyses. Bottom-up prescription volume modeling and top-down therapeutic class expenditure triangulation converged on segment-level estimates.
Market size outputs and growth trajectories across the projection horizon reflect segmented modeling by product type, delivery mode, therapy area, and regional regulatory cluster. Compound annual growth rates derived from epidemiological prevalence projections, treatment rate assumptions, and price elasticity modeling for generic versus branded formulation uptake. Forecast inputs incorporated FDA approval velocity trends, payer coverage expansion schedules, and digital therapeutic reimbursement pathway development.
Regulatory approval delays, lithium supply disruption events, and pharmacogenomic testing adoption curves are the dominant revision risks to modeled projections. Forecasts reflect documented assumptions on treatment-seeking behavior, formulary placement timelines, and generic entry sequencing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neurometabolic Disorder Market
Specialty Medicine
Impetigo Therapeutic Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
North America Sports Medicine Market
Specialty Medicine
Progressive Multifocal Leukoencephalopathy Treatment Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
Cellulitis Management Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Osteopontin Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Cholangitis Market
Specialty Medicine
Radiation Toxicity Treatment Market