
 Osteopontin Market | 2026-2036
Osteopontin Market Size, Share, and Industry Trends Forecast 2026-2036
Osteopontin Market Analytics
Recombinant protein expression systems are recalibrating cost structures for osteopontin production, displacing traditional extraction from bovine milk and enabling scalable GMP-grade supply. Arla Foods Ingredients Group P/S leverages its dairy protein heritage to anchor a position in native osteopontin sourcing for nutritional applications. ACROBiosystems specializes in recombinant protein engineering, sustaining technical credibility among assay developers who require lot-to-lot consistency. BioLegend dominates the antibody-reagent tier, extending its catalog into phospho-specific osteopontin detection tools for flow cytometry workflows.
Osteopontin is a highly phosphorylated acidic glycoprotein containing approximately 300 amino acids, secreted by multiple cell types and functionally characterized by its arginine-glycine-aspartic acid integrin-binding domain and calcium-binding polyaspartate sequences. The protein serves as a critical mediator in bone remodeling, immune cell recruitment, and extracellular matrix mineralization, with commercial utility spanning diagnostic immunoassays, therapeutic targeting, and biomarker quantification in oncology and autoimmune disease monitoring. Reagents and antibodies command the deepest margin pools due to recurring purchase cycles and qualification burdens that lock laboratories into validated suppliers. Diagnostic applications are expanding fastest as FDA-cleared osteopontin assays enter clinical validation for cardiovascular risk stratification and hepatic fibrosis staging.
FDA oversight of in vitro diagnostic devices and NIH guidelines on research reagent characterization shape product development timelines and validation requirements for US market participants. EMA's In Vitro Diagnostic Regulation and ISO 13485 quality management standards govern European commercialization, raising compliance costs but filtering substandard suppliers from the channel. Stakeholders must monitor evolving payer coverage decisions for osteopontin-based diagnostic panels and calibrate R&D portfolios toward multiplexed biomarker platforms rather than single-analyte assays.
Market Dynamics
Recombinant protein expression technology is compressing production costs for osteopontin while simultaneously fragmenting supplier power away from traditional dairy-extraction incumbents toward engineered-biology platforms.
Growth Catalysts
- NIH biomarker research funding:Sustained federal grant flows into cardiovascular and hepatic fibrosis studies are validating osteopontin as a quantifiable clinical endpoint, expanding addressable diagnostic demand.
- Flow cytometry workflow expansion:Phospho-specific detection tools are penetrating immuno-oncology research pipelines, creating recurring reagent pull-through from validated assay developers.
- GMP-grade supply maturation:Expression system advances are enabling pharmaceutical-grade batch consistency, unlocking therapeutic developer procurement previously blocked by quality variance.
Market Restraints
- Bovine milk supply concentration:Native osteopontin extraction remains tethered to Scandinavian and North American dairy cooperatives, exposing buyers to input cost volatility and geographic supply risk.
- FDA 510(k) validation timelines:In vitro diagnostic clearance pathways for novel biomarker assays extend commercialization cycles, compressing early-mover returns for assay developers.
- Serum protein substitute competition:Fetuin-A and bone sialoprotein compete for similar mineralization and immune-modulation applications in research settings.
Strategic Opportunities
- Multiplexed biomarker platform integration:Cardiovascular risk panels combining osteopontin with NT-proBNP and high-sensitivity troponin are commanding premium pricing from hospital laboratories.
- Japan's regenerative medicine framework:PMDA's conditional approval pathways for cell therapy adjuncts are creating demand for osteopontin as an ex vivo culture medium component.
- Direct-to-researcher e-commerce channels:Specialized distributors are disintermediating traditional catalog houses, enabling smaller assay developers to access qualified reagents with reduced minimum order quantities.
Industry Challenges
- Lot-to-lot validation burden:Diagnostic laboratories face substantial requalification costs when switching osteopontin antibody suppliers, creating path dependency and locking in incumbent margins.
- Phosphorylation site heterogeneity:Variable post-translational modification patterns across expression systems complicate assay standardization and inter-laboratory reproducibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osteopontin Market |
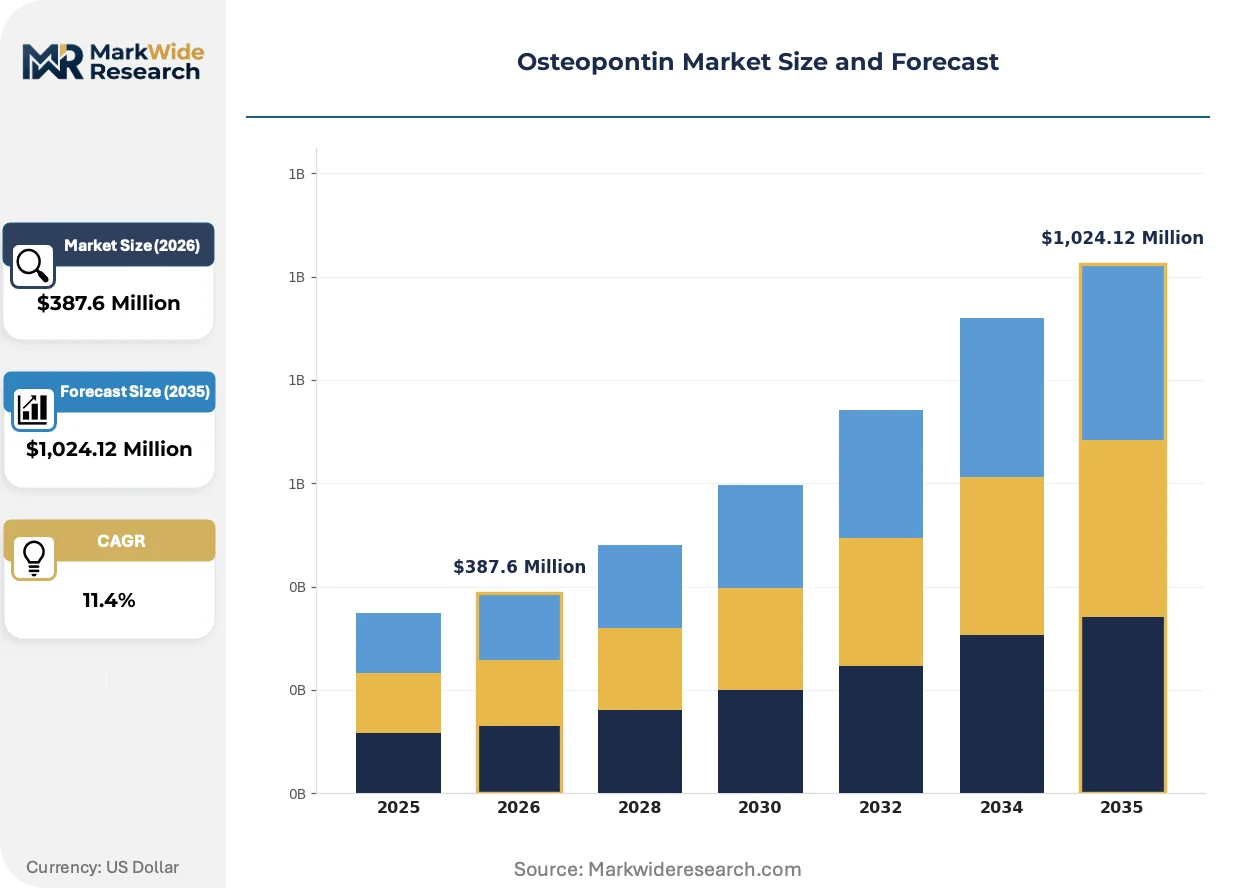
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Assays, Kits, Antibodies Application: Research, Diagnostic, Therapeutic, Biomarker Discovery End User: Hospitals, Clinics, Laboratories, Research Institutes Technology: ELISA, Western Blotting, PCR, Flow Cytometry |
| Companies Covered | Arla Foods Ingredients Group P/S, R&D Systems, Sigma-Aldrich Co., LifeSpan BioSciences, Abnova, ACROBiosystems, BioLegend, OriGene Technologies, NKMAX Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osteopontin Market Evolving Landscape
Expression platform diversification and regulatory pathway evolution are simultaneously expanding supply accessibility and compressing validation timelines for osteopontin-enabled diagnostics.
CRISPR-edited CHO cell lines producing site-specifically phosphorylated osteopontin variants are rewriting quality benchmarks for research-grade reagents. Assay developers at NIH-funded institutions are adopting these engineered proteins at accelerating pace, displacing native-extracted material from bovine sources. The shift is compressing qualification cycles while enabling phosphorylation-state-specific detection workflows previously impractical with heterogeneous natural sources.
EMA's In Vitro Diagnostic Regulation is tightening conformity assessment requirements for CE-marked osteopontin assays entering European clinical laboratories. Manufacturers must now demonstrate analytical and clinical performance through notified body review, extending development timelines but filtering substandard competitors from the channel. German and French diagnostic developers are responding by consolidating validation data packages earlier in product development.
Hospital laboratory buying cooperatives are consolidating procurement decisions for specialty immunoassay reagents, shifting negotiation leverage toward volume-aggregated purchasers and away from individual research institutions. Group purchasing organizations are replacing standalone catalog orders with multi-year supply agreements. This concentration is most visible in United States academic medical centers, where integrated delivery networks now control reagent selection for affiliated research programs.
Osteopontin Market Segmentation
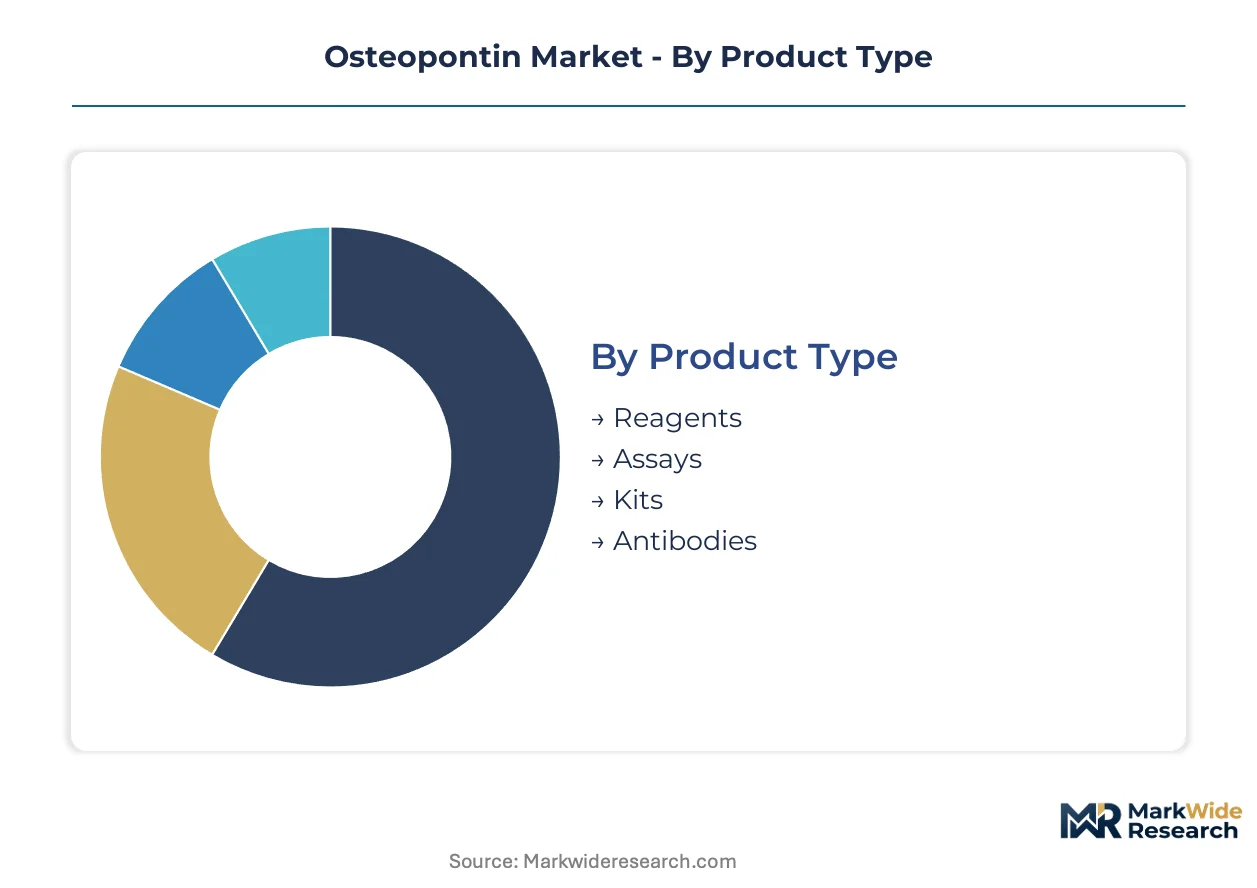
Osteopontin procurement patterns diverge sharply across product formats and use cases, with diagnostic laboratories prioritizing regulatory clearance while research institutes emphasize lot-to-lot consistency. Understanding these segment boundaries clarifies where margin pools concentrate and which validation burdens shape supplier selection.
Product Type:
Certification requirements vary substantially across this category: antibodies and reagents for clinical diagnostics demand FDA 510(k) or EMA CE-IVD clearance, while research-grade materials operate under less stringent ISO 9001 quality systems.
- Reagents:Bulk protein preparations—both native-extracted from bovine milk and recombinant-derived from CHO or HEK293 expression systems—supply immunoassay manufacturers and cell culture media formulators. NIH-funded cardiovascular research programs in the United States anchor demand for phosphorylation-state-defined variants.
- Assays:Pre-configured detection systems including capture plates, detection antibodies, and calibrator sets. Hospital laboratories in Germany and France are consolidating procurement through buying cooperatives, privileging suppliers with EMA IVDR technical documentation already assembled.
- Kits:Complete workflow packages combining all consumables for specific applications. Academic core facilities favor these for reduced qualification overhead.
- Antibodies:Monoclonal and polyclonal binding reagents, including phospho-specific clones for signaling pathway research. BioLegend and ACROBiosystems compete on clone validation depth.
Reagents sit at the top of the volume ranking, with assays climbing the fastest as diagnostic developers push toward FDA-cleared panels.
Application:
Cost tiers separate these segments: biomarker discovery commands premium pricing for custom reagent development, while routine research applications compete on catalog price points.
- Research:Fundamental investigations into osteopontin's role in bone remodeling, immune cell trafficking, and matrix mineralization. CRISPR-edited CHO cell lines producing site-specifically phosphorylated variants are displacing native-extracted material at NIH-funded institutions.
- Diagnostic:Clinical quantification for cardiovascular risk stratification and hepatic fibrosis staging. FDA 510(k) clearance pathways extend commercialization timelines but lock in recurring revenue from validated assay placements.
- Therapeutic:Target modulation and ex vivo cell culture supplementation. Japan's PMDA conditional approval pathways for regenerative medicine are creating demand for GMP-grade supply.
- Biomarker Discovery:Early-stage identification and validation of osteopontin as a quantifiable clinical endpoint. Pharmaceutical manufacturers fund these programs through externalized R&D partnerships.
Research maintains the deepest installed base, though diagnostic applications are expanding most quickly as regulatory-cleared assays enter clinical validation.
End User:
Customer type determines procurement sophistication: integrated delivery networks negotiate multi-year supply agreements, while independent research institutes remain sensitive to minimum order quantities.
- Hospitals:Clinical laboratories processing patient samples for diagnostic panels. Group purchasing organizations in the United States have concentrated negotiation leverage, shifting reagent selection authority away from individual medical centers.
- Clinics:Smaller diagnostic settings with lower test volumes. These facilities favor kit-based solutions over component sourcing.
- Laboratories:Reference and specialty testing sites running high-complexity assays. Lot-to-lot validation burdens create path dependency, locking laboratories into incumbent antibody suppliers.
- Research Institutes:Academic and government-funded facilities pursuing fundamental biology. Direct-to-researcher e-commerce channels are disintermediating traditional catalog houses, enabling smaller assay developers to access qualified reagents.
Laboratories represent the largest addressable base, with research institutes gaining share fastest through federal grant expansion.
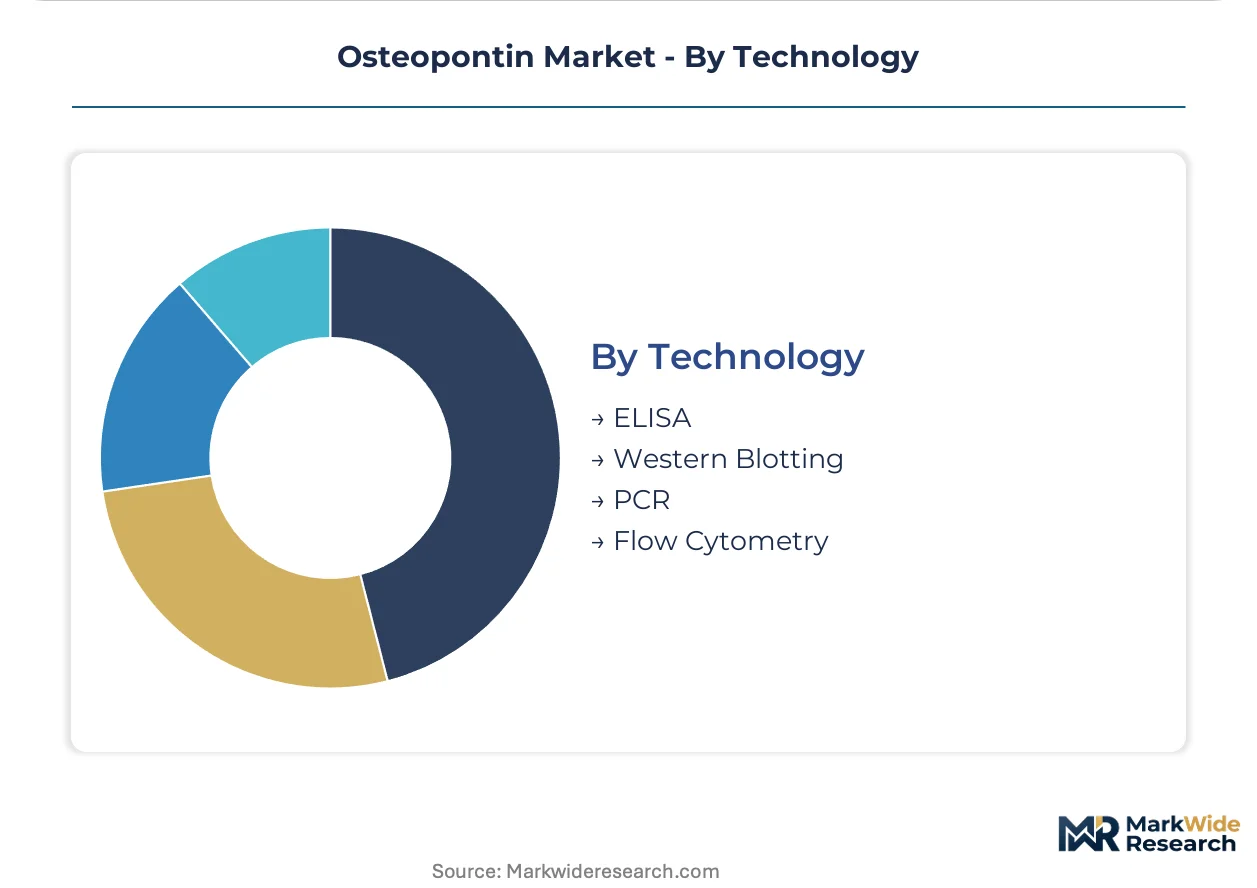
Technology:
Technology maturity shapes adoption curves: ELISA and Western blotting dominate current workflows, while flow cytometry and PCR-based methods are penetrating emerging applications.
- ELISA:Enzyme-linked immunosorbent assay remains the workhorse for quantitative osteopontin detection in serum and plasma matrices. FDA-cleared cardiovascular risk panels standardize on this format for clinical laboratory compatibility.
- Western Blotting:Semi-quantitative protein sizing and detection for research validation. Phosphorylation site heterogeneity across expression systems complicates band interpretation and inter-laboratory reproducibility.
- PCR:Nucleic acid amplification for osteopontin gene expression analysis. Immuno-oncology research pipelines adopt this for transcript-level quantification.
- Flow Cytometry:Single-cell phospho-specific detection using fluorochrome-conjugated antibodies. This modality is penetrating immuno-oncology workflows at accelerating pace, creating recurring reagent pull-through from validated assay developers.
ELISA retains the highest procedure volume, with flow cytometry posting the steepest expansion trajectory as phospho-specific tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square biotech corridor anchors global osteopontin reagent procurement through NIH-funded cardiovascular research programs. Diagnostic developers in San Diego and Research Triangle Park are advancing FDA-cleared assay validation for hepatic fibrosis staging.
United States
NIH grant flows into cardiovascular biomarker research drive demand for phosphorylation-state-defined osteopontin variants. FDA 510(k) clearance pathways for in vitro diagnostic devices extend commercialization timelines for assay developers. The Research Triangle Park cluster in North Carolina concentrates cell therapy media formulators sourcing GMP-grade recombinant protein.
Germany
Hospital laboratory buying cooperatives aggregate procurement decisions for specialty immunoassay reagents across Bavaria and Baden-Württemberg. EMA's In Vitro Diagnostic Regulation tightens conformity assessment requirements for CE-marked assays entering clinical laboratories. The Munich biotech corridor hosts diagnostic developers consolidating validation data packages for IVDR compliance.
Japan
PMDA conditional approval pathways for regenerative medicine create demand for osteopontin as an ex vivo culture medium component. METI funding for cell therapy manufacturing infrastructure accelerates GMP-grade protein procurement. The Kansai region around Osaka concentrates regenerative medicine developers integrating osteopontin into clinical-grade media formulations.
China
Domestic recombinant protein expression capacity expansion displaces imported reagents in biomarker discovery pipelines. NMPA regulatory harmonization with ICH guidelines streamlines clinical assay validation for cardiovascular applications. The Yangtze River Delta biotech corridor in Shanghai and Suzhou hosts CRISPR-edited CHO cell line developers targeting phosphorylation-specific variants.
United Kingdom
Academic core facilities at Oxford and Cambridge drive demand for kit-based workflow solutions with reduced qualification overhead. MHRA post-Brexit regulatory autonomy maintains alignment with EMA IVDR standards for diagnostic device commercialization. The Cambridge cluster concentrates phospho-specific antibody developers supplying European immuno-oncology research programs.
Osteopontin Market Competitive Landscape
Strategic partnerships dominate the current landscape as recombinant protein engineers ally with diagnostic developers to compress FDA validation timelines. The vendor base stratifies across three tiers: dairy-extraction incumbents with native protein heritage, recombinant specialists with CRISPR-edited expression platforms, and antibody-reagent catalog houses with validated clone libraries. Competitive positioning hinges on lot-to-lot consistency guarantees and pre-assembled regulatory documentation packages.
Within the recombinant engineering tier, ACROBiosystems and BioLegend exemplify contrasting archetypes. ACROBiosystems occupies a position among expression-system specialists supplying phosphorylation-state-defined variants to NIH-funded institutions. BioLegend anchors the antibody-reagent segment with fluorochrome-conjugated detection tools penetrating flow cytometry workflows. Arla Foods Ingredients Group P/S represents the dairy-extraction heritage segment, leveraging Scandinavian cooperative supply chains for native osteopontin sourcing in nutritional applications.
| Leading Market Players |
|---|
| Arla Foods Ingredients Group P/S |
| R&D Systems |
| Sigma-Aldrich Co. |
| LifeSpan BioSciences |
| Abnova |
| ACROBiosystems |
| BioLegend |
| OriGene Technologies |
| NKMAX Co. |
| Others |
Value Network & Pricing Analysis
CRISPR-edited CHO cell line engineers concentrated in Shanghai and Boston command wage premiums that widen spreads between GMP-grade phosphorylation-defined variants and research-grade native-extracted material. Labor-cost differentials between these biologics manufacturing hubs and traditional dairy processing cooperatives in Scandinavia propagate three-tier pricing stratification across certification grades.
Pricing Analysis
Input-cost pass-through from bovine milk commodity volatility and recombinant expression media chemistry anchors transactional per-gram pricing for bulk osteopontin. Price differentiation separates FDA 510(k)-cleared diagnostic-grade lots from ISO 9001 research material and uncharacterized native extract. Pricing pressure intensifies as Chinese CRISPR-edited CHO developers compress production economics for phosphorylation-specific variants. Academic core facilities exhibit highest price sensitivity, while pharmaceutical assay developers prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Workforce availability for GMP-grade biologics manufacturing concentrates supply concentration in China, Denmark, and the United States. Raw material dependencies span fetal bovine serum for cell culture, synthetic media formulations, and phospho-specific antibody clones. Single-source vulnerability pervades the Scandinavian dairy cooperative channel for native osteopontin. Distribution runs through specialized life-science distributors and direct-to-researcher e-commerce platforms serving validated assay developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EMA IVDR technical documentation requirements and FDA 510(k) validation pathways simultaneously extend development timelines and deepen incumbent moats.
For Market Incumbents: Anticipate CRISPR-edited CHO specialists eroding margin pools in research-grade reagents by securing phosphorylation-state consistency guarantees that native-extraction incumbents cannot match. Defend positioning through backward integration into GMP-grade expression capacity in Research Triangle Park and preemptive assembly of IVDR-compliant validation data packages for European diagnostic developers. For New Entrants and Emerging Players: The premium-to-economy tier price gap in phospho-specific antibody reagents offers white-space entry for validated clone developers targeting flow cytometry workflows. Japan's PMDA conditional approval pathway for regenerative medicine culture media presents the most penetrable regulatory entry point. Direct-to-researcher e-commerce channels enable minimum-order-quantity flexibility that disintermediates incumbent catalog houses. For Investors and Strategic Acquirers: Diagnostic platform developers with multiplexed cardiovascular biomarker pipelines are the most active acquirer category in this space. Long-term viability hinges on regulatory clearance density rather than research-grade volume. Acquisition target archetypes include CRISPR-edited CHO cell line developers with site-specific phosphorylation capabilities. Watch NIH grant allocation shifts toward hepatic fibrosis staging as inflection signal for diagnostic demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Locks in recurring revenue from validated hospital laboratory assay placements. |
| CRISPR-Edited CHO Cell Line Development | Enables site-specific phosphorylation variants that displace native-extracted material. |
| EMA IVDR Technical Documentation Assembly | Filters substandard competitors from European clinical laboratory channels. |
| Direct-to-Researcher E-Commerce Channel | Reduces minimum order quantities for smaller assay developers. |
| Multiplexed Biomarker Platform Integration | Commands premium pricing from hospital laboratory buying cooperatives. |
Research Methodology
Direct dialogue with diagnostic assay developers, GMP-grade protein manufacturing directors, NIH program officers, and hospital laboratory procurement managers grounded qualitative insights. Secondary validation drew from FDA 510(k) device clearances, EMA IVDR technical documentation filings, ClinicalTrials.gov cardiovascular biomarker protocols, and NIH RePORTER grant databases. Bottom-up demand modeling triangulated against top-down protein reagent market sizing.
Output projections across the analysis window reflect segment-level modeling by product format, application tier, end-user category, and detection technology modality. CAGRs derived from NIH funding trajectory analysis, diagnostic assay pipeline maturation curves, and recombinant expression platform adoption rates. Forecast inputs incorporated phosphorylation-state assay validation timelines and group purchasing organization contract renewal cycles.
Caveats apply where FDA biomarker qualification pathway revisions, EMA IVDR notified body capacity constraints, or CRISPR-edited CHO line patent disputes could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Gastritis Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Necrobiosis Lipoidica Diabeticorum Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Glioblastoma Multiforme Treatment (GBM) Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Veno-Occlusive Hepatic Disease Therapeutics Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market