
 Cholangitis Market | 2026-2036
Cholangitis Market Size, Share, and Industry Trends Forecast 2026-2036
Cholangitis Market Outlook
Project finance for late-stage clinical assets is fragmenting the competitive landscape in cholangitis therapeutics. Intercept Pharmaceuticals leverages its first-mover position in bile acid modulators to sustain development momentum. Gilead Sciences anchors its portfolio with broad infectious disease infrastructure that competes across hepatology indications. Dr. Falk Pharma specializes in European gastroenterology channels where it controls physician access for niche biliary therapies.
Cholangitis denotes acute or chronic inflammation of the bile ducts, typically arising from bacterial infection, biliary obstruction, or autoimmune processes such as primary sclerosing cholangitis, with severity graded by systemic inflammatory response and organ dysfunction criteria. Antibiotics retain the largest share of product type revenue due to their role in acute bacterial cholangitis, while biologics represent the fastest-expanding category as targeted immunomodulation gains traction in autoimmune variants. Hospital pharmacies dominate distribution channels because parenteral administration and monitoring requirements limit outpatient initiation, though specialty clinics are capturing follow-on prescribing as oral step-down protocols mature.
FDA orphan drug designations and EMA PRIME eligibility criteria shape development economics by compressing trial timelines and extending market exclusivity for novel biliary therapies. The country's national pharmaceutical regulator in Japan enforces localized clinical bridging studies that filter which biologics achieve reimbursement listing. Stakeholders must monitor pipeline readouts in fibroblast growth factor receptor and chemokine receptor antagonism to anticipate which mechanism will redefine standard of care.
Market Dynamics
Accelerated regulatory pathways for rare biliary diseases are compressing development timelines and redistributing competitive advantage toward assets with orphan designations, while hospital consolidation concentrates purchasing power among tertiary hepatology centers.
Growth Catalysts
- FDA Orphan Drug Designation:Extended market exclusivity and tax incentives for novel cholangitis therapies attract venture capital into previously overlooked indications. Biotech sponsors prioritize assets qualifying under this framework.
- Hospital-based acute care protocols:Emergency department adoption of standardized biliary sepsis pathways drives parenteral antibiotic volumes. Tertiary centers establish dedicated cholangitis response teams.
- Japan's PMDA SAKIGAKE designation:Priority review for innovative hepatology drugs accelerates commercial entry. Domestic bridging study requirements filter which biologics achieve reimbursement.
Market Restraints
- API supply concentration:Penicillin and cephalosporin active pharmaceutical ingredients cluster in Chinese and Indian manufacturing hubs. Geopolitical friction threatens continuity of antibiotic supply for acute bacterial cholangitis.
- EMA PRIME eligibility barriers:Stringent evidentiary thresholds for breakthrough therapy status exclude mid-stage assets. Smaller sponsors lack resources to generate comparative effectiveness data.
- Diagnostic substitution:Non-invasive magnetic resonance cholangiopancreatography displaces endoscopic retrograde cholangiopancreatography for initial evaluation. Procedure volume erosion limits concurrent therapeutic intervention opportunities.
Strategic Opportunities
- Germany's DiGA pathway:Digital health applications for patient monitoring in primary sclerosing cholangitis qualify for statutory reimbursement. Software-enabled adherence tools capture recurring revenue streams.
- Specialty pharmacy distribution:Oral step-down protocols for stable patients shift fulfillment from hospital infusion centers to home delivery channels. Mail-order penetration in autoimmune cholangitis remains underdeveloped.
- Fibroblast growth factor receptor antagonism:Mechanism convergence with oncology pipelines enables indication expansion. Shared toxicology databases compress preclinical development costs.
Industry Challenges
- Hepatology trial recruitment:Patient identification for rare autoimmune variants requires specialized site networks. Principal investigator scarcity at community hospitals constrains enrollment velocity.
- Biomarker qualification timelines:FDA and EMA diverge on acceptable surrogate endpoints for accelerated approval. Sponsors face parallel validation requirements that extend regulatory preparation.
- Legacy electronic health record integration:Hospital systems operate incompatible platforms for biliary imaging and laboratory data. Interoperability gaps complicate real-world evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cholangitis Market |
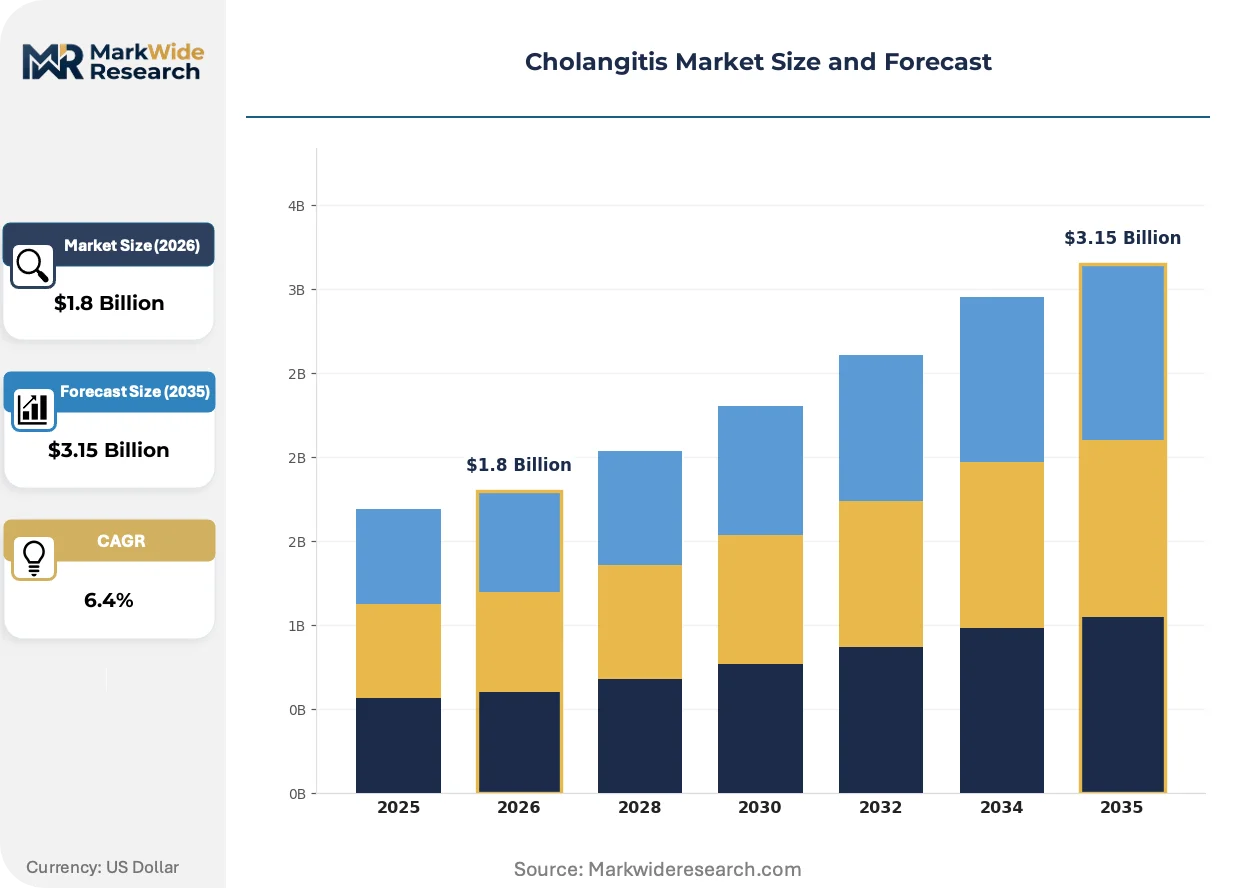
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Immunosuppressants, Biologics, Combination Therapy End User: Hospitals, Specialty Clinics, Research Institutions, Homecare Administration Route: Oral, Intravenous, Subcutaneous, Topical Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | Intercept Pharmaceuticals, Gilead Sciences, Abbott Laboratories, Ipsen, Dr. Falk Pharma, Viatris, CymaBay Therapeutics, Pliant Therapeutics, HighTide Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cholangitis Market Strategic Shifts
Next-generation sequencing of biliary microbiomes is redefining infection taxonomy, while minimally invasive drainage techniques and biomarker-guided therapy selection are compressing traditional diagnostic and treatment paradigms.
Single-use duodenoscopes with disposable elevator mechanisms are rendering obsolete reusable endoscopes in ERCP procedures. Tertiary hepatology centers in the United States and Germany are converting their fleets to eliminate cross-contamination risks. This shift is compressing capital equipment replacement cycles while elevating per-procedure supply costs.
EMA's PRIME eligibility criteria for rare biliary diseases now mandate patient-reported outcome integration from Phase II trials. This industrial consequence forces sponsors to redesign protocols around quality-of-life instruments rather than surrogate biomarkers alone. Autoimmune cholangitis indications face the steepest compliance burden as natural history data remains sparse.
Consolidated purchasing by hospital networks is unbundling device procurement from pharmaceutical contracting. Integrated delivery networks in Japan and the United States now negotiate separate tenders for antibiotics, drainage hardware, and imaging services. This fragmentation is visible most acutely in German university hospitals where procurement autonomy has shifted to centralized regional bodies.
Cholangitis Market Segmentation
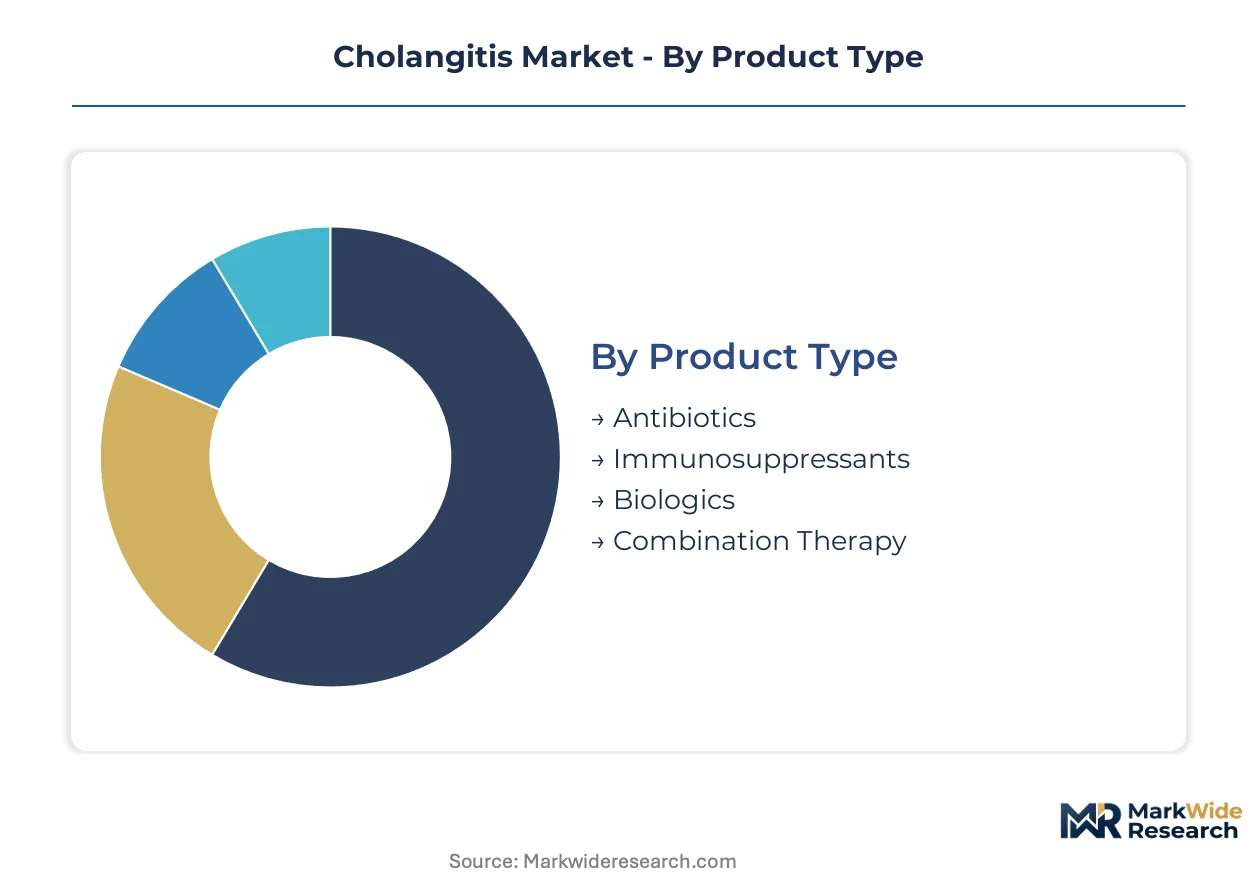
Cholangitis therapeutics fragment across acute bacterial, autoimmune, and chronic obstructive phenotypes, each demanding distinct product configurations, administration settings, and procurement pathways. Understanding segment boundaries clarifies where development capital concentrates and which distribution channels capture margin.
Product Type:
Use cases span emergency bacterial clearance through long-term immunomodulation, with cost and reimbursement tiers diverging sharply across the spectrum.
- Antibiotics:Broad-spectrum agents targeting gram-negative enteric organisms dominate acute bacterial cholangitis protocols. Hospital formularies in the United States and Germany prioritize parenteral cephalosporin and penicillin derivatives for emergency department initiation, though API supply concentration in Asian manufacturing hubs introduces continuity risk.
- Biologics:Monoclonal antibodies and fusion proteins interrupting IL-12/23 and integrin signaling address autoimmune variants including primary sclerosing cholangitis. Tertiary hepatology centers in Japan and the United States drive adoption as PMDA SAKIGAKE and FDA breakthrough pathways compress approval timelines.
- Immunosuppressants:Corticosteroid and calcineurin inhibitor regimens manage overlap syndromes.
- Combination Therapy:Sequential antibiotic-biologic protocols for complex cases.
The dominant share belongs to Antibiotics, while Biologics is closing the gap fastest.
End User:
Patient acuity and reimbursement authorization requirements concentrate volume across institutional settings, with home transition protocols emerging as a margin battleground.
- Hospitals:Tertiary hepatology centers handle acute bacterial cholangitis with ERCP-integrated antibiotic therapy and biliary drainage. Consolidated purchasing networks in the United States and Germany negotiate bundled device-pharmaceutical contracts, while Japanese university hospitals maintain procurement autonomy under regional hospital reform.
- Specialty Clinics:Gastroenterology-focused ambulatory sites manage stable autoimmune patients on oral step-down regimens. German outpatient hepatology practices leverage DiGA reimbursement for digital adherence monitoring, capturing recurring revenue beyond drug dispensing.
- Research Institutions:Academic medical centers conduct Phase II-III trials for novel mechanisms.
- Homecare:Subcutaneous biologic administration and oral antibiotic completion.
Hospitals retain the volume anchor, though Specialty Clinics are expanding share through oral protocol maturation.
Administration Route:
Pharmacokinetic requirements and patient stability determine route selection, with formulation innovation shifting the institutional-outpatient boundary.
- Intravenous:Parenteral delivery achieves rapid therapeutic levels in septic patients with biliary obstruction. Emergency department protocols in the United States mandate IV initiation before imaging confirmation, driving hospital pharmacy inventory depth and cold-chain infrastructure investment.
- Oral:Bioavailable fluoroquinolones and bile acid modulators enable discharge and chronic management. Japanese hepatology practices favor oral ursodeoxycholic acid derivatives for primary sclerosing cholangitis maintenance, with retail pharmacy fulfillment replacing infusion center visits.
- Subcutaneous:Self-administered biologics for stable autoimmune patients.
- Topical:Limited to post-procedural biliary tract applications.
Intravenous commands acute episode value, while Oral formulations are climbing fastest through step-down protocol expansion.
Distribution Channel:
Procurement control points separate inpatient acute care from chronic maintenance, with digital intermediaries fragmenting traditional wholesale relationships.
- Hospital Pharmacies:Captive dispensing for parenteral antibiotics and biologics requiring infusion supervision. Integrated delivery networks in the United States unbundle device and pharmaceutical contracting, while German regional hospital bodies centralize tender processes for antibiotic formularies.
- Retail Pharmacies:Community and specialty pharmacy fulfillment for oral maintenance regimens. Japan's reimbursement-listed biologics require dispensing through registered pharmacists with hepatology certification, filtering market access.
- Online Pharmacies:Mail-order penetration for stable autoimmune maintenance.
- Wholesalers:Three-tier distribution for generic antibiotics.
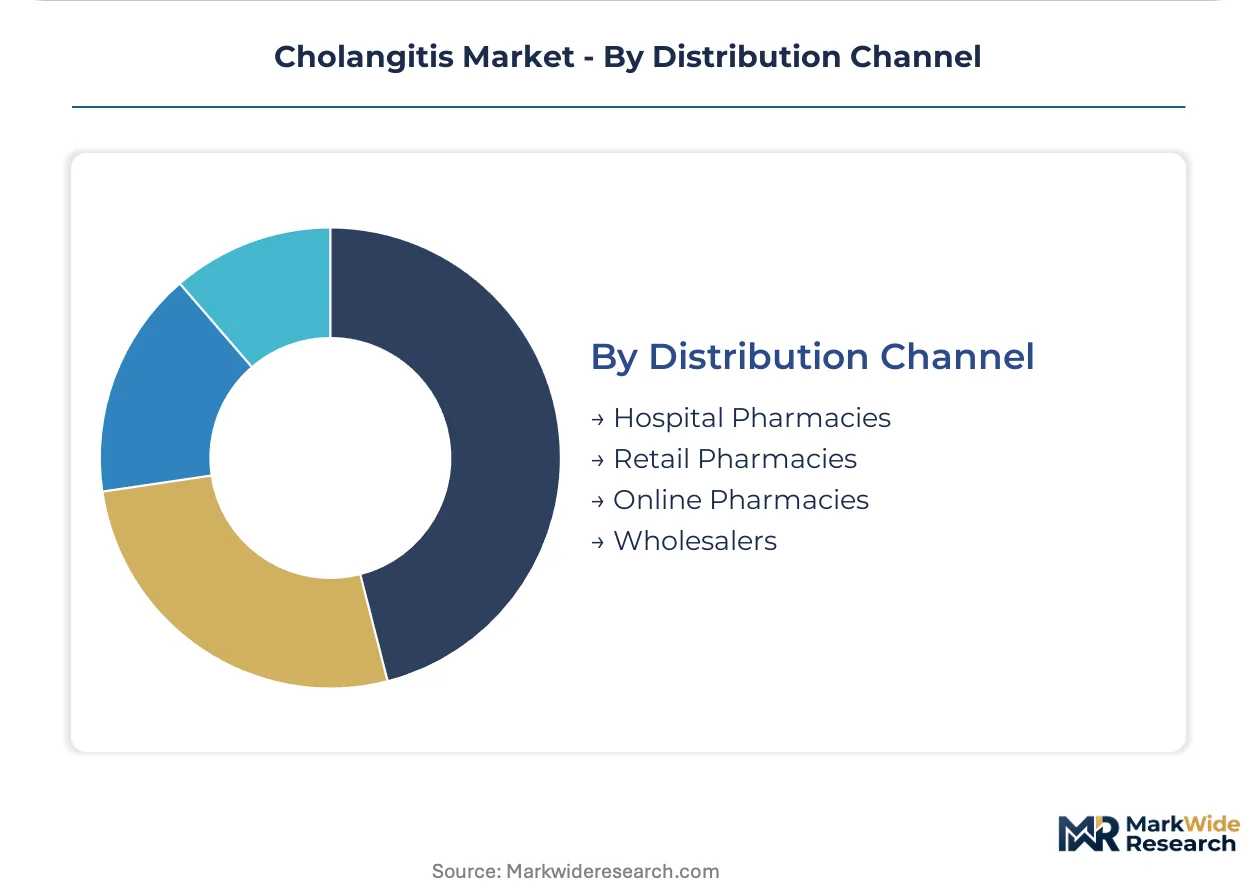
Hospital Pharmacies hold the dominant position, though Online Pharmacies are gaining traction through specialty pharmacy platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug designation and EMA PRIME eligibility compress development timelines for novel cholangitis therapies, redistributing investment toward regulatory-friendly jurisdictions. The United States, Germany, and Japan concentrate tertiary hepatology capacity where accelerated approval pathways reshape competitive entry.
United States
Tertiary hepatology centers in Boston and Houston drive ERCP-integrated antibiotic protocols for acute bacterial cholangitis. FDA breakthrough therapy designation for autoimmune variants attracts biotech sponsors to the Massachusetts and California clusters. Intermountain Healthcare and Mayo Clinic networks consolidate purchasing power across antibiotic formularies and single-use duodenoscopes.
Germany
University hospitals in Munich and Hamburg anchor European trial enrollment for primary sclerosing cholangitis biologics. EMA PRIME eligibility mandates patient-reported outcome integration from Phase II, forcing protocol redesigns at Heidelberg and Berlin sites. Regional hospital reform shifts procurement autonomy to centralized bodies in North Rhine-Westphalia and Bavaria.
Japan
PMDA SAKIGAKE designation accelerates commercial entry for innovative hepatology drugs, filtering biologics through domestic bridging study requirements. Tokyo and Osaka tertiary centers dominate patient volumes for autoimmune cholangitis. The national pharmaceutical regulator enforces localized clinical data generation that determines reimbursement listing outcomes.
United Kingdom
NHS England specialized commissioning for rare biliary diseases concentrates treatment at London and Manchester hepatology hubs. MHRA rolling review pathways align with EMA procedures post-Brexit, though divergence in biomarker qualification timelines complicates sponsor strategy. Cambridge and Oxford academic medical centers anchor Phase II-III trial infrastructure.
Switzerland
Swissmedic accelerated assessment procedures for orphan drugs attract development-stage sponsors to the Basel and Zurich clusters. University hospitals in Geneva and Lausanne participate in multinational autoimmune cholangitis trials. The country's pricing and reimbursement authority negotiates outcome-based agreements for biologics targeting rare biliary indications.
Cholangitis Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented prescribing environments. Hospital consolidation in the United States and Germany concentrates purchasing power among integrated delivery networks, while specialty gastroenterology practices in Europe retain procurement autonomy. Three archetypes dominate: large-cap diversified pharmacos with infectious disease infrastructure, mid-cap bile acid modulator specialists, and biotech developers targeting fibroblast growth factor receptor pathways. Competitive moves center on orphan designation accumulation and indication expansion from oncology pipelines.
Among development-stage specialists, Intercept Pharmaceuticals and CymaBay Therapeutics occupy positions within the bile acid modulator archetype, while Gilead Sciences anchors the diversified infectious disease tier. Dr. Falk Pharma exemplifies the European gastroenterology channel specialist model. These entities represent contrasting strategic postures toward regulatory pathway exploitation and hepatology center access.
| Leading Market Players |
|---|
| Intercept Pharmaceuticals |
| Gilead Sciences |
| Abbott Laboratories |
| Ipsen |
| Dr. Falk Pharma |
| Viatris |
| CymaBay Therapeutics |
| Pliant Therapeutics |
| HighTide Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Indian and Chinese cephalosporin API manufacturing is compressing supplier margins while amplifying pricing power among consolidated hospital purchasing networks in the United States and Germany. This utilization squeeze forces antibiotic producers to prioritize contract renewals with integrated delivery networks over spot-market sales, reshaping both procurement hierarchies and cost pass-through mechanics.
Pricing Analysis
Certification level (FDA-grade, EMA GMP, PMDA-compliant) creates the primary spread across antibiotic tiers, with hospital formularies paying premiums for validated cold-chain documentation. Biologics command value-based contracting tied to patient-reported outcomes, while generic penicillin derivatives face commodity compression. Price differentiation intensifies between orphan-designated therapies and acute-care antibiotics. Consolidated purchasing networks in Japan and Germany extract volume discounts that squeeze mid-tier suppliers. Cost compression in standard-grade antibiotics reflects API import dependency and currency fluctuation exposure.
Supply Chain Analysis
Export-control restrictions on fermentation technology and bioreactor components limit capacity expansion in emerging manufacturing hubs. Active pharmaceutical ingredients for cephalosporins and penicillins concentrate in India, China, and selected Eastern European facilities. Raw material dependencies span corn-derived dextrose for fermentation, specialized resin for chromatography purification, and borosilicate glass for parenteral packaging. Single-source vulnerability in beta-lactam intermediate supply threatens continuity for acute bacterial cholangitis protocols. Distribution runs through hospital pharmacy central warehouses and specialty cold-chain logistics providers serving tertiary hepatology centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against non-invasive diagnostic substitution eroding ERCP-integrated therapeutic opportunities, while navigating procurement consolidation that unbundles device and pharmaceutical contracting.
For Market Incumbents: Harden formulary stickiness through outcome-based agreements with integrated delivery networks that bundle antibiotics with single-use duodenoscope supply. Deepen backward integration into API fermentation capacity to insulate against Indian and Chinese supply disruption. Prioritize FDA orphan drug designation accumulation to extend exclusivity windows against biosimilar erosion.
For New Entrants and Emerging Players: Establish a beachhead in Germany's DiGA-enabled patient monitoring segment, where software reimbursement creates recurring revenue streams beyond drug margins. Target Japanese specialty clinics with subcutaneous biologic formulations that bypass hospital infusion requirements. Leverage PMDA SAKIGAKE designation to compress regulatory timelines relative to EMA and FDA pathways.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bile acid modulator developers with Phase III-ready assets and established hepatology center relationships. Long-term viability hinges on pipeline optionality across fibroblast growth factor receptor and chemokine receptor mechanisms. Acquisition candidates should demonstrate regulatory pathway sophistication and site network density. The signal to watch is EMA PRIME eligibility conversion rates as a proxy for accelerated approval velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Accumulation | FDA and EMA exclusivity extensions protect revenue streams for rare biliary indications. |
| Single-Use Duodenoscope Fleet Conversion | Tertiary centers in the United States and Germany eliminate cross-contamination liability. |
| DiGA Pathway Entry | German statutory reimbursement enables software-enabled adherence revenue capture. |
| PMDA SAKIGAKE Utilization | Priority review compresses Japanese commercial entry timelines for biologics. |
| API Backward Integration | Fermentation capacity ownership insulates against geopolitical supply disruption. |
Study Parameters
Desk research of FDA orphan drug filings, EMA PRIME eligibility databases, and PMDA SAKIGAKE designations preceded structured interviews with hepatology clinical trial investigators, hospital pharmacy procurement directors, and regulatory affairs specialists at biotech sponsors. Secondary validation drew from ClinicalTrials.gov enrollment data, hospital formulary databases, and GPO contract disclosures. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Assumptions held fixed across the analysis window include regulatory pathway timelines for orphan indications and hospital consolidation trajectories in the United States and Germany; variables stress-tested included API supply disruption severity and diagnostic substitution velocity. Segmentation modeling spanned product type, administration route, end-user setting, and regional regulatory cluster. CAGRs derived from epidemiological trend extrapolation, pricing trajectory analysis, and adoption curve fitting for novel mechanisms.
Stress conditions across API supply continuity, diagnostic procedure volume erosion, and accelerated approval conversion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and industry-specific risk factors including biomarker qualification divergence between FDA and EMA. Material shifts in regulatory harmonization or geopolitical trade restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Eye Allergy Therapeutics Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
Ulcerative Colitis Therapeutics Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Global Alcoholic Hepatitis Therapeutics Market
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Multiple Endocrine Neoplasia Market