
 Biometric Sensors Market | 2026-2036
Biometric Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Sensors Market Analysis
OEM supply contracts for smartphone fingerprint modules is rewriting procurement dynamics across the biometric sensor industry. Infineon Technologies AG leverages its capacitive and ultrasonic sensor portfolio to sustain leadership in mobile payment authentication. Shenzhen Goodix Technology Co., Ltd. dominates capacitive fingerprint module shipments through backward integration into wafer-level packaging. NEC Corporation anchors government identity projects with its multimodal biometric fusion platforms.
Biometric sensors are electro-optical or solid-state devices that capture and convert unique biological traits—fingerprint ridges, iris patterns, facial geometry, or voiceprints—into digital templates for automated identity verification, typically operating at false acceptance rates below 0.001% in enterprise-grade configurations. Optical technology retains cost advantages in access control deployments, while ultrasonic technology captures sub-dermal ridge detail through contaminated surfaces. Capacitive technology occupies mature smartphone channels where module thickness constraints dominate design trade-offs. Fingerprint sensors lead unit volumes, though facial recognition systems command premium pricing in high-security government and financial services environments.
The EU AI Act and GDPR constrain automated facial recognition deployments in European public spaces, forcing vendors to embed purpose-limitation protocols and human-in-the-loop review mechanisms. In the United States, NIST testing frameworks shape procurement specifications for federal identity systems, while the FDA oversees biometric device integration into regulated healthcare workflows. China's MIIT and GB standards mandate domestic encryption modules for state-connected identity infrastructure. Stakeholders must track divergence between permissive and restrictive regulatory blocs when allocating R&D across sensor modalities and geographic markets.
Market Dynamics
Ultrasonic fingerprint sensing is compressing capacitive module margins across smartphone supply chains while EU AI Act compliance costs reshape vendor R&D allocation toward purpose-limited biometric architectures.
Growth Catalysts
- Healthcare Contactless Mandates:Hospital systems in Germany and the United States deploy palm-vein and facial recognition for patient identification to reduce nosocomial transmission pathways.
- MIIT Encryption Standards:China's mandatory domestic cryptographic modules for state-connected identity infrastructure accelerate local production of fingerprint and iris sensors for financial and transit applications.
- Capacitive Cost Curves:Wafer-level packaging advances have collapsed per-unit sensor costs below the threshold for mid-tier smartphone integration.
Market Restraints
- GDPR Facial Recognition Friction:The EU AI Act's strict conformity assessment procedures for automated recognition in public spaces extend deployment timelines by 12-18 months.
- Optical Sensor Input Volatility:CMOS image sensor wafer pricing fluctuates with semiconductor foundry capacity allocation, compressing margins for access control module vendors.
- Silicon Supply Concentration:Advanced BSI-CIS fabrication concentrates in Taiwan and South Korea, exposing biometric OEMs to single-source geographic risk.
Strategic Opportunities
- Automotive In-Cabin Biometrics:Driver monitoring systems for drowsiness detection and personalized settings represent an underpenetrated application vector as NHTSA guidelines mature.
- India's Digital Public Infrastructure:The UIDAI ecosystem creates pull-through demand for low-cost fingerprint and iris sensors in rural banking and ration distribution.
- Multimodal Fusion Architectures:Convergence of liveness detection algorithms with thermal imaging sensors enables spoof-resistant authentication for high-value transactions.
Industry Challenges
- Algorithm Bias Certification:NIST FRVT testing protocols require demographic parity validation that extends development cycles for facial recognition vendors targeting federal procurement.
- Legacy System Integration:Enterprise access control refresh cycles lag sensor technology generations, forcing vendors to maintain backward compatibility with Wiegand and OSDP protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Sensors Market |
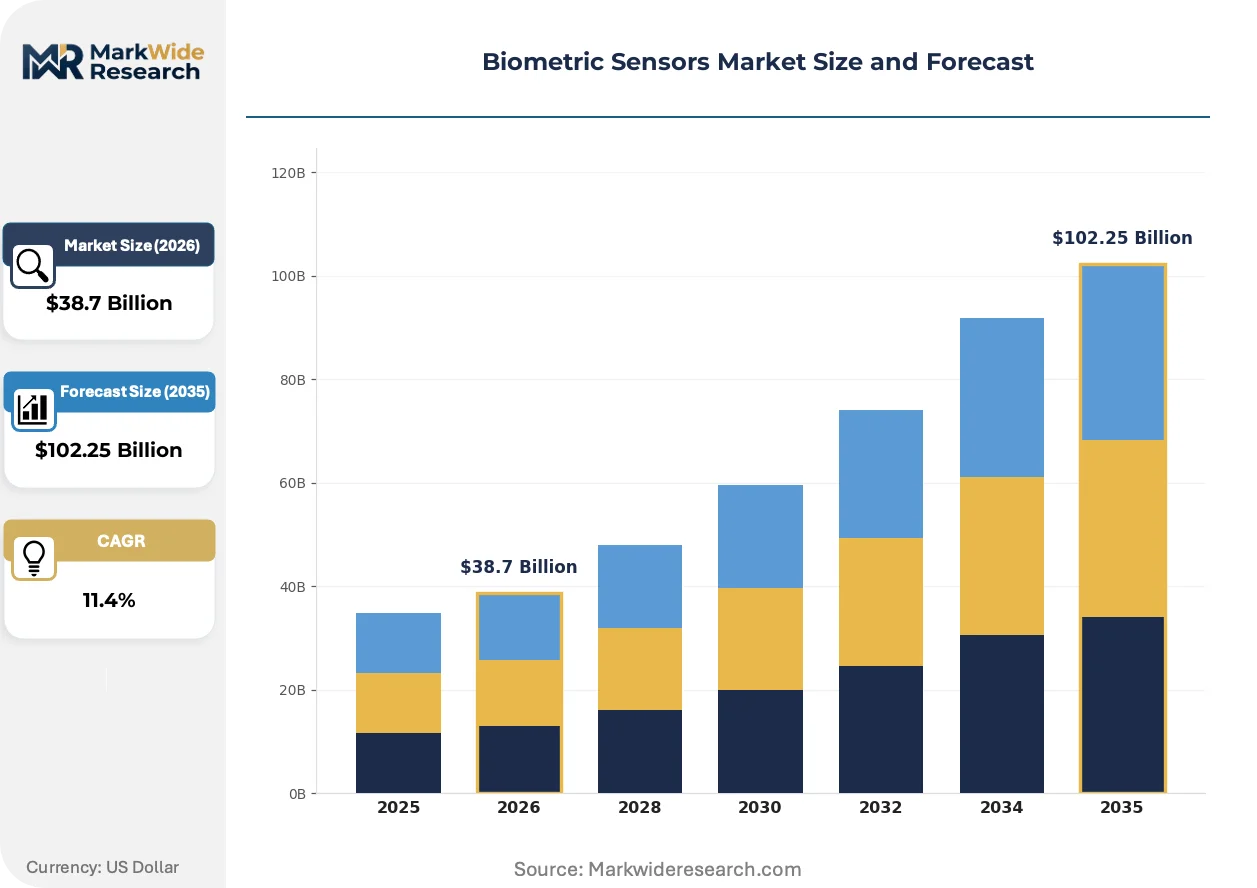
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint Sensors, Iris Scanners, Facial Recognition Systems, Voice Recognition Systems Technology: Optical Technology, Capacitive Technology, Ultrasonic Technology, Thermal Technology Application: Access Control, Identity Verification, Time Tracking, Payment Processing End User: Healthcare, Financial Services, Government, Retail |
| Companies Covered | NEC Corporation, Infineon Technologies AG, Synaptics Incorporated, IDEX Biometrics ASA, Shenzhen Goodix Technology Co., Ltd., Fujitsu, Thales, IDEMIA, Fingerprint Cards AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Sensors Market Emerging Trajectories
Sensor architectures are bifurcating between ultra-low-cost capacitive modules for volume consumer electronics and premium multimodal systems for regulated identity applications, with middleware layers absorbing increasing value share.
Ultrasonic fingerprint sensing captures sub-dermal ridge detail through moisture, grease, and contaminated glass surfaces that defeat optical alternatives. Automotive OEMs and industrial access control integrators are migrating from capacitive to ultrasonic modules at a measured pace, prioritizing reliability over unit cost. This technology is migrating from flagship smartphone channels into payment terminals and healthcare workstations where surface contamination is endemic.
The EU AI Act's risk-based classification system places most public-space facial recognition deployments in the "high-risk" category requiring third-party conformity assessment. Vendors must embed technical documentation, human oversight mechanisms, and fundamental rights impact assessments into product development workflows. Government identity projects across France, Germany, and the Netherlands now specify multimodal fusion with explicit purpose limitation as a procurement prerequisite.
Healthcare systems are unbundling biometric authentication from EHR platform contracts, creating direct procurement relationships with sensor vendors. Hospital IT departments in the United States and United Kingdom now issue separate RFPs for identity verification infrastructure, displacing the bundled authentication modules historically supplied by Epic and Cerner. This pattern is most visible in academic medical centers pursuing HIMSS Stage 7 certification where patient matching accuracy carries reimbursement implications.
Biometric Sensors Market Segmentation
Technology choices in biometric sensors cascade through cost structures, regulatory compliance burdens, and integration complexity. Procurement decisions increasingly separate high-security government deployments from volume consumer electronics channels.
Product Type:
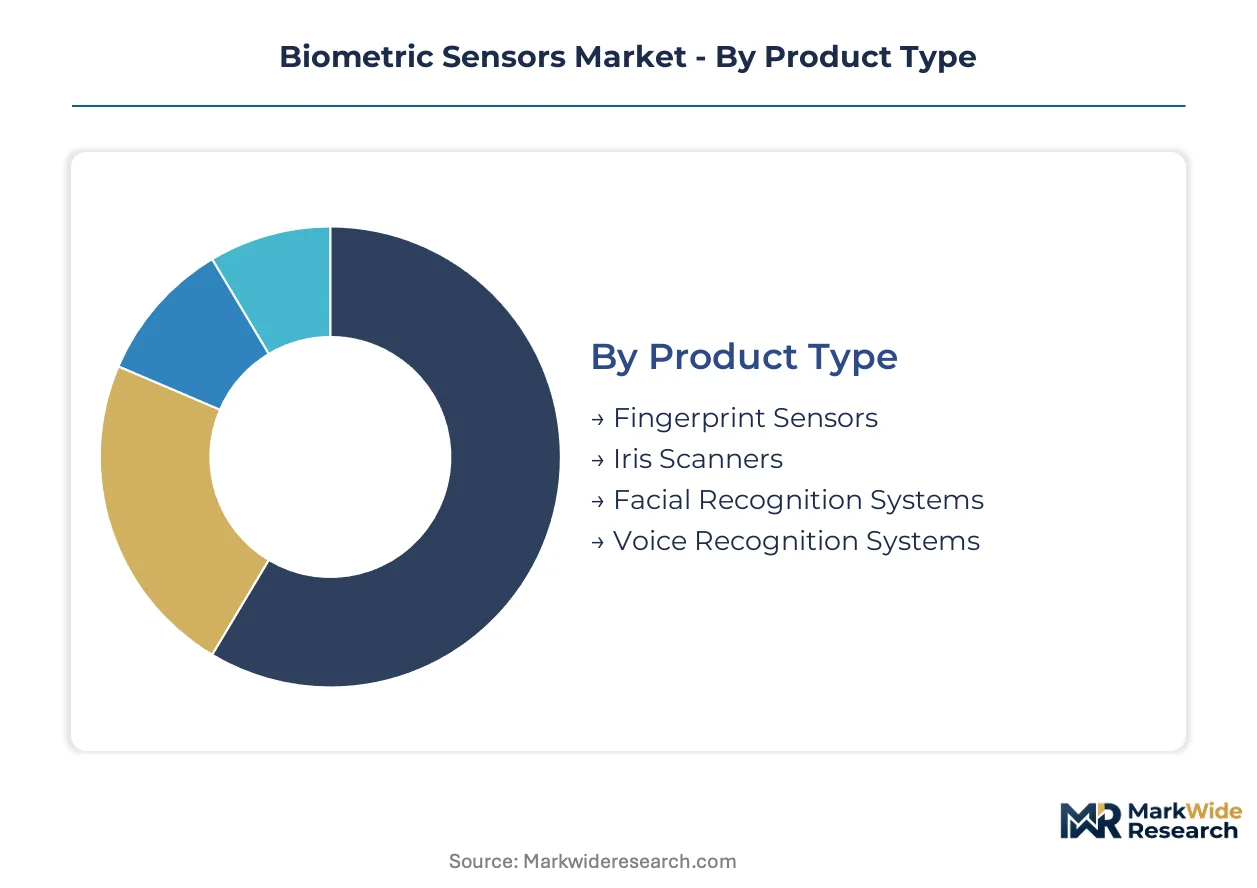
Volume concentration maps directly to unit economics and sensor form factor constraints across device categories.
- Fingerprint Sensors:Solid-state capacitive and ultrasonic modules capture ridge patterns through contact or sub-dermal imaging. Wafer-level packaging advances have collapsed per-unit costs below the threshold for mid-tier smartphone integration in China and India.
- Facial Recognition Systems:Structured light and time-of-flight cameras generate 3D facial maps for liveness detection. EU AI Act high-risk classification extends deployment timelines by 12-18 months for public-space applications in France and Germany.
- Iris Scanners:Near-infrared imaging targets high-security government identity projects.
- Voice Recognition Systems:Acoustic pattern analysis serves call center authentication and smart speaker integration.
Fingerprint sensors command the established base. The steepest expansion runs through facial recognition systems.
Technology:
Cost tiers separate mature capacitive production from premium ultrasonic and multimodal architectures.
- Capacitive Technology:Electric field disruption across fingerprint ridges enables thin-form-factor modules. Shenzhen Goodix dominates wafer-level packaging for smartphone integration through backward integration into semiconductor fabrication.
- Ultrasonic Technology:Piezoelectric transducers emit acoustic pulses that penetrate moisture, grease, and contaminated glass to image sub-dermal ridge structure. Automotive OEMs and healthcare workstation vendors are migrating from capacitive alternatives where surface contamination is endemic.
- Optical Technology:CMOS image sensors capture reflected light patterns for access control deployments.
- Thermal Technology:Infrared detectors measure heat differentials for liveness detection in high-value transaction environments.
Capacitive modules anchor current volume. Ultrasonic platforms are climbing the fastest as reliability premiums override unit cost constraints.
Application:
End-use requirements dictate sensor modality selection and certification burden intensity.
- Identity Verification:Multimodal fusion of fingerprint, facial, and iris templates underpins government ID systems and border control infrastructure. NIST FRVT testing protocols require demographic parity validation that extends development cycles for vendors targeting federal procurement in the United States.
- Access Control:Card reader replacement and biometric-enabled door locks serve enterprise and residential security. Legacy Wiegand and OSDP protocol compatibility forces vendors to maintain backward integration with decades-old wiring infrastructure.
- Payment Processing:FIDO2-compliant authentication for mobile and point-of-sale transactions.
- Time Tracking:Workforce management systems for hourly employee clock-in verification.
Identity verification absorbs the highest compliance investment. Payment processing is gaining share fastest as FIDO standards harmonize across financial services.
End User:
Customer type determines procurement centralization, integration complexity, and regulatory exposure.
- Government:National ID programs, border control, and law enforcement systems mandate multimodal fusion with explicit purpose limitation. China's MIIT encryption standards accelerate domestic production of fingerprint and iris sensors for state-connected infrastructure.
- Healthcare:Patient identification and EHR access control drive contactless biometric adoption to reduce nosocomial transmission. Hospital IT departments in the United States and United Kingdom now issue separate RFPs for identity verification infrastructure, displacing bundled modules from Epic and Cerner.
- Financial Services:Mobile banking authentication and branch identity verification.
- Retail:Self-checkout and loyalty program enrollment.
Government contracts anchor premium pricing. Healthcare is expanding most quickly as contactless mandates reshape procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German government procurement channels while Chinese volume manufacturers compress unit economics across consumer electronics tiers.
United States
Hospital IT departments in Boston and New York Metro issue separate RFPs for patient identification infrastructure, displacing bundled modules from legacy EHR vendors. The FDA oversees biometric device integration into regulated healthcare workflows. NIST testing frameworks in Maryland shape federal identity system specifications that vendors must satisfy for procurement eligibility.
China
MIIT encryption standards accelerate domestic production of fingerprint and iris sensors for financial and transit applications across Shenzhen and Shanghai. State-connected identity infrastructure mandates domestic cryptographic modules. The Yangtze River Delta cluster hosts wafer-level packaging facilities supplying mid-tier smartphone manufacturers.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia pursue HIMSS Stage 7 certification where patient matching accuracy carries reimbursement implications. The EU AI Act imposes strict conformity assessment procedures for automated recognition in public spaces. Berlin anchors government identity projects specifying multimodal fusion with explicit purpose limitation.
India
The UIDAI ecosystem generates pull-through demand for low-cost fingerprint and iris sensors in rural banking and ration distribution across Maharashtra and Karnataka. RBI guidelines shape authentication requirements for financial inclusion programs. Telangana hosts sensor assembly operations serving domestic identity verification deployments.
Japan
Automotive OEMs in Aichi Prefecture integrate in-cabin biometrics for driver monitoring systems as METI guidelines mature. JIS standards govern sensor performance specifications for industrial access control applications. The Kansai region concentrates payment terminal manufacturing migrating toward ultrasonic modules.
Biometric Sensors Market Vendor Landscape
Semiconductor-integrated conglomerates and specialized biometric module fabricators split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: wafer-level packaging specialists controlling unit economics, multimodal platform providers anchoring government contracts, and automotive-grade reliability vendors penetrating industrial channels. Competitive dynamics revolve around backward integration into semiconductor fabrication and compliance engineering for regulatory divergence between restrictive and permissive jurisdictions.
Among Asia-Pacific-based module suppliers, Shenzhen Goodix Technology Co., Ltd. and NEC Corporation occupy positions reflecting divergent strategic emphases. Infineon Technologies AG exemplifies the semiconductor-integrated archetype with captive sensor fabrication. These three entities represent the spectrum from volume consumer electronics supply to premium government identity infrastructure, illustrating how geographic regulatory exposure and vertical integration depth determine competitive positioning across procurement channels.
| Leading Market Players |
|---|
| NEC Corporation |
| Infineon Technologies AG |
| Synaptics Incorporated |
| IDEX Biometrics ASA |
| Shenzhen Goodix Technology Co., Ltd. |
| Fujitsu |
| Thales |
| IDEMIA |
| Fingerprint Cards AB |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Taiwan and South Korea for advanced BSI-CIS fabrication determines both the widening premium-to-standard pricing spreads and the geographic concentration of module assembly operations. Wafer-level packaging advances in China compress mid-tier smartphone sensor costs while EU AI Act compliance investments inflate premium-tier government identity system pricing.
Pricing Analysis
The configured-to-order premium spread separates standard capacitive fingerprint modules from ultrasonic and multimodal fusion systems engineered for healthcare workstations and automotive in-cabin applications. Pricing stratifies across premium, standard, and economy tiers based on certification grade—NIST FRVT validation for federal procurement versus consumer-grade FIDO2 compliance—and volume scale with smartphone OEM contracts. Cost compression in capacitive modules is intensifying because Shenzhen Goodix and domestic Chinese competitors exploit backward integration into wafer-level packaging. Government identity integrators exhibit the lowest price sensitivity due to multimodal fusion mandates and extended EU AI Act conformity timelines.
Supply Chain Analysis
Export-control regimes restricting advanced CMOS image sensor technology to Chinese foundries limit domestic production of high-performance facial recognition modules for state-connected infrastructure. Taiwan, South Korea, and Japan anchor supply for BSI-CIS wafers, piezoelectric transducers, and near-infrared emitters respectively. Raw material dependencies span silicon wafers, rare-earth phosphors for iris illumination, and specialized epoxy resins for sensor packaging. Single-source vulnerability concentrates in Taiwan's foundry capacity for advanced node fabrication. Distribution runs through smartphone OEM direct procurement, government identity system integrators, and healthcare IT VAR channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment—NIST certification requirements, EU AI Act conformity infrastructure, and China's MIIT encryption mandates—creates sticky procurement relationships that resist price-based displacement.
For Market Incumbents: Pre-empt margin erosion in smartphone capacitive modules by accelerating ultrasonic migration into payment terminals and healthcare workstations where surface contamination resistance commands reliability premiums. Invest in captive wafer-level packaging capacity to defend against Chinese cost compression. Anchor government identity contracts through multimodal fusion platforms with embedded purpose-limitation protocols that satisfy EU AI Act high-risk classification requirements. For New Entrants and Emerging Players: Establish a beachhead in India's UIDAI ecosystem where rural banking and ration distribution generate pull-through demand for low-cost fingerprint and iris sensors with minimal certification burden. Target automotive in-cabin biometrics as NHTSA guidelines mature for driver monitoring systems. Pursue direct hospital IT procurement relationships in the United States and United Kingdom where unbundling from EHR platform contracts creates vendor access previously monopolized by Epic and Cerner. For Investors and Strategic Acquirers: The EU AI Act's third-party conformity assessment mandate reshapes the acquisition landscape toward compliance-engineering capabilities and human-in-the-loop review infrastructure. Long-term viability centers on vendors with demonstrated regulatory navigation across restrictive and permissive jurisdictions rather than pure technology differentiation. Acquisition target archetype: specialized biometric middleware providers with embedded fundamental rights impact assessment workflows. Watch NIST FRVT demographic parity validation timelines as an inflection signal for federal procurement eligibility windows.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Module Migration | Captures sub-dermal imaging premiums in healthcare and automotive channels beyond smartphone flagships. |
| EU AI Act Compliance Engineering | Embeds purpose-limitation protocols and human oversight mechanisms required for high-risk biometric deployments. |
| Wafer-Level Packaging Expansion | Collapses per-unit sensor costs below mid-tier smartphone integration thresholds in China and India. |
| Multimodal Fusion Platform Development | Converges liveness detection with thermal imaging for spoof-resistant government identity infrastructure. |
| Healthcare IT Direct Procurement | Displaces bundled EHR authentication modules through separate RFPs for patient identification infrastructure. |
Methodological Framework
Operator-level perspectives from biometric sensor procurement managers at smartphone OEMs, government identity system integrators, hospital IT directors, and automotive Tier 1 suppliers anchored the qualitative base. Secondary validation drew from NIST FRVT test results, EU AI Act technical documentation requirements, MIIT encryption standard filings, and SEC disclosures from semiconductor-integrated vendors. Bottom-up unit shipment estimates across fingerprint, facial, iris, and voice modalities were triangulated against top-down market value reconstructions.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning technology tier, application vertical, end-user type, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical adoption rates in government identity, smartphone integration, and healthcare contactless mandates. Industry-specific forecast inputs included wafer-level packaging cost curves, EU AI Act implementation timelines, and UIDAI ecosystem expansion trajectories.
Stress conditions across semiconductor foundry capacity allocation, CMOS image sensor wafer pricing volatility, and EU AI Act conformity assessment duration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory implementation pace and technology substitution thresholds. Material shifts in export-control regime stringency or NHTSA biometric mandate timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Consumer Grade Electrochemical CO Sensor Market
Sensors and Controls
APAC Nano Sensors Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Printed Antenna Market
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
Pressure Sensor Market
Sensors and Controls
IR Emitter and Receiver Market
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
Lidar Ceilometer Market