
 Speech Intelligibility Devices Market | 2026-2036
Speech Intelligibility Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Speech Intelligibility Devices Market Analytics
Project finance and equipment leasing for assistive technology is fragmenting competitive access across the speech intelligibility landscape. Tobii Dynavox AB leverages its vertical integration in eye-tracking and speech synthesis to sustain premium positioning in educational and clinical channels. PRC-Saltillo anchors its market presence through specialized symbol-based language software that dominates pediatric rehabilitation settings. Zygo Corporation competes through durable hardware designs that extend product lifecycles in institutional procurement cycles.
Speech intelligibility devices encompass electronic systems engineered to enhance, transmit, or synthesize human speech for users with communication impairments, typically operating across frequency ranges of 300–3400 Hz with signal-to-noise ratios exceeding 15 dB for clinical-grade clarity. These systems serve industrial and commercial purposes in rehabilitation, telecommunications infrastructure, and public safety announcements where acoustic intelligibility directly determines functional outcomes. Hearing aids and amplifiers command the largest installed base within product type segments, though speech-language software captures expanding margin pools as cloud-based subscription models replace perpetual licensing. Digital signal processing leads technology adoption due to real-time adaptive noise cancellation capabilities, while wireless communication protocols are displacing wired installations in educational institutions seeking flexible classroom configurations.
FDA 510(k) clearance pathways govern medical device classification for speech-generating equipment in the United States, while the EU Medical Device Regulation imposes clinical evidence requirements that reshape market entry timelines for manufacturers seeking CE marking. HIPAA compliance obligations in American healthcare settings and GDPR data protection standards in European educational deployments further constrain how user speech data travels across cloud-connected platforms. Stakeholders must monitor how reimbursement code expansions in Medicare and national health systems interact with software update cycles to determine total cost of ownership trajectories.
Market Dynamics
Medicare reimbursement pathway expansions for augmentative and alternative communication devices are compressing procurement cycles for healthcare facilities while amplifying competitive pressure on manufacturers to demonstrate clinical efficacy metrics.
Growth Catalysts
- Statutory health insurance coverage:Germany's hearing center networks mandate device procurement through centralized reimbursement frameworks, creating predictable demand volume for amplifier and transmitter systems.
- Digital signal processing advances:Real-time adaptive noise cancellation capabilities embedded in clinical-grade hardware improve speech clarity metrics beyond the 15 dB signal-to-noise threshold.
- Cloud-based subscription models:Speech-language software vendors capture expanding margin pools as perpetual licensing structures give way to recurring revenue architectures in educational deployments.
Market Restraints
- EU Medical Device Regulation clinical evidence requirements:CE marking timelines extend substantially for speech-generating equipment, delaying market entry for non-incumbent manufacturers.
- Semiconductor component concentration:Specialized DSP chip fabrication concentrates in East Asian foundries, exposing supply continuity to geopolitical friction.
- Frequency bandwidth limitations:Narrowband transmission standards in legacy telecommunications infrastructure constrain full-spectrum speech fidelity for remote communication applications.
Strategic Opportunities
- Pediatric rehabilitation underpenetration:Symbol-based language software adoption remains below 40% in Medicaid-eligible school districts across the southern United States.
- Eye-tracking convergence with speech synthesis:Integration of gaze-controlled input with predictive text algorithms opens motor-impaired patient segments previously excluded from device access.
- Flexible classroom configurations:Wireless communication protocol adoption in K-12 institutions displaces wired installations, enabling portable device ecosystems.
Industry Challenges
- Speech-language pathologist certification bottlenecks:Device prescription authority requires state-licensed clinical evaluation, constraining sales velocity in regions with practitioner shortages.
- HIPAA-GDPR data governance friction:Cloud-connected platforms face conflicting cross-border data residency obligations when serving multinational educational institutions.
- Legacy analog system integration:Institutional procurement cycles extend product replacement timelines, delaying digital upgrade adoption in budget-constrained rehabilitation centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speech Intelligibility Devices Market |
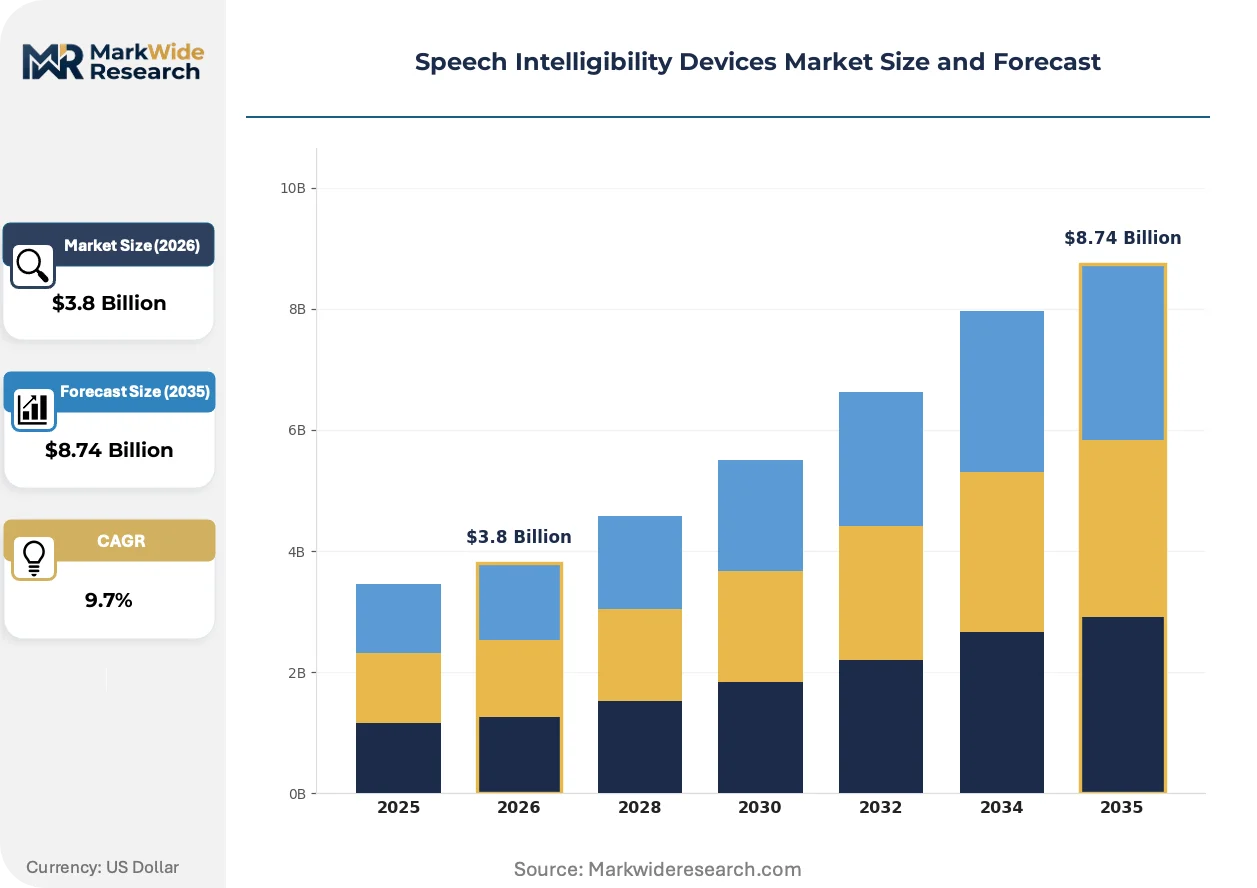
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amplifiers, Hearing Aids, Speech-Language Software, Transmitters Technology: Digital Signal Processing, Wireless Communication, Acoustic Feedback Suppression, Noise Reduction End User: Clinics, Hospitals, Educational Institutions, Hearing Centers Application: Telecommunications, Educational Tools, Rehabilitation, Public Announcements |
| Companies Covered | Tobii Dynavox AB, PRC-Saltillo, Lingraphica, Textspeak Corporation, Zygo Corporation, Adaptivation, Inc., Abilia Ltd, AbleNet, Inc., Zyteq Pty. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speech Intelligibility Devices Market Evolving Landscape
Signal processing hardware miniaturization and adaptive algorithm deployment are fundamentally restructuring how speech intelligibility systems achieve clinical-grade performance at reduced cost points.
Edge-computing DSP architectures are collapsing the cost-performance ratio for real-time noise suppression in portable devices. School districts in the United States are adopting these systems at accelerated replacement cycles. The technology is collapsing premium pricing tiers for mid-range amplification hardware.
FDA 510(k) clearance pathway refinements for software-as-a-medical-device are compressing regulatory review timelines for cloud-based speech platforms. Manufacturers now submit algorithm updates through pre-established predicate device frameworks. Pediatric rehabilitation settings benefit most from accelerated deployment cycles.
Subscription-based procurement is displacing capital expenditure models in institutional buying. Educational cooperatives in Germany aggregate demand through centralized leasing arrangements. Hearing center networks in Bavaria and North Rhine-Westphalia demonstrate the strongest migration velocity toward operational expenditure structures.
Speech Intelligibility Devices Market Segmentation
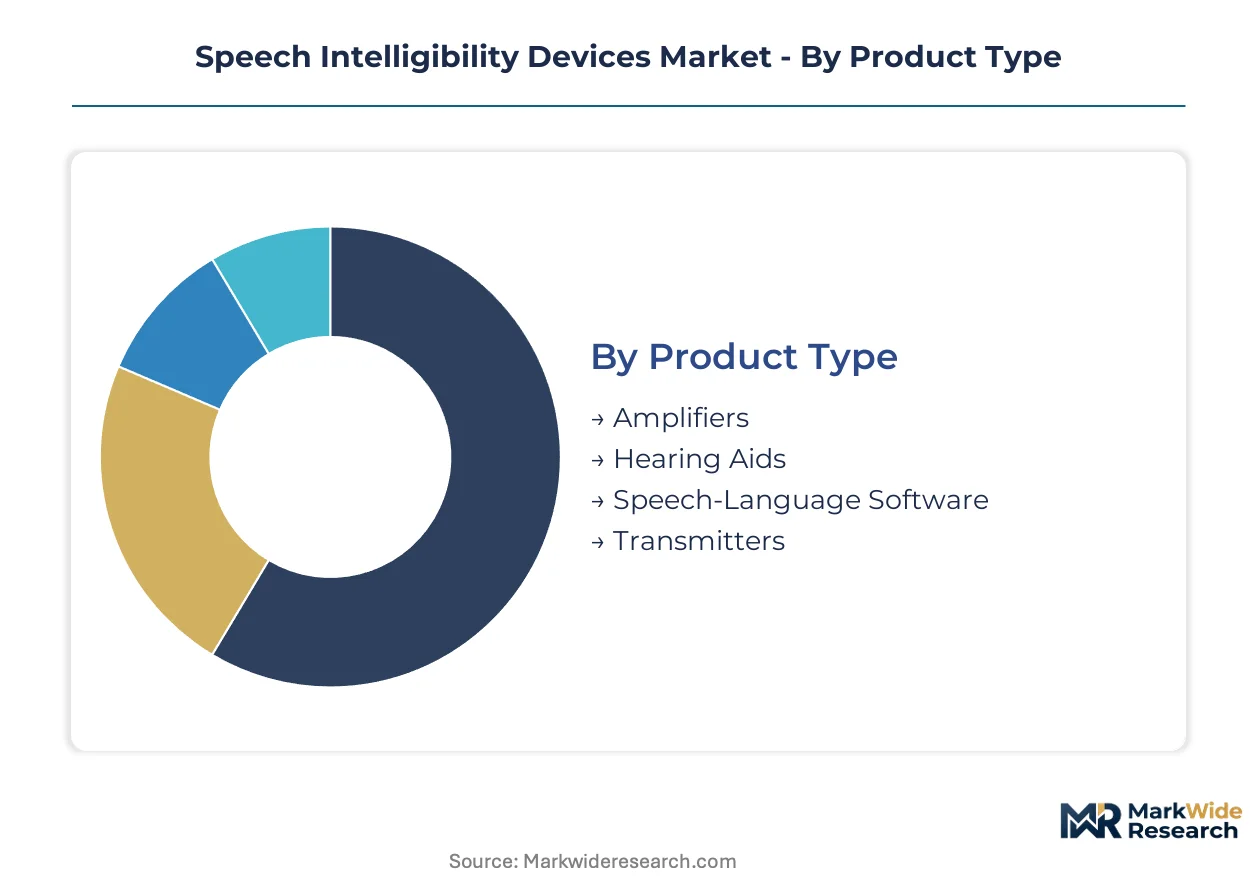
Speech intelligibility devices serve heterogeneous user needs across clinical, educational, and telecommunications contexts. Segmentation reveals where hardware replacement cycles compress against software subscription renewals, and which end-user procurement patterns concentrate margin capture.
Product Type:
Hearing aids and amplifiers turn over on 4-7 year institutional cycles, while software licenses refresh annually; transmitters occupy intermediate replacement rhythms tied to infrastructure upgrade waves.
- Hearing Aids:Miniaturized DSP architectures with adaptive noise cancellation operating across 300-3400 Hz frequency ranges. Demand concentrates in German hearing center networks under statutory insurance reimbursement, where clinical-grade clarity thresholds exceed 15 dB signal-to-noise ratios.
- Speech-Language Software:Cloud-deployed symbol-based language platforms with predictive text algorithms. Medicaid-eligible school districts across the southern United States drive expansion as perpetual licensing migrates to recurring subscription models.
- Amplifiers:Portable and fixed-installation units with real-time acoustic feedback suppression.
- Transmitters:Wireless broadcast systems for classroom and public address deployment.
Hearing aids dominate installed base. Speech-language software is where expansion concentrates.
Technology:
Cost tiers separate premium clinical-grade DSP from mid-range noise reduction implementations, with wireless protocols commanding hardware integration premiums.
- Digital Signal Processing:Real-time adaptive algorithms compressing hardware costs while improving speech clarity metrics. Edge-computing architectures are collapsing cost-performance ratios in portable devices deployed across United States school districts.
- Wireless Communication:Bluetooth and proprietary RF protocols enabling flexible classroom configurations. K-12 institutions in Germany displace wired installations fastest where centralized leasing arrangements aggregate procurement volume.
- Acoustic Feedback Suppression:Notch filtering and phase cancellation circuits for hearing aid stability.
- Noise Reduction:Spectral subtraction and beamforming techniques for challenging acoustic environments.
Digital signal processing commands premium pricing tiers. Wireless communication protocols are climbing the fastest as educational procurement shifts to operational expenditure models.
End User:
Volume concentrates in hearing centers and hospitals with centralized reimbursement pathways, while clinics and educational institutions fragment across decentralized purchasing authorities.
- Hearing Centers:Specialized facilities in Germany's Bavaria and North Rhine-Westphalia regions with statutory insurance procurement mandates. Network consolidation creates predictable demand volume for amplifier and transmitter systems.
- Hospitals:Acute and rehabilitation settings with Medicare reimbursement pathway access in the United States. FDA 510(k) clearance requirements govern device classification, compressing procurement cycles for augmentative communication equipment.
- Clinics:Outpatient speech-language pathology practices with state-licensed prescription authority.
- Educational Institutions:K-12 and higher education deployments with HIPAA-GDPR data governance obligations for cloud-connected platforms.
Hearing centers dominate installed base. Educational institutions are where expansion concentrates.
Application:
Customer type stratification separates institutional rehabilitation procurement from consumer-facing telecommunications and public safety deployments.
- Rehabilitation:Pediatric and adult speech therapy settings with symbol-based language software adoption. Eye-tracking convergence with speech synthesis opens motor-impaired patient segments previously excluded from device access.
- Educational Tools:Classroom amplification and assistive communication for students with disabilities. Wireless protocol adoption enables portable device ecosystems as United States school districts accelerate replacement cycles.
- Telecommunications:Remote communication infrastructure constrained by narrowband transmission standards in legacy systems.
- Public Announcements:Transportation hubs and emergency broadcast systems where acoustic intelligibility determines functional outcomes.
Rehabilitation dominates installed base. Educational tools are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement pathway expansions in the United States and statutory health insurance mandates in Germany are redistributing procurement volume toward concentrated healthcare networks while compressing sales cycles for augmentative communication equipment.
United States
FDA 510(k) clearance refinements for software-as-a-medical-device are accelerating deployment timelines for cloud-based speech platforms. Medicare reimbursement codes for augmentative and alternative communication devices compress procurement cycles for hospitals in acute and rehabilitation settings. Pediatric rehabilitation demand concentrates in Medicaid-eligible school districts across southern states where symbol-based language software adoption remains below penetration thresholds.
Germany
Statutory health insurance coverage mandates through centralized reimbursement frameworks create predictable demand volume for amplifier and transmitter systems. EU Medical Device Regulation clinical evidence requirements reshape market entry timelines for manufacturers seeking CE marking on speech-generating equipment. Hearing center networks in Bavaria and North Rhine-Westphalia demonstrate the strongest migration velocity toward operational expenditure leasing structures.
United Kingdom
NHS procurement frameworks for assistive technology aggregate demand through regional clinical commissioning groups. GDPR data protection standards constrain how user speech data travels across cloud-connected platforms deployed in educational institutions. London and Southeast England concentrate rehabilitation service delivery where eye-tracking convergence with speech synthesis opens motor-impaired patient segments.
Japan
PMDA medical device classification pathways govern speech-generating equipment approval timelines for manufacturers entering the market. METI industrial policy supports domestic production of miniaturized DSP architectures for hearing aid applications. Kanto region rehabilitation centers in Tokyo metropolitan clusters drive procurement volume for clinical-grade clarity systems exceeding signal-to-noise thresholds.
Canada
Health Canada medical device licensing requirements parallel FDA pathways while imposing distinct clinical evidence standards on speech-generating equipment. Provincial health insurance programs vary in coverage for augmentative communication devices, creating fragmented procurement authority across Ontario and Quebec. Greater Toronto Area hearing clinics concentrate demand for portable amplification hardware with real-time acoustic feedback suppression.
Speech Intelligibility Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authorities in educational and healthcare settings. The vendor base separates into three strategic archetypes: eye-tracking integrated platform providers, symbol-based language software specialists, and durable hardware fabricators serving institutional replacement cycles. Dominant competitive moves include vertical integration into upstream DSP component supply and subscription-based revenue model transitions displacing perpetual licensing structures.
Within the eye-tracking convergence tier, Tobii Dynavox AB represents integrated platform positioning that combines gaze-controlled input with predictive text algorithms. PRC-Saltillo occupies a position among symbol-based language software specialists dominating pediatric rehabilitation settings. Zygo Corporation exemplifies the durable hardware archetype with product lifecycle extension strategies targeting institutional procurement cycles in budget-constrained rehabilitation centers.
| Leading Market Players |
|---|
| Tobii Dynavox AB |
| PRC-Saltillo |
| Lingraphica |
| Textspeak Corporation |
| Zygo Corporation |
| Adaptivation, Inc. |
| Abilia Ltd |
| AbleNet, Inc. |
| Zyteq Pty. Ltd. |
| Others |
Value Network & Pricing Analysis
Undercapacity in East Asian DSP foundries is compressing component availability for clinical-grade hardware while simultaneously hardening pricing postures for manufacturers serving Medicare reimbursement pathways in the United States. Utilization rates above 85% in Taiwanese semiconductor fabrication are forcing device makers to absorb input cost volatility or pass through to institutional buyers with multi-year procurement contracts.
Pricing Analysis
Certification level (FDA 510(k) vs. CE marking under EU MDR) creates the primary spread between premium clinical-grade systems and mid-range educational deployments. Three-tier pricing structure across premium, standard, and economy levels stratifies by signal-to-noise performance thresholds and software subscription bundling. Cost compression in the standard tier is intensifying because edge-computing DSP architectures from United States school districts are collapsing legacy hardware premiums. Medicaid-eligible school districts exhibit highest price sensitivity; German hearing center networks under statutory insurance show lowest.
Supply Chain Analysis
Specialized DSP chip fabrication feeds from Taiwan, South Korea, and Japan, with analog component sourcing concentrated in China and Malaysia. Raw material dependencies include silicon wafers, rare-earth magnets for miniature transducers, and lithium-ion cells for portable amplification units. Single-source vulnerability in 7nm process node capacity exposes supply continuity to geopolitical friction. Distribution runs through audiology equipment distributors in healthcare channels and educational cooperatives in K-12 institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Speech intelligibility devices represent a service-attach opportunity where cloud-based software subscription renewals are expanding faster than hardware replacement cycles, particularly in United States educational deployments migrating from perpetual licensing.
For Market Incumbents: Insulate premium positioning through captive supply of edge-computing DSP components and accelerated FDA 510(k) clearance for software-as-a-medical-device updates. Eye-tracking convergence specialists threaten margin pools in motor-impaired segments; backward integration into predictive text algorithm development is the defensive priority. For New Entrants and Emerging Players: Pediatric rehabilitation underpenetration in Medicaid-eligible southern United States school districts offers the most accessible white-space target. Symbol-based language software adoption below 40% in these regions enables direct-to-district subscription sales bypassing incumbent audiology distribution. Partner with state-licensed speech-language pathologists for prescription authority validation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native speech-language software platforms as recurring revenue architectures displace hardware-heavy business models. Target acquisition archetypes are vertical specialists with installed base conversion potential to subscription billing. Watch for Medicare reimbursement code expansions as inflection signal for hardware procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-a-Medical-Device FDA Submission | Accelerates deployment timelines for cloud-based speech platforms in pediatric rehabilitation. |
| EU MDR CE Marking Pathway | Unlocks statutory insurance procurement in German hearing center networks with centralized frameworks. |
| Hospital System Partnership | Secures Medicare reimbursement pathway access for augmentative communication equipment in acute settings. |
| Software Companion Development | Captures expanding margin pools as subscription models replace perpetual licensing in educational deployments. |
| Reimbursement Strategy | Aligns device classification with Medicaid eligibility criteria for southern United States school districts. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committees, GPO contracts managers, and speech-language pathologists converged on the working assumptions underpinning demand forecasts. Primary interviews with these stakeholders were cross-referenced against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR clinical evidence submissions. Bottom-up unit economics were triangulated with top-down market sizing across the analysis window.
Demand-supply balance dynamics anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type (hearing aids, speech-language software, amplifiers, transmitters), technology tier (clinical-grade DSP, mid-range noise reduction, wireless protocols), end-user concentration (hearing centers, hospitals, educational institutions), and regional regulatory cluster (FDA-cleared United States, CE-marked Europe, PMDA-governed Japan). CAGRs were derived from replacement cycle compression rates and subscription renewal velocity. Forecast inputs incorporated Medicare reimbursement pathway expansion timelines and statutory insurance mandate coverage breadth.
The forecast holds incumbent behavior within observed patterns; aggressive moves by eye-tracking convergence specialists or cloud-native software entrants would shift outcomes beyond modeled ranges. Quarterly review of FDA 510(k) clearance velocity, German hearing center leasing arrangement migration, and Medicaid software adoption rates in southern United States school districts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Taiwan Sensors Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Touchless Sensing Market
Sensors and Controls
Germany Non-Contact Infrared Thermometer Market
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Europe MEMS and Sensors Market
Sensors and Controls
Global Wireless Sensors Network Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Microsensor Market