
 APAC Nano Sensors Market | 2026-2036
APAC Nano Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Nano Sensors Market Outlook
China's GB standards compliance is restructuring the cost-of-entry calculus for foreign nano sensor manufacturers seeking market access. STMicroelectronics leverages its European design heritage to compete in high-reliability automotive nano sensing modules across Chinese OEM supply chains. Samsung Electronics anchors its position through captive semiconductor fabrication, extending in-house production of MEMS nano sensor wafers for wearable device OEMs. Texas Instruments Incorporated dominates signal conditioning IC architectures that interface with electromechanical nano sensor arrays.
Nano sensors are transduction devices engineered at sub-100 nanometer scale, typically fabricated through electron-beam lithography or focused ion beam milling, detecting physical, chemical, or biological stimuli with detection thresholds reaching single-molecule resolution. Their primary commercial purpose centers on real-time environmental and physiological monitoring where conventional sensors lack spatial or sensitivity resolution. Optical technology leads in structural health monitoring applications due to fiber Bragg grating immunity to electromagnetic interference, while biological sensors represent the fastest-expanding margin pool as point-of-care diagnostic platforms proliferate across APAC healthcare procurement. Chemical sensors occupy a mature position in water quality networks, though acoustic technology is displacing legacy approaches in industrial predictive maintenance systems.
Japan's METI enforces JIS standards that dictate nano sensor calibration protocols for automotive safety systems, while South Korea's MFDS regulates biological sensor biocompatibility for clinical deployment. India's BIS certification requirements for imported electronic components create additional compliance layers for chip sensor vendors entering that procurement channel. Stakeholders must monitor divergence between China's SAMR market access rules and ASEAN harmonization frameworks as the primary determinant of regional manufacturing location strategy.
Market Dynamics
China's dual carbon goals and GB standards compliance are restructuring manufacturing location decisions across the APAC nano sensor value chain, forcing foreign suppliers to localize fabrication or exit procurement channels entirely.
Growth Catalysts
- Healthcare digitization mandates:Southeast Asian health ministries are embedding nano sensors into remote patient monitoring networks, creating sustained procurement volume for physiological monitoring devices.
- Japan's JIS calibration protocols:METI-enforced automotive safety standards require nano sensor certification for collision avoidance systems, generating premium-tier demand from precision manufacturing clusters.
- MEMS wafer fabrication advances:Electron-beam lithography throughput improvements are lowering unit costs for sub-100 nanometer transduction devices across South Korean semiconductor ecosystems.
Market Restraints
- Raw material concentration:Rare earth element refining for piezoelectric nano sensor substrates concentrates in Chinese processing facilities, exposing supply chains to export quota volatility.
- Technical resolution limits:Single-molecule detection thresholds in biological sensors face reproducibility constraints at commercial scale, constraining point-of-care diagnostic deployment.
- Regulatory fragmentation:Divergence between China's SAMR market access rules and ASEAN harmonization frameworks forces redundant certification expenditures for multi-country vendors.
Strategic Opportunities
- Underpenetrated Indian procurement:BIS certification requirements for imported electronic components have slowed foreign entry, creating first-mover advantage for domestic-assembled nano sensor modules.
- Industrial predictive maintenance:Acoustic nano sensor arrays are displacing legacy vibration monitoring in Japanese automotive and South Korean shipbuilding facilities.
- Technology convergence:Integration of fiber Bragg grating optical sensors with 5G edge computing infrastructure is enabling real-time structural health monitoring for civil engineering applications.
Industry Challenges
- Specialized fabrication talent scarcity:Focused ion beam milling operators and electron-beam lithography technicians command premium wages across APAC foundries, constraining capacity expansion timelines.
- Multi-jurisdiction compliance complexity:Vendors must simultaneously satisfy Japan's METI automotive protocols, South Korea's MFDS biocompatibility standards, and China's GB environmental certification, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Nano Sensors Market |
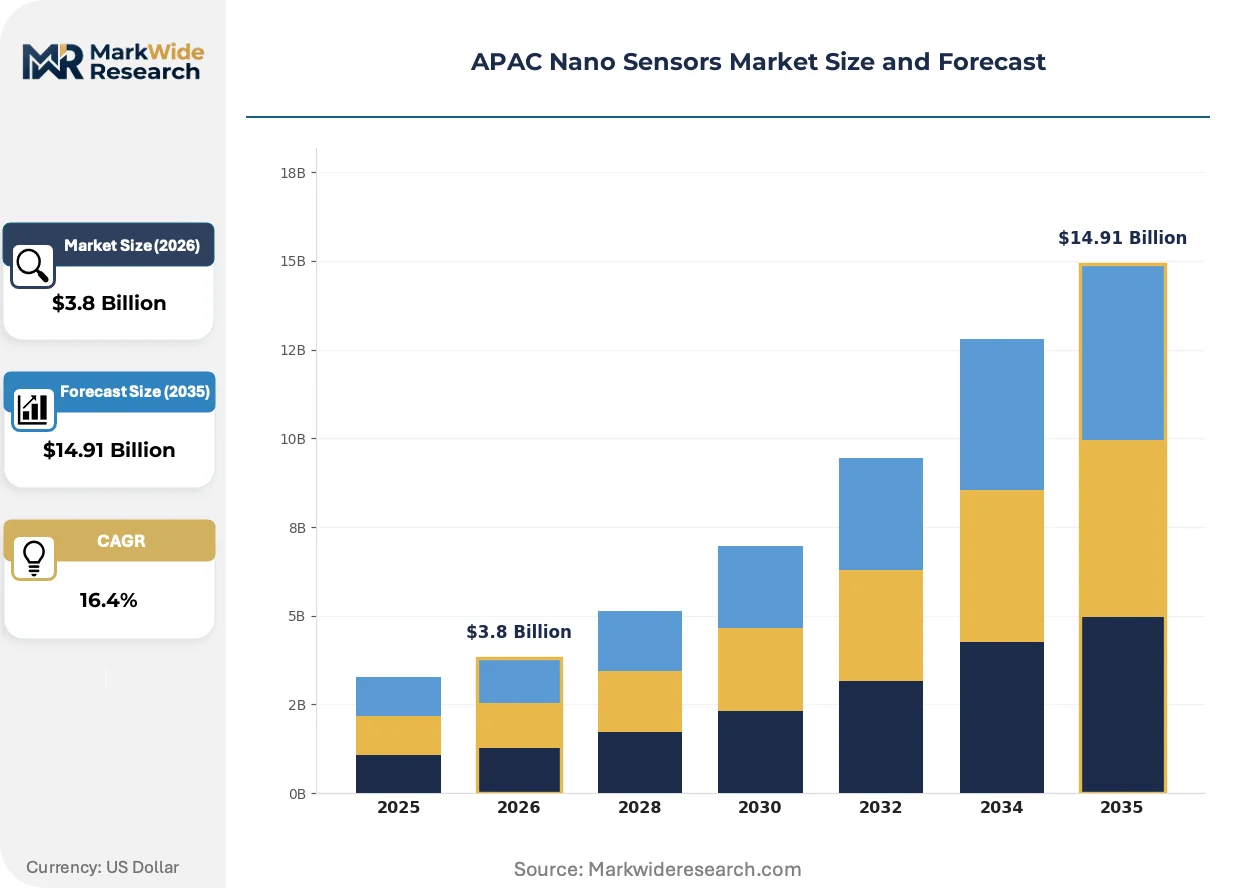
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chip Sensors, Fiber Optic Sensors, Biological Sensors, Chemical Sensors Technology: Optical, Electromechanical, Acoustic, Thermal End User: Aerospace, Healthcare, Environmental Monitoring, Automotive Application: Air Quality, Water Quality, Structural Health, Wearable Devices |
| Companies Covered | Analog Devices Inc, OMRON Corporation, Samsung Electronics, Toshiba Corporation, Honeywell International Inc, STMicroelectronics, Teledyne Technologies, Texas Instruments Incorporated, Bruker Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Nano Sensors Market Strategic Shifts
Optical nano sensing architectures are displacing electromechanical alternatives in high-interference environments, while biological sensor platforms compress diagnostic timelines from laboratory to point-of-care settings.
Photonic crystal nano sensors are decentralizing chemical detection infrastructure by enabling smartphone-integrated spectrometry for field-deployable water quality assessment. Municipal utilities in Vietnam and Thailand are piloting these devices for distributed contamination monitoring. The shift bypasses centralized laboratory bottlenecks, compressing response times from days to minutes for public health incidents.
China's GB/T environmental monitoring standards are mandating real-time particulate matter detection thresholds that legacy electrochemical sensors cannot satisfy. Domestic manufacturers are accelerating MEMS nano sensor wafer production to capture compliance-driven replacement cycles. Foreign vendors without localized fabrication face exclusion from state procurement channels under SAMR market access rules.
Hospital procurement departments across Singapore and Australia are unbundling sensor hardware from diagnostic service contracts, forcing vendors to compete on device economics rather than bundled platform pricing. This shift favors specialized nano sensor manufacturers over integrated diagnostic system suppliers. The restructuring is most visible in cardiovascular monitoring, where disposable biological sensor strips now account for the majority of recurring revenue streams.
APAC Nano Sensors Market Segmentation
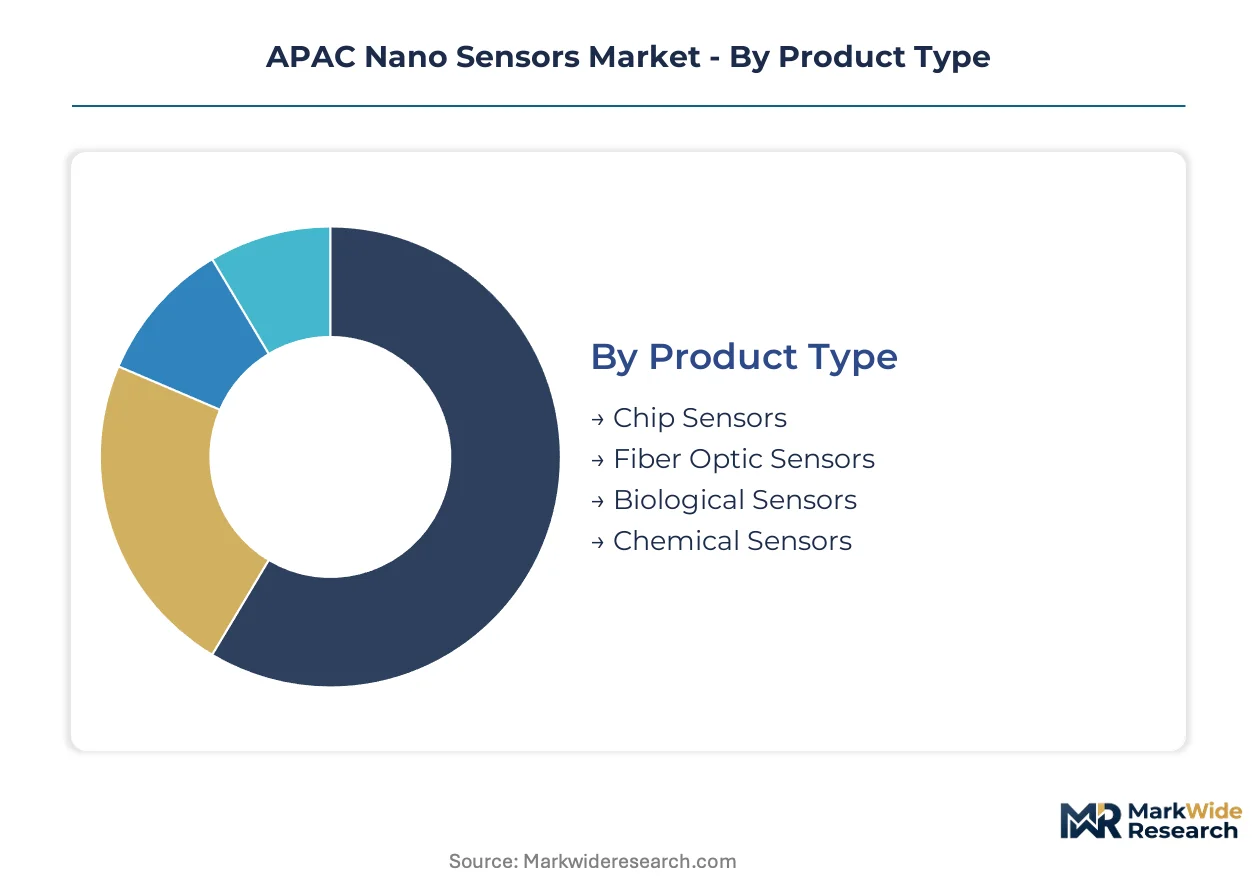
Segmentation in the APAC nano sensors market reveals divergent buyer priorities across procurement channels. Healthcare systems prioritize single-molecule sensitivity thresholds, while automotive OEMs demand JIS-certified calibration protocols for collision avoidance integration.
Product Type:
Cost tier drives procurement segmentation, with premium fabrication processes commanding distinct pricing bands against standardized commodity alternatives.
- Biological Sensors:Engineered for single-molecule detection thresholds using functionalized nanowire arrays or quantum dot probes. Demand concentrates in Singapore and Australian hospital procurement networks where unbundled diagnostic contracts favor disposable sensor strip economics over integrated platform pricing.
- Chemical Sensors:Deploy electrochemical or metal-oxide semiconductor transduction for ppb-level contaminant identification. China's municipal water utilities and Vietnam's distributed monitoring pilots generate replacement cycles as GB/T environmental standards tighten particulate detection mandates.
- Chip Sensors:MEMS-fabricated silicon substrates integrate signal conditioning for compact form factors. South Korean wearable device OEMs source captive wafer production from domestic foundries.
- Fiber Optic Sensors:Fiber Bragg grating architectures deliver EMI immunity for civil engineering applications. Japanese infrastructure contractors deploy these for real-time structural health monitoring of bridges and tunnels.
Biological sensors lead on scale through recurring diagnostic strip consumption; chemical sensors lead on momentum as environmental compliance deadlines accelerate replacement demand.
Technology:
Application environment dictates technology selection, with electromagnetic interference exposure and thermal cycling tolerance filtering viable architectures.
- Optical:Photonic crystal and interferometric architectures achieve femtometer displacement resolution. Japanese automotive suppliers specify these for precision manufacturing metrology where electromagnetic immunity is non-negotiable.
- Acoustic:Surface acoustic wave and bulk acoustic resonator platforms detect mass loading at picogram sensitivity. South Korean shipbuilding facilities and Japanese automotive plants are displacing legacy vibration monitoring with predictive maintenance arrays.
- Electromechanical:Piezoelectric cantilever and capacitive comb-drive structures dominate established industrial sensing. Rare earth substrate refining concentration in Chinese processing facilities exposes supply chains to quota volatility.
- Thermal:Calorimetric and bolometric transduction measure heat flux at microkelvin resolution. Niche deployment in semiconductor process control and battery thermal runaway detection.
Optical technology leads on scale through established fiber sensor infrastructure; acoustic platforms are expanding most quickly as industrial predictive maintenance budgets reallocate from scheduled to condition-based monitoring.
End User:
Customer procurement sophistication varies, with regulated medical and automotive verticals imposing certification barriers that filter vendor participation.
- Healthcare:Point-of-care diagnostic platforms and remote patient monitoring networks across Southeast Asian health ministries. South Korea's MFDS biocompatibility standards and Australia's TGA certification create multi-jurisdiction compliance complexity for biological sensor vendors.
- Automotive:Collision avoidance systems and battery management modules require METI-enforced JIS calibration protocols. Japan's precision manufacturing clusters generate premium-tier demand for certified nano sensing modules.
- Environmental Monitoring:China's dual carbon goals and GB standards compliance are accelerating domestic MEMS nano sensor production for real-time particulate detection. Foreign vendors without localized fabrication face SAMR market access exclusion.
- Aerospace:Structural health monitoring and propulsion system diagnostics demand radiation-hardened specifications. Limited procurement volume concentrates in defense-adjacent supply chains.
Healthcare leads on scale through recurring diagnostic consumables; environmental monitoring is gaining share fastest as compliance-driven replacement cycles concentrate procurement volume.
Application:
Maturity gradient separates established utility deployments from emerging wearable integration, with pricing power correlating to diagnostic outcome criticality.
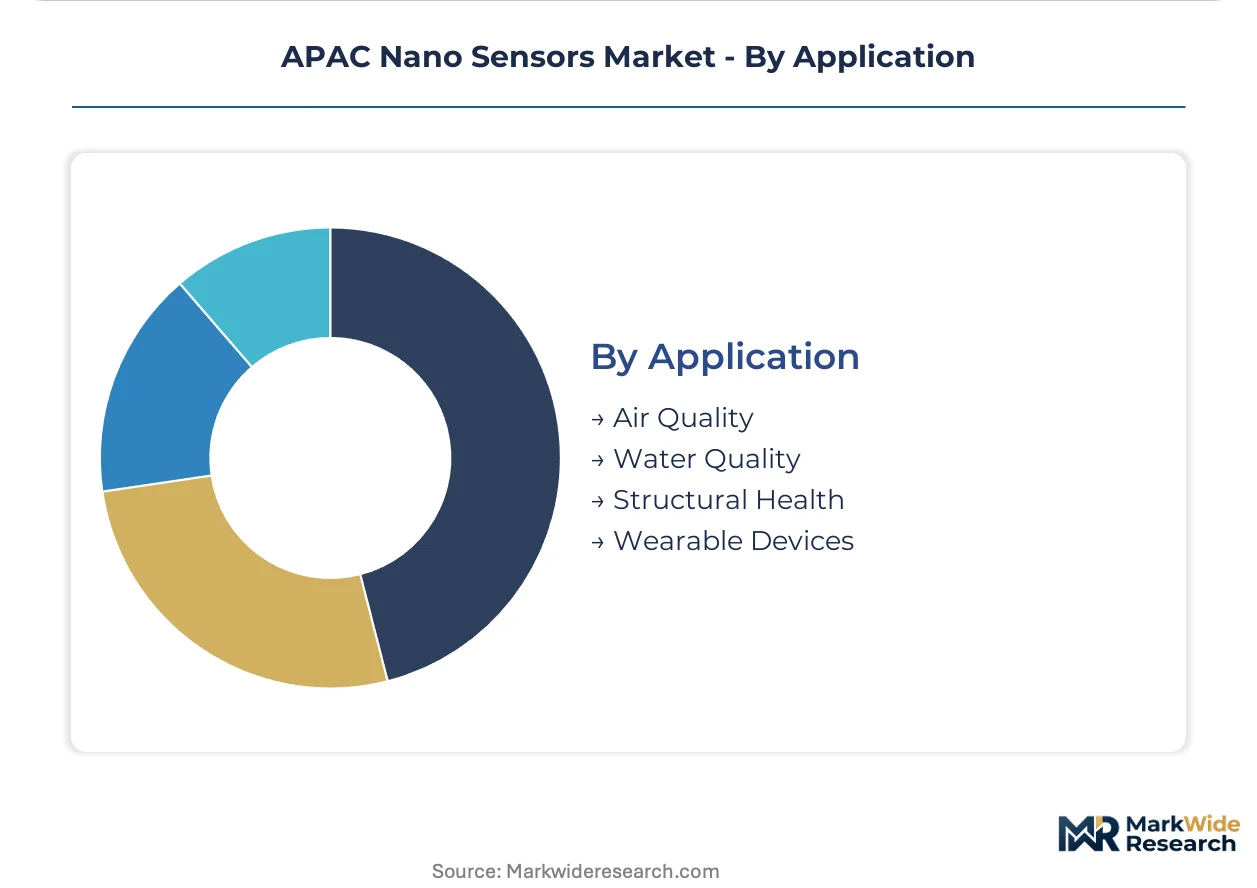
- Water Quality:Municipal utilities in Vietnam and Thailand pilot smartphone-integrated photonic crystal spectrometry for distributed contamination monitoring. The shift bypasses centralized laboratory bottlenecks, compressing public health response timelines.
- Wearable Devices:Continuous physiological monitoring drives MEMS nano sensor integration into consumer electronics. South Korean semiconductor ecosystems supply captive wafer fabrication for OEM supply chains.
- Air Quality:Electrochemical and metal-oxide sensors dominate established urban monitoring networks. China's GB/T standard thresholds are forcing replacement of legacy architectures unable to satisfy real-time particulate detection mandates.
- Structural Health:Fiber Bragg grating optical sensors integrated with 5G edge computing enable real-time civil engineering monitoring. Japanese infrastructure contractors and Australian mining operations deploy these for predictive maintenance of critical assets.
Water quality leads on scale through municipal utility procurement; wearable devices show the steepest expansion trajectory as consumer electronics OEMs integrate biometric monitoring at scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Focused ion beam milling technicians and electron-beam lithography specialists concentrate in South Korean foundry clusters and Japanese precision manufacturing zones, anchoring the region's fabrication capacity.
China
Environmental monitoring procurement accelerates as GB/T standards mandate real-time particulate detection thresholds. SAMR market access rules force foreign vendors to localize MEMS wafer fabrication or exit state procurement channels. Domestic manufacturers scale production in Yangtze River Delta clusters to capture compliance-driven replacement cycles.
Japan
METI-enforced JIS calibration protocols generate premium-tier demand for automotive collision avoidance systems. Precision manufacturing clusters in Kansai and Chubu supply certified nano sensing modules to domestic OEM supply chains. Tokyo-based infrastructure contractors deploy fiber Bragg grating optical sensors for real-time structural health monitoring.
South Korea
Captive semiconductor fabrication anchors MEMS nano sensor wafer production for wearable device OEMs. MFDS biocompatibility standards regulate biological sensor deployment in clinical settings. Daegu-Gyeongbuk foundry ecosystems leverage electron-beam lithography throughput improvements to lower unit costs for sub-100 nanometer devices.
India
BIS certification requirements for imported electronic components have slowed foreign nano sensor entry, creating first-mover advantage for domestic-assembled modules. Central government procurement channels favor localized production under Make in India incentives. Karnataka and Tamil Nadu electronics manufacturing clusters attract assembly investments from vendors seeking market access.
Singapore
Hospital procurement departments unbundle sensor hardware from diagnostic service contracts, favoring disposable biological sensor strip economics. Australian TGA certification creates multi-jurisdiction compliance complexity for vendors serving both markets. Biomedical manufacturing zones supply point-of-care diagnostic platforms across Southeast Asian health ministry networks.
APAC Nano Sensors Market Competitive Environment
The competitive structure tilts toward diversified electronics conglomerates with captive semiconductor fabrication. Player mix spans three tiers: integrated device manufacturers with in-house MEMS foundries, specialized sensor module assemblers serving regulated verticals, and fabless design houses licensing signal conditioning architectures. Strategic moves concentrate on backward integration into wafer production and geographic expansion through localized certification compliance.
Among diversified electronics conglomerates, Samsung Electronics exemplifies the captive-fabrication archetype through its semiconductor ecosystem control. STMicroelectronics occupies a position representing European design heritage competing in high-reliability automotive supply chains. Texas Instruments Incorporated anchors the signal conditioning tier, supplying interface architectures that electromechanical nano sensor arrays require.
| Leading Market Players |
|---|
| Analog Devices Inc |
| OMRON Corporation |
| Samsung Electronics |
| Toshiba Corporation |
| Honeywell International Inc |
| STMicroelectronics |
| Teledyne Technologies |
| Texas Instruments Incorporated |
| Bruker Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive semiconductor fabrication in South Korean foundry clusters anchors both supply security and premium pricing power for MEMS nano sensor wafers, while outsourced assembly in Southeast Asian electronics zones compresses margins for standardized modules. This bifurcation creates divergent economics across the APAC value chain.
Pricing Analysis
The bundled-vs-unbundled service split separates premium-tier procurement from commodity volume. Diagnostic platform vendors in Singapore and Australia now compete on disposable biological sensor strip economics rather than integrated system pricing. Price differentiation hinges on JIS calibration certification for automotive safety systems and GB standards compliance for environmental monitoring procurement. Cost compression in standardized chip sensors intensifies as South Korean captive fabrication scales output. Hospital procurement departments exhibit highest price sensitivity, while Japanese automotive OEMs absorb premiums for METI-certified collision avoidance modules.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth element refining for piezoelectric nano sensor substrates, exposing downstream fabricators to export quota volatility. MEMS wafer production concentrates in South Korea, Japan, and Taiwan, while final module assembly distributes across Vietnam, Thailand, and Malaysian electronics manufacturing zones. Raw material dependencies span gallium arsenide for optical transduction layers, platinum catalysts for electrochemical detection, and specialized photoresists for electron-beam lithography. Distribution runs through Tier 1 automotive suppliers in Japan, hospital procurement networks in Singapore and Australia, and state-owned utility channels in China under SAMR market access rules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's GB/T environmental monitoring standards and dual carbon goals are accelerating replacement demand for legacy sensor architectures.
For Market Incumbents: Cement fabrication capacity in Yangtze River Delta clusters to satisfy SAMR localization mandates and defend position against emerging domestic Chinese competitors. Deepen backward integration into rare earth substrate processing or secure long-term offtake agreements with Chinese refiners to mitigate quota volatility exposure. Prioritize JIS calibration protocol certification for automotive safety system procurement in Japan's precision manufacturing zones. For New Entrants and Emerging Players: Domestic-assembled module vendors serving India's BIS certification-constrained procurement channels face limited foreign competition and first-mover advantage. Target Karnataka and Tamil Nadu electronics manufacturing clusters under Make in India incentives. Enter through water quality monitoring pilots in Vietnam and Thailand where smartphone-integrated photonic crystal spectrometry displaces centralized laboratory infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for specialized sensor module assemblers with multi-jurisdiction certification capabilities because regulatory fragmentation forces redundant compliance expenditures that scale-efficient platforms can arbitrage. Focus on five-to-ten year viability windows for biological sensor platforms as point-of-care diagnostic procurement unbundles. Watch for convergence between China's SAMR rules and ASEAN harmonization frameworks as inflection indicator for regional manufacturing location strategy.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Secures piezoelectric substrate supply against Chinese export quota volatility. |
| JIS Calibration Protocol Certification | Unlocks premium-tier automotive collision avoidance system procurement in Japan. |
| GB Standards Compliance Investment | Enables market access to China's state-owned environmental monitoring procurement channels. |
| Multi-Jurisdiction Certification Platform | Captures arbitrage value from regulatory fragmentation across METI, MFDS, and SAMR frameworks. |
| MEMS Wafer Fabrication Scale-Up | Lowers unit costs for sub-100 nanometer devices through electron-beam lithography throughput gains. |
Study Parameters
Bottom-up end-use demand modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with MEMS foundry operations managers, hospital procurement directors, automotive Tier 1 supplier quality engineers, and environmental monitoring utility planners were cross-validated against secondary sources including SAMR market access filings, METI JIS standard documentation, MFDS biocompatibility submissions, and semiconductor trade flow data from customs authorities.
Historical trendline analysis of MEMS wafer production volumes, diagnostic platform procurement patterns, and environmental monitoring equipment replacement cycles informed the projection framework. Segmentation dimensions span product type, transduction technology, end-user vertical, and application maturity across the modeling period. CAGRs were derived from installed base growth rates, compliance-driven replacement timelines, and technology substitution curves for optical versus electromechanical architectures.
Underlying measurement precision varies by segment; healthcare diagnostic procurement carries tighter precision than aerospace defense-adjacent channels due to disclosed hospital contract values. Forecasts incorporate assumptions regarding GB standards enforcement timelines, rare earth export quota stability, and electron-beam lithography throughput improvements that could materially revise outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Europe Wearable Sensors Market
Sensors and Controls
APAC Occupancy Sensors Market
Sensors and Controls
United States Proximity Sensor Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
3D Profile Sensors Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
Submarine Sensor Market