
 In-Display Fingerprint Sensors Market | 2026-2036
In-Display Fingerprint Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
In-Display Fingerprint Sensors Market Outlook
Semiconductor packaging engineer availability is rotating toward optical module fabrication, constraining capacity expansion for ultrasonic sensor lines. Shenzhen Goodix Technology leverages its captive ASIC design team to control die-level integration costs. Qualcomm Technologies anchors the premium tier through its 3D Sonic platform, while Synaptics Incorporated competes by specializing in thin-film optical architectures for mid-range handset portfolios.
In-display fingerprint sensors embed biometric acquisition arrays beneath active-matrix OLED or LCD panels, using optical imaging, piezoelectric ultrasonic transduction, or capacitive field detection to capture ridge patterns through cover glass up to millimeter thicknesses; their primary commercial purpose is to eliminate physical button cutouts while maintaining false-accept rates below mandated security thresholds. Optical technology dominates unit shipments due to mature CMOS image sensor supply chains, yet ultrasonic modules command margin pools in flagship devices where moisture tolerance and live-finger detection justify premium positioning. Smartphone applications absorb the majority of volume, though laptop integration is accelerating as Windows Hello compatibility expands addressable hardware slots.
China's MIIT enforces GB standards for biometric data encryption on domestic devices, while the EU's GDPR and MDR frameworks impose consent-management and medical-grade accuracy requirements that filter vendor eligibility. The US FCC regulates electromagnetic emissions from sensor controllers, adding certification layers for multi-band 5G handsets. Stakeholders must monitor divergence between regional biometric data localization mandates and the modular design architectures that enable cross-market platform reuse.
Market Dynamics
Smartphone OEMs are eliminating physical button cutouts entirely, forcing sensor vendors to integrate biometric arrays beneath increasingly thick cover glass while maintaining false-accept rates below security thresholds. This structural push toward seamless industrial design concentrates procurement power among panel-integrator ecosystems in East Asian manufacturing clusters.
Growth Catalysts
- MIIT biometric encryption mandates:China's GB standards for biometric data security force domestic device upgrades, creating replacement demand for compliant in-display modules across mid-range handset portfolios.
- OLED panel proliferation:Active-matrix OLED adoption in laptops and tablets expands addressable hardware slots beyond smartphones, particularly for Windows Hello-compatible enterprise devices.
- Shenzhen manufacturing density:Panel-integrator ecosystems in Shenzhen and Seoul compress module assembly lead times and enable rapid prototyping for custom sensor geometries.
Market Restraints
- Semiconductor packaging engineer scarcity:Talent rotation toward optical module fabrication constrains capacity expansion for ultrasonic sensor lines, particularly for piezoelectric transducer packaging.
- Cover glass thickness limitations:Optical imaging performance degrades nonlinearly above millimeter-scale glass thickness, restricting design flexibility for ruggedized devices.
- GDPR-aligned certification costs:EU medical-grade accuracy requirements and consent-management frameworks filter vendor eligibility, raising compliance barriers for mid-tier sensor suppliers.
Strategic Opportunities
- Laptop biometric integration:Windows Hello compatibility expansion creates underpenetrated demand in enterprise notebook segments, particularly for thin-film optical architectures.
- Moisture-tolerant ultrasonic positioning:Premium handsets justify ultrasonic module premiums where live-finger detection and wet-finger performance differentiate security positioning.
- EU AI Act biometric governance:Emerging regulatory frameworks for automated biometric identification create compliance-service opportunities for sensor vendors with established GDPR documentation.
Industry Challenges
- ASIC design talent competition:Captive semiconductor design capabilities differentiate cost structures, yet engineer scarcity forces trade-offs between die-level integration and external procurement.
- Multi-band 5G electromagnetic certification:FCC emissions regulations for sensor controllers add certification layers and timeline risk for flagship handset launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Display Fingerprint Sensors Market |
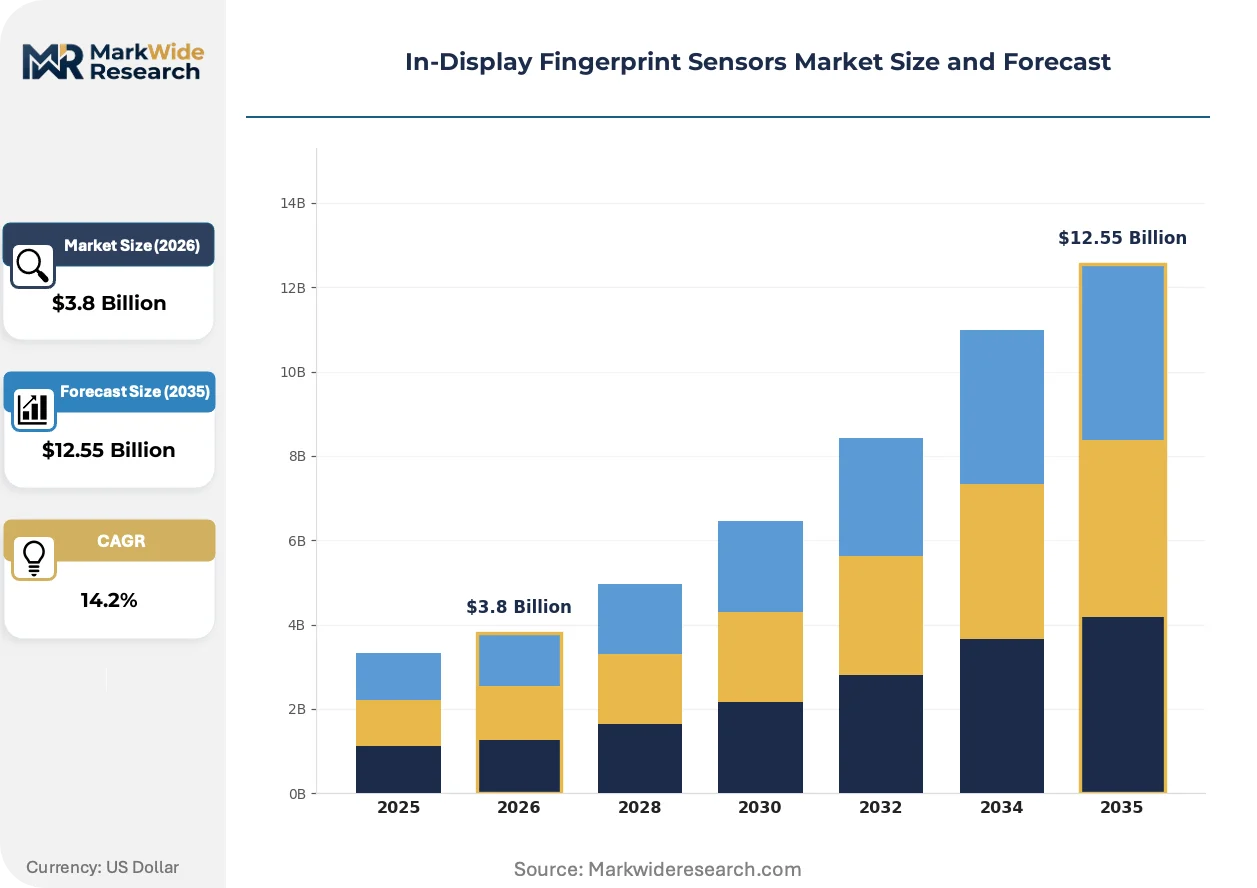
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Optical, Ultrasonic, Capacitive, Thermal Application: Smartphones, Laptops, Tablets, Wearables End User: Consumers, Enterprises, Government, Retail Deployment: On-Premises, Cloud, Hybrid, Embedded |
| Companies Covered | Synaptics Incorporated, Apple, Shenzhen Goodix Technology, CrucialTec, Novatek Microelectronics, Fingerprint Cards, Egis Technology, NEXT Biometrics, Qualcomm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Display Fingerprint Sensors Market Strategic Shifts
Ultrasonic transduction is displacing optical dominance in premium tiers, while regulatory fragmentation forces modular platform architectures. Supply chains are reconfiguring around panel-integrator ecosystems that control both display and biometric module procurement.
Ultrasonic fingerprint sensing uses piezoelectric transducers to capture ridge patterns through cover glass using acoustic reflection rather than optical imaging. Flagship smartphone OEMs are adopting 3D Sonic platforms for moisture tolerance and live-finger detection capabilities. This displacement of optical modules in devices above premium price thresholds is compressing margin pools for CMOS image sensor suppliers while rewarding vendors with captive transducer fabrication.
The EU's GDPR and MDR frameworks impose medical-grade accuracy requirements and consent-management protocols that filter vendor eligibility for devices sold in member states. Industrial consequence includes mandatory documentation of false-accept and false-reject rates for biometric authentication systems. Premium handset segments targeting EU distribution are responding by pre-certifying ultrasonic modules to clinical accuracy thresholds before product launch.
Enterprise procurement of biometric-enabled laptops is consolidating around Windows Hello compatibility as a non-negotiable security specification. Distribution through direct OEM relationships is replacing component distributor channels for high-volume notebook contracts. This pattern is most visible in North American and Western European enterprise refresh cycles, where IT departments mandate FIDO2-compliant authentication hardware.
In-Display Fingerprint Sensors Market Segmentation
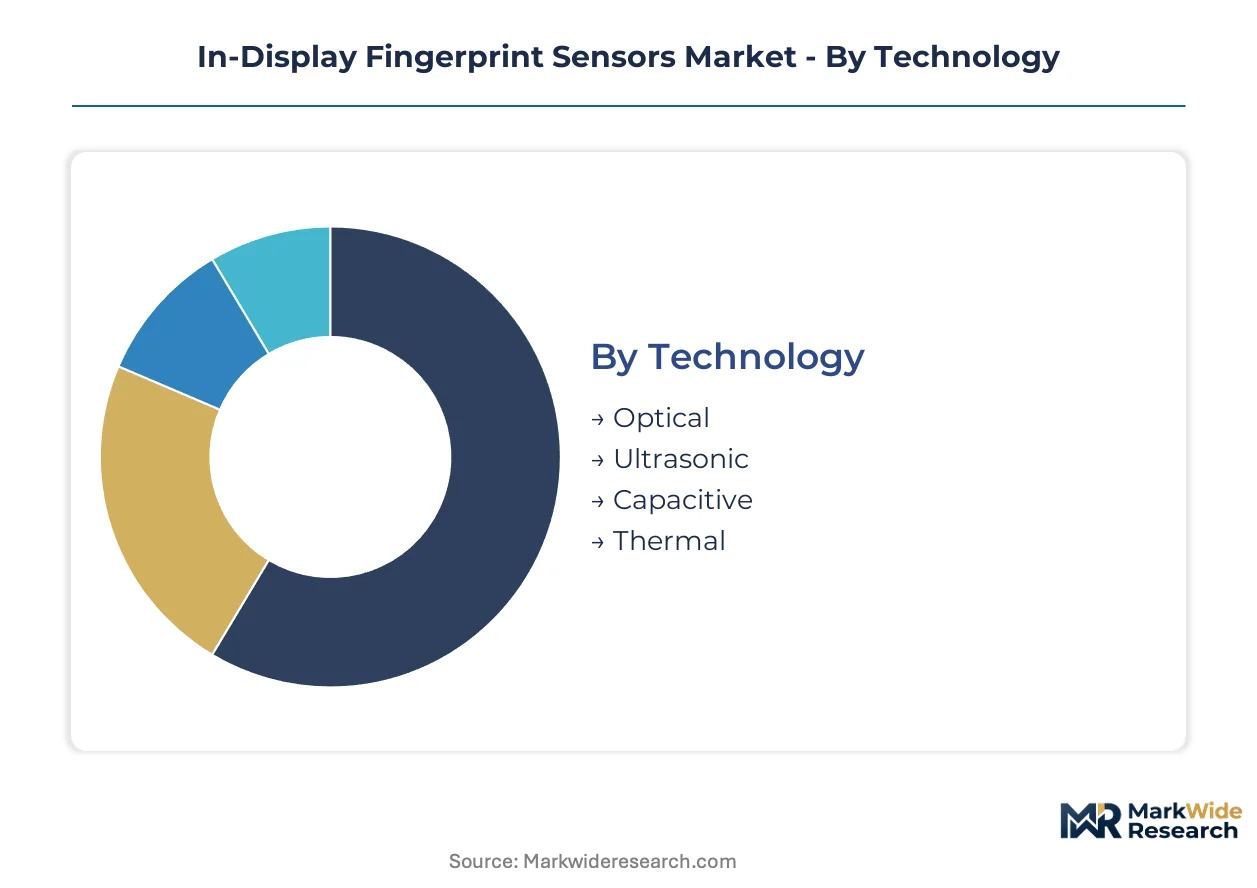
Technology choice determines manufacturing location and export eligibility for in-display fingerprint sensors. Module suppliers align production with regional certification requirements and panel-integrator proximity.
Technology:
Optical and ultrasonic variants dominate export flows to premium handset OEMs, while capacitive and thermal segments serve cost-sensitive domestic markets with lighter regulatory burdens.
- Optical:CMOS image sensor arrays capture ridge patterns through OLED or LCD panels using visible or near-infrared illumination. Shenzhen and Seoul manufacturing clusters concentrate procurement for mid-range smartphone portfolios, driven by mature supply chains and MIIT-compliant encryption module availability.
- Ultrasonic:Piezoelectric transducers emit acoustic pulses to map fingerprint topography through thicker cover glass. Qualcomm's 3D Sonic platform anchors demand in devices targeting EU and North American distribution, where moisture tolerance and live-finger detection justify premium module costs.
- Capacitive:Field-detection arrays measure electrical conductivity differences between ridges and valleys; legacy deployments persist in cost-optimized tablets and entry-level wearables.
- Thermal:Temperature differential sensors detect ridge patterns through heat conductivity mapping; niche applications in specialized government access control hardware.
Optical holds the largest share; momentum sits with ultrasonic as flagship OEMs prioritize wet-finger performance.
Application:
Volume concentration varies sharply by device category, with smartphones absorbing module fabrication capacity while laptop integration creates new demand pockets.
- Smartphones:Active-matrix OLED panels in flagship and mid-tier handsets embed biometric arrays beneath cover glass up to millimeter thicknesses. China's MIIT encryption mandates and EU GDPR consent frameworks filter vendor eligibility for devices sold across multiple jurisdictions.
- Laptops:Windows Hello-compatible enterprise notebooks drive thin-film optical adoption as IT departments mandate FIDO2-compliant authentication hardware. North American and Western European refresh cycles concentrate procurement through direct OEM relationships rather than component distributors.
- Tablets:Larger display areas enable multiple fingerprint enrollment for shared enterprise devices; education and healthcare verticals dominate procurement.
- Wearables:Miniaturized sensor footprints and power constraints limit biometric integration to premium smartwatch tiers with dedicated security processors.
Smartphone modules generate dominant volume; laptop integration is climbing the fastest as enterprise security specifications harden.
End User:
Procurement authority fragments across buyer types, with enterprise and government segments imposing certification requirements that consumer markets bypass.
- Consumers:Individual handset purchasers prioritize unlock speed and industrial design seamlessness over clinical accuracy documentation; price sensitivity concentrates demand in optical module tiers.
- Enterprises:IT departments mandate FIDO2 and Windows Hello compatibility, filtering vendor pools to suppliers with pre-certified biometric stacks. Deployment scale justifies custom sensor geometries from Shenzhen panel-integrator ecosystems.
- Government:National security applications require documented false-accept and false-reject rates; procurement runs through specialized contractors with classified facility clearances.
- Retail:Point-of-sale biometric authentication for payment verification drives demand in markets with central bank digital currency pilots.
Consumer volume leads; enterprise specifications are tightening fastest as zero-trust security architectures spread.
Deployment:
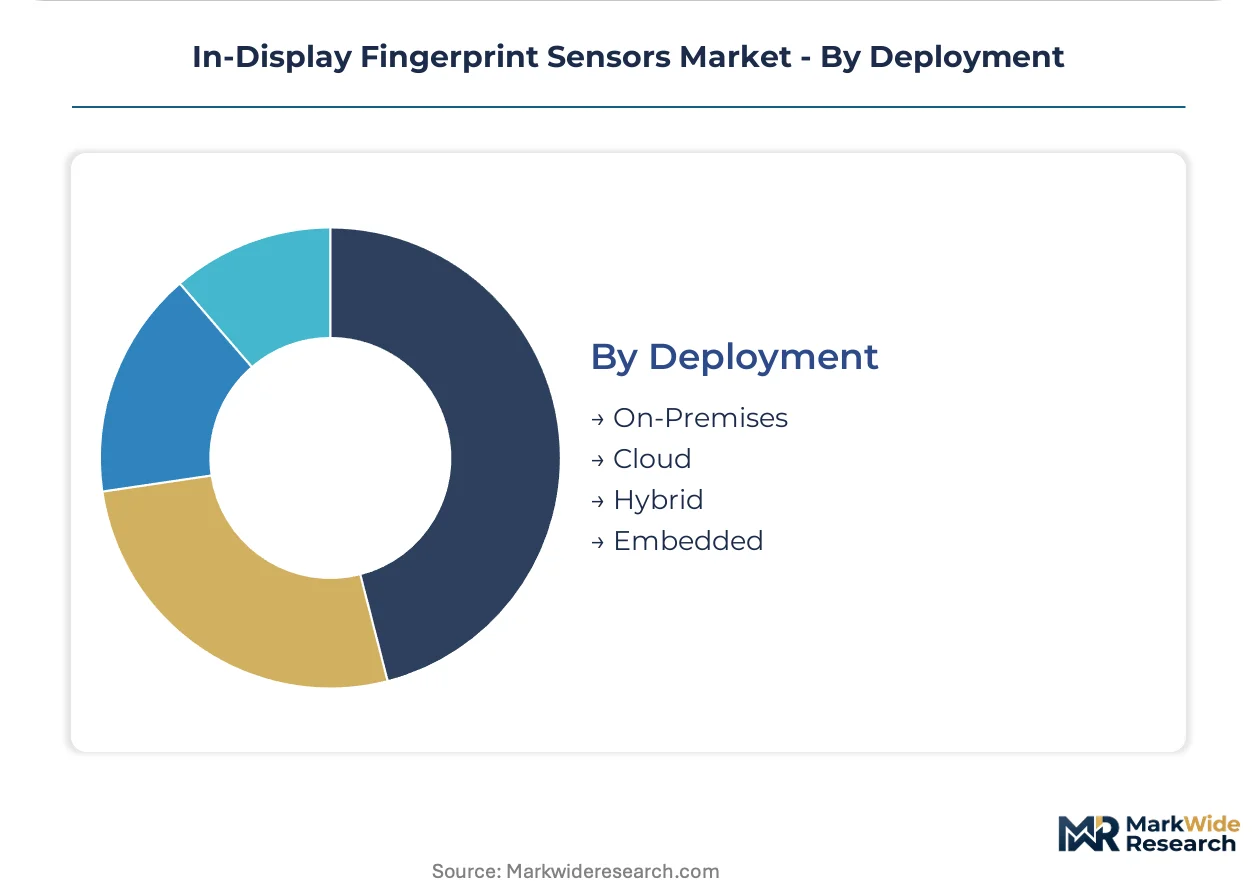
Architecture choice determines data sovereignty compliance and biometric template storage location, with regulatory fragmentation forcing modular platform designs.
- On-Premises:Biometric templates remain within device secure enclaves, satisfying China's data localization requirements and EU GDPR storage limitation principles. Embedded ASICs handle matching without cloud transmission.
- Cloud:Template storage and matching occur on remote servers, enabling cross-device authentication continuity. Deployment concentrates in markets with lighter data sovereignty constraints.
- Hybrid:Enrollment occurs on-device with encrypted template backup to regional cloud instances; architecture balances convenience against compliance for multi-jurisdiction handset portfolios.
- Embedded:Standalone biometric modules operate without network connectivity; government and critical infrastructure applications dominate procurement.
On-premises deployment commands the dominant share; hybrid architectures are gaining share fastest as OEMs seek cross-market platform reuse.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the regulatory framework that shapes procurement patterns across the dominant manufacturing geography. Shenzhen panel-integrator ecosystems compress module assembly lead times while Seoul fabrication clusters advance ultrasonic transducer packaging.
China
Domestic handset OEMs drive optical module procurement for mid-range portfolios under GB standards enforcement. MIIT biometric encryption mandates force device upgrades, creating replacement demand across tier-one and tier-two manufacturers. Shenzhen manufacturing density enables rapid prototyping for custom sensor geometries serving both domestic and export markets.
South Korea
Seoul-based display panel manufacturers integrate biometric arrays beneath active-matrix OLED substrates for flagship device portfolios. The country's national technology regulator enforces electromagnetic compatibility certification for 5G handsets embedding sensor controllers. Busan-Ulsan industrial corridors concentrate piezoelectric transducer packaging capacity for ultrasonic module exports.
United States
Enterprise IT departments mandate Windows Hello-compatible biometric hardware for laptop refresh cycles, concentrating demand in thin-film optical architectures. FCC emissions regulations add certification layers for multi-band 5G handsets embedding sensor controllers. California-based semiconductor design houses supply ASICs for module controller integration.
Germany
Automotive OEMs pilot under-display biometric authentication for shared mobility fleet access, extending sensor applications beyond consumer electronics. BSI technical standards for biometric system security filter vendor eligibility for devices targeting federal procurement. Bavaria's industrial automation clusters prototype manufacturing quality systems for medical-grade accuracy requirements.
Japan
Precision equipment manufacturers supply lithography and deposition systems for CMOS image sensor fabrication serving optical module production. METI industrial standards govern biometric data handling for financial services applications. Kyushu semiconductor fabrication parks anchor die-level integration capacity for sensor controller ASICs.
In-Display Fingerprint Sensors Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the in-display fingerprint sensors market. The vendor base separates into three tiers: captive ASIC designers controlling die-level integration costs, premium ultrasonic specialists commanding flagship device slots, and thin-film optical fabricators serving mid-range volume. Two competitive moves dominate strategic positioning: backward integration into transducer or image sensor fabrication, and geographic expansion through Shenzhen panel-integrator partnerships.
Within the captive semiconductor design tier, Shenzhen Goodix Technology exemplifies cost-control through in-house ASIC development. Qualcomm Technologies anchors premium-tier positioning through its platform approach to ultrasonic modules. Synaptics Incorporated occupies a position specializing in thin-film optical architectures for mid-range handset portfolios.
| Leading Market Players |
|---|
| Synaptics Incorporated |
| Apple |
| Shenzhen Goodix Technology |
| CrucialTec |
| Novatek Microelectronics |
| Fingerprint Cards |
| Egis Technology |
| NEXT Biometrics |
| Qualcomm Technologies |
| Others |
Value Chain & Pricing Dynamics
Ultrasonic module displacement of optical arrays in premium handsets simultaneously redistributes manufacturing gravity toward Seoul piezoelectric packaging corridors and compresses margin pools for Shenzhen CMOS image sensor suppliers. This substitution dynamic concentrates pricing power among vendors with captive transducer fabrication while eroding commodity premiums for thin-film optical architectures.
Pricing Analysis
Price spreads between Shenzhen-assembled optical modules and Seoul-fabricated ultrasonic units exceed three-to-one, reflecting die-level integration cost structures and EU MDR certification overhead. Pricing stratifies across premium ultrasonic tiers for flagship OEMs, standard optical configurations for mid-range handsets, and economy capacitive residuals for entry tablets. Cost compression in optical tiers intensifies because panel-integrator ecosystems in Shenzhen compress assembly margins through vertical integration. Enterprise IT departments purchasing Windows Hello-compatible laptop modules exhibit lowest price sensitivity; domestic Chinese handset OEMs face acute pressure from MIIT-mandated encryption module upgrades.
Supply Chain Analysis
Strait of Malacca transit underwrites lithography equipment delivery schedules for CMOS image sensor foundries serving optical module production. Module assembly concentrates in China, South Korea, and Taiwan, drawing from piezoelectric ceramic substrates, CMOS wafers, and cover glass tempering systems. Single-source vulnerability sits with Qualcomm's 3D Sonic transducer architecture for premium ultrasonic shipments. Distribution runs through direct OEM procurement channels rather than component distributors for high-volume smartphone and enterprise notebook contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facial recognition authentication in Apple and Android flagships threatens to bypass fingerprint sensors entirely, forcing incumbents to defend biometric modality relevance through performance differentiation and regulatory pre-certification.
For Market Incumbents: Consolidate ASIC design capabilities in Shenzhen or Seoul to control die-level integration costs against Synaptics and Goodix price competition. Deepen ultrasonic module pre-certification to EU MDR clinical accuracy thresholds before product launch, converting GDPR compliance documentation into competitive moats against optical-only rivals.
For New Entrants and Emerging Players: Enterprise laptop biometric integration under-serves mid-tier OEMs lacking Windows Hello engineering partnerships, creating white-space for FIDO2-compliant thin-film optical specialists. Target North American IT refresh cycles through direct OEM relationships bypassing distributor markups, with initial beachhead in education-sector Chromebook deployments.
For Investors and Strategic Acquirers: EU AI Act biometric governance reshapes the acquisition landscape toward vendors with established GDPR documentation and medical-grade accuracy certifications. Long-term viability favors captive semiconductor design houses controlling upstream transducer or image sensor fabrication. Watch MIIT enforcement patterns for biometric data localization as inflection signal for domestic Chinese vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Design Capability Acquisition | Captive die-level integration controls module cost structures against Shenzhen competitors. |
| EU MDR Pre-Certification Investment | Clinical accuracy documentation unlocks premium handset slots in GDPR-regulated markets. |
| Panel-Integrator Partnership Expansion | Shenzhen ecosystem access compresses prototyping lead times for custom sensor geometries. |
| Ultrasonic Transducer Fabrication Scale-Up | Piezoelectric packaging capacity anchors moisture-tolerant positioning in flagship tiers. |
| Windows Hello Compatibility Engineering | FIDO2 stack certification opens enterprise notebook procurement through direct OEM channels. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC semiconductor filings, MIIT device certification databases, and EU MDR technical documentation. Semiconductor packaging engineers, smartphone OEM procurement directors, panel-integrator supply chain managers, and enterprise IT hardware specifiers provided operational perspective. Bottom-up module shipment estimates triangulate against top-down display panel production forecasts across the analysis window.
Segmentation dimensions modeled include technology type, device application, end-user procurement authority, and deployment architecture across the projection horizon. CAGRs derive from installed base replacement cycles, OLED panel adoption curves, and regulatory mandate compliance deadlines. Forecast inputs incorporate MIIT encryption upgrade timelines and Windows Hello enterprise penetration assumptions.
Forecasts assume regulatory continuity in China's MIIT GB standards enforcement and EU GDPR/MDR certification frameworks; material policy shifts would require re-modeling. Biometric data localization mandates, facial recognition substitution rates, and 5G electromagnetic certification timeline risks could revise trajectory. Practitioners should keep alternative scenarios live as EU AI Act biometric governance rules and panel-integrator consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Microsensor Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Flow Sensor Market
Sensors and Controls
Occupancy Sensor Market
Sensors and Controls
Bee Hive Monitoring Sensor Market
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
Specialty Control Plasma Market
Sensors and Controls
Portable Air Purifier Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
Cryogenic Temperature Controller Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
Global Biosensors Market