
 Magnetic Proximity Sensor Market | 2026-2036
Magnetic Proximity Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Proximity Sensor Market Outlook
IP67 ingress protection rating is collapsing the gap between standard industrial sensors and harsh-environment applications. Honeywell International Inc. leverages its aerospace heritage to anchor premium positioning in mil-spec proximity sensing. Infineon Technologies AG sustains R&D intensity around integrated magnetic-field measurement ICs. STMicroelectronics dominates consumer electronics miniaturization with wafer-level chip-scale packaging.
A magnetic proximity sensor detects ferromagnetic objects through Hall Effect voltage variation or reed switch closure without physical contact, typically operating at supply voltages between 3.3 V and 30 V DC with switching frequencies up to 5 kHz. Its primary industrial purpose is non-contact position verification in automated machinery where mechanical wear would degrade reliability. Hall Effect Sensors capture the largest volume pool due to semiconductor scalability and programmable switching thresholds. Reed Sensors retain niche dominance in explosion-proof environments where galvanic isolation matters. Industrial Automation end users concentrate margin pools through long-term frame contracts for predictive maintenance integration.
FCC Part 15 electromagnetic emission limits shape product design for US-bound magnetic proximity sensors, while CE marking under the EU Machinery Directive governs European market access with specific requirements for functional safety in automated systems. China's GB standards administered by SAMR enforce electromagnetic compatibility testing protocols for industrial sensor imports. Stakeholders must monitor divergence between IEC 60947-5-2 editions and national adoptions when configuring global product platforms.
Market Dynamics
IP67-rated Hall Effect sensors are displacing reed switch architectures across Germany's automotive automation sector as OEMs consolidate sensor procurement under predictive maintenance frame contracts.
Growth Catalysts
- Industrial Automation:Germany's automotive sector accelerates procurement of IP67-rated Hall Effect sensors for robotic welding and assembly line position verification.
- IEC 60947-5-2:Tightening proximity switch certification requirements worldwide force sensor vendors to upgrade electromagnetic compatibility testing protocols.
- Precision Manufacturing Clusters:Japan's Nagoya and Osaka industrial corridors concentrate demand for sub-millimeter accuracy magnetic position sensing in semiconductor fabrication equipment.
Market Restraints
- Rare Earth Magnet Supply:Neodymium price volatility and China's export licensing regime for processed rare earth concentrates create input cost instability for Hall Effect sensor manufacturers.
- Semiconductor Foundry Concentration:Taiwan-based 200mm wafer capacity shortages limit integrated magnetic-field measurement IC production scaling.
- Optical Encoder Substitution:Photoelectric position sensors achieve comparable accuracy at lower per-unit cost in clean-environment applications, eroding magnetic sensor volume in material handling.
Strategic Opportunities
- India Manufacturing:PLI scheme incentives for industrial automation equipment create underpenetrated demand for cost-optimized magnetic proximity sensors in Pune and Chennai automotive clusters.
- Functional Safety Integration:EU Machinery Directive SIL 2/3 certification requirements open premium positioning for redundant magnetic sensor architectures in collaborative robotics.
- Wireless-Enabled Sensors:Convergence of Hall Effect measurement with Bluetooth Low Energy and IO-Link protocols enables cable-free installation in modular production lines.
Industry Challenges
- Embedded Firmware Talent:Scarcity of engineers combining magnetic physics expertise with real-time signal processing slows programmable switching threshold development cycles.
- Multi-Standard Certification:Divergence between IEC 60947-5-2 editions and China's GB/T 14048.10 national adoptions forces parallel testing tracks, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Proximity Sensor Market |
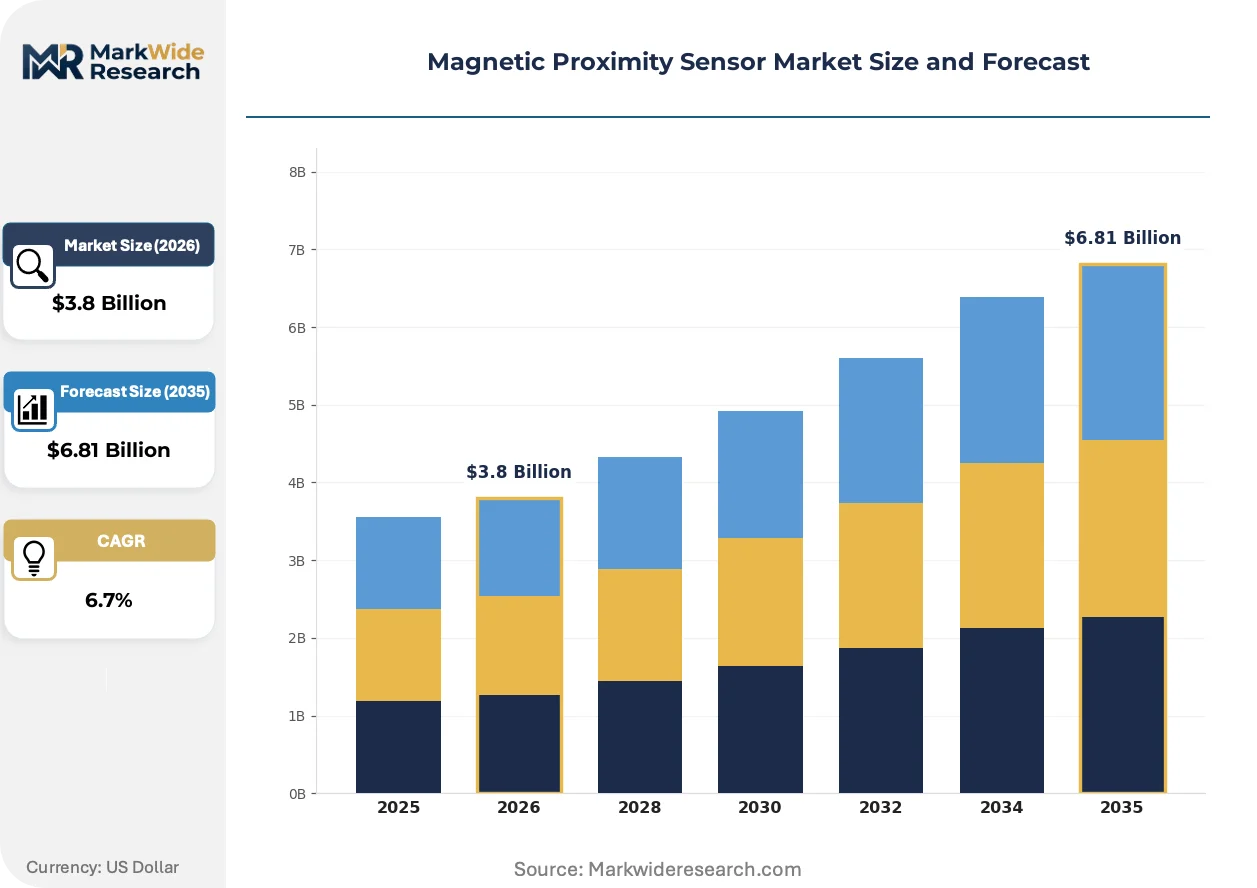
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reed Sensors, Hall Effect Sensors, Magnetic Switches, Other Sensors End User: Automotive, Industrial Automation, Consumer Electronics, Aerospace Installation Type: Surface Mounted, Flush Mounted, Embedded, Cabinet Mounted Application: Position Detection, Proximity Sensing, Security Systems, Automation |
| Companies Covered | Honeywell International Inc., Infineon Technologies AG, STMicroelectronics, NXP Semiconductors, TDK Corporation, TE Connectivity, Omron Corporation, Panasonic Corporation, SICK AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Proximity Sensor Market Strategic Shifts
Wafer-level chip-scale packaging and integrated magnetic-field measurement architectures are compressing sensor form factors while expanding addressable applications beyond traditional industrial boundaries.
Silicon-based Hall Effect arrays with programmable sensitivity is fragmenting the historical trade-off between precision and cost in magnetic proximity detection. Semiconductor vendors now embed temperature compensation and self-diagnostic routines directly onto sensing dies. Medical device manufacturers and consumer robotics startups adopt these integrated solutions faster than established industrial automation buyers, creating two-speed adoption curves within the same technology generation.
China's GB standards administered by SAMR enforce electromagnetic compatibility testing protocols that exceed baseline IEC requirements for industrial sensor imports. SAMR's 2024 technical revisions mandate additional surge immunity and radiated emission testing for sensors deployed in smart grid infrastructure. European sensor vendors with existing CE marking under the EU Machinery Directive must duplicate certification efforts, compressing margin on China-bound product lines.
Automotive Tier 1 suppliers unbundle after-sales calibration services from hardware procurement, converting magnetic sensor relationships from component supply to lifecycle data contracts. BMW and Volkswagen now specify sensor platforms with cloud-connected health monitoring as standard in new production line RFPs. This service-layer pivot is most visible in Germany's Baden-Württemberg and Bavaria automotive engineering clusters, where predictive maintenance integration determines vendor selection criteria.
Magnetic Proximity Sensor Market Segmentation
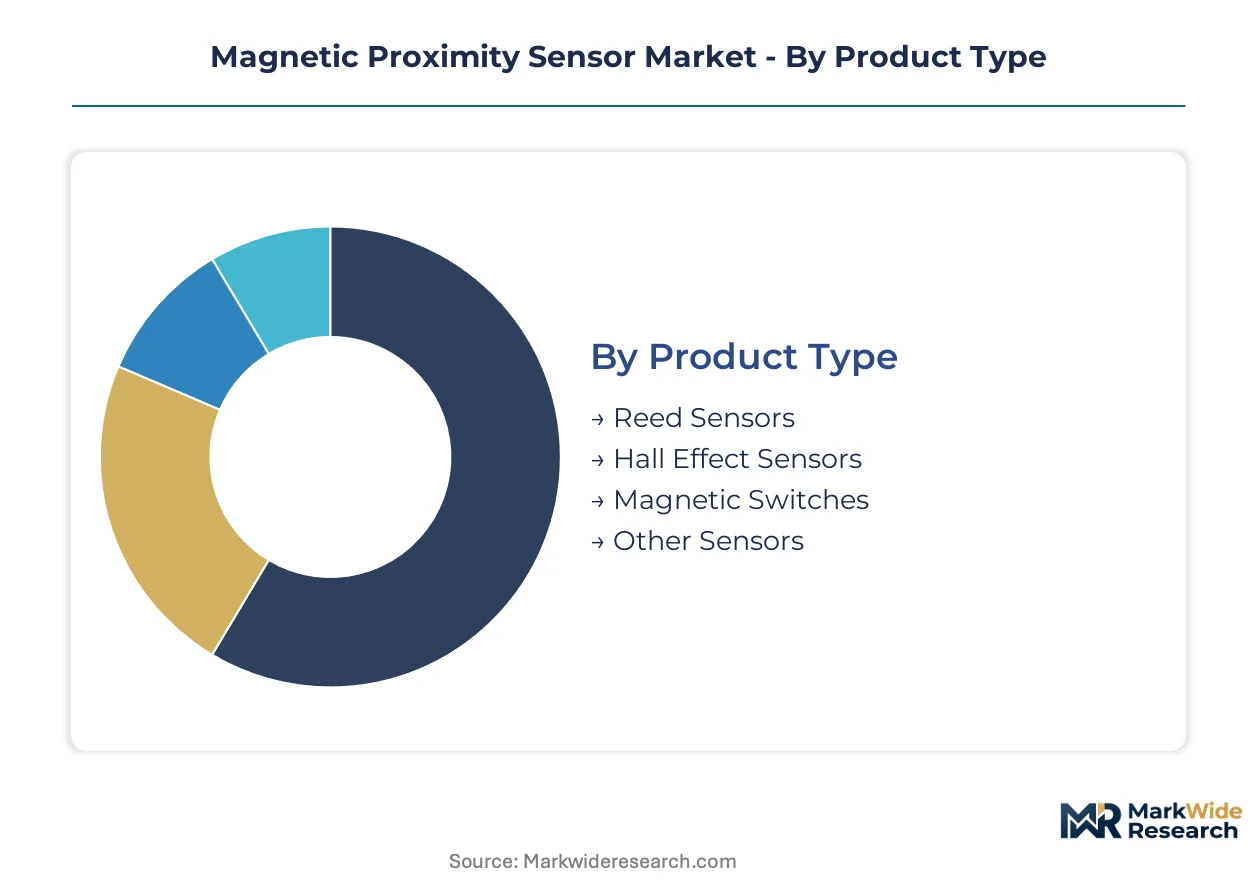
Magnetic proximity sensor procurement patterns diverge sharply across product architectures and installation environments. Substitution pressures from optical encoders and capacitive alternatives reshape competitive dynamics within each segment cluster.
Product Type:
Optical encoder substitution threatens reed switch architectures most severely in clean-environment material handling, while Hall Effect platforms defend position through semiconductor scalability.
- Hall Effect Sensors:Semiconductor-based magnetic-field measurement ICs operate at 3.3 V to 30 V DC with programmable switching thresholds up to 5 kHz. Germany's automotive automation sector concentrates procurement of IP67-rated variants for robotic welding position verification under predictive maintenance frame contracts.
- Reed Sensors:Magnetically-actuated hermetic switches provide galvanic isolation without external power amplification. Explosion-proof certification requirements in hazardous chemical processing sustain niche demand despite displacement pressure from solid-state alternatives.
- Magnetic Switches:Simplified electromechanical designs target cost-sensitive position detection in basic automation equipment.
- Other Sensors:Emerging magnetoresistive and anisotropic magnetoresistance technologies address sub-millimeter accuracy requirements in precision manufacturing clusters.
Hall Effect Sensors anchor the volume base while Other Sensors gain share at the steepest rate.
End User:
Margin concentration follows predictive maintenance integration intensity, with automotive Tier 1 suppliers unbundling after-sales calibration from hardware procurement.
- Industrial Automation:Non-contact position verification in automated machinery drives the largest procurement volumes. Japan's Nagoya and Osaka semiconductor fabrication equipment manufacturers specify sub-millimeter accuracy magnetic position sensing for wafer handling robotics.
- Automotive:BMW and Volkswagen specify cloud-connected sensor health monitoring as standard in new production line RFPs. Germany's Baden-Württemberg and Bavaria engineering clusters determine vendor selection through predictive maintenance integration capabilities.
- Consumer Electronics:Wafer-level chip-scale packaging from STMicroelectronics enables miniaturization in wearable devices and smartphones.
- Aerospace:Mil-spec proximity sensing requirements leverage Honeywell's aerospace heritage for premium positioning in altitude and landing gear applications.
Industrial Automation captures the deepest margin pools while Automotive expands most quickly through service-layer contract conversion.
Installation Type:
Physical integration constraints separate premium positioning from commodity replacement demand based on environmental sealing requirements.
- Flush Mounted:Recessed installation behind metallic or non-metallic surfaces protects sensing elements from mechanical damage. IP67 ingress protection ratings collapse the gap between standard industrial sensors and harsh-environment applications in outdoor automation infrastructure.
- Surface Mounted:External attachment enables rapid retrofit in legacy equipment without structural modification. Material handling conveyor systems in India's Pune and Chennai automotive clusters favor this approach for cost-optimized deployment.
- Embedded:Integration within machinery structural elements requires upfront design collaboration. Collaborative robotics manufacturers specify redundant magnetic sensor architectures for EU Machinery Directive SIL 2/3 functional safety certification.
- Cabinet Mounted:Enclosed installation in electrical control panels addresses switching applications with minimal environmental exposure.
Flush Mounted dominates specification intensity while Embedded climbs the fastest through collaborative robotics safety integration.
Application:
Wireless protocol convergence reshapes installation economics across detection use cases, with Bluetooth Low Energy and IO-Link enabling cable-free modular production lines.
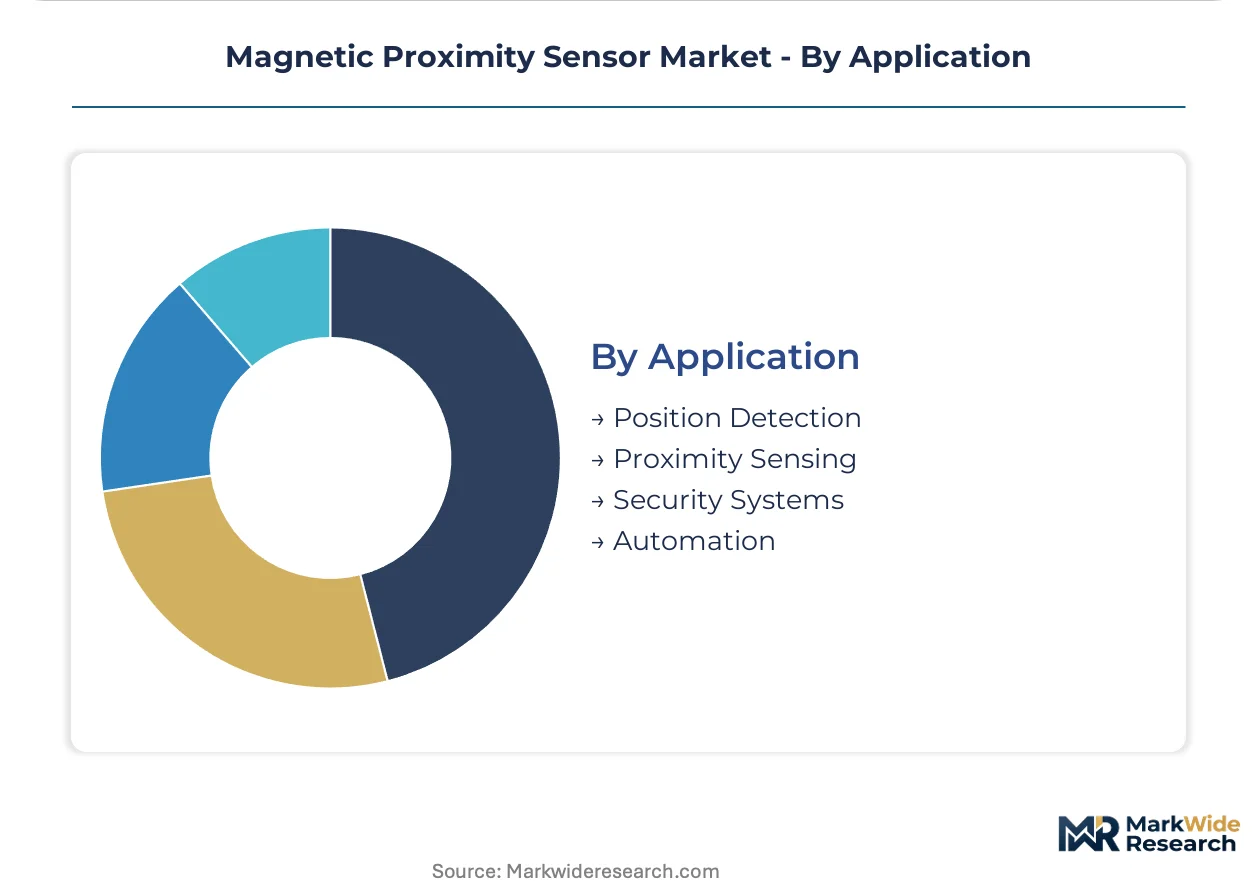
- Position Detection:Absolute and incremental position verification in linear and rotary motion systems. Germany's automotive sector accelerates procurement for assembly line tooling alignment under long-term frame contracts.
- Proximity Sensing:Ferromagnetic object detection without physical contact prevents mechanical wear degradation. Smart grid infrastructure deployments in China face additional SAMR-mandated surge immunity and radiated emission testing beyond baseline IEC requirements.
- Security Systems:Door and window position monitoring in access control applications favors reed switch galvanic isolation.
- Automation:General-purpose presence detection in programmable logic controller networks.
Position Detection retains the largest installed base while Proximity Sensing shows the steepest expansion trajectory through wireless-enabled sensor convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor foundry capacity in Taiwan constrains integrated magnetic-field measurement IC production scaling worldwide. Rare earth magnet supply chains concentrate in China's processing facilities, creating input cost instability for Hall Effect sensor manufacturers across all demand centers. Regulatory divergence between IEC 60947-5-2 editions and national adoptions forces parallel certification tracks in major economies.
Germany
Automotive automation accelerates IP67-rated Hall Effect sensor procurement for robotic welding position verification. KBA vehicle safety standards and EU Machinery Directive CE marking requirements govern functional safety certification. Baden-Württemberg and Bavaria engineering clusters unbundle after-sales calibration from hardware procurement under predictive maintenance frame contracts.
China
Smart grid infrastructure deployments drive additional SAMR-mandated surge immunity and radiated emission testing beyond baseline IEC requirements. GB/T 14048.10 magnetic sensor specifications administered by SAMR enforce electromagnetic compatibility protocols for industrial imports. Yangtze River Delta manufacturing bases concentrate rare earth magnet processing capacity for Hall Effect sensor input materials.
Japan
Precision manufacturing corridors around Nagoya and Osaka specify sub-millimeter accuracy magnetic position sensing for semiconductor fabrication equipment. METI industrial standards and JIS certification requirements shape domestic procurement specifications. Chubu region automotive and electronics clusters sustain demand for integrated magnetic-field measurement architectures.
United States
FCC Part 15 electromagnetic emission limits constrain product design for industrial sensor platforms bound for North American deployment. OSHA workplace safety regulations intersect with predictive maintenance integration requirements in automotive manufacturing. Michigan and Ohio automotive engineering centers specify cloud-connected sensor health monitoring in production line RFPs.
India
PLI scheme incentives for industrial automation equipment create underpenetrated demand in Pune and Chennai automotive clusters. BIS certification requirements and DGFT import regulations shape sensor procurement compliance frameworks. Tamil Nadu and Maharashtra manufacturing corridors favor surface-mounted installation for cost-optimized retrofit deployment in legacy material handling systems.
Magnetic Proximity Sensor Market Competitive Environment
Concentration sits with diversified semiconductor conglomerates and specialized industrial automation vendors. The vendor base spans three tiers: integrated device manufacturers with captive foundry access, fabless semiconductor designers licensing magnetic sensing IP, and pure-play sensor specialists focused on application-specific packaging. Strategic moves center on functional safety certification stacking and wireless protocol integration partnerships.
Among diversified electronics conglomerates, Honeywell International Inc., Infineon Technologies AG, and STMicroelectronics occupy positions across multiple competitive vectors. Honeywell exemplifies the aerospace-heritage premium positioning archetype. Infineon represents integrated magnetic-field measurement IC specialization. STMicroelectronics anchors consumer electronics miniaturization through wafer-level chip-scale packaging capabilities.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Infineon Technologies AG |
| STMicroelectronics |
| NXP Semiconductors |
| TDK Corporation |
| TE Connectivity |
| Omron Corporation |
| Panasonic Corporation |
| SICK AG |
| Others |
Value Chain & Pricing Dynamics
Reed switch displacement by solid-state Hall Effect architectures simultaneously concentrates semiconductor foundry dependency in Taiwan and compresses pricing premiums for galvanic isolation. This substitution dynamic reroutes procurement toward 200mm wafer capacity while eroding the cost justification for hermetic switch designs in non-hazardous environments.
Pricing Analysis
IEC 60947-5-2 certification tiers dictate the pricing stratification across premium SIL 2/3 redundant architectures, standard IP67-rated industrial variants, and economy-grade surface-mounted units. Price differentiation rests on functional safety grade and predictive maintenance software bundling, with automotive Tier 1 suppliers in Baden-Württemberg extracting steepest discounts through long-term frame contracts. Cost compression in economy tiers intensifies because India's PLI scheme attracts low-cost entrants. Small-scale material handling integrators in Pune exhibit highest price sensitivity; aerospace mil-spec buyers at Honeywell's tier show least.
Supply Chain Analysis
Taiwan Strait transit underwrites semiconductor wafer availability for integrated magnetic-field measurement ICs. Manufacturing concentrates in Taiwan, Germany, and China. Raw material flows draw from Yangtze River Delta rare earth processing for neodymium magnets, 200mm silicon wafers from Taiwan Semiconductor, and epoxy molding compounds from Japan. Single-source vulnerability concentrates in Taiwan-based foundry capacity. Distribution runs through automotive Tier 1 direct procurement, industrial automation distributors, and electronics component brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM consolidation under predictive maintenance frame contracts has shifted bargaining power toward buyers, compressing vendor margins and forcing service-layer pivots.
For Market Incumbents: Fortify Hall Effect sensor platforms with embedded Bluetooth Low Energy and IO-Link protocol stacks to defend against optical encoder substitution in clean-environment material handling. Deepen backward integration into Taiwan foundry partnerships or captive 200mm capacity investments to offset semiconductor supply concentration. Prioritize SAMR pre-certification for China's GB/T 14048.10 surge immunity mandates ahead of competitors. For New Entrants and Emerging Players: Differentiate on wireless-enabled sensor form factors targeting India's Pune and Chennai automotive clusters where surface-mounted retrofit demand outpaces embedded design cycles. White-space sits in cost-optimized IP54 variants for legacy conveyor upgrades. Penetrate through direct engagement with Tamil Nadu material handling integrators bypassing established distributor markups. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors fabless semiconductor designers with magnetic sensing IP and wireless protocol integration capabilities. Long-term viability hinges on functional safety certification stacking and cloud-connected health monitoring service contracts. Acquisition targets should exhibit SIL 2/3 pipeline progress and established Tier 1 automotive qualification. Watch for inflection when Taiwan 200mm capacity expansion announcements accelerate or stall.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Stacking | SIL 2/3 redundant architectures unlock EU Machinery Directive premium positioning in collaborative robotics. |
| Wireless Protocol Integration Partnership | Bluetooth Low Energy and IO-Link convergence enables cable-free modular production line installations. |
| Backward Integration into Foundry Capacity | Taiwan 200mm wafer access secures integrated magnetic-field measurement IC supply against allocation risk. |
| Predictive Maintenance Service Unbundling | Cloud-connected health monitoring converts hardware procurement into lifecycle data contracts with BMW and Volkswagen. |
| SAMR Pre-Certification Investment | GB/T 14048.10 surge immunity readiness compresses competitor launch timelines for China-bound product lines. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with semiconductor product managers, automotive Tier 1 procurement directors, industrial automation plant engineers, and magnetic sensor R&D leads. Secondary validation drew from IEC 60947-5-2 standard revision documentation, SAMR technical bulletins, Taiwan Semiconductor capacity disclosures, and EU Machinery Directive implementation guidance. Bottom-up segment sizing triangulated against top-down macroeconomic demand modeling.
Across the projection horizon, the analytical framework modeled volume and value outputs through product architecture segmentation, end-user industry clustering, installation environment categorization, and regional regulatory adoption patterns. CAGRs derived from historical shipment correlations with industrial automation capital expenditure cycles and semiconductor foundry utilization rates. Forecast inputs incorporated rare earth magnet price volatility indices and automotive production line automation intensity metrics.
The analysis sits within stated boundaries; outcomes outside sustained Taiwan foundry capacity expansion or stable neodymium supply from Yangtze River Delta processing would require recalibration. Practitioners should keep alternative scenarios live as IEC 60947-5-2 edition divergence and SAMR technical revision timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Taiwan Sensors Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
US Distributed Acoustic Sensing Market
Sensors and Controls
Digital Automation Temperature Regulator Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
Global Biosensors Market
Sensors and Controls
Capacitive Proximity Sensor Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Global Level Sensors Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
Tunnel Sensor Market