
 Bioactive Coating Devices Market | 2026-2036
Bioactive Coating Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Bioactive Coating Devices Market Intelligence
The bundling of proprietary bioactive coatings with specific medical implants as integrated systems is expanding the accessible market for device manufacturers. SurModics Inc. specializes in surface modification technologies, including drug-delivery coatings for vascular devices. DSM Biomedical leverages its biomaterial science expertise to create solutions that improve implant biocompatibility. Meanwhile, Biocoat Inc. focuses on developing and licensing hydrophilic coatings for a range of medical devices, enhancing lubricity and performance.
Bioactive coating devices are medical products featuring a surface layer engineered to interact with biological systems. These coatings incorporate agents like drugs, proteins, or enzymes to elicit a specific physiological response, such as preventing microbial colonization or promoting tissue integration. Cardiovascular and orthopedic applications represent the largest demand segments, driven by the need to improve the performance and longevity of implants. While dip coating remains a foundational technology, plasma spray and sol-gel methods are gaining adoption for their ability to create more durable and functional surfaces.
Regulatory frameworks from the US FDA and the European Union under the Medical Device Regulation (MDR) impose strict requirements for demonstrating the safety and efficacy of combination products. Compliance with ISO 10993 standards for biocompatibility is a critical prerequisite for market entry in nearly all major jurisdictions. Future competitive positioning will depend on a manufacturer's ability to generate robust clinical data supporting the therapeutic claims of their coated devices.
Market Dynamics
The central tension in the bioactive coatings market is the push-pull between rapid material science innovations and the increasingly stringent regulatory oversight for combination products. This dynamic forces manufacturers to balance the development of advanced functional surfaces with the extensive clinical validation required by bodies like the FDA and under the EU MDR.
Growth Catalysts
- Favorable Regulatory Pathways:The European Union's Medical Device Regulation (MDR), while strict, provides a clear framework for high-quality combination products, creating a competitive advantage for manufacturers with robust clinical data.
- Orthopedic Implant Demand:An aging population in developed countries like Germany and Japan drives significant demand for joint replacements and spinal implants, where bioactive coatings improve osseointegration and reduce infection rates.
- Chronic Disease Prevalence:The rising incidence of cardiovascular diseases in nations such as the United States fuels continuous innovation and utilization of drug-eluting stents and other coated vascular devices to improve patient outcomes.
Market Restraints
- High Material Costs:The specialized nature of active pharmaceutical ingredients (APIs) and advanced polymers used in coatings leads to high raw material costs, which directly translates to more expensive end-products for healthcare systems.
- Stringent Clinical Evidence:Regulatory bodies including the US FDA and Swissmedic demand extensive and costly clinical trials to prove the safety and efficacy of the coating-device combination, creating a significant barrier to entry.
- Coating Adhesion and Durability:A primary technical restraint is the risk of coating delamination or degradation over the lifetime of an implant, which can lead to loss of therapeutic effect or adverse biological reactions.
Strategic Opportunities
- Antimicrobial Applications:There is a significant opportunity to develop and market antimicrobial coatings for devices outside the cardiovascular space, such as catheters, dental implants, and surgical instruments, to combat hospital-acquired infections.
- Smart Implant Integration:The convergence of bioactive coatings with micro-sensor technologies presents an opportunity to create intelligent implants that can monitor physiological conditions like inflammation or tissue healing and release therapeutic agents on demand.
- Expansion in Asia-Pacific:Markets in South Korea and Australia are investing heavily in healthcare infrastructure, creating new opportunities for advanced medical devices, including those with specialized bioactive coatings.
Industry Challenges
- Biocompatibility Certification Delays:Securing compliance with ISO 10993 standards for new coating formulations is a time-consuming and resource-intensive process that can significantly delay product launches.
- Intellectual Property Complexity:Licensing agreements for proprietary coating technologies applied to third-party medical devices often involve complex IP negotiations, creating potential for legal disputes and commercial friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioactive Coating Devices Market |
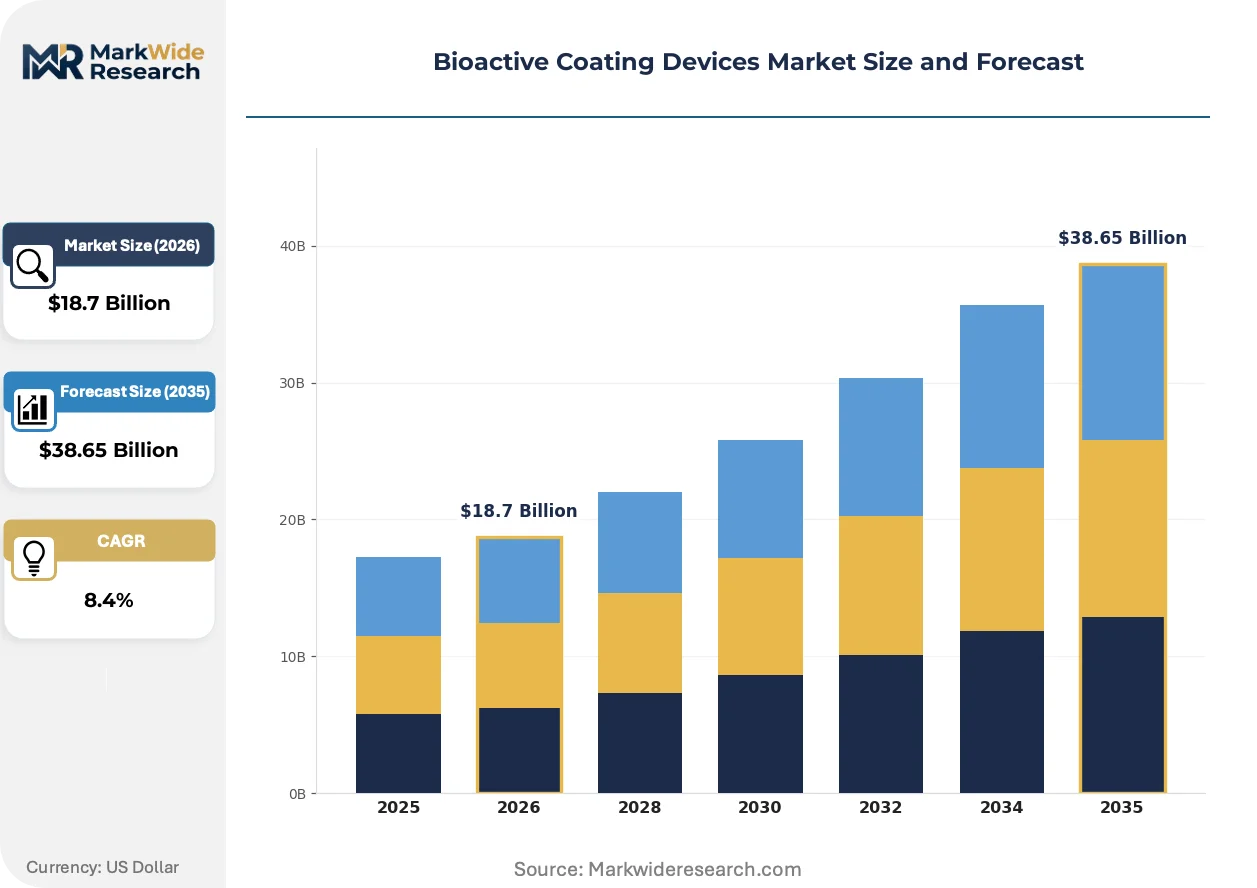
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Implants, Drug Delivery Systems, Wound Dressings End User: Hospitals, Research Laboratories, Clinics, Rehabilitation Centers Technology: Electrospinning, Sol-Gel, Plasma Spray, Dip Coating Application: Orthopedics, Cardiovascular, Dentistry, Tissue Engineering |
| Companies Covered | Biocoat Inc., Evonik Industries AG, DSM Biomedical, Formacoat, Harland Medical Systems, Hydromer Inc., AST Products Inc., Specialty Coatings Systems Inc., SurModics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioactive Coating Devices Market Strategic Shifts & Innovations
Material science and process engineering are advancing to create more intelligent surfaces that actively manage biological interactions. This evolution moves beyond passive drug elution towards coatings that can sense, respond, and promote specific cellular activities, fundamentally altering device functionality and therapeutic potential.
Advanced deposition techniques like automated plasma spray and robotic dip-coating systems ensure precise control over coating thickness and uniformity. Medical device manufacturers in high-volume segments such as cardiovascular and orthopedic implants are rapidly adopting these systems. This technology is automating critical quality control steps, reducing batch-to-batch variability and minimizing the risk of human error during the application of functional surface layers.
The European Union's Medical Device Regulation (MDR) now mandates more rigorous clinical evidence and lifecycle surveillance for combination products. This directive significantly increases the burden of proof for manufacturers, requiring deep data on the interaction between the coating, the drug, and the device. Cardiovascular device producers are most affected, now compelled to fund longer-term studies to validate the sustained safety and efficacy claims of their drug-eluting technologies.
A preference for single-source procurement of integrated implant systems is growing among hospital administrators. This behavioral shift disrupts the business model for standalone coating applicators, favoring original device manufacturers who can deliver a fully validated, pre-coated product. The trend is most prominent in the United States and Germany, where large hospital networks seek to simplify their supply chains, reduce variability, and mitigate integration risks.
Bioactive Coating Devices Market Segmentation
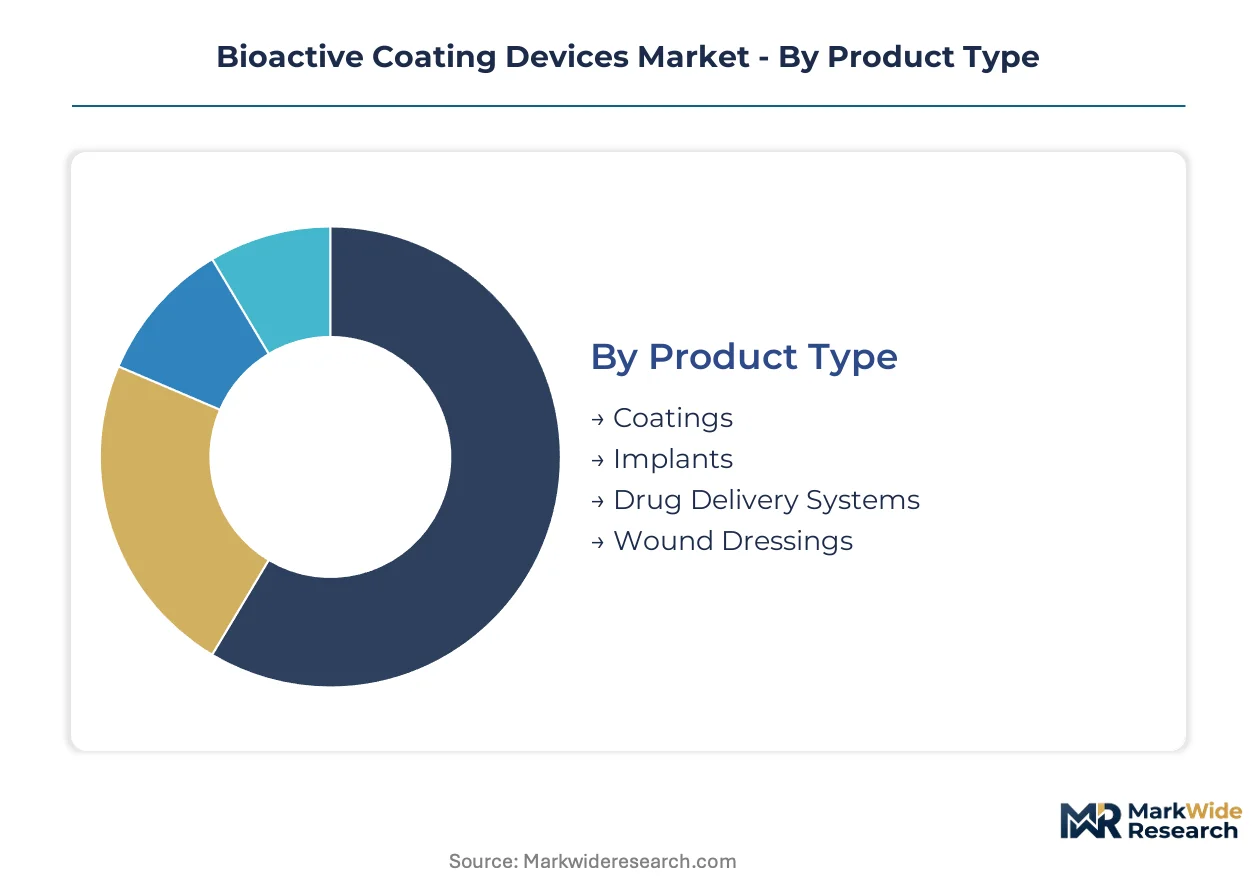
The segmentation of the bioactive coating devices market offers a granular view of distinct product requirements and end-user needs. Understanding these segments is critical for manufacturers to tailor their research and development efforts, optimize production processes, and strategically position their offerings within competitive landscapes.
Product Type:
The market's product type segmentation highlights how device upgrade cycles and replacement frequencies drive demand for specific coating solutions.
- Coatings:These are surface layers engineered to interact with biological systems, incorporating agents like drugs, proteins, or enzymes to elicit a specific physiological response. Demand is high in cardiovascular applications for drug-eluting stents and in orthopedic implants, driven by the need for improved device performance and longevity.
- Implants:Medical devices permanently or semi-permanently placed within the body, often requiring bioactive surfaces for enhanced integration, reduced infection, or specific therapeutic effects. Demand is significant in Germany and the United States for joint replacements and spinal implants, fueled by an aging population and advanced healthcare infrastructure.
- Drug Delivery Systems:These products integrate active pharmaceutical ingredients into a matrix for controlled release at a targeted physiological site.
- Wound Dressings:Bioactive wound dressings promote healing and prevent infection through incorporated antimicrobial agents or growth factors, enhancing tissue repair.
Volume placements concentrate in Implants; the faster expansion belongs to Coatings.
End User:
End user segmentation reflects the diverse clinical settings where bioactive coated devices improve patient care.
- Hospitals:Large medical institutions providing comprehensive care, utilizing a broad array of coated devices for surgery, intervention, and long-term patient management. Demand is driven by high-volume procedures in cardiovascular and orthopedic fields, especially in the United States and Germany.
- Clinics:Outpatient facilities offering specialized medical services, often employing coated devices for diagnostics, minor procedures, and follow-up care. Demand is growing in areas like dentistry and specialized vascular clinics, where minimally invasive procedures are common.
- Research Laboratories:These facilities focus on developing new bioactive coating formulations and testing their biocompatibility and efficacy before clinical application.
- Rehabilitation Centers:These centers utilize bioactive-coated devices, particularly orthopedic implants, to aid in patient recovery and functional restoration post-surgery or injury.
The steepest expansion trajectory is observed within Clinics, while Hospitals maintain the largest installed base.
Technology:
The technology segmentation illustrates the varying maturity levels and precision capabilities defining current coating application methods.
- Plasma Spray:A thermal deposition process creating durable, functional surfaces by melting and spraying powdered materials onto a substrate. Demand is increasing in orthopedic applications for creating porous surfaces that promote osseointegration, particularly for hip and knee implants.
- Sol-Gel:A chemical process that forms ceramic or glass-like coatings at low temperatures, enabling the incorporation of heat-sensitive bioactive agents. Demand is rising for drug-eluting stents and dental implants, where precise control over drug release kinetics is crucial.
- Dip Coating:This foundational method involves immersing a device into a coating solution, known for its cost-effectiveness and scalability for high-volume production.
- Electrospinning:This technique produces ultra-fine fibers and nanofiber meshes, enabling the creation of advanced tissue engineering scaffolds and drug delivery systems.
Supply concentration remains strong with Dip Coating, though Plasma Spray technology is rapidly gaining market share.
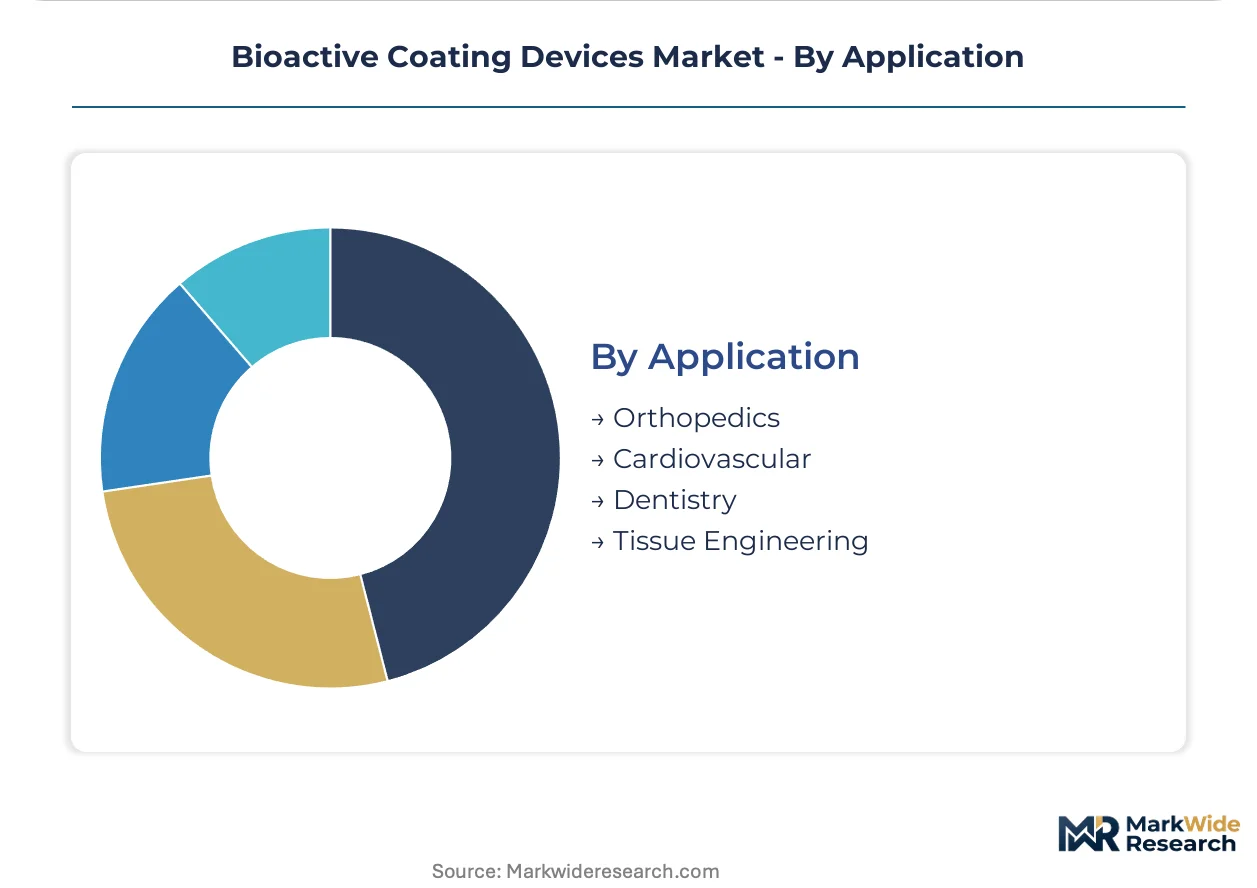
Application:
Application segmentation highlights where the highest value and most complex bioactive coating solutions are deployed.
- Cardiovascular:Involves devices like drug-eluting stents and coated guidewires designed to prevent restenosis or thrombosis in the circulatory system. Demand is significant in the United States due to high chronic disease prevalence and continuous innovation in vascular interventions.
- Orthopedics:Focuses on improving osseointegration, reducing infection, and enhancing the longevity of joint replacements and spinal implants. Demand is strong in Germany and Japan, driven by an aging population requiring joint and spinal procedures.
- Dentistry:Bioactive coatings enhance the integration of dental implants and prevent microbial colonization in various oral devices, improving long-term patient outcomes.
- Tissue Engineering:This application leverages bioactive coatings on scaffolds to promote cell growth, differentiation, and the regeneration of damaged tissues for regenerative medicine.
Revenue concentration is highest within Cardiovascular applications, while Tissue Engineering demonstrates strong growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of bioactive coating devices often concentrates in regions with advanced manufacturing capabilities, while consumption spans global healthcare markets. This creates a clear divide between where these specialized medical products are made and where they are ultimately utilized by patients. Developed medical device markets drive significant demand for these coated solutions.
United States
Demand for bioactive coating devices in the United States stems from high chronic disease prevalence, particularly cardiovascular conditions. The US FDA imposes strict regulatory requirements, necessitating extensive clinical validation for new combination products. Major medical device hubs like Minneapolis and Boston are centers for innovation in coated vascular devices.
Germany
Germany represents a significant market for bioactive coatings, driven by an aging population and high demand for orthopedic implants. The European Union's MDR framework establishes rigorous standards for product safety and efficacy. Munich and Berlin host advanced research institutions and medical technology firms developing next-generation coated implants.
Japan
Japan's aging demographic fuels substantial demand for joint replacements and spinal implants, benefiting bioactive coating applications. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees stringent approval processes for medical devices. The Kansai region, including Osaka, is a hub for biomaterials and medical device manufacturing.
South Korea
South Korea's strong investment in healthcare infrastructure and R&D activities creates a growing market for advanced medical devices. The Ministry of Food and Drug Safety (MFDS) regulates the entry of coated devices, emphasizing clinical performance. Seoul and its surrounding areas are home to numerous medical device companies and research laboratories.
Australia
Australia exhibits increasing demand for bioactive coatings due to an expanding healthcare sector and focus on improving patient outcomes. The Therapeutic Goods Administration (TGA) ensures compliance with safety and quality standards for medical products. Melbourne and Sydney feature burgeoning medical technology ecosystems supporting device innovation.
Bioactive Coating Devices Market Key Industry Players
The competitive structure tilts toward specialized technology providers and integrated medical device manufacturers. The market includes both companies developing proprietary coating formulations and those offering application services, creating a diverse ecosystem. Strategic partnerships between coating specialists and device OEMs are common, alongside portfolio diversification efforts by larger players to offer comprehensive solutions. Technology licensing agreements also shape the competitive dynamics, allowing broader market access for innovative coating solutions.
Specialists in surface modification technologies, such as SurModics Inc., exemplify the expertise required for advanced bioactive coatings, particularly for vascular devices. DSM Biomedical, leveraging its strong biomaterial science foundation, occupies a position focused on improving implant biocompatibility and functionality for a wide array of medical products. Biocoat Inc. further anchors the market by developing and licensing hydrophilic coatings, enhancing device lubricity and performance across various medical applications and contributing to better patient outcomes.
| Leading Market Players |
|---|
| Biocoat Inc. |
| Evonik Industries AG |
| DSM Biomedical |
| Formacoat |
| Harland Medical Systems |
| Hydromer Inc. |
| AST Products Inc. |
| Specialty Coatings Systems Inc. |
| SurModics Inc. |
| Others |
Cost & Logistics Intelligence
Single-source procurement preferences among hospital administrators are reshaping manufacturing strategies, influencing pricing power for integrated device solutions. This demand-side pressure compels device manufacturers to offer fully validated, pre-coated products, impacting the cost structure across the supply chain.
Pricing Analysis
Margin tightening in the specialty coating segment reflects increasing regulatory compliance costs. The dominant pricing model incorporates value-based pricing for integrated implant systems and licensing/royalty agreements for proprietary coating technologies. Price differentiation drivers include certification levels, such as ISO 10993 compliance and FDA/MDR approvals, alongside customization levels for specific medical devices. Pricing pressure stems from the extensive clinical validation required by regulatory bodies. Hospitals, especially large networks, exhibit the most price sensitivity due to volume purchasing, while research laboratories are less price-sensitive for novel coating formulations.
Supply Chain Analysis
Local content mandates in regions like the European Union are prompting a re-evaluation of raw material sourcing for specialized polymers. Geographic supply concentration for finished bioactive coating devices centers in Germany and the United States. The supply chain draws from raw material dependencies on active pharmaceutical ingredients (APIs) and advanced polymers. A primary supply chain risk is single-source vulnerability for niche bioactive agents crucial for specific therapeutic effects. Distribution runs through direct sales channels to hospitals and clinics, alongside strategic OEM partnerships for integrated solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bioactive coatings market is undergoing a technology transition, with advanced plasma spray methods displacing traditional dip coating for complex surface functionalities.
For Market Incumbents: Anchor market share by deepening vertical integration into specialized coating application services. This move mitigates the threat of increased regulatory burden by ensuring end-to-end quality control and compliance. Invest in automated deposition systems, a key lever for reducing batch-to-batch variability and improving production efficiency. Strategic partnerships with biomaterial suppliers also secure access to critical raw materials.
For New Entrants and Emerging Players: Underserved clinics in emerging Asia-Pacific markets present a significant white-space opportunity for novel antimicrobial coatings. Target devices outside the cardiovascular space, such as catheters and dental implants, which have high infection risks. The most penetrable segment includes smaller clinics in South Korea and Australia seeking cost-effective, easily integrated coating solutions. A focused go-to-market angle emphasizing proven infection prevention outcomes can accelerate adoption.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term value in specialized coating technology providers. The market remains viable for the next decade, driven by chronic disease prevalence and an aging population. Identify mid-sized firms with proprietary sol-gel or electrospinning technologies as prime acquisition targets. Increased FDA or EU MDR approvals for smart implant coatings will serve as a key signal of market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Demonstrates safety and efficacy to meet rigorous EU MDR requirements. |
| Licensing Agreement | Expands market access for proprietary coating formulations across diverse device manufacturers. |
| Manufacturing Scale-Up | Reduces per-unit costs for high-volume orthopedic and cardiovascular implant production. |
| Hospital System Partnership | Secures preferred vendor status and simplifies procurement for integrated implant systems. |
| Regulatory Approval Pathway | Accelerates market entry for novel combination products in the United States. |
Research Approach
ClinicalTrials.gov, ISO 10993 guidelines, and EU MDR guidance documents formed the secondary backbone for this analysis. This data was combined with primary interviews involving biomedical engineers, regulatory affairs specialists, hospital procurement managers, and R&D directors. The findings were triangulated through both bottom-up and top-down approaches to ensure comprehensive market coverage and validation.
A bottom-up approach aggregated data from product types and applications, while a top-down validation confirmed overall market estimates. The analytical framework modeled key segmentation dimensions, including product type, end-user, technology, application, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from historical growth patterns and projected technological advancements. Key forecast inputs included implant replacement cycles and chronic disease prevalence rates.
Revisions become necessary when significant shifts in regulatory policy or unforeseen material science breakthroughs materialize. Forecasts reflect current market dynamics and expected technological trajectories. Potential risk factors include unexpected coating delamination issues or new biocompatibility challenges. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
3D Bioprinting Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Tissue Engineering Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Biocompatible 3D Printing Market
Biomedical Engineering
Argentina Artificial Organs and Bionic Implants Market
Biomedical Engineering
Large and Small-Scale Bioprocessing Market