
 Europe Molecular Biosensors Market | 2026-2036
Europe Molecular Biosensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Molecular Biosensors Market Analysis
CE marking under the EU In Vitro Diagnostic Regulation is unwinding market access for legacy product portfolios. F. Hoffmann-La Roche Ltd leverages its established diagnostics infrastructure to sustain compliance leadership across European notified body networks. Dynamic Biosensors GmbH anchors its position through specialized surface plasmon resonance instrumentation. Siemens Healthineers competes by extending its installed base of integrated laboratory systems into molecular workflows.
Europe molecular biosensors are analytical devices that detect biological analytes through transduction of molecular recognition events into quantifiable electrochemical, optical, or piezoelectric signals, typically achieving detection limits in the nanomolar to picomolar range for nucleic acid and protein targets. Their primary commercial purpose centers on accelerating diagnostic turnaround times and enabling point-of-care decision-making in clinical and research settings. Electrochemical platforms dominate current revenue pools due to lower instrument cost and minimal sample preparation requirements, while optical technologies capture expanding share in drug development applications demanding real-time binding kinetics. Nanotechnology-enabled formulations represent the fastest-growing technology segment as European research institutions scale funding for label-free detection architectures.
EMA medical device coordination group activity, ECHA substance registration requirements, and IVDR conformity assessment procedures collectively elevate compliance expenditure for market entrants. These frameworks shape demand by mandating clinical evidence packages that favor established manufacturers with dedicated regulatory affairs capacity. Stakeholders must monitor notified body capacity constraints as backlog duration determines effective product launch timing across member states.
Market Dynamics
The EU In Vitro Diagnostic Regulation is compressing product launch timelines and forcing portfolio rationalization across European molecular diagnostics manufacturers. CE marking transitions under IVDR are redistributing competitive advantage toward firms with dedicated regulatory affairs infrastructure and established notified body relationships.
Growth Catalysts
- IVDR Clinical Evidence Mandates:Stricter conformity assessment procedures under the EU In Vitro Diagnostic Regulation are accelerating replacement cycles for legacy instruments. Hospital laboratories in Germany and France are upgrading to compliant platforms.
- Nanotechnology Research Funding:European research institutions are scaling capital deployment for label-free detection architectures. Surface plasmon resonance and electrochemical nanosensor programs receive priority allocation in Horizon Europe frameworks.
- Rhine-Main Biotech Corridor Concentration:Germany's central biotech cluster generates concentrated demand for point-of-care molecular workflows. Frankfurt and Mainz-based clinical laboratories are expanding nucleic acid testing capacity.
Market Restraints
- Notified Body Capacity Bottlenecks:IVDR-designated notified bodies face application backlogs extending conformity assessment duration. Manufacturers experience 12-18 month delays for CE certificate issuance.
- Precious Metal Input Volatility:Electrochemical biosensor production depends on platinum and gold electrode materials. Price swings in these inputs compress margin stability for instrument manufacturers.
- Optical Platform Cost Barriers:Real-time binding kinetics systems require capital expenditure multiples above electrochemical alternatives. Mid-sized clinical laboratories defer optical technology adoption.
Strategic Opportunities
- Eastern European Laboratory Modernization:Poland and Czech Republic clinical networks remain underpenetrated by automated molecular diagnostic platforms. EU cohesion funds are financing infrastructure upgrades in these markets.
- CRISPR-Integrated Detection Convergence:Gene editing technology is merging with electrochemical transduction architectures. Combined platforms enable single-molecule sensitivity without amplification steps.
- EU Green Deal Procurement Incentives:Public hospital purchasing frameworks are embedding sustainability criteria. Biosensor manufacturers with reduced reagent waste profiles gain preferential tender scoring.
Industry Challenges
- IVDR Technical Documentation Expertise Scarcity:Clinical evidence compilation and performance evaluation reporting require specialized regulatory skill sets. Manufacturers compete for limited talent pools in Brussels and Berlin.
- Legacy System Integration Friction:New molecular biosensor platforms must interface with established laboratory information management systems. Siemens Healthineers and Roche installed bases create switching costs for competing entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Molecular Biosensors Market |
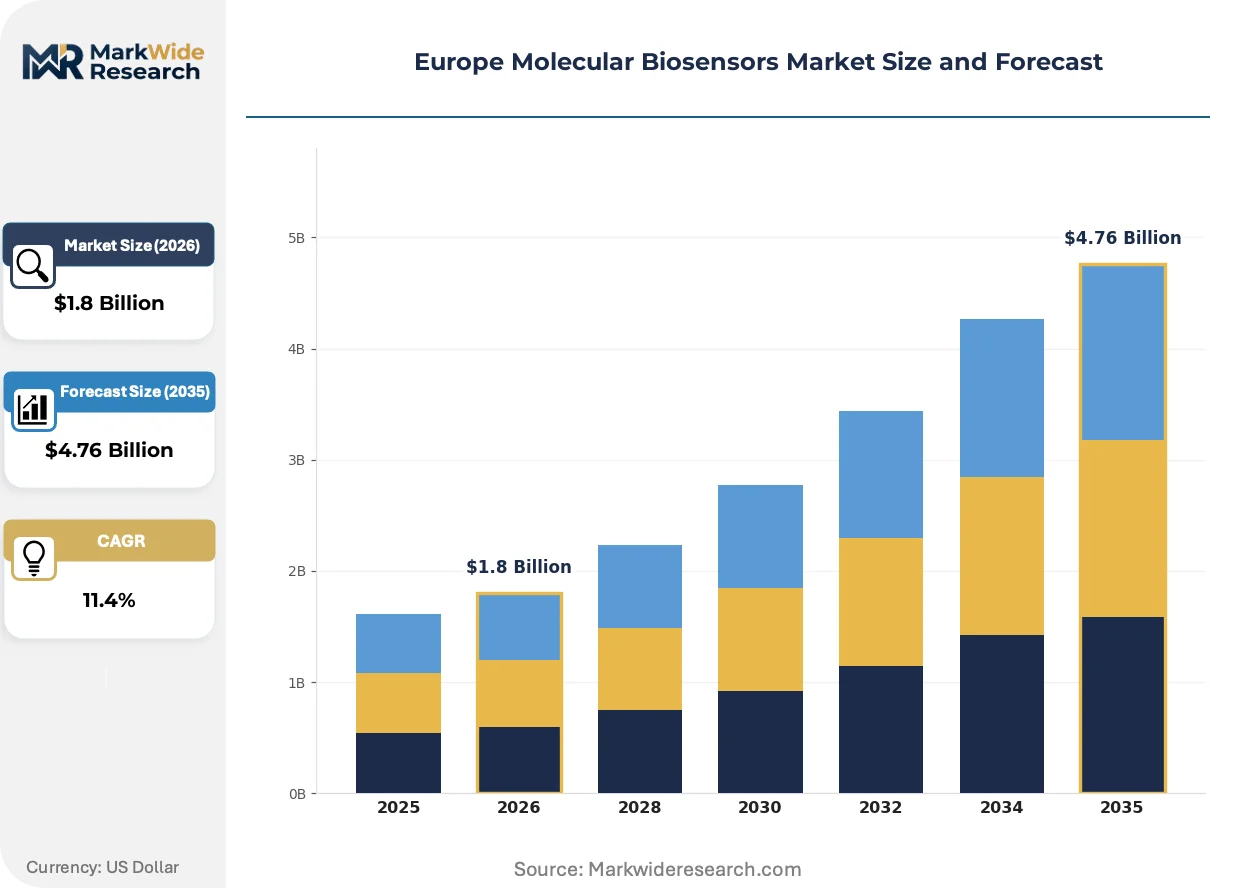
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical, Optical, Piezoelectric, Thermal Technology: Nanotechnology, Bioluminescence, Surface Plasmon Resonance, FRET End User: Pharmaceuticals, Biotechnology, Research Institutions, Clinical Labs Application: Diagnostics, Environmental Monitoring, Food Safety, Drug Development |
| Companies Covered | Nova Biomedical Corporation, F. Hoffmann-La Roche Ltd, Dynamic Biosensors GmbH, Danaher Corporation, Johnson & Johnson, Abbott Laboratories, Sysmex Corporation, Medtronic PLC, Siemens Healthineers, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Molecular Biosensors Market Emerging Trajectories
European molecular biosensor development is pivoting toward label-free architectures and integrated microfluidic cartridges. These shifts are compressing assay turnaround times while elevating regulatory documentation burdens for manufacturers.
Electrochemical nanosensor technology is miniaturizing through graphene and carbon nanotube electrode formulations. German clinical laboratories are adopting palm-sized glucose and lactate analyzers for bedside monitoring. This form factor reduction is enabling decentralized testing outside traditional laboratory infrastructure.
EMA medical device coordination group guidance is harmonizing clinical evidence requirements across member states. The regulation is forcing manufacturers to standardize post-market surveillance protocols. High-throughput drug development applications in Switzerland and the Netherlands are experiencing the steepest compliance cost increases.
Hospital procurement departments are consolidating vendor relationships through framework agreements. France's AP-HP and Germany's university hospital networks are reducing supplier counts from twelve to three for molecular diagnostics. This concentration is visible most acutely in the Benelux region's group purchasing organization activity.
Europe Molecular Biosensors Market Segmentation
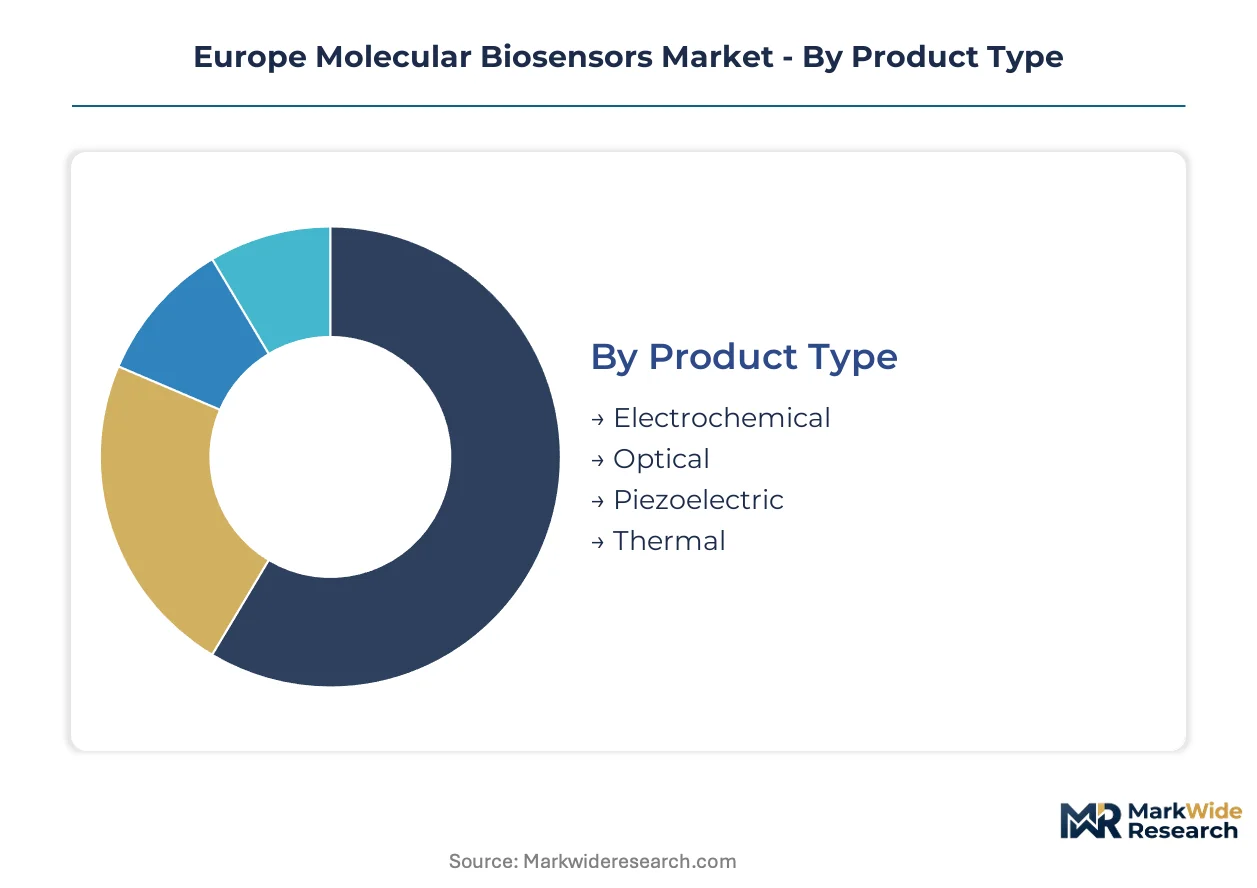
Segmentation reveals how IVDR compliance costs and detection sensitivity requirements reshape purchasing patterns across European clinical networks. Platform selection increasingly correlates with laboratory scale and regulatory certification capacity rather than technology preference alone.
Product Type:
CE marking pathways diverge sharply by transduction mechanism, with electrochemical platforms facing streamlined conformity assessment under IVDR Annex IX compared to novel optical architectures requiring Annex X scrutiny.
- Electrochemical:Platinum and gold electrode configurations dominate bedside glucose and lactate monitoring in German university hospitals. Lower instrument costs and minimal sample preparation sustain preference among France's AP-HP network laboratories upgrading legacy systems.
- Optical:Real-time binding kinetics systems command capital expenditure multiples above electrochemical alternatives, concentrating adoption in Swiss and Dutch high-throughput drug development facilities where binding affinity data justifies premium positioning.
- Piezoelectric:Quartz crystal microbalance platforms enable mass-sensitive detection without labeling in specialized research settings.
- Thermal:Calorimetric biosensors remain niche for enzyme kinetic studies in European academic institutions.
Established volume favors electrochemical; emerging adoption favors optical.
Technology:
Horizon Europe funding allocations prioritize label-free architectures, compressing development timelines for nanotechnology-enabled platforms while extending validation cycles for fluorescence-based methods.
- Nanotechnology:Graphene and carbon nanotube electrode formulations miniaturize detection systems to palm-sized formats. Frankfurt-based clinical laboratories deploy these for decentralized nucleic acid testing outside traditional infrastructure.
- Surface Plasmon Resonance:Dynamic Biosensors GmbH anchors German market presence through specialized instrumentation. Real-time biomolecular interaction analysis sustains demand from Rhine-Main biotech corridor contract research organizations.
- Bioluminescence:Luciferase reporter systems maintain presence in European environmental monitoring applications.
- FRET:Fluorescence resonance energy transfer configurations face margin pressure from label-free alternatives in protein-protein interaction studies.
Research funding concentrates on nanotechnology; commercial deployment concentrates on surface plasmon resonance.
End User:
Procurement authority consolidation across European hospital networks is reducing vendor counts from twelve to three, favoring manufacturers with dedicated regulatory affairs infrastructure.
- Clinical Labs:Germany's Rhine-Main corridor and France's AP-HP network drive replacement cycles for IVDR-compliant platforms. Hospital laboratory directors prioritize integrated systems compatible with existing Siemens Healthineers and Roche installed bases.
- Pharmaceuticals:Novartis and Roche diagnostic divisions internalize molecular biosensor development for companion diagnostic programs. In-house production of specialized detection platforms reduces dependency on external suppliers.
- Biotechnology:Mid-sized European biotech firms outsource biosensor development to specialized contract manufacturers.
- Research Institutions:Max Planck and CNRS laboratories receive priority allocation for label-free detection architectures under Horizon Europe frameworks.
Procurement consolidation favors clinical labs; technology development favors research institutions.
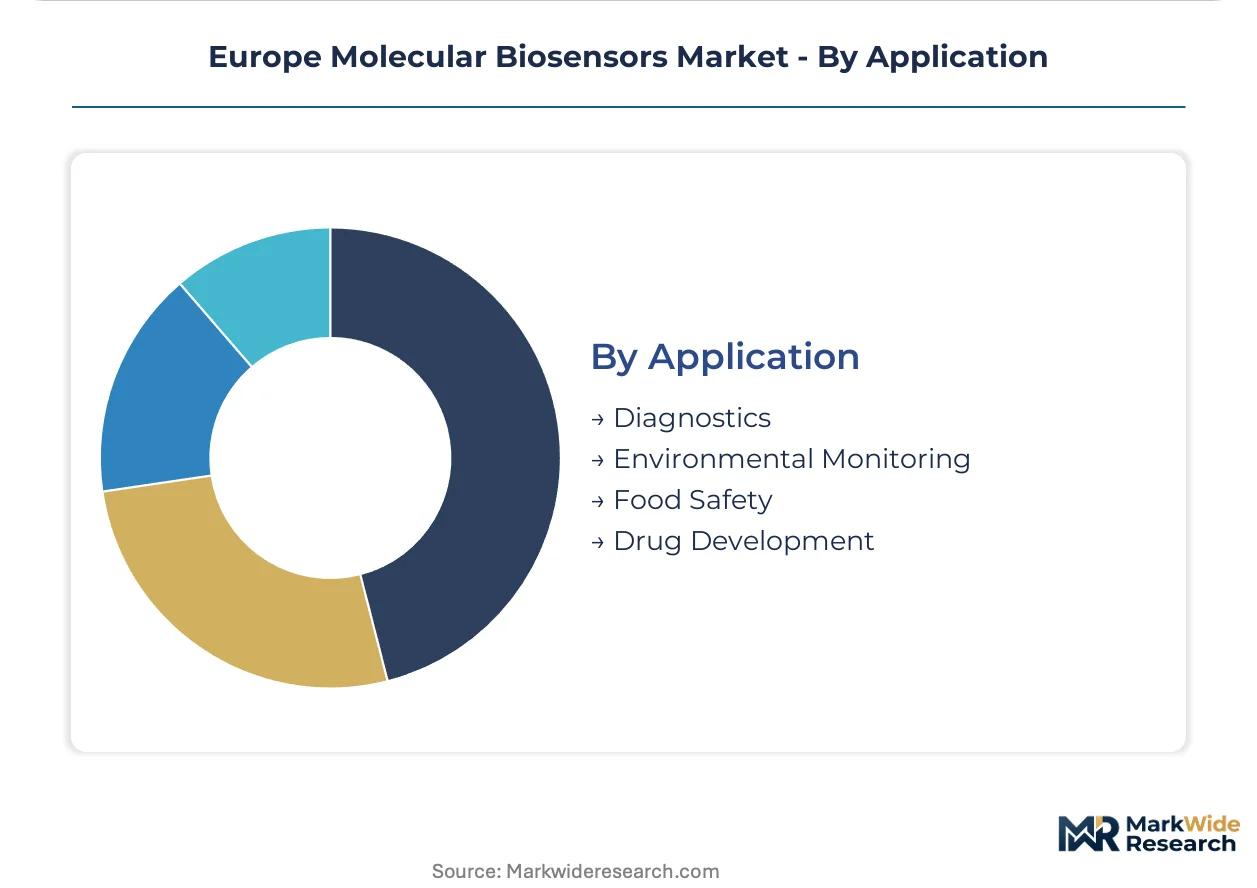
Application:
EU Green Deal procurement incentives embed sustainability criteria in public hospital tender scoring, advantaging platforms with reduced reagent waste profiles.
- Diagnostics:Point-of-care nucleic acid testing expansion in Poland and Czech Republic clinical networks drives demand for automated molecular platforms. EU cohesion funds finance infrastructure upgrades in these underpenetrated markets.
- Drug Development:Switzerland and Netherlands-based pharmaceutical R&D facilities experience steepest compliance cost increases under EMA medical device coordination group guidance harmonization.
- Environmental Monitoring:ECHA substance registration requirements elevate sensor calibration documentation burdens for water quality applications.
- Food Safety:Rapid pathogen detection systems face price pressure from culture-based methods in Southern European agricultural testing laboratories.
Regulatory momentum favors diagnostics; sustainability incentives favor environmental monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU cohesion funds and IVDR implementation timelines are redistributing molecular biosensor deployment across member states. Hospital laboratory modernization programs concentrate capital flows in Germany, France, and emerging Eastern European clinical networks.
Germany
The Rhine-Main biotech corridor generates concentrated demand for point-of-care nucleic acid testing platforms. IVDR conformity assessment procedures under EMA medical device coordination group guidance accelerate replacement cycles in Frankfurt and Mainz-based laboratories. Siemens Healthineers maintains installed base dominance across university hospital networks in Hesse and Baden-Württemberg.
France
AP-HP procurement consolidation reduces molecular diagnostics vendor counts from twelve to three across Paris hospital networks. ANSM clinical evidence requirements under IVDR Annex IX streamline CE marking pathways for electrochemical platforms. Île-de-France clinical laboratories expand automated workflows in response to post-market surveillance mandates.
Switzerland
Swissmedic harmonization with EU IVDR standards compresses product registration timelines for cross-border manufacturers. Novartis and Roche diagnostic divisions internalize biosensor development for companion diagnostic programs in Basel. High-throughput drug development facilities in Zurich and Geneva experience steepest compliance cost increases.
Poland
EU cohesion funds finance clinical laboratory infrastructure upgrades in Warsaw and Kraków hospital networks. The country's national pharmaceutical regulator aligns device registration with IVDR technical documentation requirements. Mid-sized clinical laboratories in Silesia and Greater Poland regions adopt automated molecular platforms for the first time.
Netherlands
Amsterdam and Rotterdam-based contract research organizations drive demand for real-time binding kinetics systems in drug development applications. Dutch healthcare procurement frameworks embed EU Green Deal sustainability criteria in tender scoring. Eindhoven microfluidics clusters supply cartridge components to pan-European biosensor manufacturers.
Europe Molecular Biosensors Market Vendor Landscape
Player mix skews toward diversified diagnostics conglomerates with established regulatory affairs infrastructure. Market structure concentrates around firms with dedicated notified body relationships and legacy CE marking experience. Three archetypes dominate: integrated laboratory systems providers, specialized surface plasmon resonance instrument manufacturers, and point-of-care electrochemical platform developers. Competitive moves center on portfolio rationalization to eliminate non-compliant legacy products and strategic partnerships to access Eastern European distribution channels.
Within the diversified diagnostics tier, F. Hoffmann-La Roche Ltd and Siemens Healthineers occupy positions shaped by installed base dominance across German and French hospital networks. Dynamic Biosensors GmbH anchors the specialized instrumentation segment through its Munich-based surface plasmon resonance operations. Danaher Corporation exemplifies the acquisition-driven consolidation archetype common among US-domiciled conglomerates competing in European molecular diagnostics. These three entities represent distinct strategic postures: regulatory compliance leadership through scale, technical specialization in label-free detection, and portfolio breadth through M&A integration.
| Leading Market Players |
|---|
| Nova Biomedical Corporation |
| F. Hoffmann-La Roche Ltd |
| Dynamic Biosensors GmbH |
| Danaher Corporation |
| Johnson & Johnson |
| Abbott Laboratories |
| Sysmex Corporation |
| Medtronic PLC |
| Siemens Healthineers |
| Others |
Supply Flow & Price Mechanics
Installed base economies across German and French hospital networks compress price floors for electrochemical platforms while elevating premium capture for IVDR-certified optical systems. IVDR conformity assessment backlogs create capacity scarcity that insulates compliant manufacturers from price erosion in the near term.
Pricing Analysis
Certification level (CE-IVDR grade versus legacy CE-IVD) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with platinum electrode configurations commanding premiums over gold alternatives. Pricing pressure stems from EU cohesion fund procurement in Eastern Europe, where mid-sized laboratories prioritize instrument cost over binding kinetics capability. Clinical laboratories in Poland and Czech Republic exhibit highest price sensitivity; Swiss pharmaceutical R&D facilities show lowest sensitivity due to real-time data requirements.
Supply Chain Analysis
Germany and Switzerland anchor precision electrode manufacturing for electrochemical platforms, while Netherlands-based microfluidics clusters supply cartridge components. Production draws from platinum and gold feedstocks sourced through South African and Russian refining channels, with graphene electrode formulations increasingly sourced from Chinese material suppliers. Single-source vulnerability concentrates in noble metal electrode supply, with distribution running through pan-European diagnostics distributors serving hospital procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
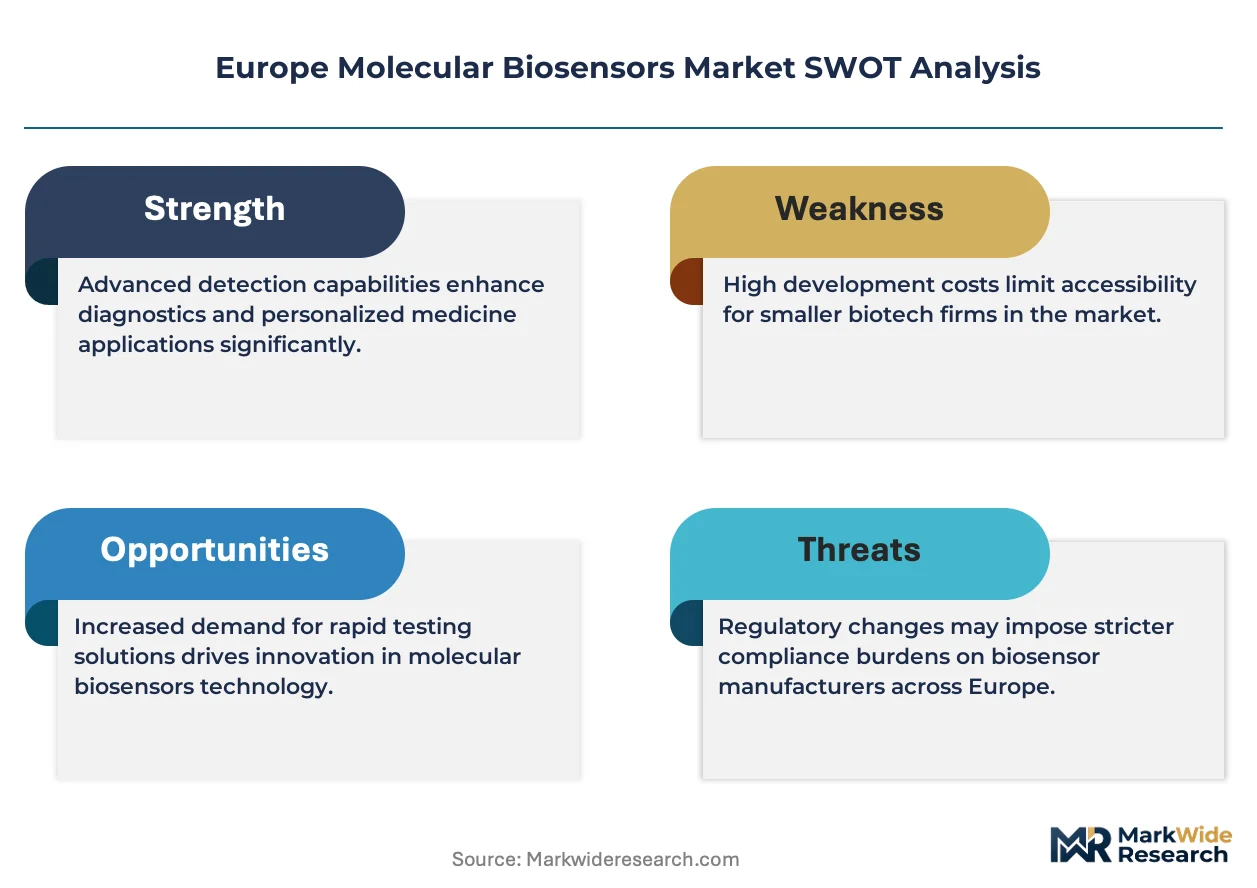
IVDR regulatory disruption compresses launch timelines and consolidates vendor relationships, creating asymmetric returns for compliance-ready manufacturers versus legacy product holders.
For Market Incumbents: Shield market position by accelerating portfolio rationalization to eliminate non-compliant legacy instruments before notified body backlogs clear. Deepen notified body relationships in Germany and France to secure priority assessment slots. Channel control through Siemens Healthineers and Roche installed bases creates switching costs that emerging competitors struggle to overcome. For New Entrants and Emerging Players: Lead with CRISPR-integrated electrochemical platforms targeting Poland and Czech Republic clinical networks where EU cohesion funds finance first-time automated molecular platform adoption. Eastern European laboratory modernization represents the most penetrable geography. Partner with Eindhoven microfluidics clusters for cartridge supply to bypass capital-intensive instrument manufacturing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized surface plasmon resonance instrument manufacturers with Horizon Europe funding relationships and established academic distribution. Long-term viability hinges on label-free detection architecture dominance as fluorescence methods face margin displacement. Watch EMA medical device coordination group guidance harmonization timing as the critical inflection signal for compliance cost trajectories across drug development applications.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Pathway Acceleration | Notified body prioritization secures CE marking ahead of competitor backlog clearance in German networks. |
| Horizon Europe Funding Alignment | Label-free detection architectures receive priority capital allocation from Max Planck and CNRS laboratories. |
| Eastern European Distribution Partnership | EU cohesion fund procurement channels in Poland bypass entrenched Siemens and Roche hospital relationships. |
| Microfluidics Cartridge Integration | Eindhoven cluster supply agreements reduce reagent waste profiles for EU Green Deal tender scoring. |
| Companion Diagnostic Co-development | Novartis and Roche internalization trends create outsourced development opportunities for specialized CROs. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with clinical laboratory directors, hospital procurement managers, regulatory affairs leads at notified bodies, and biomedical engineers at research institutions. Secondary validation incorporated EMA medical device coordination group guidance documents, IVDR technical documentation requirements, Horizon Europe funding allocation records, and hospital procurement database extracts from France's AP-HP and Germany's university hospital networks. Bottom-up instrument deployment estimates triangulated against top-down market sizing from electrochemical and optical platform revenue pools.
Across the analysis window, forecasts segmented by transduction mechanism, technology architecture, end-user category, and geographic regulatory cluster modeled replacement cycle timing under IVDR implementation schedules. CAGRs derived from instrument shipment trajectories and reagent consumables attach rates, with nanotechnology-enabled platform adoption curves calibrated against Horizon Europe capital deployment patterns and surface plasmon resonance installed base expansion in the Rhine-Main corridor.
The analysis sits within stated boundaries; outcomes outside IVDR notified body capacity resolution timelines or noble metal price stability corridors would require recalibration. Forecasts assume EMA guidance harmonization proceeds without member state derogation, with risk factors including extended platinum supply disruption or Eastern European cohesion fund reallocation. Recalibration cycles align with material shifts in regulatory implementation velocity and research funding priority reallocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanobiotechnology
Boron Nitride Nanotubes in Nanomedicine Market
Nanobiotechnology
Nanopore Sequencing Market
Nanobiotechnology
Bio-Inspired and Nano-Engineered Surfaces Market
Nanobiotechnology
Nanobody Market
Nanobiotechnology
Nanopharmaceuticals Market
Nanobiotechnology
Nanotechnology Drug Delivery Market
Nanobiotechnology
Nanobiotechnology Market
Nanobiotechnology
Europe Nanozymes Market
Nanobiotechnology
Nanopore Technologies Market
Nanobiotechnology
Nanozymes Market
Nanobiotechnology
Nano Biosensors Market
Nanobiotechnology
Designer DNA Nanocages Market