
 Bioabsorbable Osteosynthesis Devices Market | 2026-2036
Bioabsorbable Osteosynthesis Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Bioabsorbable Osteosynthesis Devices Market Analytics
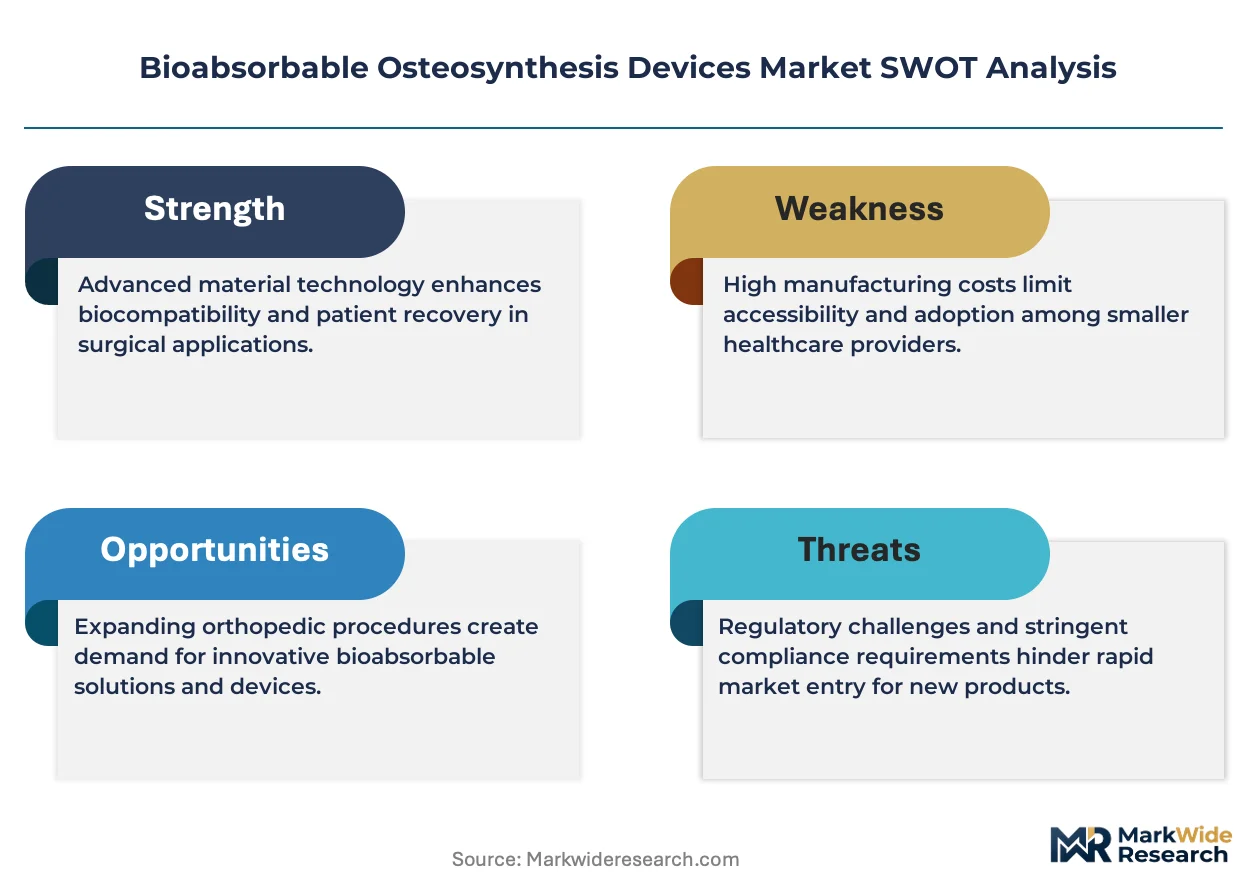
The gap between premium composite-based systems and standard polylactic acid hardware is repositioning procurement criteria across hospital networks and ambulatory surgical centers. DePuy Synthes leverages its orthopedic franchise breadth to sustain contract penetration with integrated delivery networks. Zimmer Biomet anchors its position through specialized trauma portfolios that emphasize controlled resorption kinetics. Smith & Nephew competes by dominating sports medicine applications where athlete recovery timelines dictate hardware selection.
Bioabsorbable osteosynthesis devices are implantable fixation constructs manufactured from polymers such as polylactic acid, polyglycolic acid, or polycaprolactone that degrade through hydrolysis and eliminate the need for secondary removal surgery. These devices achieve initial mechanical strength comparable to cortical bone while resorbing over 12 to 24 months depending on copolymer ratio and crystallinity. The screws segment leads current revenue contribution due to high utilization in ankle and wrist fracture fixation, while composite materials represent the fastest-expanding material category as surgeons demand tailored degradation profiles for load-bearing applications. Trauma repair occupies the largest application share reflecting emergency department admission patterns, though sports medicine generates superior per-procedure margins through premium pricing of athlete-specific fixation systems.
The FDA enforces biocompatibility and degradation testing under ISO 10993 and ASTM F1635 standards, while the EU Medical Device Regulation mandates clinical evidence for resorbable implant longevity claims that shapes product development timelines and market access costs. Japan's PMDA applies distinct JIS standards for polymer purity that create additional compliance layers for manufacturers seeking reimbursement under the national health insurance system. Stakeholders must monitor evolving regulatory divergence between major markets to anticipate where clinical trial investment will yield prioritized approval pathways.
Market Dynamics
The divergence between FDA's updated bioresorbable polymer degradation guidance and Japan's PMDA JIS purity standards is forcing manufacturers to run parallel validation tracks, compressing development timelines while expanding compliance budgets across all major markets.
Growth Catalysts
- Trauma Volume Surge:Aging populations in the United States, Germany, and Japan are driving emergency department admissions for ankle and wrist fractures that require resorbable fixation hardware.
- ISO 10993 Harmonization:The FDA's alignment with international biocompatibility standards is streamlining premarket notification pathways for polymer-based osteosynthesis devices.
- Secondary Surgery Elimination:Patient preference for single-procedure fracture management is accelerating hospital procurement of screws and plates that hydrolyze within 24 months.
Market Restraints
- Lactide Monomer Volatility:Purified polylactic acid feedstock costs fluctuate with agricultural commodity markets, squeezing gross margins for standard-grade hardware manufacturers.
- Composite Production Concentration:Controlled-resorption polymer-ceramic blending capabilities cluster in Switzerland and southern Germany, creating supply vulnerability for tailored degradation profiles.
- Metallic Implant Substitution:Titanium mini-plates retain dominance in mandibular and craniofacial applications where mechanical load exceeds polymer strength thresholds.
Strategic Opportunities
- Pediatric Deformity Correction:Underpenetrated demand in adolescent scoliosis and craniosynostosis procedures offers expansion paths for devices with 12-month resorption cycles.
- Ambulatory Surgery Center Channel:Freestanding orthopedic clinics in Texas and Florida are building captive inventory of absorbable fixation kits for same-day discharge protocols.
- EU MDR Clinical Evidence Pathways:The Medical Device Regulation's emphasis on longitudinal implant performance data rewards manufacturers investing in 5-year patient registries with preferential notified body attention.
Industry Challenges
- Polymer Crystallinity Expertise Gap:Formulation chemists capable of tuning copolymer ratios for load-bearing applications command premium compensation, constraining R&D team scaling.
- ASTM F1635 Timeline Compression:Accelerated degradation testing under hydrolytic conditions requires 6-12 month validation cycles that delay product launches despite simulated aging protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioabsorbable Osteosynthesis Devices Market |
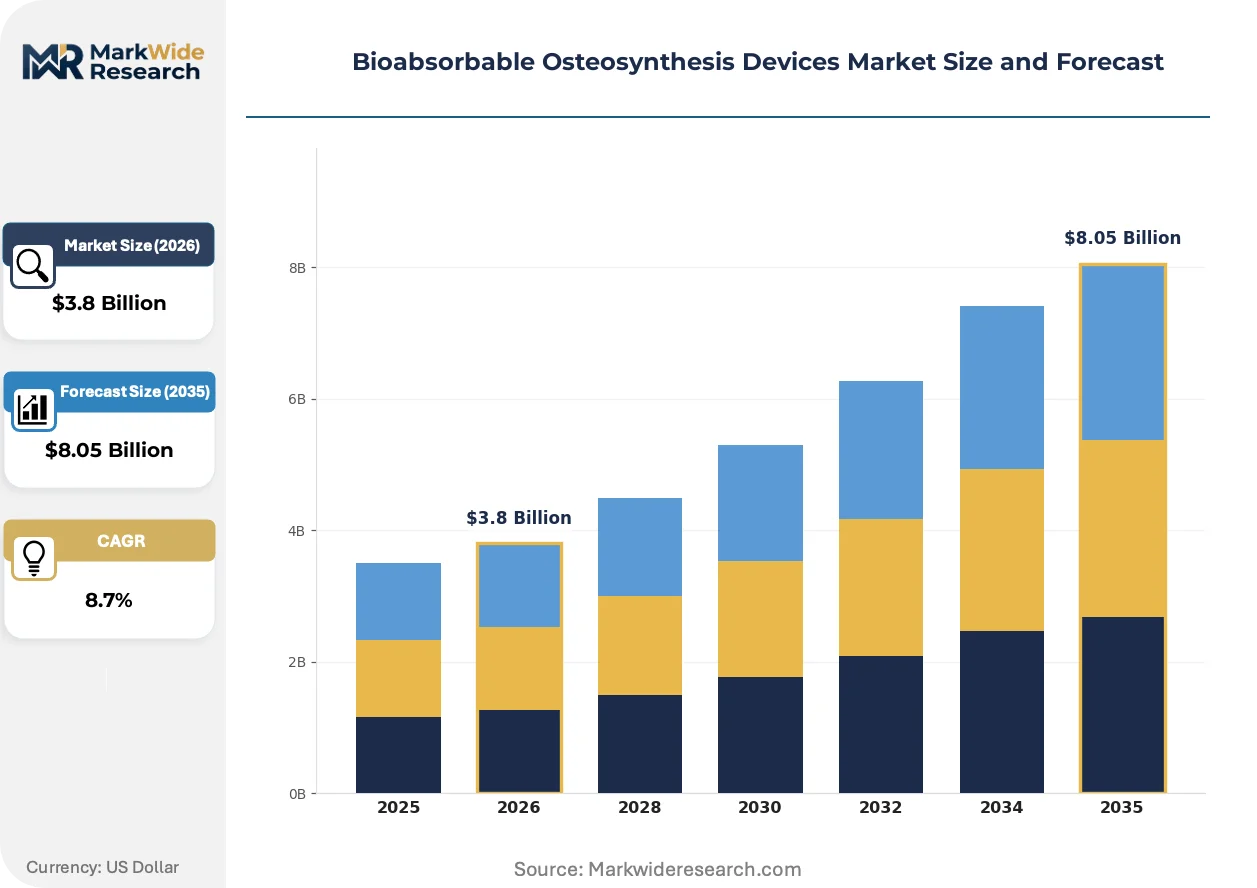
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screws, Plates, Pins, Wires Material: Polylactic Acid, Polyglycolic Acid, Polycaprolactone, Composite Materials Application: Trauma Repair, Orthopedic Surgery, Maxillofacial Surgery, Sports Medicine Delivery Mode: Implantation, Injection, Surgical Insertion, Custom Fabrication |
| Companies Covered | DePuy Synthes, Stryker, Zimmer Biomet, Smith & Nephew, Medtronic, Arthrex, Globus Medical, OSSIO, Bioretec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioabsorbable Osteosynthesis Devices Market Evolving Landscape
Manufacturing automation and regulatory data requirements are converging to reshape how resorbable fixation devices move from formulation to surgical implantation, with material science advances outpacing traditional quality assurance frameworks.
Self-reinforced polylactic acid composites are automating the production of patient-specific osteosynthesis plates through fused filament fabrication systems that deposit fiber-aligned polymer structures. Orthopedic device contract manufacturers in Massachusetts and Baden-Württemberg are installing these systems at pilot scale. The technology is automating lot-size reduction from thousands to single-unit batches while maintaining ISO 10993 compliance documentation.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic implant tracking through EUDAMED, the European database for medical devices. Manufacturers must now submit periodic safety update reports that correlate clinical outcomes with polymer batch records. Trauma applications face the steepest documentation burden as high-volume screw utilization generates disproportionate follow-up data obligations.
Integrated delivery networks are consolidating orthopedic hardware procurement through centralized value analysis committees that evaluate total episode cost rather than device price alone. Hospital systems in California and New York are disqualifying vendors lacking real-time inventory visibility through electronic data interchange protocols. This consolidation is most visible in sports medicine segments where athlete-specific fixation systems command premium positioning and surgeons wield concentrated purchasing influence.
Bioabsorbable Osteosynthesis Devices Market Segmentation
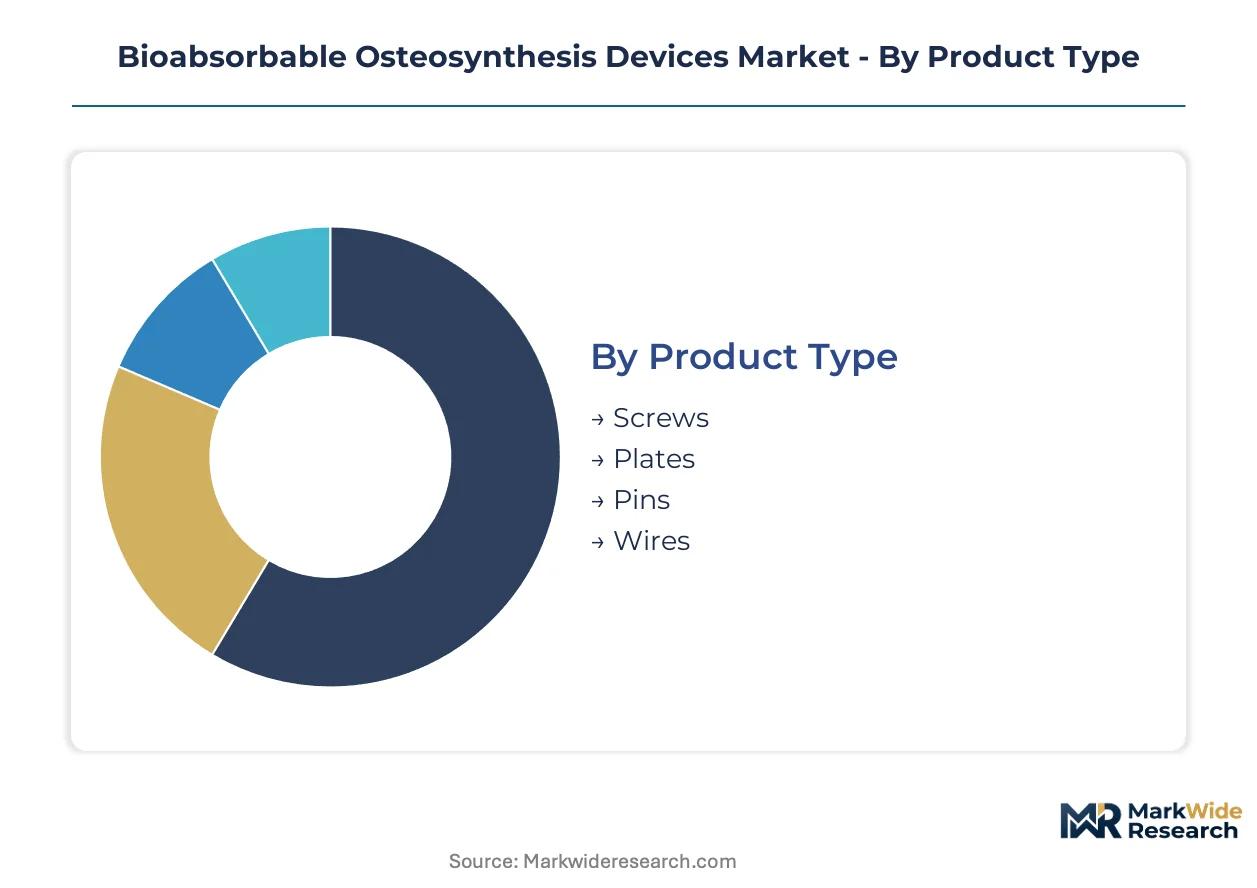
Segmentation in bioabsorbable osteosynthesis devices reveals how polymer chemistry, anatomical application, and procedural setting intersect to determine procurement patterns. Hospital value analysis committees weigh degradation kinetics against inventory complexity when standardizing across product categories.
Product Type:
Replacement cycles for resorbable hardware accelerate as surgeons upgrade from first-generation pins to composite-reinforced screws with controlled hydrolysis profiles.
- Screws:Self-tapping designs manufactured from self-reinforced polylactic acid achieve initial pull-out strength matching cortical bone. Demand concentrates in ankle fracture fixation at United States trauma centers where emergency department volume drives consumption.
- Plates:Contoured osteosynthesis plates with fiber-aligned polymer structures distribute mechanical load across comminuted fractures. German orthopedic departments prioritize these for distal radius reconstruction where resorption must outlast bone consolidation.
- Pins:Kirschner-wire equivalents in polyglycolic acid provide provisional fixation for pediatric supracondylar humerus fractures.
- Wires:Cerclage configurations address sternal closure and small bone tethering where tensile strength requirements are modest.
Screws sit at the top of the volume ranking, with plates climbing the fastest as composite manufacturing enables load-bearing applications.
Material:
Cost tier differentiation separates commodity lactide polymers from premium composite formulations that command three-fold price multiples in sports medicine procurement.
- Polylactic Acid:Semi-crystalline PLLA and amorphous PDLLA copolymers dominate standard trauma applications with 18-24 month resorption timelines. United States hospital systems standardize on these for high-volume ankle and wrist fixation to minimize SKU complexity.
- Composite Materials:Polymer-ceramic blends incorporating beta-tricalcium phosphate or bioactive glass tune degradation rates for load-bearing scenarios. Japanese orthopedic surgeons specify these for tibial plateau fractures where mechanical demand exceeds pure polymer capabilities.
- Polyglycolic Acid:Rapid hydrolysis over 4-6 weeks suits temporary fixation in craniofacial applications where bone healing proceeds quickly.
- Polycaprolactone:Extended 24-36 month resorption profiles address pediatric deformity correction where growth modulation requires prolonged implant presence.
Polylactic acid sits at the top of the volume ranking, with composite materials gaining share fastest as surgeon demand for tailored degradation profiles expands.
Application:
Procedure volume distribution across emergency, elective, and specialized surgical settings determines how manufacturers configure sales force deployment and inventory positioning.
- Trauma Repair:Emergency department admission patterns for distal radius and ankle fractures generate predictable demand spikes. German level-one trauma centers maintain captive inventory of resorbable screw kits for immediate operative availability.
- Sports Medicine:Athlete-specific fixation systems command premium positioning through accelerated rehabilitation protocols. United States ambulatory surgery centers in Texas and Florida stock specialized inventory for same-day discharge ACL reconstruction with absorbable interference screws.
- Orthopedic Surgery:Elective joint reconstruction and deformity correction procedures utilize larger plates and customized constructs.
- Maxillofacial Surgery:Mandibular and craniofacial applications favor smaller profiles where polymer strength thresholds meet reduced mechanical load requirements.
Trauma repair sits at the top of the volume ranking, with sports medicine climbing the fastest as per-procedure margins attract manufacturer investment.
Delivery Mode:
Supply concentration in sterile-packaged implants versus patient-specific fabrication capabilities is reshaping how manufacturers organize production workflows and regulatory documentation.
- Implantation:Pre-sterilized screws and plates in peel-pouch packaging dominate hospital procurement through distributor channels. United States integrated delivery networks mandate electronic data interchange visibility for these SKUs.
- Custom Fabrication:Fused filament fabrication systems producing patient-specific plates from medical-grade polymer filament are piloting at Massachusetts and Baden-Württemberg contract manufacturers. These single-unit batches require individualized ISO 10993 documentation.
- Surgical Insertion:Standard open reduction internal fixation techniques utilize conventional instrumentation sets.
- Injection:Injectable polymer formulations for cancellous bone void filling represent an emerging delivery mechanism.
Implantation sits at the top of the volume ranking, with custom fabrication climbing the fastest as additive manufacturing enables lot-size reduction without regulatory compromise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's trauma centers deploy resorbable fixation hardware at higher per-capita rates than United States hospitals, while Japan's PMDA maintains stricter polymer purity protocols than FDA equivalents. National reimbursement frameworks and regulatory divergence create distinct procurement environments across major markets.
United States
Emergency department volumes for ankle and wrist fractures drive screw consumption at level-one trauma centers. The FDA's updated bioresorbable polymer degradation guidance accelerates manufacturer investment in ISO 10993 validation studies. Massachusetts contract manufacturers pilot fused filament fabrication systems for patient-specific plate production.
Germany
Aging demographics expand distal radius reconstruction procedures requiring load-bearing plates with 18-24 month resorption timelines. The EU Medical Device Regulation mandates clinical evidence for implant longevity claims that extends product development cycles. Baden-Württemberg orthopedic departments prioritize fiber-aligned polymer structures for comminuted fracture management.
Japan
National health insurance reimbursement policies favor premium composite materials for tibial plateau fractures exceeding pure polymer strength thresholds. PMDA applies distinct JIS standards for polymer purity that create additional compliance layers for market entry. Tokyo metropolitan trauma centers maintain captive inventory for immediate operative availability.
Switzerland
Controlled-resorption polymer-ceramic blending capabilities concentrate in Swiss manufacturing clusters serving European orthopedic networks. Swissmedic oversees medical device conformity assessment under EU MDR mutual recognition agreements. Basel-region contract manufacturers supply beta-tricalcium phosphate composite formulations to German hospital systems.
United Kingdom
NHS value analysis committees evaluate total episode cost for fracture fixation hardware procurement decisions. The Medicines and Healthcare products Regulatory Agency aligns with EUDAMED post-market surveillance requirements for implant tracking. London teaching hospitals standardize on polylactic acid screws to minimize SKU complexity across orthopedic departments.
Bioabsorbable Osteosynthesis Devices Market Competitive Landscape
Top-tier vendors anchor integrated delivery network contracts, while mid-tier specialists concentrate on sports medicine niches and regional trauma markets. The vendor base spans diversified orthopedic conglomerates with broad franchise breadth and focused resorbable polymer specialists with formulation expertise. Two strategic archetypes dominate: diversified device manufacturers leveraging hospital system relationships, and materials science specialists commanding premium positioning through controlled degradation profiles. Competitive moves center on M&A activity consolidating trauma and sports medicine portfolios, and strategic partnerships securing polymer-ceramic blending capabilities.
Within the diversified orthopedic tier, DePuy Synthes and Stryker occupy positions reflecting broad franchise integration with hospital procurement systems. Zimmer Biomet exemplifies the trauma-specialist archetype through its emphasis on resorption kinetics for load-bearing applications. Smith & Nephew represents the sports medicine-focused positioning where athlete recovery timelines command premium hardware selection.
| Leading Market Players |
|---|
| DePuy Synthes |
| Stryker |
| Zimmer Biomet |
| Smith & Nephew |
| Medtronic |
| Arthrex |
| Globus Medical |
| OSSIO |
| Bioretec |
| Others |
Value Network & Pricing Analysis
Purified polylactic acid feedstock costs fluctuate with agricultural commodity markets, cascading through three-tier pricing structures across premium composite formulations, standard lactide polymers, and economy-grade pins. Hospital value analysis committees in the United States and Germany negotiate contract tiers that reflect these input cost variations while demanding ISO 10993 documentation compliance.
Pricing Analysis
Capacity additions in Switzerland and southern Germany are reshaping price floors for polymer-ceramic composite formulations. Three-tier pricing structure across premium, standard, and economy levels separates fiber-aligned plates with tailored degradation profiles from commodity screws and basic pins. Cost compression in standard-grade hardware intensifies because lactide monomer volatility squeezes manufacturer margins. Ambulatory surgery centers in Texas and Florida exhibit highest price sensitivity, while Japanese trauma centers prioritize performance over unit cost for tibial plateau applications.
Supply Chain Analysis
Japan's PMDA JIS purity standards and domestic-content verification requirements are reshaping sourcing patterns for manufacturers seeking reimbursement under national health insurance. Controlled-resorption polymer-ceramic blending capabilities concentrate in Switzerland, southern Germany, and Massachusetts, creating geographic clustering around formulation expertise. Raw material dependencies include purified lactide monomers, beta-tricalcium phosphate ceramics, and medical-grade polyglycolic acid resins. Single-source vulnerability runs through Swiss composite manufacturing clusters serving European orthopedic networks. Distribution runs through integrated delivery network value analysis committees that mandate electronic data interchange visibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by aging demographics that sustain trauma and joint reconstruction volumes across developed economies.
For Market Incumbents: Anticipate metallic implant substitution pressure in mandibular and craniofacial applications where titanium mini-plates retain mechanical superiority. Deepen backward integration into polymer-ceramic blending capabilities in Switzerland or Baden-Württemberg to secure controlled-resorption formulation supply. Fortify hospital system partnerships through real-time inventory visibility protocols that satisfy value analysis committee requirements. For New Entrants and Emerging Players: EU MDR clinical evidence pathways in Europe open a window for registry-based market entry strategies that reward longitudinal implant performance documentation. Pediatric deformity correction represents the most penetrable segment, with adolescent scoliosis and craniosynostosis procedures currently underserved by resorbable fixation specialists. Target ambulatory surgery center channels in Texas and Florida with same-day discharge protocol compatibility as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where polymer crystallinity expertise gaps constrain R&D team scaling for load-bearing applications. The five-to-ten-year viability window favors acquisition targets with captive ISO 10993 validation capabilities and existing notified body relationships. Materials science specialists with proprietary copolymer ratio tuning expertise represent the preferred target archetype. Watch FDA guidance evolution on bioresorbable polymer degradation profiles as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer-Ceramic Composite Capacity Expansion | Swiss and German manufacturing clusters secure supply for load-bearing orthopedic applications. |
| FDA Degradation Profile Validation Investment | Accelerated ISO 10993 studies preempt regulatory scrutiny for bioresorbable implant approvals. |
| Hospital System Partnership Deepening | Integrated delivery network contracts lock in volume through electronic data interchange mandates. |
| Patient-Specific Fabrication Pilot Scaling | Massachusetts and Baden-Württemberg contract manufacturers automate fused filament production systems. |
| EU MDR Post-Market Surveillance Buildout | EUDAMED tracking compliance satisfies notified body attention for longitudinal implant registries. |
Research Methodology
Bottom-up trauma volume modeling reconciled against top-down polymer feedstock tracking forms the analytical core of this study. Primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers informed demand-side assumptions. Secondary validation drew from FDA 510(k) filings, EUDAMED device registrations, CMS Medicare procedure data, and hospital procurement database extracts. Top-down and bottom-up estimates triangulated through cross-referencing manufacturer capacity disclosures with emergency department admission patterns.
Historical trendline analysis of resorbable fixation procedure volumes established baseline growth trajectories across the projection horizon. The analytical framework models segmentation across product type, material composition, anatomical application, and delivery mode, with additional dimensioning by regional regulatory cluster. CAGRs derive from curve-fitting techniques applied to validated historical series. Forecast inputs include trauma center admission forecasts, polymer crystallinity advancement timelines, and reimbursement policy evolution in Japan's national health insurance system.
Revisions become necessary when regulatory divergence between FDA and PMDA accelerates, when lactide monomer costs spike beyond agricultural commodity baseline volatility, or when additive manufacturing adoption in custom fabrication outpaces quality assurance framework adaptation. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market
Biomedical Engineering
Bioink Market
Biomedical Engineering
Tissue Engineering Market
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Bioactive Coating Devices Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Bioprosthetics Market
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
Global Bionics Market
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
Biological Derived Devices Market