
 North America Lab-On-A-Chip and Microarrays (Biochip) Market | 2026-2036
North America Lab-On-A-Chip and Microarrays (Biochip) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lab-On-A-Chip and Microarrays (Biochip) Market Analytics
Hospital-based diagnostics labs is collapsing as the dominant buyer archetype while pharmaceutical companies and contract research organizations capture rising procurement share. Thermo Fisher Scientific leverages its reagent-instrument bundled model to anchor large-scale genomics workflows. Illumina dominates high-throughput sequencing microarrays through proprietary flow cell chemistry. Agilent Technologies specializes in multimodal detection platforms that integrate optical and electrochemical readouts.
Lab-On-A-Chip and Microarrays (Biochip) refers to miniaturized analytical devices fabricated on glass, silicon, or polymer substrates with channel dimensions typically ranging from tens to hundreds of micrometers, enabling parallel biochemical reactions at nanoliter volumes for molecular analysis and clinical diagnostics. Microfluidics-based Lab-On-A-Chip devices lead in growth velocity due to their integration of sample preparation, reaction, and detection on single substrates. DNA Chips retain the largest installed base among product categories, though Protein Chips are gaining traction in precision oncology biomarker panels where margin pools concentrate.
FDA premarket review under the In Vitro Diagnostics framework shapes product validation requirements, while EPA standards govern manufacturing waste streams for semiconductor-grade substrate fabrication. Health Canada and the Canadian Standards Association coordinate with FDA on parallel quality system recognition, reducing dual-compliance burdens for cross-border suppliers. Stakeholders must monitor evolving reimbursement codes from the Centers for Medicare and Medicaid Services as these determine commercial viability of multiplexed diagnostic panels.
Market Dynamics
Academic medical centers in Boston and Research Triangle Park are consolidating point-of-care diagnostic procurement, compressing vendor qualification cycles and favoring platforms with integrated reagent-instrument bundles over standalone microarray consumables.
Growth Catalysts
- Companion Diagnostic Pathways:FDA premarket review under the In Vitro Diagnostics framework is accelerating clearance timelines for multiplexed biomarker panels, enabling parallel drug-diagnostic co-development.
- Microfluidics Integration:Sample preparation, reaction, and detection on single substrates is reducing hands-on time for hospital-based laboratories processing high-complexity oncology specimens.
- Northeast Corridor Concentration:Research Triangle Park and Boston-Cambridge bioclusters are driving installed base expansion through NIH-funded precision medicine consortia requiring high-throughput genomics infrastructure.
Market Restraints
- Semiconductor-Grade Substrate Costs:Silicon and glass wafer prices fluctuate with electronics industry demand cycles, squeezing gross margins for polymer-substrate alternatives.
- Reagent Supply Concentration:Enzyme and fluorescent dye production concentrates among a handful of chemical suppliers, creating single-source vulnerability for multiplexed assay manufacturers.
- Detection Chemistry Limitations:Electrochemical readouts face sensitivity ceilings in low-abundance protein detection compared to optical methods, restricting application scope in early-stage biomarker discovery.
Strategic Opportunities
- Canadian Parallel Recognition:Health Canada and CSA coordination with FDA quality systems reduces dual-compliance burdens, lowering market entry costs for US-based platform vendors.
- Protein Chip Oncology Panels:Precision oncology biomarker workflows represent underpenetrated white space where margin pools concentrate higher than commoditized DNA genotyping arrays.
- Pharmaceutical CRO Procurement:Contract research organizations are capturing rising procurement share as pharmaceutical companies outsource toxicogenomics and pharmacogenomics screening workflows.
Industry Challenges
- Multiplex Validation Complexity:CMS reimbursement code determination for novel diagnostic panels requires extensive clinical utility evidence, extending commercialization timelines.
- Cross-Platform Standardization:Lack of unified file formats between Illumina, Agilent, and Thermo Fisher workflows complicates multi-site clinical trial data aggregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lab-On-A-Chip and Microarrays (Biochip) Market |
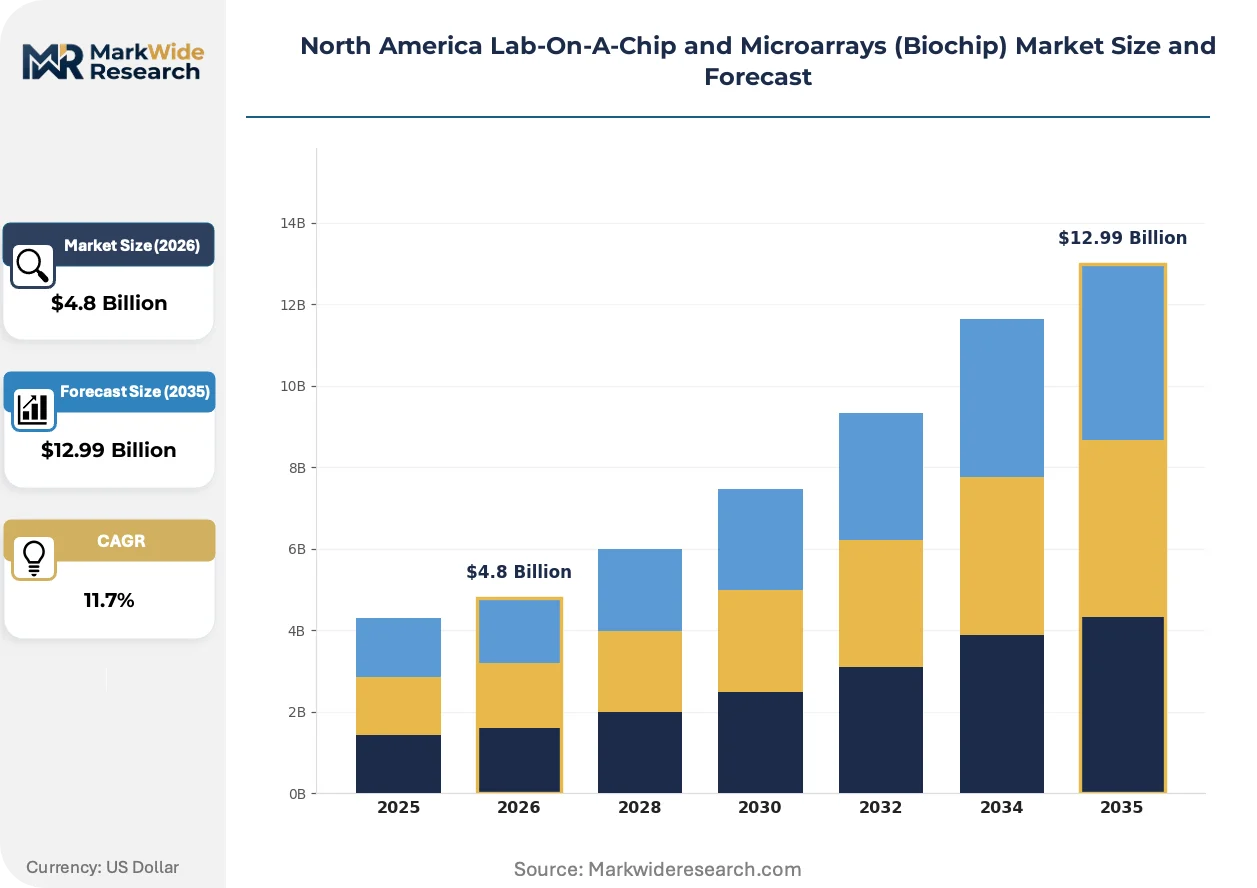
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microarrays, DNA Chips, Protein Chips, Lab-On-A-Chip Technology: Optical Detection, Electrochemical Detection, Microfluidics, Hybridization Application: Genomics, Proteomics, Diagnostics, Drug Discovery End User: Research Institutions, Hospitals, Diagnostics Labs, Pharmaceutical Companies |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, Illumina, Bio-Rad Laboratories, Danaher Corporation, PerkinElmer, Abbott Laboratories, Merck, F. Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lab-On-A-Chip and Microarrays (Biochip) Market Evolving Landscape
Workflow automation and detection modality convergence are restructuring competitive advantage in molecular diagnostics, favoring vendors with integrated platform architectures over consumable-only suppliers.
Digital microfluidics is decomposing traditional liquid-handling robotics in high-throughput screening applications. Pharmaceutical discovery groups at contract research organizations are adopting electrowetting-on-dielectric platforms for nanoliter-scale reagent dispensing. This compression of sample-to-answer workflows is decomposing the historical separation between sample prep, amplification, and detection instrumentation.
EPA semiconductor manufacturing waste stream standards are tightening substrate fabrication compliance costs for silicon-based biochip producers. Facilities in the US Southwest and Pacific Northwest face expanded reporting requirements for photoresist and etchant discharge. Smaller polymer-substrate vendors are capturing share among academic buyers less sensitive to optical performance degradation.
Consolidated procurement by integrated delivery networks is compressing vendor qualification cycles from eighteen months to under nine. Hospital systems in the Northeast United States are mandating LIS integration and remote diagnostics capabilities as table stakes. This behavioral shift favors Thermo Fisher and Illumina with established enterprise service organizations over emerging platform developers.
North America Lab-On-A-Chip and Microarrays (Biochip) Market Segmentation
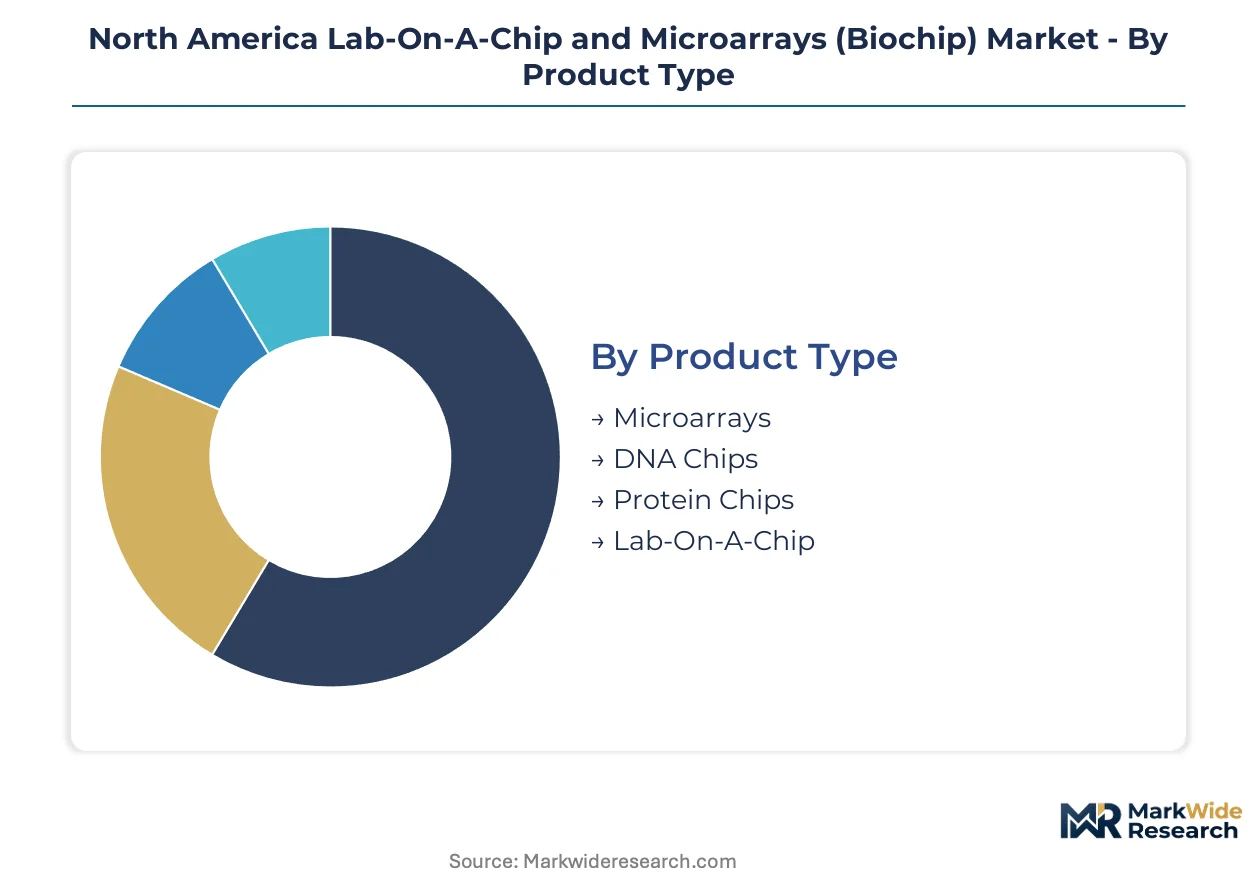
Segmentation in the North America biochip market reveals distinct regulatory pathways and procurement behaviors across product architectures. FDA In Vitro Diagnostics framework applicability varies sharply by detection chemistry and intended use, creating divergent commercialization timelines for vendors.
Product Type:
FDA premarket review intensity differs materially across substrate formats, with silicon-based devices facing EPA semiconductor waste stream compliance burdens absent from polymer alternatives.
- Microarrays:Glass or silicon substrates spotted with biomolecular probes enable parallel analysis of thousands of targets simultaneously. Research Triangle Park academic medical centers are consolidating procurement of high-density formats for NIH-funded precision medicine consortia, compressing vendor qualification cycles to under nine months.
- DNA Chips:Oligonucleotide arrays for genotyping and gene expression profiling retain the largest installed base among all biochip categories. Boston-Cambridge bioclusters drive replacement demand as legacy 3' expression arrays reach end-of-life, though margin pools are compressing toward commoditized pricing.
- Protein Chips:Antibody and recombinant protein arrays for biomarker quantification. Precision oncology workflows in Northeast corridor hospitals represent concentrated margin opportunity.
- Lab-On-A-Chip:Integrated microfluidic devices combining sample prep, reaction, and detection on single substrates. Point-of-care diagnostic platforms are displacing centralized lab workflows in hospital emergency departments.
DNA Chips handle the majority of throughput; Lab-On-A-Chip is expanding most quickly on share.
Technology:
Detection modality selection directly determines sensitivity ceilings and reagent cost structures, with optical methods dominating high-abundance applications and electrochemical approaches gaining traction in resource-limited settings.
- Optical Detection:Fluorescence and chemiluminescence readouts using confocal scanning or CCD imaging. Pharmaceutical companies in Research Triangle Park prefer multi-color formats for toxicogenomics screening.
- Electrochemical Detection:Amperometric and impedimetric sensors eliminating optical components. Sensitivity limitations in low-abundance protein detection restrict application scope in early-stage biomarker discovery.
- Microfluidics:Channel-based or digital droplet architectures manipulating nanoliter volumes. Contract research organizations are adopting electrowetting-on-dielectric platforms for high-throughput pharmaceutical screening.
- Hybridization:Nucleic acid annealing kinetics on solid supports, the foundational chemistry underlying DNA microarray function. Mature technology with established supply chains for oligonucleotide synthesis.
Optical Detection commands the dominant share of installed systems; Microfluidics is climbing the fastest as sample-to-answer integration demands intensify.
Application:
Reimbursement code availability from CMS shapes commercial viability, with diagnostics applications facing steeper evidence requirements than research-use-only segments.
- Genomics:SNP genotyping, copy number variation analysis, and transcriptome profiling. Academic medical centers anchor demand through NIH-funded infrastructure grants.
- Proteomics:Protein expression profiling and post-translational modification analysis. Multiplexed oncology biomarker panels represent the steepest expansion trajectory as companion diagnostic pathways mature.
- Diagnostics:Clinical-grade assays for infectious disease, oncology, and pharmacogenomics. FDA premarket review timelines compress when co-developed with therapeutic candidates.
- Drug Discovery:Target identification, lead optimization, and toxicogenomics screening. Pharmaceutical companies are outsourcing workflows to contract research organizations, shifting procurement concentration.
Genomics maintains the largest revenue base; Diagnostics is gaining share fastest on companion diagnostic co-development momentum.
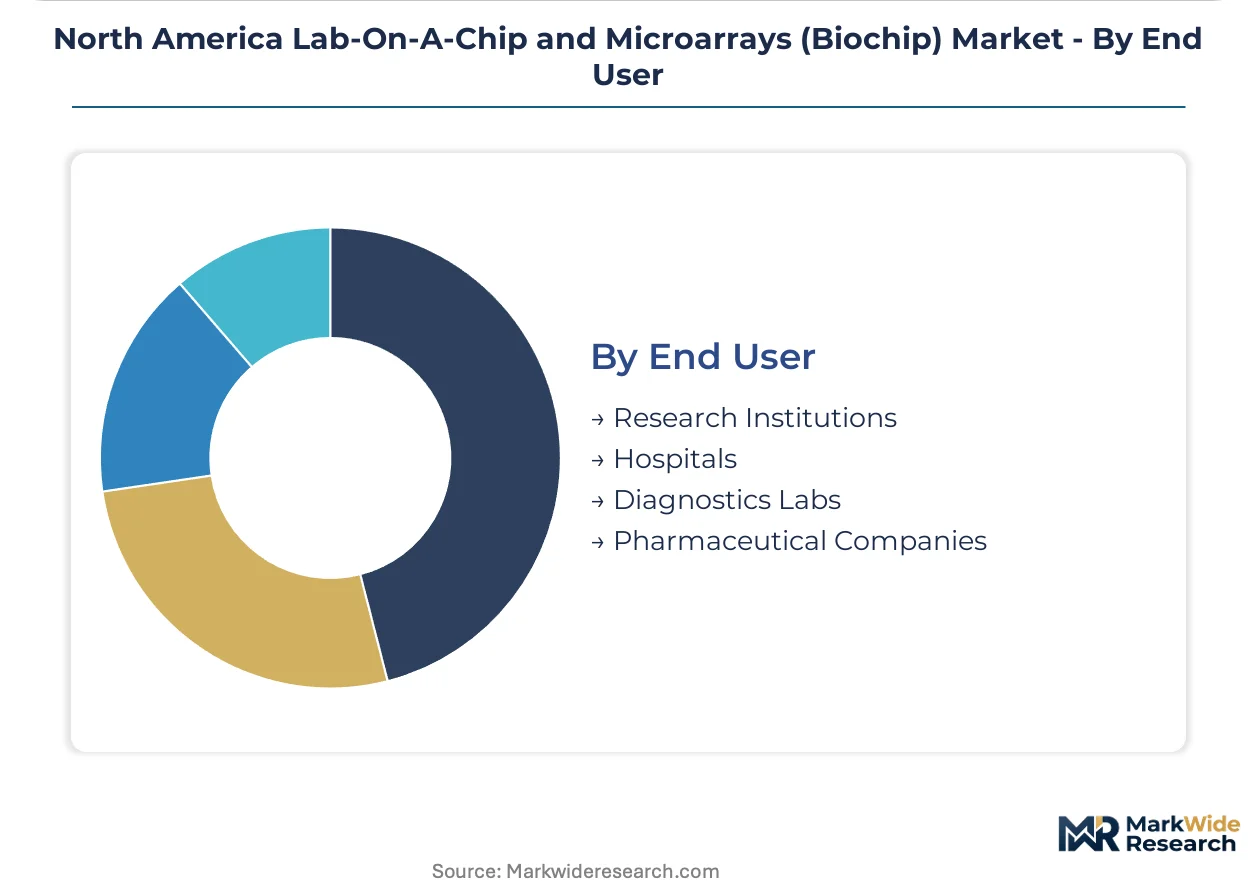
End User:
Procurement authority is migrating from hospital-based diagnostics labs toward integrated delivery networks and pharmaceutical outsourcing partners, restructuring vendor relationship dynamics.
- Research Institutions:University core facilities and academic medical center genomics cores. NIH funding cycles drive capital equipment refresh patterns.
- Hospitals:Clinical laboratories within integrated delivery networks. Northeast United States systems mandate LIS integration and remote diagnostics capabilities as qualification requirements.
- Diagnostics Labs:Independent reference laboratories and hospital-affiliated testing facilities. Consolidating procurement share as standalone buyers lose leverage.
- Pharmaceutical Companies:Internal discovery groups and clinical trial operations. Outsourcing trends to contract research organizations are redirecting capital expenditure toward fee-for-service arrangements.
Research Institutions retain the deepest installed base; Pharmaceutical Companies are shifting procurement fastest toward outsourced models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-95 corridor and cross-border freight rail networks linking the Northeast United States to Ontario and Quebec underwrite North America's biochip manufacturing and distribution architecture. This infrastructure enables just-in-time reagent supply chains and rapid platform deployment across academic medical centers.
United States
NIH-funded precision medicine consortia in Boston-Cambridge and Research Triangle Park drive installed base expansion for high-throughput genomics infrastructure. FDA premarket review under the In Vitro Diagnostics framework compresses clearance timelines for companion diagnostic co-development. The Northeast corridor from Boston to Research Triangle Park concentrates procurement authority among integrated delivery networks.
Canada
Health Canada and the Canadian Standards Association coordinate quality system recognition with FDA, reducing dual-compliance burdens for cross-border suppliers. Parallel regulatory pathways lower market entry costs for US-based platform vendors seeking Health Canada approval. Toronto and Vancouver anchor biotech clusters where academic medical centers adopt point-of-care diagnostic platforms.
Mexico
Maquiladora manufacturing zones near the US border assemble polymer-substrate biochip components for North American supply chains. COFEPRIS regulatory alignment with FDA standards accelerates import registration for diagnostic devices. Guadalajara and Mexico City host emerging clinical research organizations conducting pharmacogenomics screening for pharmaceutical sponsors.
North America Lab-On-A-Chip and Microarrays (Biochip) Market Competitive Landscape
Concentration sits with diversified life science conglomerates and specialized genomic platform developers. The vendor base stratifies across three tiers: integrated reagent-instrument bundlers, high-throughput sequencing specialists, and multimodal detection platform engineers. Strategic moves center on reagent supply chain consolidation and microfluidics technology licensing agreements.
Among diversified life science conglomerates, Thermo Fisher Scientific exemplifies the reagent-instrument bundled model anchoring large-scale workflows. Illumina occupies a dominant position in high-throughput sequencing microarrays through proprietary flow cell chemistry. Agilent Technologies represents the multimodal detection archetype, integrating optical and electrochemical readouts for pharmaceutical screening applications.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| Illumina |
| Bio-Rad Laboratories |
| Danaher Corporation |
| PerkinElmer |
| Abbott Laboratories |
| Merck |
| F. Hoffmann-La Roche |
| Others |
Value Network & Pricing Analysis
Ninety-day substrate inventory buffers at Northeast corridor distributors anchor pricing power for silicon-based biochip producers while compressing margin flexibility for polymer-substrate competitors. This lead-time architecture concentrates procurement leverage among integrated delivery networks qualifying vendors on bundled reagent-instrument platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by optical performance grade and FDA premarket review tier. Premium silicon-substrate arrays command certification premiums for companion diagnostic workflows, while economy polymer alternatives face price erosion from academic buyers with lower sensitivity to detection sensitivity. Pharmaceutical companies and contract research organizations exhibit least price sensitivity due to co-development timeline pressures.
Supply Chain Analysis
Photoresist and etchant chemical supply from Germany, Japan, and the United States creates single-source vulnerability for semiconductor-grade substrate fabrication. Enzyme and fluorescent dye production concentrates among specialty chemical suppliers in Switzerland and the Netherlands, tethering multiplexed assay manufacturers to long-term offtake contracts. Distribution runs through just-in-time reagent networks linking the I-95 corridor to Ontario and Quebec manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic pathway compression at FDA represents a regulatory inflection accelerating platform consolidation in this high-growth molecular diagnostics disruption.
For Market Incumbents: Compound defensive positioning through backward integration into enzyme and fluorescent dye supply chains to neutralize single-source vulnerability. Lock in eighteen-to-twenty-four-month reagent supply contracts with Research Triangle Park and Boston-Cambridge academic medical centers before vendor qualification cycles compress further. Prioritize LIS integration capabilities as table stakes for Northeast corridor integrated delivery network procurement mandates. For New Entrants and Emerging Players: Protein chip oncology panel service-layer gaps expose white space where precision biomarker workflows concentrate higher margins than commoditized DNA genotyping arrays. Target contract research organization fee-for-service procurement as the most penetrable buyer archetype, bypassing eighteen-month hospital qualification barriers. Lead with electrowetting-on-dielectric microfluidics platforms for pharmaceutical toxicogenomics screening applications. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because workflow automation and detection modality convergence favor integrated architectures over consumable-only suppliers. Acquisition targets should display captive microfluidics IP and established Health Canada-FDA parallel quality system recognition. Watch NIH precision medicine consortium funding cycles as the signal for installed base expansion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent-Instrument Bundle Expansion | Thermo Fisher's anchored model locks in large-scale genomics workflows at academic medical centers. |
| Microfluidics Technology Licensing | Electrowetting-on-dielectric platforms decompose liquid-handling robotics in pharmaceutical screening. |
| Companion Diagnostic Co-Development | FDA In Vitro Diagnostics framework compression enables parallel drug-diagnostic pathway acceleration. |
| Canadian Parallel Recognition Pursuit | Health Canada-CSA coordination reduces dual-compliance burdens for cross-border platform vendors. |
| Protein Chip Oncology Panel Development | Precision biomarker workflows capture concentrated margin pools in Northeast corridor hospitals. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with biomedical engineers at academic medical centers, GPO contracts managers at integrated delivery networks, regulatory affairs leads at platform vendors, and procurement directors at contract research organizations. Secondary validation drew from FDA 510(k) filings, Health Canada device licenses, CMS reimbursement code determinations, and NIH precision medicine consortium grant disclosures. Bottom-up installed base modeling triangulated against top-down market sizing across substrate format, detection modality, and end-user concentration dimensions.
Across the analysis window, volume and value outputs reflect segmentation by product architecture, detection chemistry, application workflow, and procurement authority migration patterns. CAGRs derived from replacement cycle analysis of legacy 3' expression arrays, expansion rates for point-of-care diagnostic platforms, and pharmaceutical outsourcing intensity to contract research organizations. Industry-specific inputs captured EPA semiconductor waste stream compliance cost trajectories and CMS multiplexed panel reimbursement pathway evolution.
Material uncertainties — FDA premarket review timeline variability, silicon wafer price volatility, and CMS novel technology add-on payment determinations — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as companion diagnostic co-development pathway maturation and integrated delivery network procurement consolidation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Tissue Engineered Skin Substitute Market
Biomedical Engineering
Bionic Eye Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Bioink Market
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Tissue Engineering Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
3D Bioprinting Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market
Biomedical Engineering
Bioactive Coating Devices Market
Biomedical Engineering
Global Bionics Market