
 Bioprosthetics Market | 2026-2036
Bioprosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Bioprosthetics Market Analysis
Multi-source procurement for biological tissues is pivoting toward vertically integrated supply chains as manufacturers seek traceability and quality assurance. Edwards Lifesciences Corporation anchors its position through captive bovine pericardium processing facilities. Medtronic plc competes by sustaining broad geographic manufacturing footprints across multiple continents. Abbott Laboratories differentiates through specialized cryopreservation technologies that extend tissue viability windows.
Bioprosthetics comprise implantable medical devices fabricated from chemically treated animal tissues or engineered biological matrices, typically cross-linked with glutaraldehyde to reduce immunogenicity while preserving structural integrity for hemodynamic function. These devices primarily serve to replace or repair damaged human tissues without provoking chronic immune responses, with heart valve replacements representing the most established commercial application. Heart valves command the largest revenue share within product type segmentation due to established surgical volumes and premium pricing for transcatheter delivery systems. Vascular grafts represent the fastest-expanding category as endovascular repair protocols displace open surgical techniques in hospital settings. Biomaterials and biological tissues capture disproportionate margin pools compared to synthetic polymeric alternatives, reflecting raw material scarcity and proprietary fixation chemistries.
FDA premarket approval requirements and EMA Medical Device Regulation standards dictate biocompatibility testing protocols and post-market surveillance obligations for tissue-derived implants. ISO 14155 clinical investigation standards further constrain trial design, extending development timelines and elevating capital requirements for market entrants. Stakeholders must monitor evolving FDA guidance on xenograft sourcing and emerging EUDAMED transparency mandates that will reshape competitive disclosure requirements.
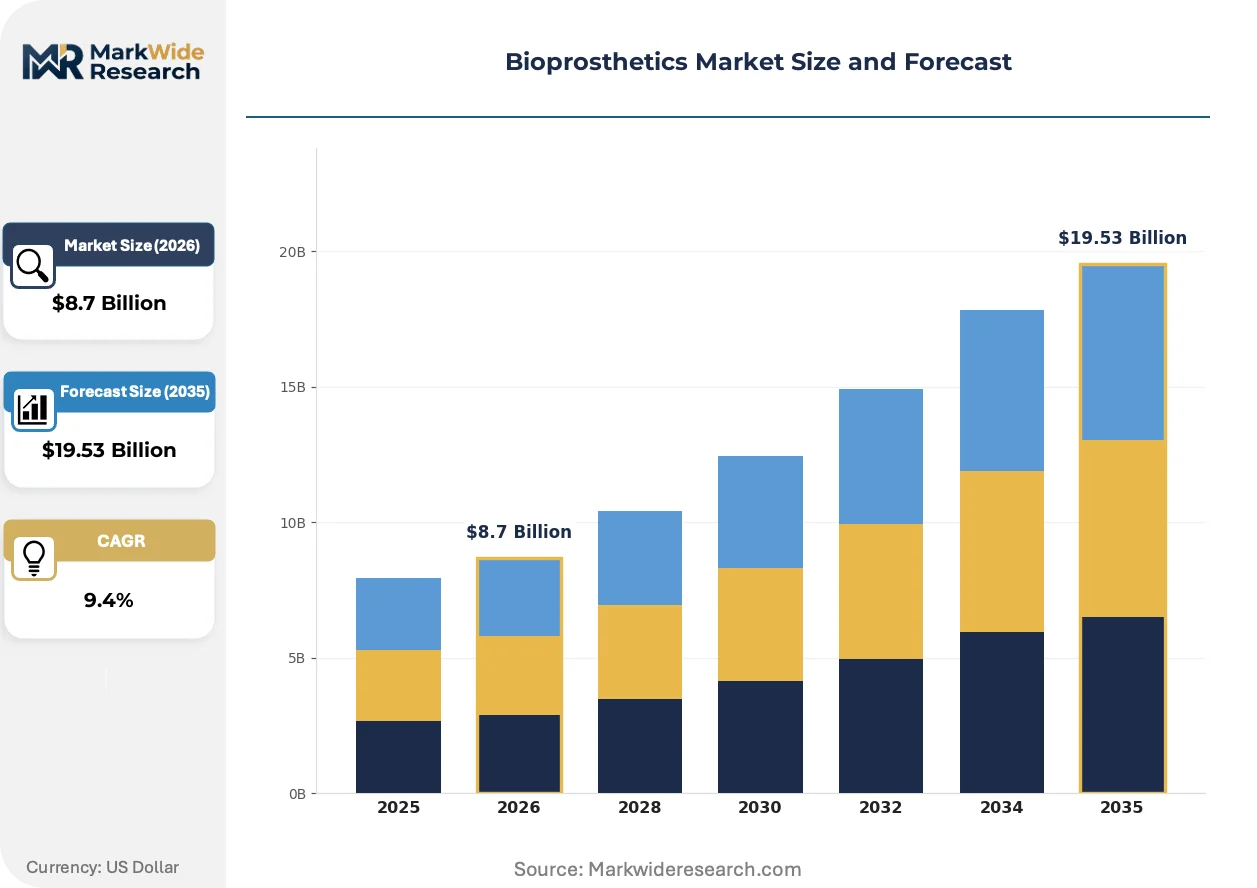
Market Dynamics
Transcatheter delivery systems are compressing surgical volumes for open-heart valve replacement, forcing manufacturers to reallocate R&D budgets toward minimally invasive platforms while maintaining tissue processing capabilities for hybrid surgical approaches.
Growth Catalysts
- EMA Medical Device Regulation harmonization:The MDR's expanded clinical evidence requirements for tissue-based implants create a compliance moat that filters out undercapitalized competitors, consolidating demand among established suppliers with dedicated regulatory affairs infrastructure.
- Aging demographics in Germany and Japan:Population cohorts over 75 years drive structural heart disease prevalence, expanding the addressable patient pool for aortic valve replacement procedures in hospital systems with established cardiac surgery departments.
- Glutaraldehyde cross-linking refinements:Advanced fixation chemistries extend bioprosthetic valve durability beyond 15 years, reducing reoperation rates and improving long-term cost-effectiveness metrics for hospital value analysis committees.
Market Restraints
- Bovine pericardium supply concentration:Premium tissue sourcing depends on captive herds in Australia and New Zealand, exposing processors to veterinary health regulations and climate-related pasture disruptions that constrain raw material availability.
- FDA premarket approval timelines:The PMA pathway for novel bioprosthetic designs demands multi-year clinical investigations under ISO 14155 standards, extending capital lockup periods and deterring early-stage investment in breakthrough configurations.
- Mechanical valve substitution in younger patients:Improved anticoagulation management protocols and patient preference for permanent solutions limit bioprosthetic penetration among demographics under 60 years, capping volume in specific age segments.
Strategic Opportunities
- Underpenetrated cardiac centers in India:CDSCO regulatory alignment with international standards enables multinational manufacturers to establish localized tissue processing partnerships, capturing demand from expanding private hospital networks in Mumbai and Delhi.
- Pulmonary valve reconstruction in pediatric congenital repair:Specialized cryopreserved homograft applications address unmet needs in children's hospitals, commanding premium pricing for customized sizing and extended viability windows.
- EU Green Deal biomedical waste mandates:Circular economy requirements for surgical byproduct disposal incentivize investment in closed-loop tissue recovery systems that reduce environmental liability while securing traceable supply chains.
Industry Challenges
- Biocompatibility testing capacity constraints:ISO 10993 cytotoxicity and sensitization studies face backlog at certified laboratories, delaying submission packages and compressing launch windows for competitive product introductions.
- Integration complexity with hybrid OR infrastructure:Transcatheter bioprosthetic deployment requires coordination between imaging systems, catheter labs, and surgical suites, demanding capital expenditure that strains hospital capital allocation committees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioprosthetics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Valves, Vascular Grafts, Orthopedic Implants, Surgical Meshes Material: Biomaterials, Collagen, Biological Tissues, Synthetic Polymeric End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Application: Cardiovascular, Orthopedic, Dental, General Surgery |
| Companies Covered | Edwards Lifesciences Corporation, Medtronic plc, Abbott Laboratories, LivaNova PLC, Boston Scientific Corporation, Artivion, Inc., LeMaitre Vascular, Inc., Braile Biomédica, Inc., Labcor Laboratórios Ltda., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioprosthetics Market Emerging Trajectories
Computational modeling and additive manufacturing are converging to enable patient-specific bioprosthetic geometries, while regulatory agencies accelerate pathways for breakthrough device designation in structural heart applications.
Decellularized xenograft matrices treated with detergent-based cell removal protocols are absorbing the functional requirements previously met by chemically fixed native tissues. Cardiac surgery departments at academic medical centers in the United States and Germany are piloting these scaffolds for complex reconstruction cases where standard commercial sizes prove inadequate. The technology is absorbing development resources from conventional glutaraldehyde fixation programs as manufacturers anticipate future immunogenicity standards that may restrict current processing methods.
REACH authorization requirements for glutaraldehyde handling are tightening occupational exposure limits across European manufacturing facilities. The ECHA regulatory pressure forces processors to invest in closed-system chemistry containment or substitute alternative cross-linking agents, elevating production costs for tissue fixation operations. Vascular graft manufacturers with facilities in Ireland and the Netherlands face the most acute compliance timelines as national enforcement agencies align inspection protocols with the 2023 delegated act amendments.
Hospital procurement committees are consolidating bioprosthetic purchasing through single-source agreements that bundle valve, graft, and repair patch categories. Cardiovascular service line directors at integrated delivery networks in Texas and California are displacing traditional distributor relationships with direct manufacturer contracts that include consignment inventory and procedural utilization guarantees. This concentration is most visible in Medicare Advantage–dominated markets where episode-based reimbursement creates incentive alignment between implant cost and total procedural spend.
Bioprosthetics Market Segmentation
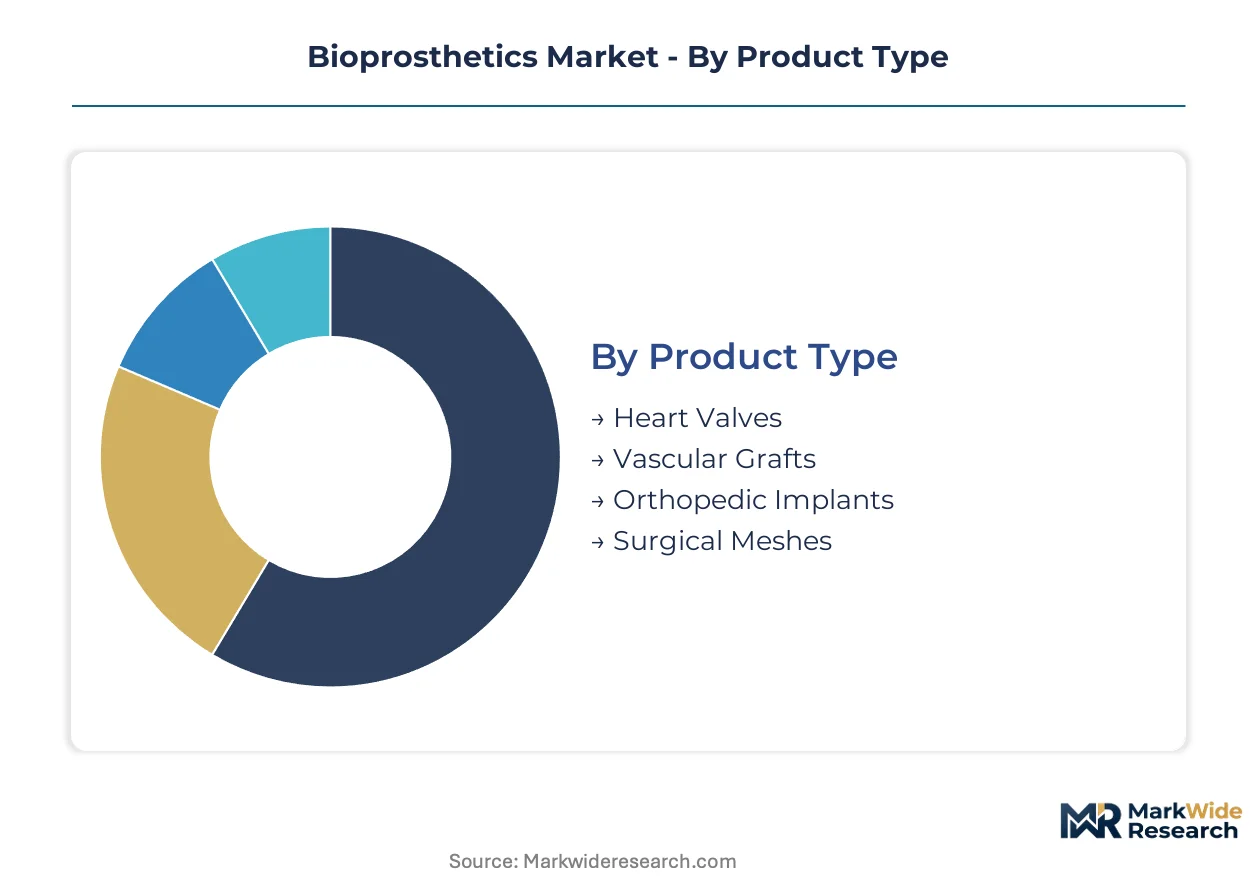
Segmentation in bioprosthetics reveals how tissue sourcing, procedural setting, and anatomical application shape procurement patterns and margin structures across the value chain. Manufacturers configure product portfolios around specific fixation chemistries and delivery modalities that match distinct clinical workflows.
Product Type:
Standalone implantable devices dominate revenue concentration, while combination products embedding bioprosthetic components within delivery systems are reshaping competitive positioning.
- Heart Valves:Chemically fixed bovine pericardium or porcine aortic tissue cross-linked with glutaraldehyde forms the structural leaflets. Demand concentrates in United States hospital cardiac surgery departments where transcatheter delivery systems command premium pricing against conventional surgical valves.
- Vascular Grafts:Tubular constructs from decellularized biological matrices or synthetic-biological hybrids enable endovascular aneurysm repair. German and Japanese vascular surgery units are expanding utilization as minimally invasive protocols displace open reconstruction techniques.
- Orthopedic Implants:Meniscal allografts and tendon scaffolds processed through cryopreservation or lyophilization protocols.
- Surgical Meshes:Cross-linked collagen or biological tissue matrices for hernia repair and pelvic floor reconstruction.
Heart valves lead volumes today; vascular grafts are gaining share fastest.
Material:
Cost tier stratification separates premium biological matrices from commodity synthetic alternatives, with proprietary processing chemistries capturing disproportionate margin pools.
- Biomaterials:Engineered extracellular matrix scaffolds and recombinant protein constructs produced through bioreactor cultivation. United States academic medical centers in Boston and Cleveland are piloting these materials for complex cardiac reconstructions where standard xenografts prove inadequate.
- Collagen:Purified type I collagen from bovine or porcine dermis processed into sheets, sponges, or injectable formulations. Wound care centers and plastic surgery clinics in California and Texas are absorbing expanded supply as manufacturers diversify beyond cardiovascular applications.
- Biological Tissues:Chemically fixed or cryopreserved allograft and xenograft tissues including pericardium, dermis, and small intestinal submucosa.
- Synthetic Polymeric:Polytetrafluoroethylene and polyester fabrics competing in price-sensitive vascular and hernia repair segments.
Biological tissues dominate current revenue; biomaterials show the steepest expansion trajectory.
End User:
Customer type segmentation tracks capital intensity requirements, with integrated delivery networks consolidating purchasing power against fragmented outpatient settings.
- Hospitals:Tertiary cardiac surgery centers and academic medical institutions performing complex valve replacements and aortic reconstructions. Medicare reimbursement structures in the United States and statutory health insurance frameworks in Germany sustain procedural volumes through established DRG and EBM coding systems.
- Ambulatory Surgical Centers:Freestanding facilities performing low-acuity hernia repairs and minor orthopedic procedures. Texas and Florida regulatory environments permit expanded scope-of-practice protocols that are absorbing volume migration from hospital outpatient departments.
- Specialty Clinics:Cardiovascular and orthopedic focused practices performing diagnostic and minor interventional procedures.
- Research Laboratories:Academic and commercial R&D facilities conducting biocompatibility testing and preclinical validation studies.
Hospitals retain the dominant share; ambulatory surgical centers are expanding most quickly.
Application:
Anatomical application segmentation aligns with regulatory pathway complexity, with cardiovascular indications commanding the most stringent premarket approval requirements.
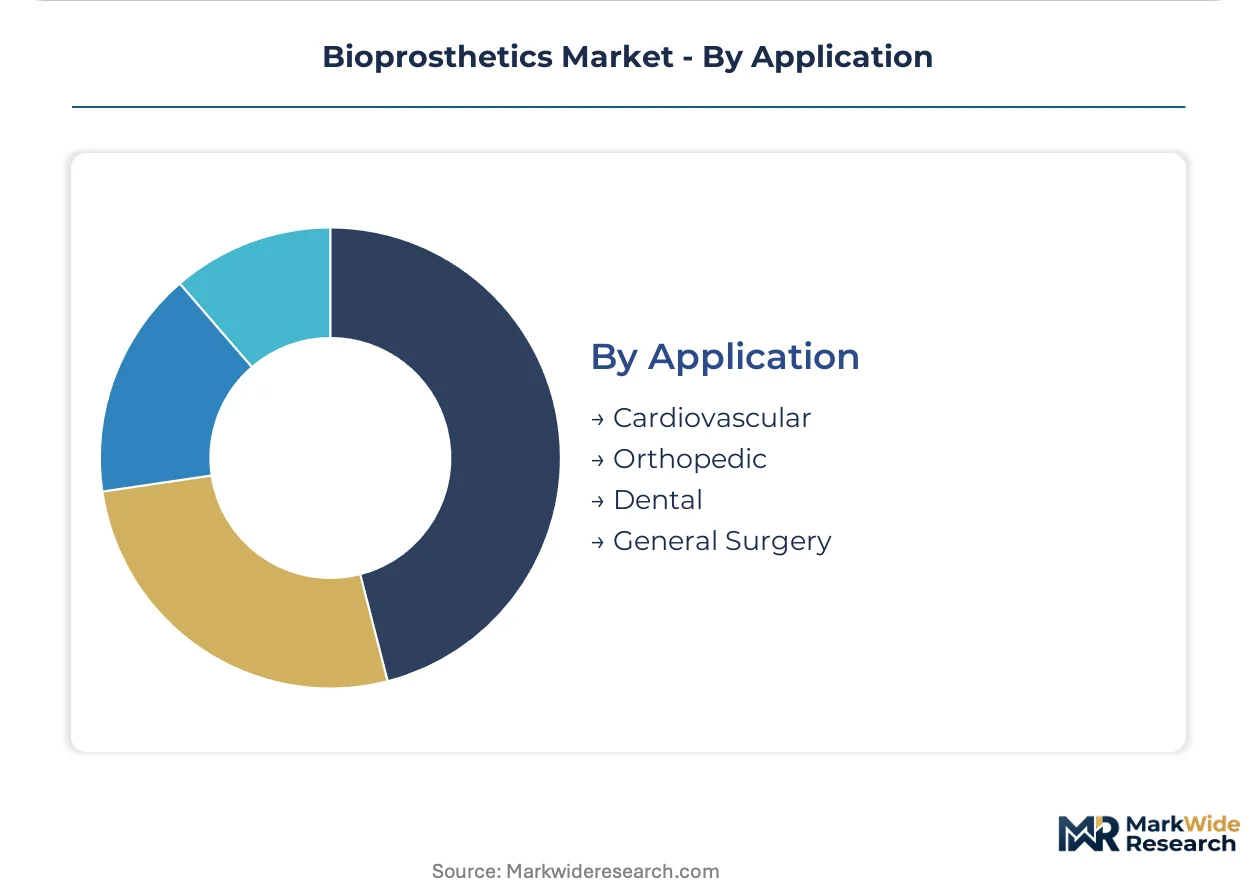
- Cardiovascular:Aortic, mitral, pulmonary, and tricuspid valve replacements plus aortic arch and peripheral vascular reconstructions. FDA premarket approval and EMA MDR conformity assessment procedures create compliance barriers that filter market participation toward established manufacturers with dedicated regulatory infrastructure.
- Orthopedic:Meniscal, ligament, and tendon reconstructions using allograft or xenograft tissues. Sports medicine practices in Australia and specialized orthopedic centers in Germany are driving demand as active aging demographics expand the candidate pool for biological joint preservation procedures.
- Dental:Ridge augmentation and periodontal regeneration using collagen membranes and mineralized bone substitutes.
- General Surgery:Hernia repair, pelvic floor reconstruction, and wound management applications.
Cardiovascular leads application revenue; orthopedic is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac surgery centers in the United States absorb the largest share of bioprosthetic valve procedures, with Medicare reimbursement structures sustaining hospital investment in transcatheter delivery infrastructure.
United States
Aging demographics and established DRG coding for heart valve replacements drive procedural volumes at tertiary cardiac centers. FDA premarket approval pathways shape product development timelines for tissue-based implants. Academic medical clusters in Boston and Cleveland pilot decellularized xenograft matrices for complex reconstructions.
Germany
Statutory health insurance frameworks through EBM coding sustain demand for aortic valve replacements among patients over 75 years. EMA Medical Device Regulation harmonization creates compliance barriers that filter market participation toward established suppliers. Vascular surgery units in Baden-Württemberg expand endovascular aneurysm repair protocols using biological grafts.
Japan
Population cohorts exceeding 75 years expand the candidate pool for structural heart interventions at specialized cardiac institutions. PMDA consultation procedures align with international standards for xenograft biocompatibility testing. Tokyo and Osaka metropolitan hospital networks concentrate procurement of cryopreserved homografts for pediatric congenital repairs.
India
Private hospital networks in Mumbai and Delhi scale cardiac surgery departments to serve affluent patient segments seeking valve replacement procedures. CDSCO regulatory alignment with international standards enables multinational manufacturers to establish localized tissue processing partnerships. Maharashtra and Karnataka host emerging distribution hubs for biological tissue procurement.
Australia
Captive bovine herds in Queensland and New South Wales supply premium pericardium raw materials to global processors. TGA conformity assessment procedures govern import and distribution of xenograft-derived implants. Brisbane tissue processing facilities face climate-related pasture disruption risks that constrain raw material availability seasons.
Bioprosthetics Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized cryopreservation and decellularized matrix applications. The vendor base concentrates among cardiovascular-focused conglomerates with dedicated regulatory affairs infrastructure and captive tissue supply chains. Three archetypes dominate: integrated tissue processors controlling raw material sourcing, diversified medical technology conglomerates leveraging distribution scale, and regional specialists serving price-sensitive emerging markets. Competitive moves center on backward integration into biological tissue sourcing and strategic partnerships with academic medical centers for clinical validation.
Among United States-based enterprises, Edwards Lifesciences Corporation and Abbott Laboratories exemplify the integrated processor archetype through captive supply chain control and specialized fixation technologies. Medtronic plc, organized under Irish jurisdiction, represents the diversified conglomerate model with broad geographic manufacturing footprints. These three anchors demonstrate how regulatory compliance infrastructure and tissue processing capabilities create sustainable competitive position in a market shaped by FDA and EMA quality mandates.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Medtronic plc |
| Abbott Laboratories |
| LivaNova PLC |
| Boston Scientific Corporation |
| Artivion, Inc. |
| LeMaitre Vascular, Inc. |
| Braile Biomédica, Inc. |
| Labcor Laboratórios Ltda. |
| Others |
Supply Flow & Price Mechanics
Captive bovine pericardium sourcing in Australia and New Zealand anchors pricing power for integrated processors while exposing spot-market buyers to raw material volatility and veterinary health regulation shifts. Edwards Lifesciences Corporation and Abbott Laboratories leverage in-house tissue processing to command premium positioning for transcatheter delivery systems against competitors dependent on third-party supply.
Pricing Analysis
Input-cost pass-through from biological tissue scarcity drives contract-based long-term offtake agreements between manufacturers and captive herd operators. Price differentiation rests on FDA premarket approval tier and proprietary glutaraldehyde fixation chemistry, with transcatheter valve systems capturing substantial premiums over surgical alternatives. Cost compression in standard surgical valves is intensifying as hospital procurement committees consolidate purchasing through single-source agreements. Ambulatory surgical centers exhibit highest price sensitivity due to episode-based reimbursement constraints, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from FDA and EMA regulators mandate multi-supplier qualification for biological tissues, forcing manufacturers to maintain redundant processing relationships across Australia, New Zealand, and United States facilities. Raw material dependencies center on bovine pericardium, porcine aortic tissue, and cryopreservation media formulations. Single-source vulnerability concentrates in Queensland and New South Wales captive herds exposed to climate-related pasture disruption. Distribution runs through direct manufacturer contracts with integrated delivery networks, displacing traditional distributor relationships in Medicare Advantage–dominated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from EMA Medical Device Regulation compliance costs in Europe versus CDSCO-aligned regulatory pathways in India, enabling cost-advantaged tissue processing partnerships for multinational expansion.
For Market Incumbents: Deepen backward integration into biological tissue sourcing through captive herd investments in Australia to defend against supply concentration risk from climate-related pasture disruptions. Expand cryopreservation technology R&D to differentiate from emerging decellularized matrix substitutes threatening glutaraldehyde fixation market share.
For New Entrants and Emerging Players: Launch via specialized cryopreserved homograft distribution partnerships with children's hospitals in Tokyo and Osaka, where pediatric congenital repair applications command premium pricing and face limited incumbent competition. Target pulmonary valve reconstruction as the most penetrable segment, leveraging customized sizing capabilities and extended viability windows unavailable from standard commercial xenografts.
For Investors and Strategic Acquirers: Roll-up economics work for regional tissue processing specialists because EMA MDR compliance barriers filter out undercapitalized competitors and consolidate demand among established suppliers with dedicated regulatory infrastructure. Long-term viability centers on platform scale across fixation chemistry, tissue sourcing, and delivery system integration. Watch FDA guidance evolution on xenograft sourcing transparency as the inflection indicator for competitive disclosure requirements reshaping valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tissue Sourcing | Captive bovine herds in Australia secure traceable supply chains against climate-related raw material disruption. |
| CE Marking Pathway Investment | EMA MDR compliance infrastructure creates competitive moats filtering out undercapitalized market entrants. |
| Hospital System Partnership | Direct contracts with Texas and California integrated delivery networks displace distributor relationships through consignment inventory models. |
| Reimbursement Strategy Development | Medicare DRG coding alignment sustains procedural volumes for transcatheter valve replacement at tertiary cardiac centers. |
| Software Companion Development | Computational modeling platforms enable patient-specific bioprosthetic geometries for complex reconstruction cases. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cardiac surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation from FDA premarket approval filings, EMA MDR submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis were triangulated to anchor market sizing.
Segment-weighting approaches modeled cardiovascular, orthopedic, dental, and general surgery applications across biomaterials, collagen, biological tissues, and synthetic polymeric materials, with end-user stratification across hospitals, ambulatory surgical centers, specialty clinics, and research laboratories. CAGRs were derived from procedure volume trajectories and pricing trend analysis, incorporating aging demographic projections and regulatory pathway timelines as industry-specific forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA REACH authorization amendments tightening glutaraldehyde occupational exposure limits. Deviation in bovine pericardium supply availability from Australian climate events would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
Tissue Expansion Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
3D Bioprinting Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
Tissue Engineering Market
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Bio-Engineered Stent Market