
 Global Biomedical Tester Market | 2026-2036
Global Biomedical Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biomedical Tester Market Foresight
Hospital procurement channels is tilting toward bundled service contracts that combine equipment placement with consumable lock-in. Fluke Biomedical leverages its calibration heritage to dominate preventive maintenance agreements. Rigel Medical competes through portable electrical safety tester lines that target point-of-care installations. BC Group International anchors its position with anesthesia and ventilator analyzer specialization that reduces total cost of ownership for mid-sized hospitals.
A biomedical tester is an instrument that validates, calibrates, or verifies the performance of medical devices and diagnostic equipment against established safety and accuracy parameters, typically measuring electrical safety, gas flow, pressure, or optical density with traceable standards. Its primary purpose is to ensure clinical devices operate within manufacturer specifications and regulatory tolerances before patient contact. Hematology analyzers and immunoassay systems occupy the deepest installed bases, while molecular diagnostics equipment captures the fastest replacement cycle as PCR throughput demands intensify. Flow cytometry and spectrophotometry technologies concentrate margin pools in reagent-locked platforms that generate recurring revenue streams beyond initial hardware placement.
FDA premarket notification requirements under 21 CFR Part 820, the EU Medical Device Regulation's Class IIa classification for active diagnostic devices, and China's NMPA technical review standards for in vitro diagnostic instruments collectively elevate validation documentation burdens for market entry. These frameworks compel manufacturers to embed automated self-test routines and electronic record-keeping into new platform designs. Stakeholders must monitor how divergent cybersecurity addenda across FDA, EMA, and NMPA guidance documents reshape firmware update obligations and post-market surveillance costs.
Market Dynamics
Hospital procurement departments now mandate bundled service contracts that fuse equipment placement with consumable lock-in, compressing vendor margins while extending customer lifetime value through reagent-locked platforms. This structural pivot favors incumbents with calibration heritage and preventive maintenance infrastructure over pure-play hardware suppliers.
Growth Catalysts
- EU Medical Device Regulation (MDR):The MDR's Class IIa classification for active diagnostic devices elevates validation documentation burdens, compelling manufacturers to embed automated self-test routines into new platform designs.
- Molecular diagnostics throughput demands:PCR intensification is shortening replacement cycles for testing equipment, creating recurring hardware refresh opportunities in centralized laboratory infrastructure.
- China's NMPA technical review standards:Tightened quality mandates for in vitro diagnostic instruments are accelerating procurement of automated hematology and immunoassay platforms in tier-one hospital networks.
Market Restraints
- Specialized component concentration:Precision optical sensors and traceable calibration gases concentrate supply among German and Japanese specialty chemical suppliers, exposing buyers to input cost volatility.
- Firmware update obligations:Divergent cybersecurity addenda across FDA, EMA, and NMPA guidance documents inflate post-market surveillance costs and complicate multi-territory product launches.
- Service contract lock-in:Bundled preventive maintenance agreements with consumable minimums raise total cost of ownership for mid-sized diagnostic laboratories with limited capital budgets.
Strategic Opportunities
- Point-of-care electrical safety testing:Portable analyzer demand in decentralized clinical settings creates white space for battery-operated, wireless-enabled validation tools outside centralized laboratory infrastructure.
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing of diagnostic equipment reduce import dependency and open procurement channels for localized service networks.
- Cloud-connected validation platforms:Convergence of IoT telemetry with electronic record-keeping enables predictive maintenance models that shift revenue from hardware sales to subscription-based uptime guarantees.
Industry Challenges
- Metrology technician scarcity:Specialized calibration expertise for electrical safety and gas flow analyzers concentrates in aging workforces, constraining service expansion into secondary hospital markets.
- Legacy system integration friction:New automated platforms must interface with hospital information systems running decade-old middleware, extending deployment timelines and inflating implementation costs.
- Multi-territory certification timelines:Sequential FDA 510(k), CE marking, and NMPA registration processes delay commercialization by 18-24 months for novel analyzer technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biomedical Tester Market |
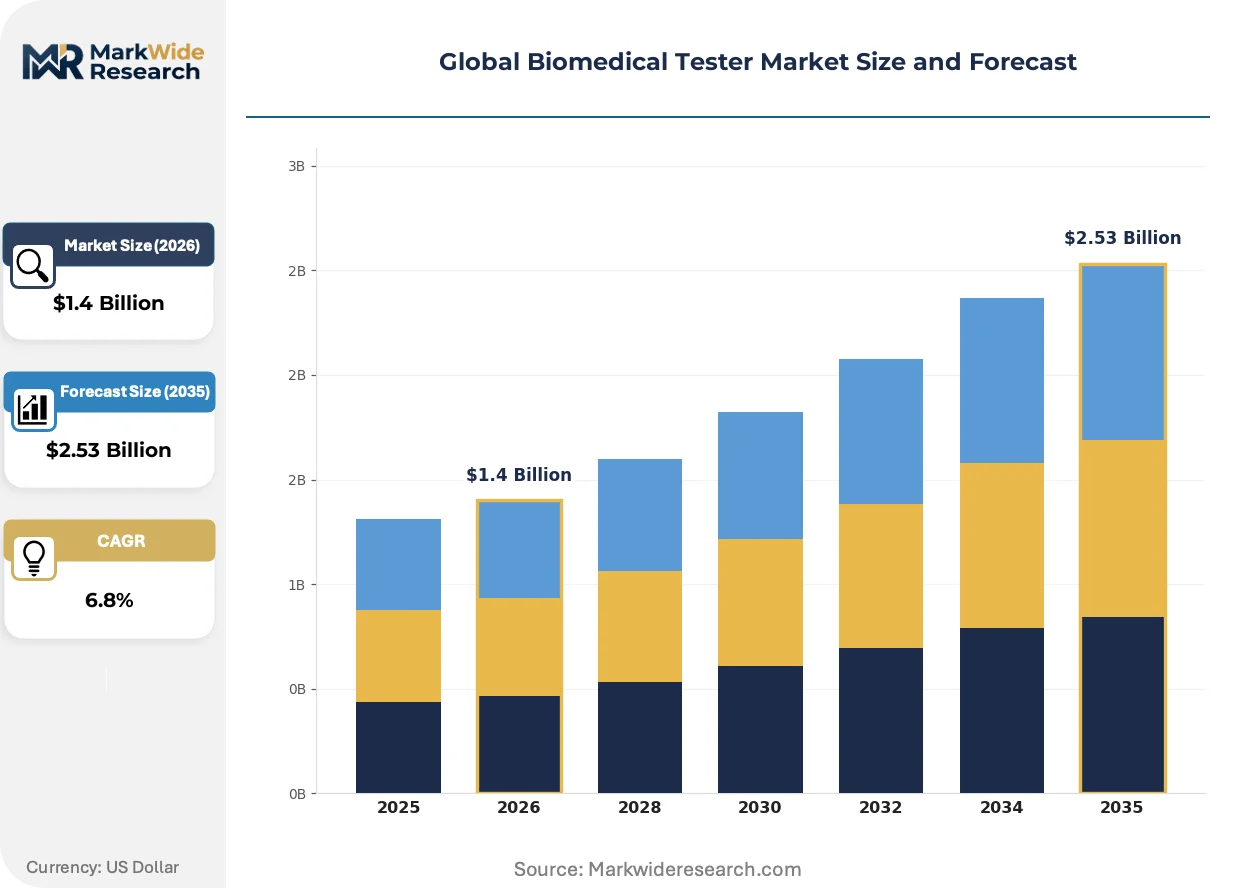
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hematology Analyzer, Immunoassay System, Clinical Chemistry Analyzer, Molecular Diagnostics Equipment, Microbiology Tester Application: Blood Screening, Infectious Disease Detection, Genetic Testing, Drug Development, Quality Control End User: Hospitals, Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies, Biotechnology Firms Technology: Flow Cytometry, PCR Amplification, Spectrophotometry, Immunofluorescence, Electrophoresis |
| Companies Covered | Fluke Biomedical, Rigel Medical, BC Group International, Datrend Systems, Seaward Electronic, Netech, Dynatech CBET, Southeastern Biomedical, Presto Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biomedical Tester Market Shifts & Advancements
Wireless-enabled portable analyzers are redrawing competitive boundaries between centralized laboratory equipment and point-of-care validation tools. Firmware architectures now embed automated compliance documentation as a native feature rather than aftermarket add-on.
Cloud-native calibration management systems aggregate instrument performance data across hospital networks, enabling predictive failure detection before patient safety parameters drift out of tolerance. Large health systems in the United States and Germany are adopting these platforms fastest, compressing preventive maintenance intervals from quarterly to continuous monitoring. This capability is rendering obsolete the traditional break-fix service model that dominated biomedical tester aftermarket revenue.
The FDA's evolving premarket review pathways under 21 CFR Part 820 now explicitly incorporate cybersecurity validation as a gate for in vitro diagnostic device clearance. Manufacturers must demonstrate secure firmware update mechanisms and vulnerability disclosure protocols before commercial authorization. Hematology and immunoassay platforms with network-connected self-test routines face the steepest compliance documentation requirements.
Diagnostic laboratory procurement committees now evaluate total cost of ownership over seven-year horizons rather than upfront capital expenditure alone. Reagent-locked platforms with captive consumable supply contracts displace open-system analyzers in competitive tenders. This pattern concentrates purchasing authority in Germany, China, and the United States where centralized laboratory infrastructure scales justify long-term vendor commitments.
Global Biomedical Tester Market Segmentation
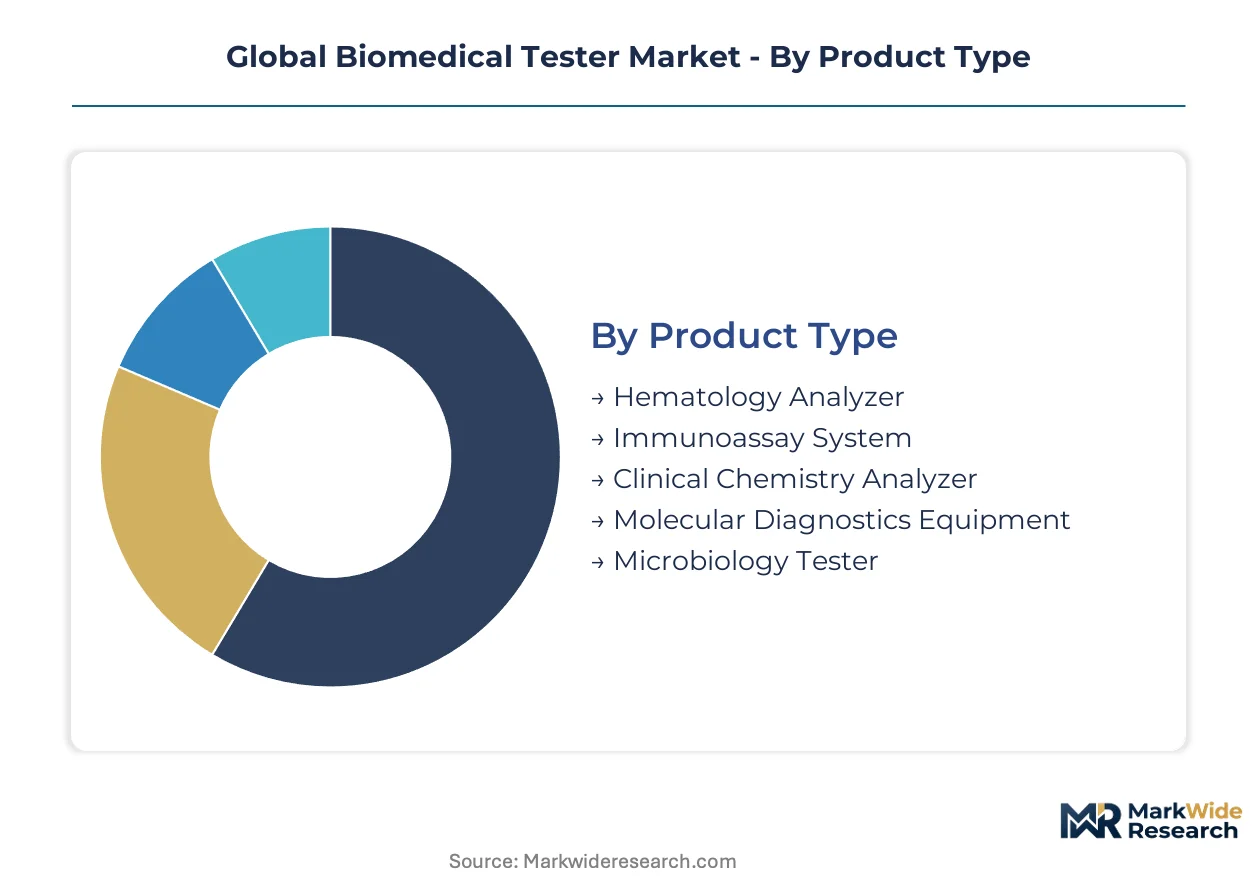
Biomedical tester segmentation reveals how procurement committees balance throughput requirements against total cost of ownership calculations. Equipment categories cluster around hematology and immunoassay platforms with deep installed bases, while molecular diagnostics commands premium replacement cycles driven by PCR intensification.
Product Type:
Use-case spectrum spans high-volume screening platforms to specialized genetic analysis instruments with divergent margin profiles and service contract structures.
- Hematology Analyzer:Automated cell counting platforms measure blood components using impedance and optical scatter methods. Demand concentrates in United States and Chinese hospital networks where centralized laboratory infrastructure scales justify seven-year total cost of ownership contracts with reagent lock-in provisions.
- Molecular Diagnostics Equipment:PCR and nucleic acid amplification systems detect genetic markers with traceable thermal cycling precision. Replacement cycles compress in German diagnostic laboratories as throughput demands intensify, creating recurring hardware refresh opportunities independent of equipment failure rates.
- Immunoassay System:Antibody-antigen detection platforms with chemiluminescence readouts dominate infectious disease and hormone testing workflows.
- Clinical Chemistry Analyzer:Enzymatic and ion-selective electrode systems process routine metabolic panels with standardized calibration protocols.
- Microbiology Tester:Automated culture and susceptibility systems accelerate bacterial identification in antimicrobial stewardship programs.
Established volume favors hematology analyzers; emerging adoption favors molecular diagnostics equipment.
Application:
Customer workflows range from regulatory-mandated screening programs to research-phase drug candidate validation with distinct compliance documentation burdens.
- Blood Screening:Donor testing protocols detect infectious agents and blood group antigens using serological and nucleic acid methods. Procurement in United States blood centers follows FDA 21 CFR Part 820 quality system requirements with embedded automated self-test routines.
- Infectious Disease Detection:Pathogen identification platforms combine PCR amplification with immunofluorescence confirmation for syndromic panels. Chinese tier-one hospitals accelerate procurement under tightened NMPA technical review standards for in vitro diagnostic instruments.
- Genetic Testing:Carrier screening and pharmacogenomic analysis platforms process targeted gene panels with variant classification protocols.
- Drug Development:Biomarker quantification systems support clinical trial endpoints with GLP-compliant documentation trails.
- Quality Control:Manufacturing release testing validates reagent batch consistency against master reference standards.
Regulatory volume anchors blood screening; pipeline investment drives infectious disease detection.
End User:
Capital deployment capacity separates centralized laboratory networks from distributed point-of-care installations with divergent service contract preferences.
- Hospitals:Acute care networks integrate multi-platform testing with electronic medical record systems and automated specimen tracking. Bundled service contracts with consumable minimums raise total cost of ownership concerns for mid-sized United States facilities with limited capital budgets.
- Diagnostic Laboratories:Independent reference labs and hospital outreach programs concentrate high-throughput testing in automated platforms. German laboratory networks adopt cloud-native calibration management systems fastest, compressing preventive maintenance intervals from quarterly to continuous monitoring.
- Research Institutes:Academic medical centers deploy flexible open-system analyzers for protocol development and grant-funded studies.
- Pharmaceutical Companies:Contract research organizations and sponsor laboratories validate companion diagnostic assays for regulatory submission packages.
- Biotechnology Firms:Cell therapy and gene editing developers implement in-process testing with rapid turnaround requirements.
Service contract scale favors hospitals; platform flexibility favors diagnostic laboratories.
Technology:
Detection modalities range from light-scatter cell sorting to electric field separation with distinct consumable revenue profiles and technician skill requirements.
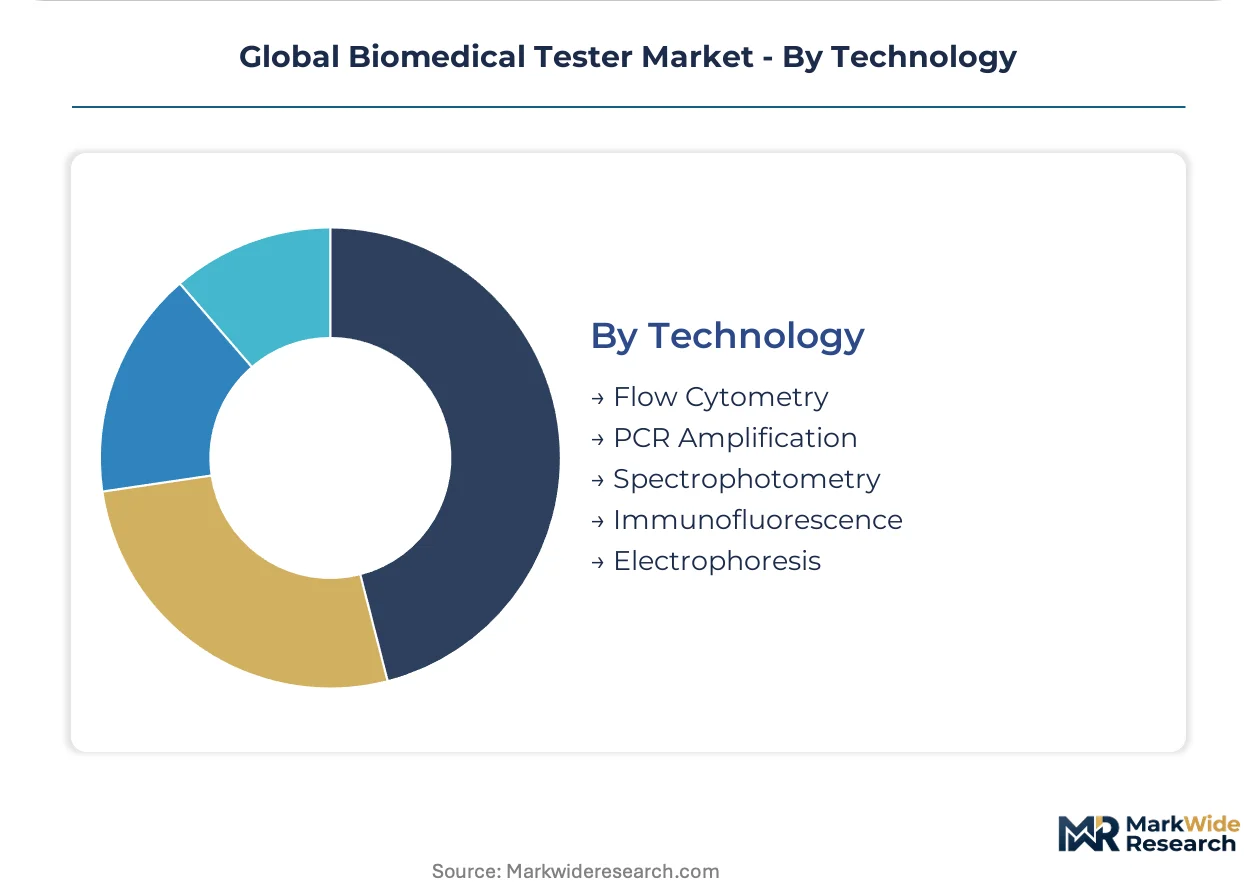
- Flow Cytometry:Laser-based cell sorting platforms quantify surface and intracellular markers with multi-parameter fluorescence detection. Margin pools concentrate in reagent-locked platforms that generate recurring revenue streams beyond initial hardware placement in United States cancer centers.
- PCR Amplification:Thermal cycling systems amplify DNA sequences with real-time fluorescence monitoring for quantitative analysis. Throughput demands in Chinese infectious disease programs drive fastest replacement cycles as platform specifications evolve.
- Spectrophotometry:UV-visible absorbance systems quantify analyte concentrations with Beer-Lambert law calibration curves.
- Immunofluorescence:Antibody-conjugated fluorophore detection enables cellular and tissue-based diagnostic applications.
- Electrophoresis:Electric field separation resolves nucleic acid fragments and protein mixtures by size and charge.
Reagent lock-in sustains flow cytometry; throughput scaling drives PCR amplification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives for domestic manufacturing are reshaping procurement patterns across major diagnostic equipment markets. Regulatory tightening in the United States, Germany, and China accelerates validation documentation burdens while expanding centralized laboratory infrastructure.
United States
FDA premarket notification requirements under 21 CFR Part 820 elevate cybersecurity validation as a clearance gate for in vitro diagnostic devices. Large health systems in Greater Boston and the Pacific Northwest adopt cloud-native calibration management systems fastest, compressing preventive maintenance intervals from quarterly to continuous monitoring. Hospital procurement committees now evaluate total cost of ownership over seven-year horizons.
Germany
The EU Medical Device Regulation's Class IIa classification for active diagnostic devices compels manufacturers to embed automated self-test routines into new platform designs. Diagnostic laboratory networks in Bavaria and Baden-Württemberg concentrate margin pools in reagent-locked platforms that generate recurring revenue streams. German specialty chemical suppliers dominate precision optical sensors and traceable calibration gases.
China
NMPA technical review standards for in vitro diagnostic instruments tighten quality mandates across tier-one hospital networks. PCR intensification in the Yangtze River Delta and Pearl River Delta shortens replacement cycles for molecular diagnostics equipment. Tier-one cities scale centralized laboratory infrastructure while procurement shifts toward bundled service contracts with consumable minimums.
India
PLI scheme incentives for domestic manufacturing of diagnostic equipment reduce import dependency and open procurement channels for localized service networks. Maharashtra and Karnataka host emerging clusters of contract manufacturers serving hospital networks in Delhi-NCR. Mid-sized diagnostic laboratories face total cost of ownership pressures from service contract lock-in structures.
Japan
METI industrial standards and PMDA quality system requirements shape validation protocols for hematology and immunoassay platforms. The Kanto region around Tokyo anchors demand for automated cell counting platforms with impedance and optical scatter methods. Aging metrology technician workforces constrain service expansion into secondary hospital markets.
Global Biomedical Tester Market Competitive Landscape
On the supply side, the industry is consolidating around calibration heritage and preventive maintenance infrastructure rather than pure-play hardware supply. Incumbents with bundled service contract capabilities capture extended customer lifetime value through reagent-locked platforms. Three archetypes dominate: heritage calibration specialists, portable analyzer innovators, and anesthesia-ventilator specialists. M&A activity concentrates on service network expansion and cloud-connected validation platform acquisitions.
Within the heritage calibration tier, Fluke Biomedical anchors positioning through decades of metrology expertise and preventive maintenance agreement scale. Rigel Medical and BC Group International occupy complementary positions—Rigel exemplifies portable electrical safety testing specialization for point-of-care installations, while BC Group represents anesthesia and ventilator analyzer concentration that reduces total cost of ownership for mid-sized hospitals. These three entities collectively illustrate how service contract bundling and consumable lock-in reshape competitive boundaries.
| Leading Market Players |
|---|
| Fluke Biomedical |
| Rigel Medical |
| BC Group International |
| Datrend Systems |
| Seaward Electronic |
| Netech |
| Dynatech CBET |
| Southeastern Biomedical |
| Presto Group |
| Others |
Supply & Pricing Matrix
German and Japanese specialty chemical suppliers dominate precision optical sensors and traceable calibration gases, anchoring margin pools in reagent-locked platforms downstream. This upstream concentration transfers pricing power to consumable-locked vendors while exposing mid-sized diagnostic laboratories to input cost volatility.
Pricing Analysis
Volume-discount tiering structures separate enterprise health systems from mid-sized diagnostic laboratories in contract negotiations. Three-tier pricing stratification across premium certified, standard validated, and economy basic levels reflects FDA 510(k) clearance status and ISO 17025 calibration traceability. Pricing pressure stems from bundled service contracts with consumable minimums that compress hardware margins. Mid-sized United States hospitals exhibit highest price sensitivity due to limited capital budgets, while German laboratory networks show lowest sensitivity given reagent-locked platform commitments.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for biomedical tester manufacturers. Component sourcing concentrates in Germany, Japan, and China for precision optical sensors, thermal cycling modules, and traceable calibration gases. Raw material dependencies include rare-earth magnets for motor assemblies, high-purity quartz for optical pathways, and specialty fluoropolymers for fluid handling. Single-source vulnerability persists for EUV-grade optical coatings. Distribution runs through authorized service networks with regional calibration laboratories rather than direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biomedical tester market rewards specialized calibration expertise that concentrates in aging workforces, creating durable competitive moats for incumbents with metrology heritage. This capability scarcity elevates preventive maintenance infrastructure above pure hardware supply as the decisive competitive dimension.
For Market Incumbents: Entrench market position through backward integration into precision optical sensor supply and captive calibration gas production. Acquire cloud-native validation platform capabilities to shift revenue from hardware sales toward subscription-based uptime guarantees. Consolidate service networks in secondary hospital markets where metrology technician scarcity constrains competitor expansion. For New Entrants and Emerging Players: India's tier-two and tier-three cities present underpenetration opportunities as PLI scheme incentives localize manufacturing and reduce import dependency. Target point-of-care electrical safety testing with battery-operated, wireless-enabled portable analyzers outside centralized laboratory infrastructure. Pursue hospital system partnerships in Maharashtra and Karnataka as anchor customers for regional service network buildout. For Investors and Strategic Acquirers: Capital is best deployed toward heritage calibration specialists with preventive maintenance agreement scale and reagent-locked platform portfolios. Long-term viability across the analysis window hinges on cloud-connected validation capabilities that enable predictive maintenance revenue streams. Watch FDA cybersecurity guidance evolution as the inflection signal for firmware architecture investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Validation Platform Development | Enables predictive maintenance models that shift revenue from hardware sales to subscription-based uptime guarantees in United States health systems. |
| Backward Integration into Precision Optics | Reduces dependency on German and Japanese specialty chemical suppliers for traceable calibration gases and optical sensors. |
| Hospital System Partnership Expansion | Secures bundled service contract anchors with consumable minimums that extend customer lifetime value across seven-year horizons. |
| Point-of-Care Portable Analyzer Launch | Captures white space in decentralized clinical settings with battery-operated, wireless-enabled electrical safety testing tools. |
| India PLI Scheme Manufacturing Localization | Reduces import dependency and opens procurement channels for localized service networks in Maharashtra and Karnataka clusters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, NMPA registration databases, and hospital procurement contract records. Primary interviews engaged biomedical engineering directors, hospital purchasing committee members, GPO contracts managers, and metrology service technicians across United States, German, and Chinese healthcare networks. Bottom-up equipment shipment analysis triangulates against top-down healthcare capital expenditure tracking.
Forecast inputs incorporate product type segmentation across hematology analyzers, molecular diagnostics equipment, and immunoassay systems alongside technology dimensions including flow cytometry and PCR amplification. End-user stratification separates hospitals, diagnostic laboratories, and research institutes by capital deployment capacity and service contract preferences. CAGRs derive from installed base replacement cycle analysis and reagent-locked platform revenue persistence modeling across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native validation platform entrants or cybersecurity-focused firmware specialists would shift outcomes. Regulatory timeline acceleration at FDA, EMA, or NMPA could compress commercialization windows for novel analyzer technologies. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Large and Small-Scale Bioprocessing Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Tissue Engineering Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Global Continuous Bioprocessing Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market
Biomedical Engineering
Biocompatible 3D Printing Market
Biomedical Engineering
3D Bioprinting Market
Biomedical Engineering
Global Single Use Bioprocessing Probes and Sensors Market