
 North America Biosurgery Market | 2026-2036
North America Biosurgery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biosurgery Market Analytics
The divergence between premium biologic hemostats and commodity synthetic sealants is hardening across North American procurement channels. Integra LifeSciences leverages its regenerative tissue matrix portfolio to dominate high-margin neurosurgical applications. BD sustains competitive positioning through integrated vascular closure and hemostasis platforms that anchor hospital system contracts.
Biosurgery encompasses intraoperative products derived from biologic, synthetic, or hybrid materials designed to control bleeding, prevent adhesions, and facilitate tissue repair during open and minimally invasive procedures; these formulations typically incorporate collagen, gelatin, oxidized cellulose, or recombinant thrombin with defined viscosity and absorption profiles measured in days to weeks. Hemostatic agents lead product type revenue due to universal surgical utilization, while bone graft substitutes represent the fastest-expanding category driven by spine and orthopedic volume growth. Biologics technology commands premium pricing through proprietary human and animal tissue processing, whereas synthetic polymers compete on scale and supply consistency.
FDA 510(k) clearance pathways and the agency's evolving guidance on animal-derived medical devices shape product development timelines and clinical evidence requirements for biosurgery manufacturers. Health Canada and the EPA jointly influence environmental and biologic sourcing standards that constrain raw material supply chains for collagen and thrombin-based products. Stakeholders must monitor reimbursement shifts toward outpatient surgical settings and ambulatory surgical center expansion as these sites redefine volume allocation across product categories.
Market Dynamics
Hospital procurement consolidation in the United States is compressing vendor margins and forcing biosurgery manufacturers to bundle hemostatic agents with adhesion barriers under single-source contracts.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined premarket notification for recombinant thrombin products reduces clearance timelines for novel hemostatic formulations entering orthopedic surgery suites.
- Ambulatory Surgical Center Expansion:Medicare reimbursement shifts toward outpatient settings drive volume migration for synthetic sealants used in minimally invasive cardiovascular procedures.
- Collagen-Gelatin Hybrid Maturation:Advanced cross-linking chemistry improves absorption profiles, expanding utilization in neurosurgical applications across Northeastern academic medical centers.
Market Restraints
- Bovine-Derived Material Sourcing:EPA environmental compliance and BSE-related import restrictions constrain thrombin supply chains originating from cattle-processing regions.
- Synthetic Polymer Price Compression:Commodity oxidized cellulose manufacturers face margin erosion as hospital systems standardize on lower-cost alternatives for routine procedures.
- Biologics Reimbursement Uncertainty:CMS coverage determinations for premium-priced regenerative matrices create adoption friction in cost-constrained Medicaid expansion states.
Strategic Opportunities
- Canadian Market Underpenetration:Health Canada alignment with FDA biologics guidance creates regulatory arbitrage for US-cleared products entering Quebec and Ontario hospital networks.
- Spine Fusion Adjunct Positioning:Bone graft substitute formulations targeting lumbar interbody fusion procedures capture incremental share from autograft harvesting in high-volume orthopedic centers.
- Synthetic-Biologic Convergence:Hybrid scaffolds combining recombinant proteins with absorbable polymers command premium positioning in sports medicine arthroscopy suites.
Industry Challenges
- Biologics Processing Expertise Scarcity:Human and animal tissue decellularization requires specialized technicians, constraining manufacturing scale-up for regenerative matrix producers.
- 510(k) Clinical Evidence Burden:FDA demands for predicate device equivalence studies extend development timelines for novel oxidized regenerated cellulose formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biosurgery Market |
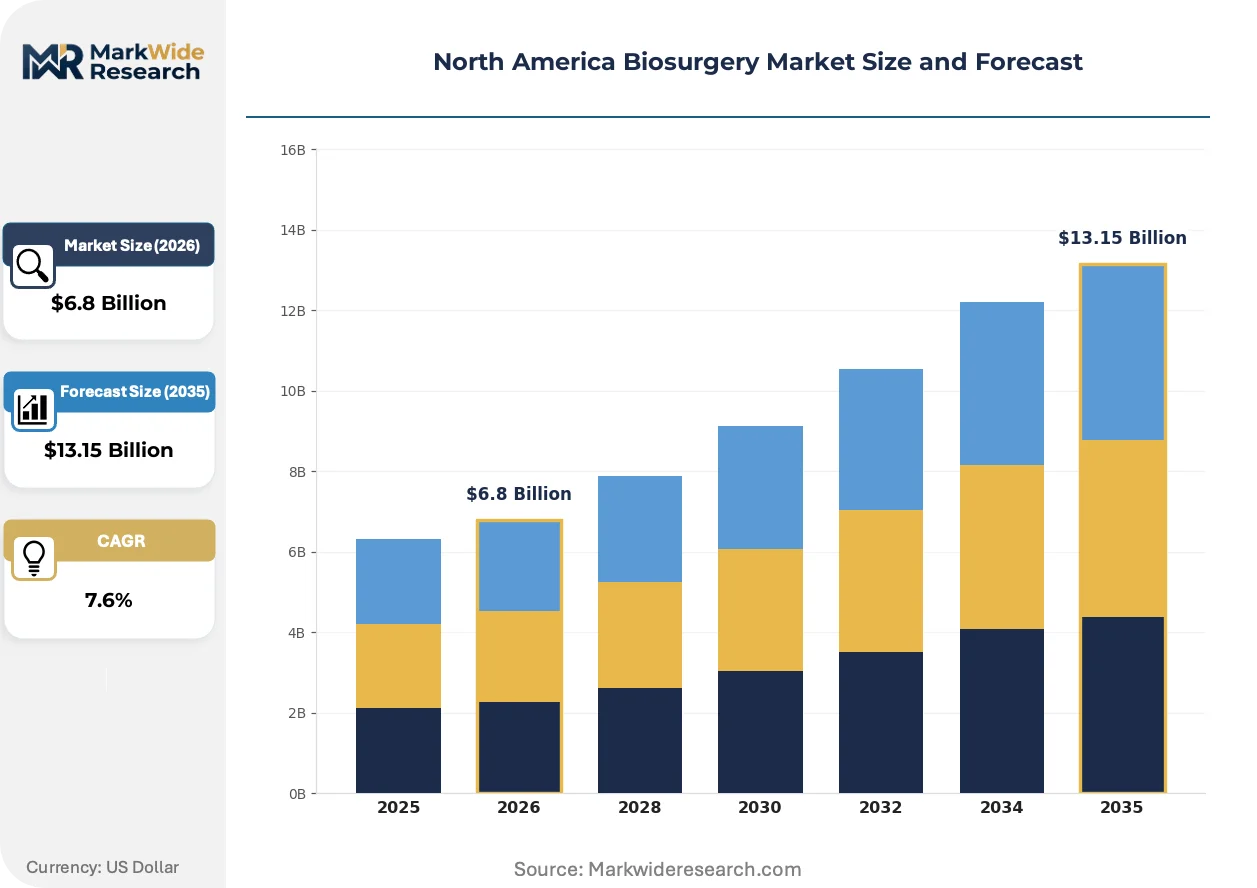
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
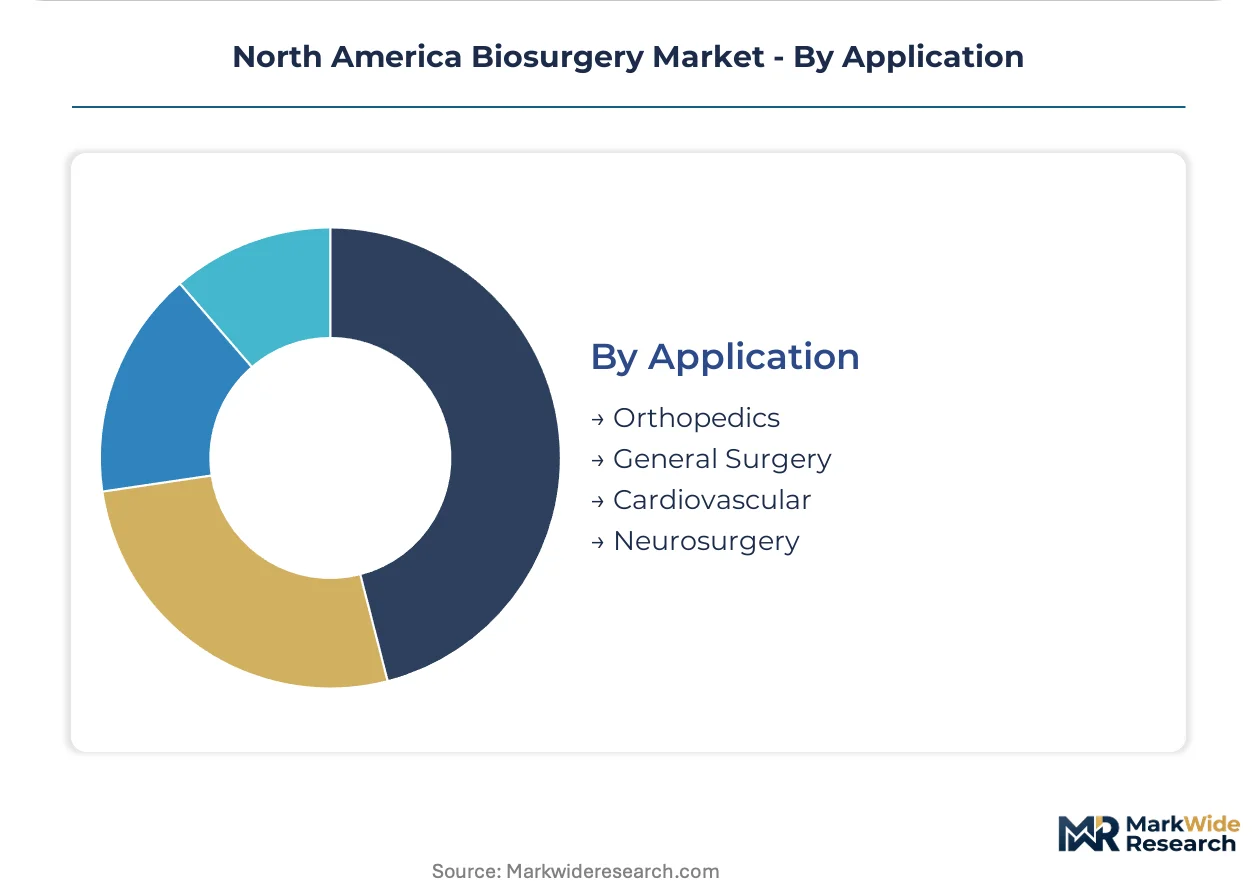
| Segmentation | Product Type: Adhesion Barriers, Hemostatic Agents, Wound Management, Bone Graft Substitutes End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Biologics, Synthetic Polymers, Natural Polymers, Hybrid Solutions Application: Orthopedics, General Surgery, Cardiovascular, Neurosurgery |
| Companies Covered | INTEGRA LIFESCIENCES, BD, Medtronic, Sanofi, B. Braun SE, Baxter, Stryker, Pfizer Inc, Johnson & Johnson Services, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biosurgery Market Evolving Landscape
Recombinant protein engineering and point-of-care manufacturing are compressing traditional supply chains while regulatory harmonization between Washington and Ottawa reshapes cross-border commercialization strategies.
Recombinant thrombin synthesized through microbial fermentation is decentralizing production economics for hemostatic agents. Regional hospital networks in Texas and Florida are adopting on-site reconstitution protocols for lyophilized formulations. This distributed manufacturing model is decentralizing inventory risk from centralized distributors to individual surgical suites.
FDA's evolving guidance on animal-derived medical devices tightens viral inactivation documentation requirements for collagen-based products. Manufacturers must now submit extensive BSE/TSE risk assessments alongside traditional biocompatibility data. Canadian orthopedic device firms are responding by accelerating synthetic polymer development to circumvent bovine sourcing constraints entirely.
Hospital value analysis committees now mandate head-to-head cost-effectiveness data before approving premium biologic hemostats for formulary inclusion. Integrated delivery networks in California and Illinois are unbundling device procurement from physician preference item contracts. This behavioral shift concentrates purchasing power within supply chain executives rather than individual surgeons, compressing brand loyalty and accelerating generic synthetic sealant uptake in high-volume cardiac catheterization labs.
North America Biosurgery Market Segmentation
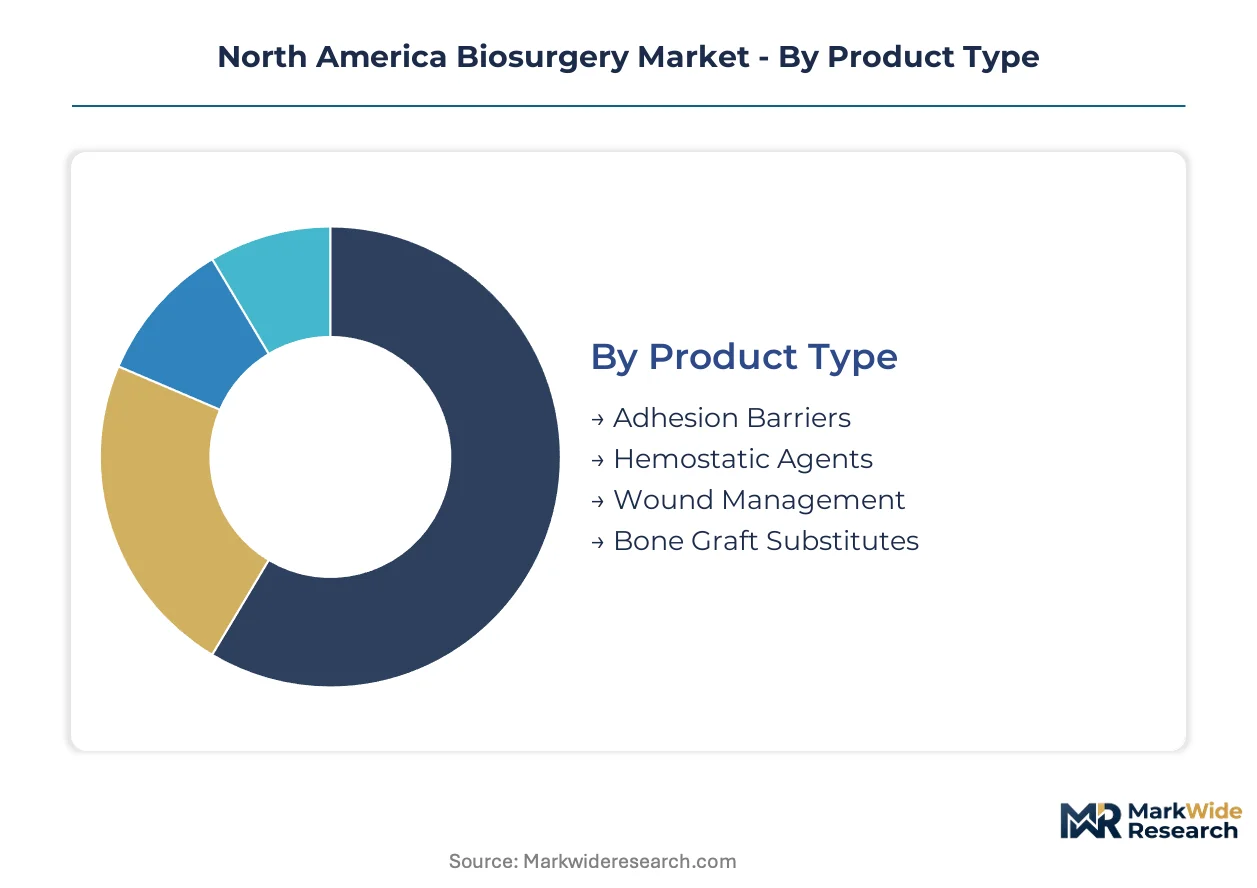
Biosurgery manufacturers must navigate distinct procurement logics across product categories, where clinical efficacy thresholds and reimbursement codes vary sharply. Understanding how segments intersect—particularly between technology platforms and surgical applications—determines portfolio prioritization for North American market access.
Product Type:
Formulation chemistry and absorption kinetics define competitive positioning across this axis, with regulatory clearance pathways diverging between biologic and synthetic material classes.
- Hemostatic Agents:Collagen, gelatin, and oxidized cellulose formulations control intraoperative bleeding through mechanical and biochemical clotting acceleration. Demand concentrates in cardiovascular catheterization labs across Texas and Florida hospital systems, driven by Medicare reimbursement shifts toward outpatient settings.
- Bone Graft Substitutes:Demineralized bone matrix and synthetic calcium phosphate scaffolds facilitate osseointegration in spinal fusion procedures. Northeastern academic medical centers drive volume for lumbar interbody fusion applications, capturing share from autograft harvesting through reduced operative time and donor site morbidity.
- Adhesion Barriers:Hyaluronic acid and oxidized regenerated cellulose sheets prevent post-surgical tissue adhesion in pelvic and abdominal procedures.
- Wound Management:Advanced dressings incorporating antimicrobial agents and moisture-retentive substrates address chronic and surgical wound closure.
Mature deployment sits with Hemostatic Agents. Newer deployment is concentrated in Bone Graft Substitutes.
End User:
Site-of-care economics reshape volume allocation as reimbursement migrates from inpatient DRG codes toward outpatient APC structures.
- Hospitals:Integrated delivery networks in California and Illinois centralize purchasing through value analysis committees, unbundling device procurement from physician preference contracts. Academic medical centers in the Northeastern United States anchor demand for premium biologic matrices in complex neurosurgical and orthopedic reconstruction.
- Ambulatory Surgical Centers:Freestanding facilities in Texas and Florida exploit Medicare reimbursement parity for outpatient cardiovascular and orthopedic procedures. Synthetic sealant uptake accelerates in these settings due to formulary standardization and compressed inventory carrying costs.
- Specialty Clinics:Orthopedic and sports medicine practices perform arthroscopic procedures with hybrid scaffold applications.
- Research Institutions:University-affiliated medical centers conduct clinical trials for novel recombinant protein formulations and decellularized tissue matrices.
Procurement consolidation favors Ambulatory Surgical Centers. Technology validation requirements favor Research Institutions.
Technology:
Raw material sourcing constraints and viral inactivation documentation requirements differentiate competitive economics across material platforms.
- Biologics:Human and animal-derived tissue matrices command premium pricing through proprietary decellularization and cross-linking processes. FDA demands for BSE/TSE risk assessments alongside biocompatibility data extend development timelines, constraining manufacturing scale-up due to specialized technician scarcity.
- Hybrid Solutions:Recombinant proteins combined with absorbable polymers bridge performance and cost positioning. Sports medicine arthroscopy suites in academic medical centers drive adoption, capturing premium positioning through tunable absorption profiles and reduced inflammatory response.
- Synthetic Polymers:Oxidized cellulose and polysaccharide formulations compete on supply consistency and manufacturing scale.
- Natural Polymers:Plant-derived and marine collagen alternatives circumvent bovine sourcing constraints.
Regulatory burden concentrates in Biologics. Manufacturing flexibility concentrates in Synthetic Polymers.
Application:
Procedure volume growth and reimbursement adequacy determine addressable market expansion across surgical specialties.
- Orthopedics:Spine fusion, joint reconstruction, and sports medicine procedures consume hemostatic agents and bone graft substitutes at scale. Volume growth in lumbar interbody fusion drives the steepest expansion trajectory for synthetic-biologic hybrid formulations.
- Cardiovascular:Catheterization labs and open-heart surgery suites deploy hemostatic sealants and adhesion barriers. Synthetic polymer standardization accelerates as hospital systems consolidate vendor contracts around lower-cost alternatives for routine procedures.
- General Surgery:Abdominal and pelvic procedures utilize adhesion barriers and topical hemostats.
- Neurosurgery:Cranial and spinal cord procedures require precision hemostasis with minimal tissue reactivity.
Volume scale sits with Orthopedics. Margin concentration sits with Neurosurgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge corridor anchors North American biosurgery innovation through its dense concentration of academic medical centers and regenerative medicine startups. Hospital procurement networks across this cluster drive early adoption of hybrid hemostatic technologies before broader commercial rollout.
United States
Texas and Florida hospital systems expand ambulatory surgical center capacity for cardiovascular procedures, accelerating synthetic sealant volume migration from inpatient settings. FDA 510(k) pathway refinements for recombinant thrombin products compress clearance timelines for manufacturers targeting orthopedic surgery suites. Northeastern academic medical centers in Massachusetts and New York anchor demand for premium biologic matrices in complex neurosurgical reconstruction.
Canada
Ontario and Quebec hospital networks underutilize advanced adhesion barriers relative to US penetration rates, creating expansion headroom for US-cleared products. Health Canada alignment with FDA biologics guidance reduces regulatory friction for cross-border commercialization of collagen-based hemostats. Toronto's university-affiliated medical centers conduct clinical validation trials that accelerate provincial formulary adoption for hybrid scaffold technologies.
Mexico
Private hospital chains in Mexico City and Monterrey import US-manufactured biosurgery products through distributor relationships constrained by import tariff structures. COFEPRIS regulatory harmonization efforts with FDA standards streamline registration pathways for hemostatic agents and bone graft substitutes. Guadalajara's medical device manufacturing zone attracts contract production for synthetic polymer components serving North American supply chains.
North America Biosurgery Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across North American biosurgery supply chains. Vertically integrated medical device conglomerates with captive tissue processing facilities command premium pricing in biologic hemostats. Specialized regenerative medicine firms lacking manufacturing scale partner with contract research organizations for clinical evidence generation. Consolidation pressures intensify as hospital procurement committees unbundle physician preference contracts and standardize on multi-product vendor relationships.
Within the integrated medical technology tier, Integra LifeSciences and BD occupy positions that exemplify divergent strategic archetypes. Integra LifeSciences anchors the regenerative tissue matrix segment through proprietary decellularization expertise. BD represents the vascular closure and integrated hemostasis platform model that secures multi-year hospital system contracts. Medtronic sits within the diversified conglomerate category with cross-portfolio bundling capabilities spanning surgical navigation and biologic adjuncts.
| Leading Market Players |
|---|
| INTEGRA LIFESCIENCES |
| BD |
| Medtronic |
| Sanofi |
| B. Braun SE |
| Baxter |
| Stryker |
| Pfizer Inc |
| Johnson & Johnson Services, Inc |
| Others |
Value Network & Pricing Analysis
Specialized tissue processing technicians in Massachusetts and New Jersey command wage premiums that compress manufacturing margins for biologic hemostat producers. This workforce concentration forces three-tier pricing stratification across premium regenerative matrices, standard collagen formulations, and economy synthetic sealants.
Pricing Analysis
Outcome-based pricing tied to reduced operative time and lower revision rates anchors premium biologic hemostat positioning in Northeastern academic medical centers. Price differentiation separates FDA-cleared recombinant thrombin products from commodity oxidized cellulose through clinical evidence depth and viral inactivation documentation. Pricing pressure stems from hospital value analysis committees mandating head-to-head cost-effectiveness data before formulary inclusion. Ambulatory surgical centers in Texas and Florida exhibit highest price sensitivity, while academic medical centers in Massachusetts show lowest sensitivity due to outcome-linked procurement protocols.
Supply Chain Analysis
Dual-sourcing requirements imposed by integrated delivery networks in California and Illinois mandate qualified backup suppliers for all critical hemostatic inputs. Geographic supply concentration centers on United States, Ireland, and Switzerland for recombinant protein fermentation and collagen extraction facilities. Raw material dependencies include bovine thrombin, porcine gelatin, and microbial fermentation substrates. Supply chain risk manifests in BSE-related import restrictions constraining cattle-derived material flows. Distribution runs through specialized medical device distributors with cold-chain capabilities serving hospital networks and ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American biosurgery represents a vertical-integration race where captive tissue processing capabilities determine margin sustainability. Players are pursuing upstream control over decellularization expertise and downstream hospital system contract anchoring.
For Market Incumbents: Deploy proprietary cross-linking chemistry as a defensive moat against synthetic polymer commoditization. Incumbents should secure multi-year GPO contracts bundling hemostatic agents with adhesion barriers before procurement committees complete vendor consolidation. Capacity addition in Texas and Florida ambulatory surgical center corridors captures volume migration from inpatient settings. FDA 510(k) pathway expertise serves as a certification investment lever that extends development timelines for challengers. For New Entrants and Emerging Players: Launch via Health Canada regulatory arbitrage into Ontario and Quebec hospital networks where advanced adhesion barriers remain underpenetrated relative to US benchmarks. White-space targets include point-of-care manufacturing partnerships with regional hospital networks in Texas adopting lyophilized recombinant thrombin reconstitution protocols. Synthetic-biologic hybrid scaffolds for sports medicine arthroscopy offer the most penetrable application segment given tunable absorption profile demand from academic medical centers. For Investors and Strategic Acquirers: Re-rating potential sits with specialized regenerative medicine firms possessing captive decellularization facilities given FDA's escalating viral inactivation documentation requirements. Long-term viability over the coming decade hinges on backward integration into tissue sourcing and processing rather than reliance on contract research organizations. Acquisition target archetypes include mid-cap hybrid scaffold developers with Health Canada clearance and established Northeastern academic medical center relationships. The signal to watch is CMS coverage determination shifts for premium-priced regenerative matrices in Medicaid expansion states.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Streamlined premarket notification accelerates recombinant thrombin product entry into orthopedic surgery suites. |
| Hospital System Partnership | Multi-year GPO contracts bundling hemostatic agents with adhesion barriers secure volume commitments against procurement consolidation. |
| Reimbursement Strategy | CMS coverage determination alignment enables premium biologic matrix adoption in cost-constrained Medicaid expansion states. |
| Software Companion Development | Digital inventory management platforms reduce carrying costs for ambulatory surgical center synthetic sealant formulary standardization. |
| Backward Integration into Tissue Processing | Captive decellularization facilities circumvent biologics processing expertise scarcity constraining manufacturing scale-up. |
Research Methodology
Document review covered FDA 510(k) clearance databases, Health Canada medical device licenses, and hospital procurement records, complemented by interviews with supply chain executives, biomedical engineers, GPO contracts managers, and regulatory affairs leads. Secondary validation drew from CMS Medicare reimbursement data, hospital value analysis committee documentation, and EPA environmental compliance filings. Bottom-up volume modeling triangulated against top-down market sizing across product categories.
Segment-level revenue outputs reflect procedure volume projections, technology adoption curves, and site-of-care migration patterns across the analysis window. The analytical framework modeled dimensions including product formulation chemistry, end-user facility type, raw material technology platform, and surgical application specialty. CAGRs were derived from weighted procedure growth assumptions and reimbursement adequacy indices. Industry-specific forecast inputs incorporated FDA guidance evolution on animal-derived devices and ambulatory surgical center capacity expansion trajectories.
Regulatory guidance shifts, reimbursement determination reversals, and raw material sourcing disruptions are the dominant revision risks to the outlook. Deviation in FDA biologics documentation requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
Biocompatible 3D Printing Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Global Bionics Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
Bioactive Coating Devices Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Global Single Use Bioprocessing Probes and Sensors Market
Biomedical Engineering
Bioink Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Global Continuous Bioprocessing Market
Biomedical Engineering
Next-Generation Biomanufacturing Market