
 Polycarbonate Resin Market | 2026-2036
Polycarbonate Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Polycarbonate Resin Market Intelligence
A shift from single-source to multi-source procurement of specialty grades is broadening the supplier base for automotive and electronics OEMs. SABIC leverages its massive scale in base resin production to serve high-volume applications globally. In contrast, Covestro AG differentiates through its focus on high-performance materials for regulated industries. Teijin Limited specializes in advanced polycarbonate composites for demanding sectors like aerospace and automotive.
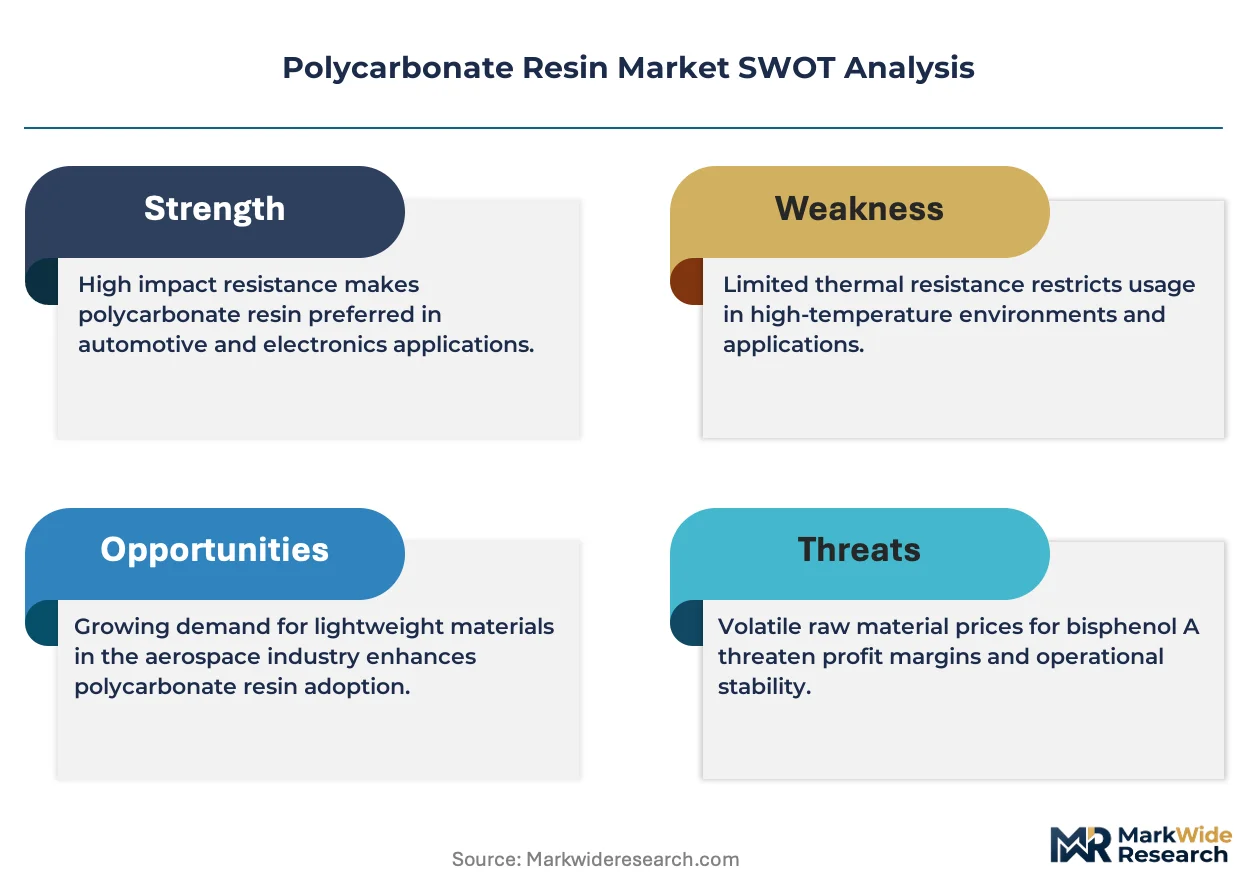
Polycarbonate resin is a thermoplastic polymer known for its exceptional impact strength, temperature resistance, and optical clarity. These properties derive from its chemical structure, typically synthesized from bisphenol A (BPA) and a carbonate source. While general purpose grades constitute the largest volume, flame retardant and optical grade products command higher margins due to stringent performance requirements. The automotive interiors and medical devices applications represent key end-use markets, driving demand for high-impact and biocompatible variants respectively.
Regulatory frameworks, including the EU's REACH and RoHS directives, heavily influence material composition, particularly concerning bisphenol A (BPA) content. In the United States, the FDA sets standards for food-contact applications, while China's GB standards govern product safety for electronics. Navigating the trade-offs between performance, regulatory compliance, and the development of sustainable, BPA-free alternatives will define future competitive positioning.
Market Dynamics
The polycarbonate resin market is defined by the core tension between performance demands in sectors like automotive and electronics, and mounting regulatory pressure for circularity. This dynamic is forcing a fundamental re-evaluation of material composition, particularly concerning BPA content and the integration of recycled feedstocks.
Growth Catalysts
- EV Lightweighting:Demand for high-strength, low-weight polycarbonate in automotive interiors and battery components is accelerating, driven by electric vehicle manufacturers' focus on extending range.
- EU Circularity Mandates:The EU Green Deal's emphasis on a circular economy is creating a significant pull for recycled-grade polycarbonate resins, especially in consumer electronics and packaging.
- Chinese Manufacturing Base:China’s vast and integrated electronics and automotive production ecosystems provide a concentrated and sustained demand base for both general purpose and specialty polycarbonate grades.
Market Restraints
- Feedstock Volatility:Price fluctuations in key petrochemical feedstocks, particularly bisphenol A (BPA), create margin pressure and unpredictability for resin producers.
- Regulatory Scrutiny:Heightened regulatory oversight of BPA under frameworks like the EU's REACH and US FDA rules restricts use in sensitive applications like food contact and medical devices.
- Material Substitution:In optical applications, high-clarity acrylics (PMMA) and in structural components, other engineering polymers, present viable substitution threats based on cost-performance trade-offs.
Strategic Opportunities
- Biocompatible Medical Grades:Expansion into single-use medical devices and diagnostic equipment offers a high-margin opportunity for specialized biocompatible and sterilization-resistant polycarbonate grades.
- BPA-Free Formulations:Developing and commercializing high-performance, BPA-free polycarbonate alternatives creates a significant competitive advantage in regulated consumer and medical markets.
- Southeast Asia Expansion:Establishing production and compounding facilities in emerging manufacturing hubs like Vietnam and Indonesia can capture demand from diversifying electronics supply chains.
Industry Challenges
- Recycling Infrastructure Costs:The significant capital investment required to build and scale advanced sorting and purification facilities for producing high-purity recycled polycarbonate is a major barrier.
- Complex Global Compliance:Navigating disparate and evolving chemical safety standards, such as China's GB standards and Europe's RoHS directive, complicates global product launches and increases compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycarbonate Resin Market |
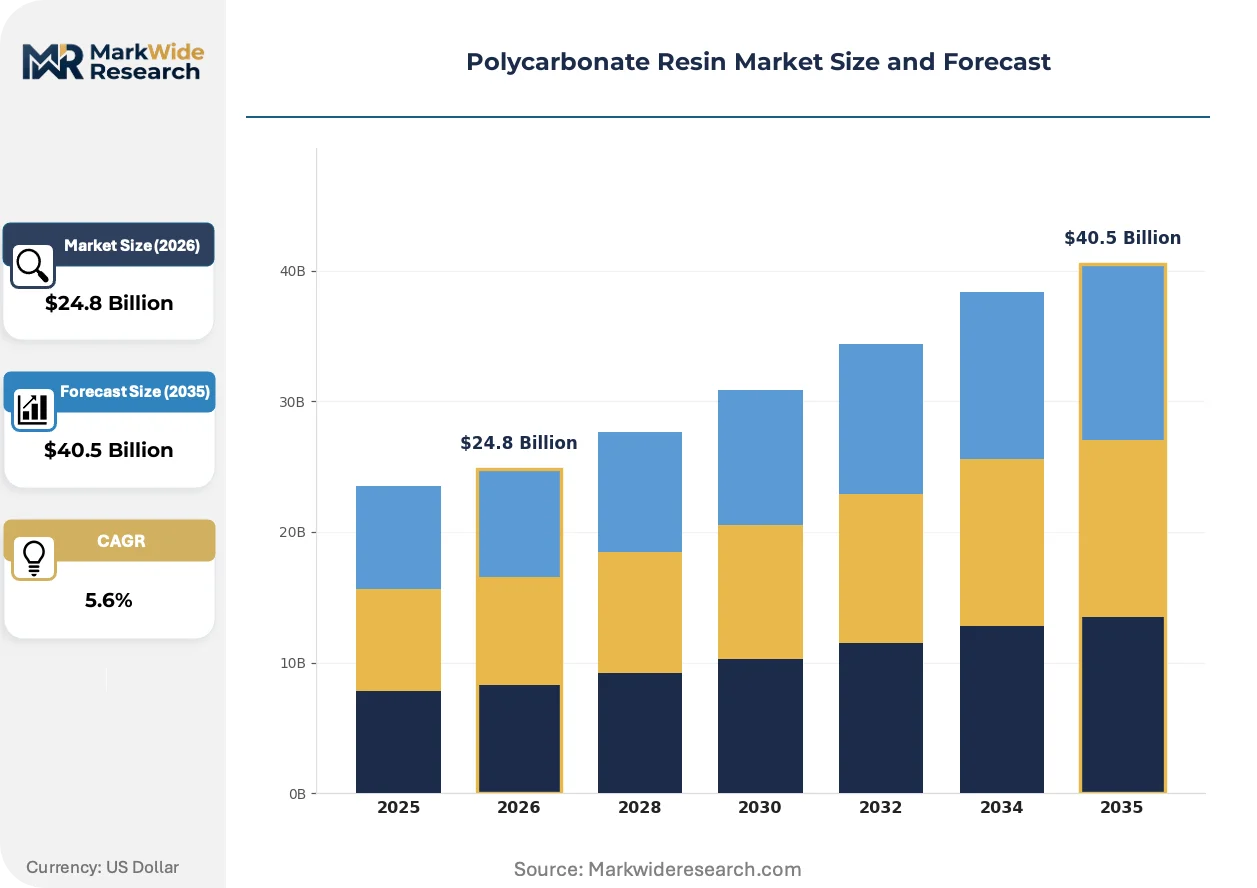
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.5 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose, High Impact, Optical Grade, Flame Retardant Application: Automotive Interiors, Electronics, Medical Devices, Construction End User: OEMs, Tier-1 Suppliers, Manufacturing, Retail Shape: Sheet, Film, Rod, Tube |
| Companies Covered | Lotte Chemical Corporation, LG Chem, Covestro AG, Chimei Corporation, Formosa Chemicals and Fibre Corporation, SABIC, Teijin Limited, Idemitsu Kosan Co., Ltd., Mitsubishi Engineering-Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycarbonate Resin Market Strategic Shifts & Innovations
Innovation in the polycarbonate resin market centers on reconciling sustainability goals with stringent performance criteria. The development of circular economy models and bio-based alternatives is fundamentally altering material science and supply chain structures.
Advanced chemical recycling processes depolymerize post-consumer polycarbonate waste back into its monomer constituents. Resin manufacturers and specialized recycling firms are adopting these methods to achieve virgin-like quality. This technology is automating the purification of complex waste streams, enabling a closed-loop system for high-performance applications.
The EU's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure on material circularity and supply chain emissions. This policy forces OEMs to quantify and report the use of recycled materials in their products. The automotive and electronics sectors are most affected, driving them to secure stable supplies of certified recycled-grade polycarbonate to meet new transparency obligations.
A clear shift toward multi-sourcing for specialty grades is disrupting traditional procurement models. Automotive OEMs, wary of supply chain fragility, are diversifying their supplier base beyond single, dominant producers. This change in buying behavior is most pronounced in North America and Europe, where resilience is now prioritized alongside cost and performance.
Polycarbonate Resin Market Segmentation
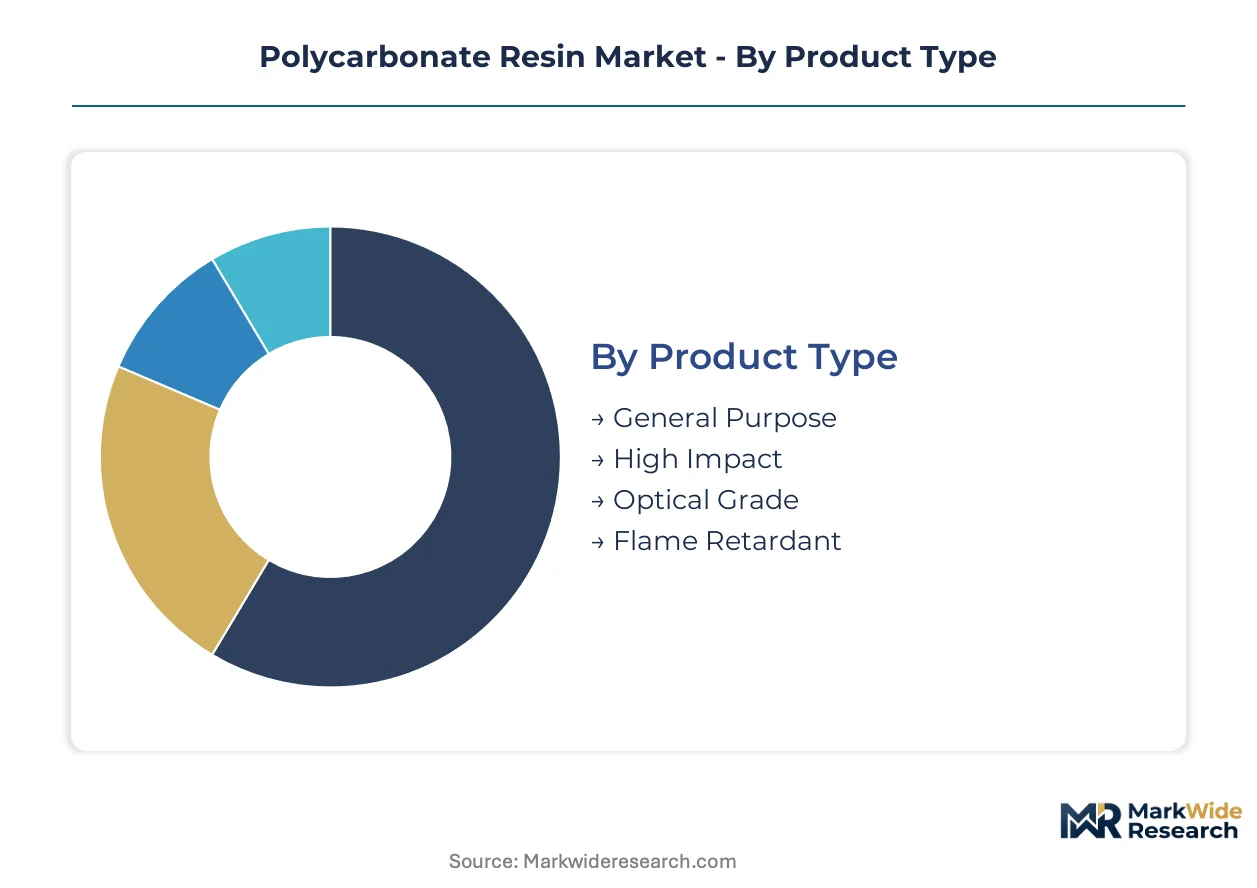
Segmentation of the polycarbonate resin market provides critical insights into diverse material requirements and value chain dynamics. Understanding these distinct segments helps producers align product development with specific industry demands, from high-volume general purpose applications to specialized, high-performance niches.
Product Type:
The polycarbonate resin market differentiates across product types, reflecting a clear split between high-volume, cost-effective grades and premium, performance-driven specialties.
- General Purpose:This segment includes cost-effective polycarbonate resins offering basic properties like impact strength and transparency. Demand concentrates in consumer goods and packaging applications, driven by material versatility and economic efficiency.
- High Impact:These resins deliver enhanced durability and shatter resistance, crucial for applications requiring superior mechanical performance. Automotive interiors and industrial safety equipment represent key end-use areas for high impact variants.
- Optical Grade:Optical grade polycarbonate features exceptional clarity, low haze, and precise refractive index control. Demand stems from LED lighting components and advanced automotive displays, where optical performance is paramount.
- Flame Retardant:Formulations with added flame retardant properties prevent ignition and slow fire propagation. Electronics enclosures and building materials extensively use these grades for critical fire safety compliance.
Mature deployment sits with General Purpose grades. Newer deployment is concentrated in Optical Grade products.
Application:
Application-specific demands dictate material specifications across the polycarbonate resin market, with each end-use sector valuing distinct properties.
- Automotive Interiors:Polycarbonate offers lightweighting advantages, aesthetic appeal, and impact resistance for vehicle cabin components. Electric vehicle manufacturers prioritize these materials for extending range and enhancing passenger safety.
- Electronics:This segment utilizes polycarbonate for device casings, connectors, and optical media due to its insulation properties and durability. China's extensive electronics production drives significant demand for these grades.
- Medical Devices:Biocompatible and sterilization-resistant polycarbonate variants are essential for single-use diagnostic equipment and surgical instruments. Regulatory compliance and patient safety drive material selection in this high-value segment.
- Construction:Polycarbonate finds use in glazing, roofing, and safety barriers, valued for its impact resistance and UV stability. Architectural panels and protective shields represent common applications.
Segments like Construction show consistent growth, while Medical Devices exhibits the steepest expansion trajectory.
End User:
The end-user landscape for polycarbonate resin reflects varied procurement models and influence points throughout the value chain.
- OEMs:Original Equipment Manufacturers directly integrate polycarbonate resins into their final products, such as automobiles or consumer electronics. Their material choices are driven by brand reputation and design control.
- Tier-1 Suppliers:These companies fabricate components and sub-assemblies for OEMs, specifying polycarbonate based on engineering requirements and supply chain efficiency. Automotive and aerospace sectors rely heavily on Tier-1 suppliers.
- Manufacturing:This segment encompasses a broad range of industrial users producing intermediate goods or specialized industrial equipment. Material selection often prioritizes cost-effectiveness and processability.
- Retail:Retailers primarily represent the point-of-sale for finished polycarbonate products like display units or consumer packaging. Their demand is influenced by consumer trends and aesthetic considerations.
The procurement influence of OEMs shapes upstream material choices, while Retail represents a direct channel to consumers.
Shape:
Polycarbonate resin is supplied in various physical shapes, each optimized for specific manufacturing processes and final product forms.
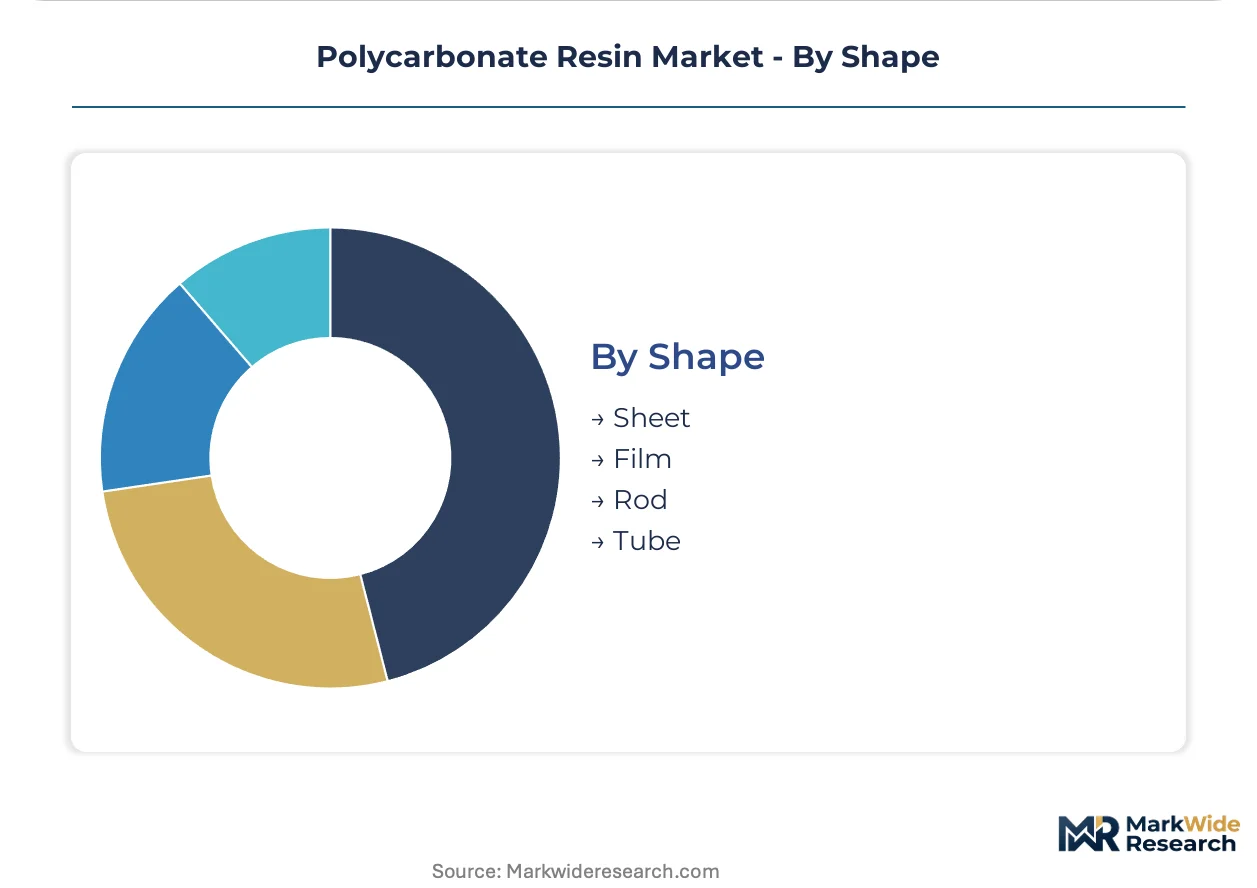
- Sheet:Rigid, flat panels of polycarbonate are widely used in construction, protective glazing, and machine guards. Their impact resistance and optical clarity are key attributes.
- Film:Thin, flexible polycarbonate layers serve applications in electronic displays, protective overlays, and membrane switches. Lightweighting and barrier properties are critical for film products.
- Rod:Solid cylindrical forms of polycarbonate are typically machined into precision parts or used for electrical insulation. Mechanical strength and dimensional stability are important.
- Tube:Hollow cylindrical polycarbonate forms find use in medical tubing, fluid transport systems, and specialized industrial conduits. Sterilization resistance is vital for medical applications.
High-volume processing characterizes Sheet and Film, while Rod and Tube serve more specialized fabrication needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for polycarbonate resin shows significant concentration in key manufacturing hubs globally. This material's versatility makes it indispensable across diverse applications, from high-volume electronics to specialized automotive components. Strategic geographic positioning aligns with major end-use industries.
China
China's vast electronics and automotive production ecosystems drive substantial demand for polycarbonate resins. China's GB standards for product safety heavily influence material selection. The Yangtze River Delta region, with its extensive manufacturing base, remains a critical hub for specialty polycarbonate consumption.
United States
Automotive interiors and medical devices drive polycarbonate resin demand in the United States. The FDA's stringent standards for biocompatibility and food-contact applications shape material development. Manufacturing clusters in Michigan for automotive and California for medical devices demonstrate significant material consumption.
Germany
High-performance automotive materials and regulated industrial applications underpin polycarbonate demand in Germany. EU's REACH and RoHS directives heavily influence material composition, especially for bisphenol A. Major automotive and chemical production centers in Bavaria sustain consistent need for advanced grades.
Japan
Japan's demand for advanced polycarbonate composites and optical grade products remains strong in aerospace and automotive. JIS standards ensure rigorous quality control for materials in precision electronics. The Kanto region, including Tokyo, serves as a hub for electronics and advanced material innovation.
South Korea
Electronics, including displays and device casings, and automotive components drive polycarbonate consumption in South Korea. The country's national product safety regulations mandate specific material properties. The Seoul Capital Area concentrates major electronics manufacturers, generating high material demand.
Polycarbonate Resin Market Key Industry Players
Portfolio diversification, particularly into recycled and bio-based alternatives, dominates the current competitive landscape. The market structure features a tiered arrangement of large-scale base resin producers and specialized high-performance material suppliers. Strategic archetypes include global chemical giants leveraging massive production capabilities, alongside niche players focusing on advanced formulations for regulated industries. Strategic partnerships with recycling firms and geographic expansion into emerging manufacturing hubs are common competitive moves observed.
At the scale-driven end of the market, SABIC leverages its global production capabilities to serve high-volume applications across various industries worldwide, including consumer goods and construction. Covestro AG, a German-based materials company, exemplifies a focus on high-performance materials for regulated sectors, such as medical devices and advanced electronics, demanding stringent specifications. Meanwhile, Teijin Limited, a Japanese corporation, represents a specialization in advanced polycarbonate composites, catering to demanding applications like aerospace and automotive components requiring enhanced strength and durability.
| Leading Market Players |
|---|
| Lotte Chemical Corporation |
| LG Chem |
| Covestro AG |
| Chimei Corporation |
| Formosa Chemicals and Fibre Corporation |
| SABIC |
| Teijin Limited |
| Idemitsu Kosan Co., Ltd. |
| Mitsubishi Engineering-Plastics Corporation |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers and large multinational chemical giants influence polycarbonate resin supply behavior and pricing discipline. Their massive scale in base resin production allows for cost efficiencies, impacting global market prices.
Pricing Analysis
Volume-driven general purpose grades experience commodity spot pricing, while specialty grades command contract-based long-term offtake agreements. Price differentiation stems from quality grade certifications, such as those required for medical devices, and specific performance attributes like flame retardancy. Pricing softness reflects persistent feedstock volatility, particularly for bisphenol A inputs. Buyers in consumer goods applications demonstrate high price sensitivity, whereas medical device and aerospace OEMs prioritize performance over cost.
Supply Chain Analysis
Regional distribution centers facilitate the efficient flow of polycarbonate resins, supporting a hub-and-spoke distribution model for major manufacturing hubs. Geographic supply concentration for raw materials primarily anchors in China, the United States, and Germany. The market relies heavily on petrochemical feedstocks, especially bisphenol A and carbonate sources. Regulatory restrictions on BPA content represent a significant structural supply chain risk. Distribution primarily runs through direct sales to OEMs and specialized compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polycarbonate resin market is undergoing a technology-transition phase, with advanced chemical recycling methods displacing traditional linear production models.
For Market Incumbents:Cement leadership by investing heavily in advanced chemical recycling infrastructure to produce virgin-like polycarbonate from post-consumer waste. Secure long-term supply agreements for bio-based feedstocks to mitigate regulatory pressure on BPA content. Diversify specialty grade portfolios for high-margin applications like medical devices and aerospace. Protect market share against material substitution threats from high-clarity acrylics.
For New Entrants and Emerging Players:Specialized compounding distributors represent an effective channel partner to penetrate niche markets. Target white-space opportunities in high-performance BPA-free formulations for regulated consumer electronics. Focus on establishing production and compounding facilities in Southeast Asia to capture demand from diversifying electronics supply chains. A direct-to-OEM sales approach for specialized, certified recycled grades offers a viable go-to-market angle.
For Investors and Strategic Acquirers:Investment in chemical recycling technology is the leading indicator that circularity goals are becoming economically viable within the polycarbonate market. The long-term viability of this sector depends on successful integration of sustainable practices over the next 5-10 years. Target acquisition profiles include specialized recycling firms with proprietary depolymerization technologies or developers of high-performance bio-based polycarbonate alternatives. Watch for significant capital investments in advanced sorting and purification facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Recycled Grades | Increases availability of circular materials, addressing EU Green Deal mandates for OEMs. |
| Joint Venture with Recycling Technology Firms | Accelerates development and commercialization of advanced chemical recycling processes for polycarbonate waste. |
| Product Launch of BPA-Free Formulations | Captures market share in sensitive applications, mitigating regulatory scrutiny in medical and food-contact sectors. |
| Long-term Supply Agreements for Bio-based Feedstocks | Ensures stable input for sustainable polycarbonate production, reducing reliance on petrochemical derivatives. |
| Geographic Manufacturing Footprint in Southeast Asia | Positions producers to serve electronics and automotive OEMs in rapidly growing regional production hubs. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, complemented by primary interviews. The research team engaged with R&D directors, procurement leads at major OEMs, sustainability officers, and material engineers to gather granular insights. Company annual reports, patent databases, and chemical industry publications provided additional validation. A rigorous bottom-up and top-down triangulation approach ensured data accuracy.
The market was modeled with granularity across product type, application, end-user, and key geographic regions over the projection horizon. Compound annual growth rates were derived from historical data analysis and projected market dynamics, factoring in anticipated shifts in demand and supply. Industry-specific forecast inputs included electric vehicle production forecasts and anticipated recycled content mandates within the automotive and electronics sectors.
Several conditions sit outside the modeled scope, including unforeseen geopolitical trade tensions and rapid shifts in feedstock prices. Forecasts reflect assumptions regarding current regulatory frameworks and technological advancements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market
Polymers & Resins
South America Polycarbonate (PC) Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
N-Vinylformamide Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
Chelating Resins Market
Polymers & Resins
Bio-Based Polyvinyl Chloride Market