
 Europe Predictive Analytics Market | 2026-2036
Europe Predictive Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Predictive Analytics Market Foresight
Mid-market manufacturers are rotating toward cloud-based predictive tools as large enterprises consolidate existing platforms. SAP SE leverages its deep ERP integration to anchor industrial deployments across German automotive suppliers. SAS Institute Inc. differentiates through specialized risk-scoring algorithms that dominate European banking compliance workflows. Microsoft Corporation extends its Azure ML footprint by competing on hybrid deployment flexibility for regulated healthcare systems.
Predictive analytics encompasses statistical modeling, machine learning algorithms, and data mining techniques that forecast future outcomes from historical and real-time data streams, typically processing structured and unstructured inputs through regression, classification, and time-series methods to enable proactive decision-making in commercial and industrial operations. Cloud-based deployment leads in new installations as European firms prioritize scalability and reduced capital overhead, while risk management applications capture the largest margin pools due to regulatory complexity in BFSI. Customer analytics is expanding fastest among retail end users seeking real-time personalization across digital channels.
The EU AI Act and GDPR impose strict transparency and data governance requirements that shape product architecture and vendor liability across the European Economic Area. EMA guidelines on algorithmic validation in healthcare and ECB stress-testing frameworks for model risk further segment compliance obligations by industry. Stakeholders must monitor evolving supervisory interpretations of automated decision-making to align procurement timelines with certification requirements.
Market Dynamics
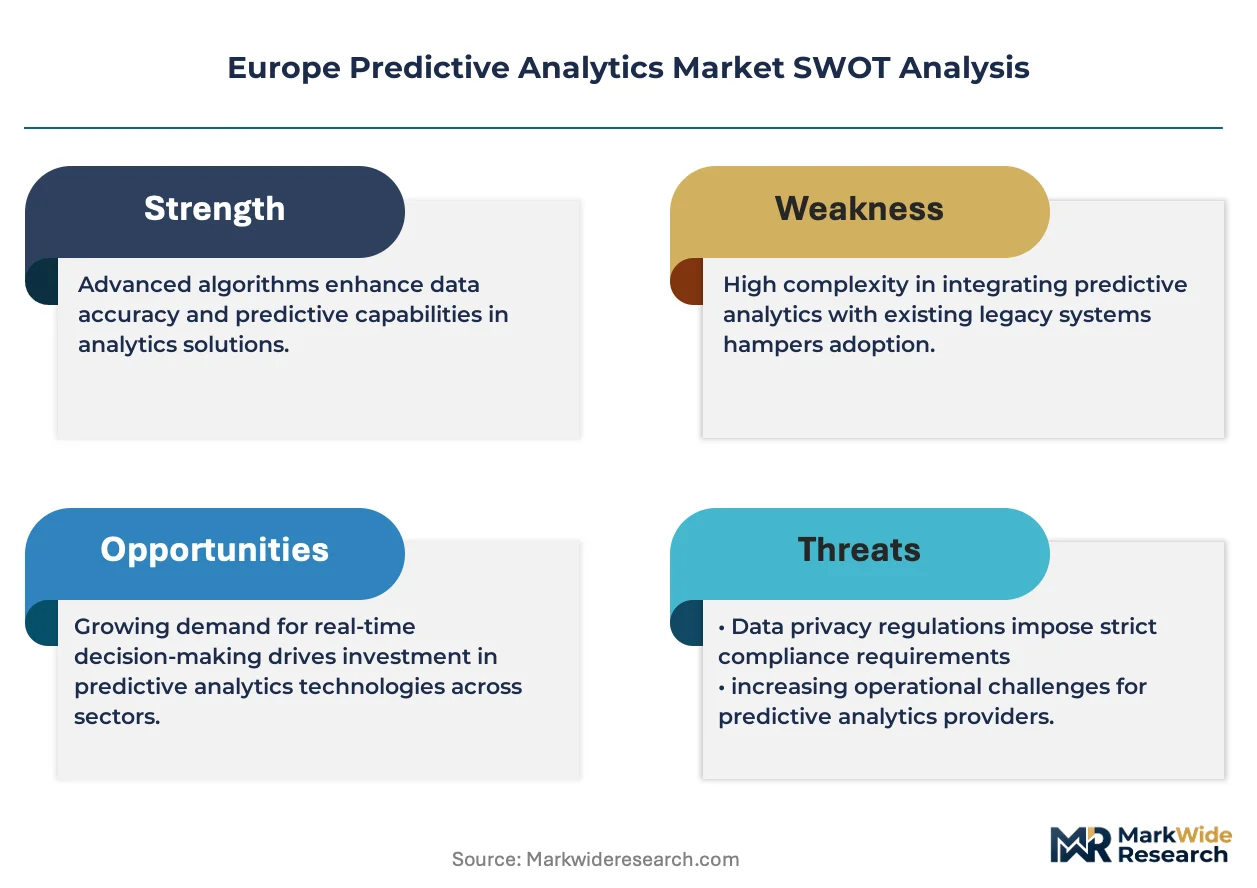
The EU AI Act is forcing predictive analytics vendors to rearchitect platforms for algorithmic transparency, while German industrial manufacturers accelerate deployment of cloud-native tools for supply chain optimization and predictive maintenance.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making systems in banking and insurance face mandatory risk classification, driving replacement cycles for legacy scoring engines.
- German automotive supplier adoption:Industrial clusters in Baden-Württemberg and Bavaria deploy predictive maintenance modules integrated with existing ERP infrastructure.
- Real-time personalization demand:European retail chains process streaming customer data to optimize inventory positioning and dynamic pricing across digital channels.
Market Restraints
- GDPR data governance friction:Cross-border data transfers for model training face supervisory scrutiny, constraining cloud deployment architectures.
- Specialized talent scarcity:Shortages of MLOps engineers and regulatory compliance specialists in France and the Netherlands inflate implementation timelines.
- Legacy system integration costs:On-premise data warehouses in European banks require expensive middleware layers to connect with modern inference pipelines.
Strategic Opportunities
- Healthcare algorithmic validation:EMA guidelines create first-mover advantage for vendors achieving certification for clinical decision-support tools.
- Eastern European manufacturing penetration:Polish and Czech industrial firms remain underpenetrated for predictive quality control applications.
- CSRD sustainability reporting convergence:Predictive models that forecast emissions trajectories capture procurement budgets from ESG compliance officers.
Industry Challenges
- Model risk management certification:ECB stress-testing frameworks require documented validation protocols that extend sales cycles by six to twelve months.
- Interoperability with proprietary ERP systems:Custom data connectors for SAP deployments consume disproportionate professional services resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Predictive Analytics Market |
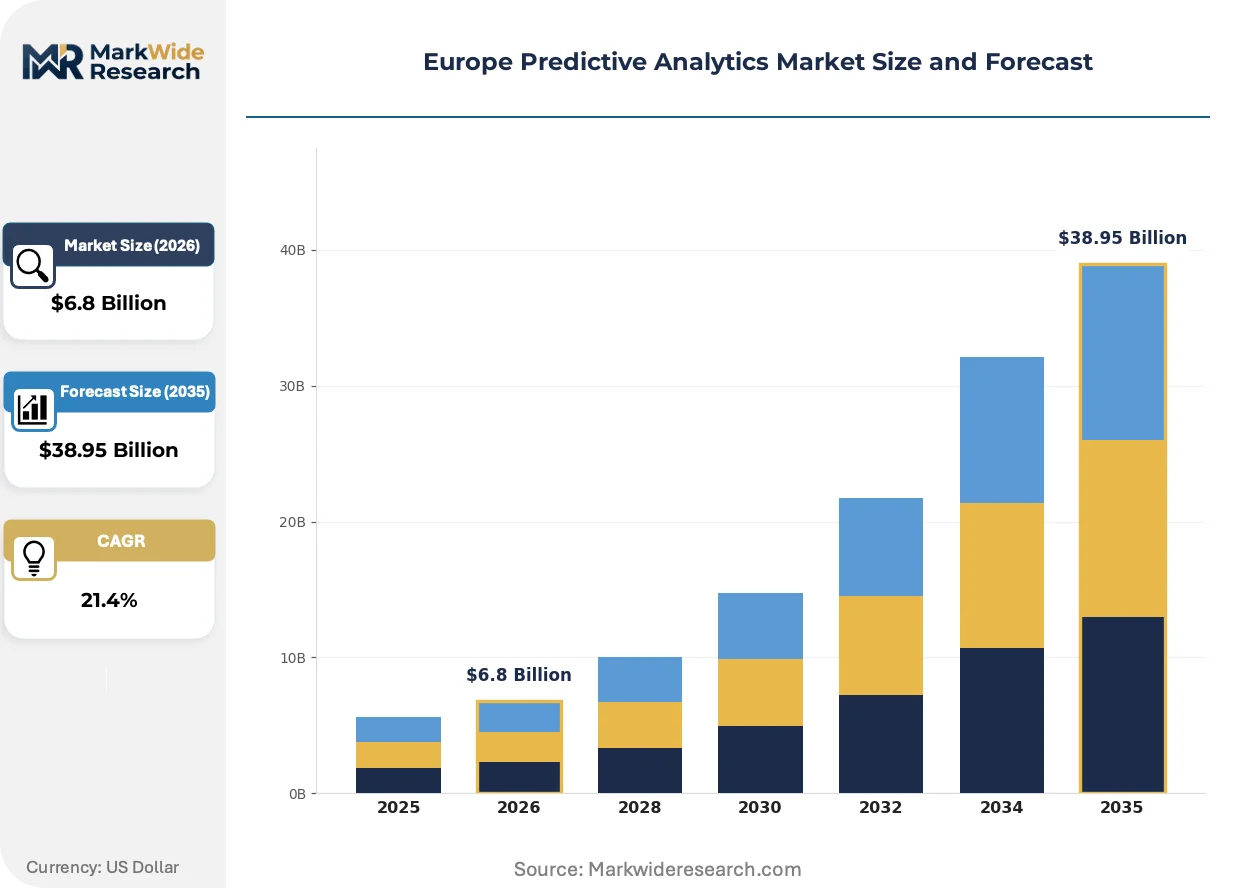
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $38.95 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
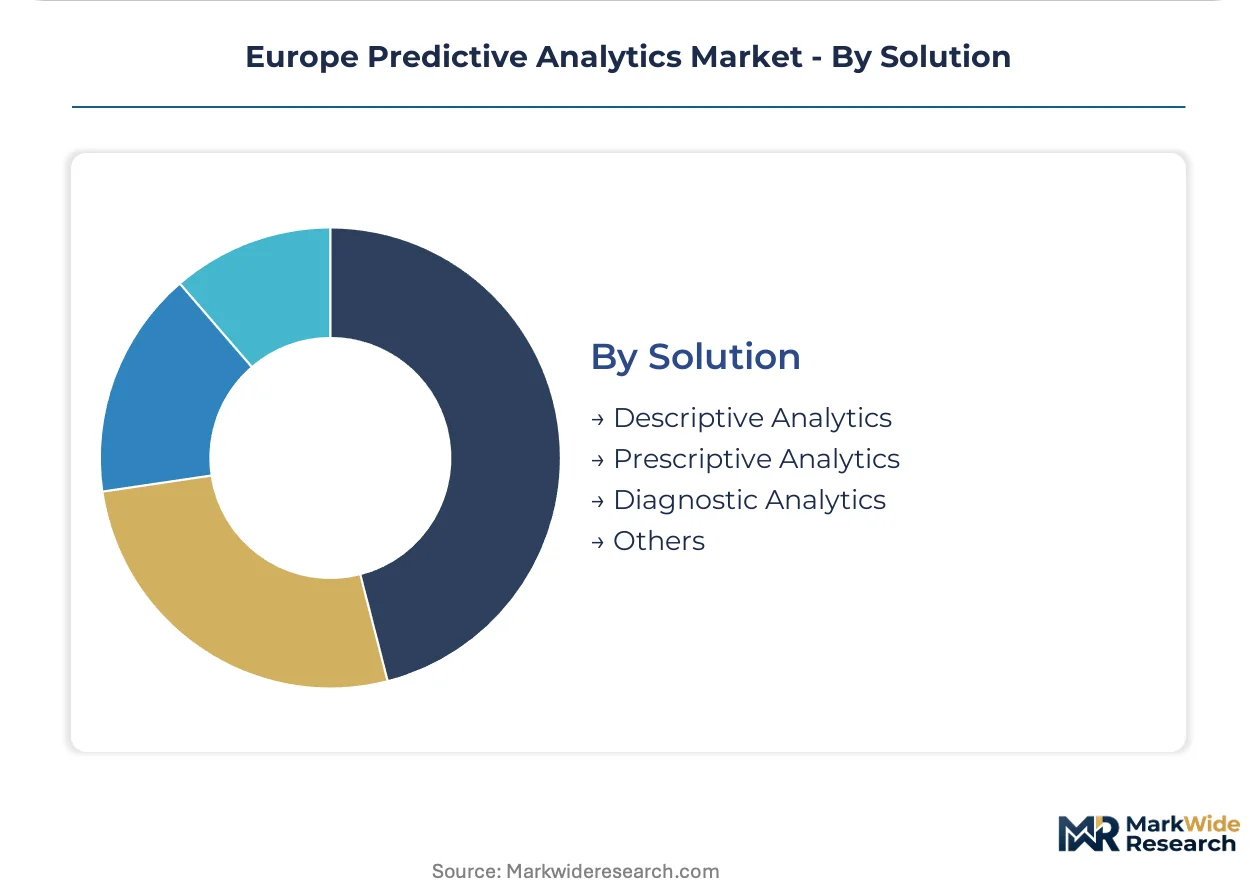
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services Application: Risk Management, Customer Analytics, Marketing Forecasting, Supply Chain Optimization End User: Manufacturing, Retail, BFSI, Healthcare Solution: Descriptive Analytics, Prescriptive Analytics, Diagnostic Analytics, Others |
| Companies Covered | IBM Corporation, SAS Institute Inc., SAP SE, Oracle Corporation, Microsoft Corporation, TIBCO Software Inc., NTT Data Corporation, Fair Isaac Corporation, Google LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Predictive Analytics Market Shifts & Advancements
Deployment architectures are splitting between cloud-native scalability and edge-constrained latency requirements, while regulatory pressure accelerates investment in explainable AI methods.
Explainable AI techniques are bifurcating the competitive landscape between black-box accuracy and interpretable model architectures. German automotive suppliers prioritize SHAP-value transparency for regulatory defensibility over marginal predictive gains. This technical split is compressing vendor differentiation to integration depth rather than algorithmic performance alone.
The EU AI Act's risk-based classification system imposes documentation burdens on high-risk applications in credit scoring and recruitment. Vendors must maintain technical files and conformity assessments that mirror medical device pathways. French and Dutch banking supervisors are interpreting these requirements most strictly, forcing earlier compliance investments than in Southern Europe.
Subscription pricing for predictive modules is displacing perpetual licenses among mid-market manufacturers. Industrial buyers in Spain and Italy now favor consumption-based arrangements tied to measurable downtime reduction. This purchasing shift is most visible in metalworking and packaging machinery sectors where capital constraints dominate procurement decisions.
Europe Predictive Analytics Market Segmentation
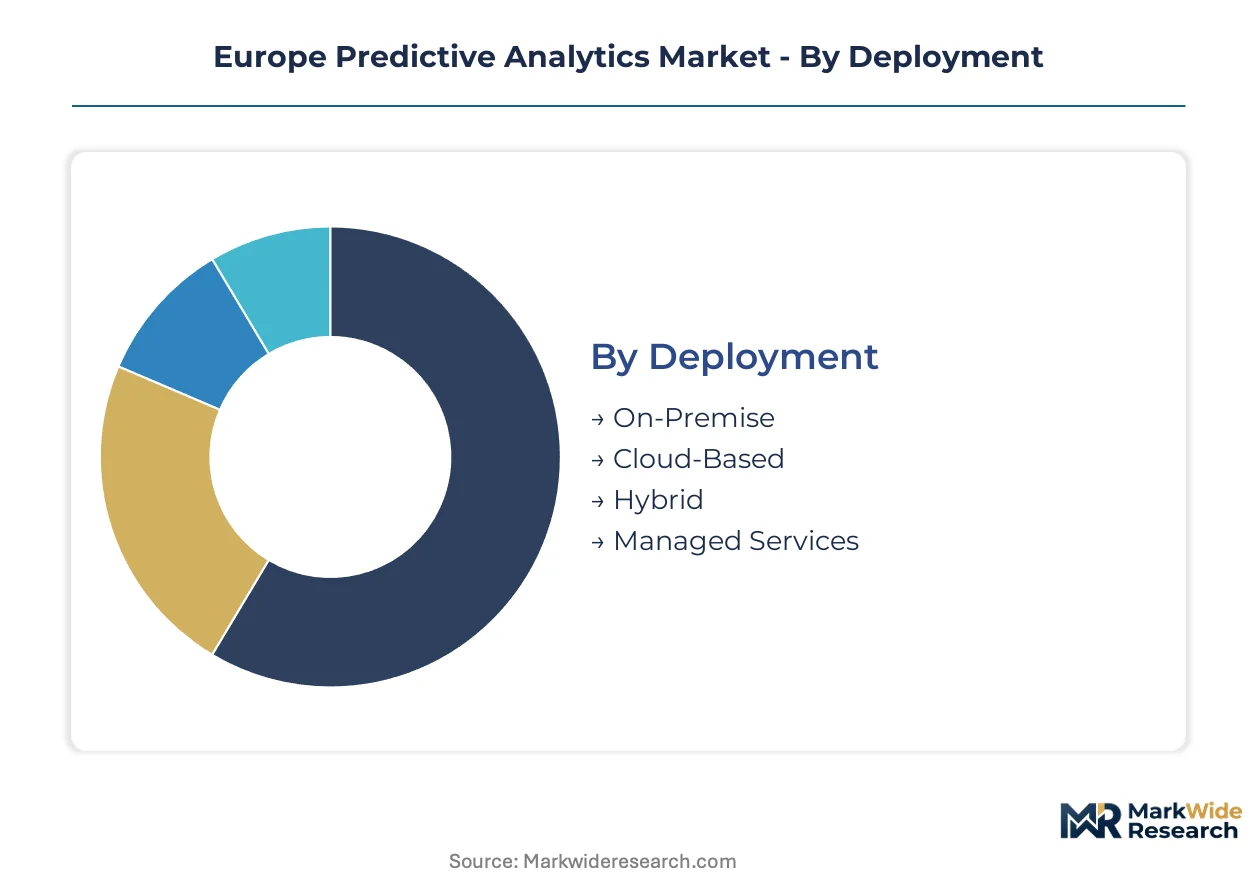
Predictive analytics procurement across Europe fragments along deployment architecture, regulatory exposure, and solution maturity. Buyers in Germany, France, and the Netherlands weight these dimensions differently based on industry-specific compliance obligations and legacy infrastructure constraints.
Deployment:
GDPR's cross-border data transfer restrictions and the EU AI Act's risk classification system create divergent infrastructure requirements across European Economic Area jurisdictions.
- Cloud-Based:Scalable compute resources enable real-time model inference without capital-intensive hardware procurement. German automotive suppliers in Baden-Württemberg prioritize cloud-native architectures for predictive maintenance workloads, though supervisory scrutiny of transatlantic data flows constrains vendor selection.
- Hybrid:Split processing between on-premise sensitive data and cloud-based model training addresses ECB model risk guidelines for banking clients. French and Dutch banking supervisors mandate documented data residency controls that hybrid architectures satisfy more readily than pure cloud deployments.
- On-Premise:Air-gapped installations persist in defense-adjacent manufacturing and Swiss pharmaceutical quality control where data sovereignty requirements override cost considerations.
- Managed Services:Outsourced model operations appeal to mid-market Spanish and Italian manufacturers lacking internal MLOps capabilities, with pricing tied to uptime reduction metrics.
Established volume favors Cloud-Based; emerging adoption favors Hybrid.
Application:
Margin concentration aligns with regulatory complexity rather than transaction volume alone.
- Risk Management:Credit scoring, fraud detection, and insurance underwriting models face mandatory conformity assessments under EU AI Act high-risk system definitions. ECB stress-testing frameworks extend validation timelines but lock in multi-year vendor relationships for compliant platforms.
- Customer Analytics:Real-time personalization engines process streaming behavioral data across digital retail channels. GDPR consent management requirements fragment data lakes, favoring vendors with privacy-preserving federated learning capabilities.
- Supply Chain Optimization:Demand forecasting and inventory positioning tools gain traction among Polish and Czech industrial firms seeking to narrow the gap with German predictive maturity.
- Marketing Forecasting:Campaign attribution models compete for budget with established business intelligence dashboards, with adoption concentrated in UK-headquartered retail chains operating across EEA markets.
Margin capture concentrates in Risk Management; steepest expansion trajectory appears in Customer Analytics.
End User:
Industry-specific validation protocols and data infrastructure maturity shape procurement velocity.
- BFSI:Banking and insurance carriers operate under the strictest algorithmic governance requirements, with French and Dutch supervisors interpreting EU AI Act documentation burdens most aggressively. Legacy core banking systems necessitate expensive middleware for model integration.
- Manufacturing:Predictive maintenance and quality control applications dominate German industrial clusters, with SAP-integrated deployments commanding premium pricing. Eastern European metalworking and packaging machinery sectors remain underpenetrated.
- Healthcare:Clinical decision-support tools require EMA algorithmic validation that only a handful of vendors have achieved, creating first-mover advantages in a high-barrier segment.
- Retail:Dynamic pricing and inventory optimization drive demand among grocery and fashion chains, with Spanish and Italian buyers favoring consumption-based pricing arrangements.
Compliance investment intensity peaks in BFSI; manufacturing delivers the broadest addressable base.
Solution:
Maturity gradients separate descriptive baseline capabilities from prescriptive optimization engines.
- Descriptive Analytics:Historical pattern visualization and diagnostic dashboards constitute the installed base across European enterprises, increasingly bundled as table stakes rather than premium offerings.
- Prescriptive Analytics:Optimization engines that recommend specific actions command pricing premiums in supply chain and resource allocation use cases, with German automotive suppliers driving specification requirements.
- Diagnostic Analytics:Root-cause analysis tools bridge descriptive baselines and predictive forecasting, with strongest penetration in industrial quality control workflows.
- Others:Emerging categories including causal inference and simulation-based scenario planning capture experimental budgets from advanced manufacturing and pharmaceutical R&D operations.
Revenue concentration remains in Descriptive Analytics; capability differentiation shifts toward Prescriptive Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Cologne rail corridor and Rhine River logistics artery underpin Germany's central role in European predictive analytics deployment, connecting industrial clusters across the continent's densest manufacturing belt.
Germany
Automotive suppliers in Baden-Württemberg and Bavaria drive predictive maintenance adoption integrated with SAP ERP systems. The KBA automotive regulator influences algorithmic validation standards for industrial AI applications. Stuttgart's manufacturing belt hosts the densest concentration of cloud-native predictive deployments for quality control and supply chain optimization.
France
Paris-based banking groups and insurers deploy risk-scoring models under strict CNIL data protection oversight. The EU AI Act's high-risk system classification faces its most aggressive supervisory interpretation from French regulators. Île-de-France's fintech corridor concentrates vendor development for compliance-heavy financial services applications.
United Kingdom
London-headquartered retail chains process streaming customer data for real-time personalization across EEA digital channels. The Information Commissioner's Office enforces GDPR consent management requirements that fragment data lake architectures. The M4 corridor tech cluster anchors development of privacy-preserving federated learning capabilities.
Netherlands
Amsterdam's logistics hub operators optimize container routing through demand forecasting algorithms. Dutch banking supervisors mandate documented data residency controls that favor hybrid deployment architectures. The Eindhoven-Brabant technology belt concentrates industrial IoT sensor deployments feeding predictive quality control systems.
Poland
Warsaw-based manufacturers seek predictive maturity gains in quality control and inventory positioning. The country's national data protection authority applies GDPR cross-border transfer rules that constrain cloud vendor selection. Silesian industrial zones remain underpenetrated for predictive maintenance relative to German benchmarks, creating expansion headroom.
Europe Predictive Analytics Market Competitive Landscape
Listed leaders compete with private specialists across compliance certification depth and ERP integration breadth. The vendor base stratifies between scale-driven cloud platforms and domain-specific algorithm developers. Three archetypes dominate: ERP-anchored industrial specialists, risk-scoring compliance leaders, and horizontal cloud ML providers. Competitive moves concentrate on strategic partnerships for data connector development and geographic expansion into underpenetrated Eastern European manufacturing markets.
Within the ERP-anchored tier, SAP SE exemplifies deep manufacturing system integration, while SAS Institute Inc. occupies the specialized risk-scoring position for banking compliance workflows. Microsoft Corporation represents the horizontal cloud provider archetype competing on hybrid deployment flexibility. These three anchors illustrate how vendor differentiation compresses toward integration depth rather than algorithmic performance alone.
| Leading Market Players |
|---|
| IBM Corporation |
| SAS Institute Inc. |
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| TIBCO Software Inc. |
| NTT Data Corporation |
| Fair Isaac Corporation |
| Google LLC |
| Others |
Supply & Pricing Matrix
Ninety-day implementation timelines for SAP-integrated predictive modules compress vendor margins while amplifying pricing power for established ERP-anchored providers. This lead-time band concentrates procurement decisions around pre-certified platforms, embedding supply-chain dependencies into long-term subscription arrangements that resist price negotiation.
Pricing Analysis
Volume-discount tiering structures separate enterprise deployments exceeding five hundred nodes from mid-market SaaS arrangements and managed-service contracts tied to uptime metrics. Certification grade under EU AI Act high-risk system classifications commands premium positioning, while consumption-based arrangements for Polish and Czech manufacturers face downward pressure from capital-constrained procurement committees. French banking groups exhibit lowest price sensitivity due to mandatory compliance investments, whereas Spanish metalworking sectors prioritize measurable downtime reduction over feature depth.
Supply Chain Analysis
Germany and the Netherlands anchor predictive analytics platform development, with Baden-Württemberg industrial clusters hosting dense concentrations of SAP-integrated deployment specialists. Cloud infrastructure draws from hyperscaler facilities in Ireland and Frankfurt, while algorithmic IP development centers on Paris and London regulatory technology corridors. Single-source vulnerability concentrates in proprietary ERP connector development for automotive supplier integrations. Distribution runs through systems integrators with vertical expertise in banking compliance and manufacturing maintenance workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MLOps engineering talent scarcity across France and the Netherlands extends implementation timelines by six to twelve months, constraining vendor scaling velocity and inflating professional services premiums. This capability gap rewards firms with pre-built regulatory compliance documentation and established supervisor relationships.
For Market Incumbents: Fortify algorithmic transparency documentation to preempt stricter French and Dutch supervisory interpretations of EU AI Act technical file requirements. Deepen vertical integration into edge-deployment hardware partnerships to capture latency-sensitive manufacturing workloads escaping pure cloud architectures. Lock in multi-year relationships with German automotive suppliers through SAP-native module development that raises switching costs for challenger platforms. For New Entrants and Emerging Players: EMA algorithmic validation fast-tracks for clinical decision-support tools open first-mover positioning in healthcare segments where incumbent certification lags. Polish and Czech manufacturing quality control applications remain underpenetrated relative to German benchmarks, offering white-space entry through consumption-based pricing aligned with downtime reduction metrics. Channel partnerships with regional systems integrators accelerate credibility building without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified technology conglomerates with underutilized predictive analytics divisions lacking vertical-specific compliance depth. Long-term viability hinges on regulatory certification moats rather than algorithmic performance differentiation alone. Monitor ECB stress-testing framework evolutions as inflection signals for banking vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Technical file documentation satisfies French CNIL and Dutch banking supervisor mandates ahead of competitors. |
| SAP ERP Native Integration | Pre-built connectors capture German automotive supplier procurement budgets with reduced implementation risk. |
| Hybrid Deployment Architecture | Split processing models address ECB data residency requirements for French and Dutch banking clients. |
| EMA Algorithmic Validation | Clinical decision-support certification creates defensible positioning in high-barrier healthcare segments. |
| Eastern European Channel Expansion | Regional systems integrator partnerships unlock Polish and Czech manufacturing penetration without direct sales overhead. |
Research Methodology
Initial hypotheses were tested against primary input from banking risk officers, manufacturing IT directors, healthcare compliance leads, and cloud procurement specialists and refined through secondary validation against ECB stress-testing documentation, EMA algorithmic validation guidelines, EU AI Act implementing acts, SAP partner ecosystem disclosures, and hyperscaler regional infrastructure announcements. Bottom-up deployment estimates triangulated with top-down addressable market calculations across the European Economic Area.
Variance-decomposition framing separated growth contributions from regulatory compliance mandates, cloud migration velocity, and vertical-specific adoption curves. Segmentation dimensions modeled encompass deployment architecture, application type, end-user industry, solution maturity tier, and country-level supervisory stringency. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with inputs including GDPR enforcement intensity indices and manufacturing automation investment surveys.
Decision-makers should treat outputs as directional under sustained EU AI Act implementation timelines and stable transatlantic data transfer arrangements; material deviation in supervisory interpretation stringency or cross-border cloud governance would warrant model refresh. Recalibration cycles align with material shifts in ECB model risk framework updates and EMA validation pathway revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Prescriptive Analytics Market
Analytics
Middle East Geospatial Analytics Market
Analytics
AI Performance Marketing Market
Analytics
Imagery Analytics Market
Analytics
Hadoop Big Data Analytics Solution Market
Analytics
Regression Analysis Tool Market
Analytics
Data Mining Tools Market
Analytics
Data Analytics in Telecom Market
Analytics
Global Wi-Fi Analytics Market
Analytics
Embedded Analytics Software Market
Analytics
APAC Operational Intelligence Market
Analytics
Event Stream Processing Market
Analytics
Advanced Analytics Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
Predictive Analytics Market
Analytics
Brazil Big Data Analytics Market