
 United States ICT Market | 2026-2036
United States ICT Market Size, Share, and Industry Trends Forecast 2026-2036
United States ICT Market Analytics
Platform licensing revenue is reconfiguring margin pools away from perpetual software sales toward recurring subscription models. Microsoft Corporation leverages its Azure cloud infrastructure to anchor enterprise workloads across hybrid environments. Amazon Web Services dominates public cloud capacity expansion through hyperscale data center investments. Oracle Corporation specializes in database-to-cloud migration services that sustain high-margin support contracts.
Information and communications technology encompasses computing hardware, software applications, telecommunications equipment, and data networking infrastructure operating across standardized protocols with throughput measured in terabits per second. Its primary commercial purpose is enabling digital transaction processing, real-time collaboration, and automated decision systems across organizational boundaries. Software and cloud services segments capture the majority of value-added margins as enterprises shift capital expenditure to operational expenditure models. Hardware and networking categories remain volume-intensive with compressed margins concentrated among semiconductor fabricators and original equipment manufacturers.
FCC spectrum allocation rules shape wireless infrastructure deployment timelines while NIST cybersecurity frameworks mandate zero-trust architecture adoption across federal contractors. FedRAMP authorization requirements create compliance barriers that filter vendor participation in government cloud procurement. SEC disclosure rules on material cybersecurity incidents are elevating board-level accountability for technology risk management. Stakeholders must monitor evolving AI governance standards from NIST and emerging state-level data privacy statutes to anticipate compliance cost trajectories.
Market Dynamics
FedRAMP authorization requirements are compressing vendor participation windows while accelerating cloud procurement consolidation across federal agencies. This regulatory filter is reshaping competitive positioning by elevating compliance infrastructure as a primary barrier to entry.
Growth Catalysts
- Zero-trust architecture mandates:NIST cybersecurity frameworks require federal contractors to reconfigure network access protocols. Defense and civilian agencies are driving infrastructure refresh cycles.
- Hyperscale data center expansion:Northern Virginia and California Bay Area corridors concentrate enterprise AI workload demand. Power density requirements above 50kW per rack are pulling specialized cooling and fiber investments.
- AI-integrated software suites:Enterprise buyers in financial services and healthcare are consolidating vendor relationships around platforms embedding predictive analytics and automated decision workflows.
Market Restraints
- Semiconductor supply concentration:Advanced logic and memory fabrication remains concentrated in East Asian foundry networks. Geographic risk exposure constrains domestic capacity scaling timelines.
- FedRAMP authorization friction:The certification timeline averages 12-18 months for moderate-impact systems. This duration filters smaller vendors from federal cloud procurement pools.
- Legacy system integration debt:Mainframe-dependent agencies in Treasury and Social Security face architectural lock-in. Migration costs compound with each deferred modernization cycle.
Strategic Opportunities
- State-level data privacy statutes:California CCPA amendments and emerging Virginia, Colorado frameworks create compliance tooling demand. Legal-tech vendors are embedding automated data mapping.
- Edge computing convergence with 5G:FCC mid-band spectrum auctions enable low-latency industrial IoT applications. Manufacturing and logistics verticals in Michigan and Ohio represent early deployment zones.
- Outcome-based infrastructure contracts:State governments are piloting availability-payment models for broadband expansion. Rural utility cooperatives are emerging as alternative deployment vehicles.
Industry Challenges
- Cloud architecture specialization scarcity:FedRAMP-certified engineers and zero-trust implementers command premium compensation. Workforce pipeline constraints limit delivery velocity for systems integrators.
- Multi-cloud orchestration complexity:Enterprise buyers are fragmenting workloads across Azure, AWS, and Google Cloud environments. Interoperability tooling and cost governance remain immature.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States ICT Market |
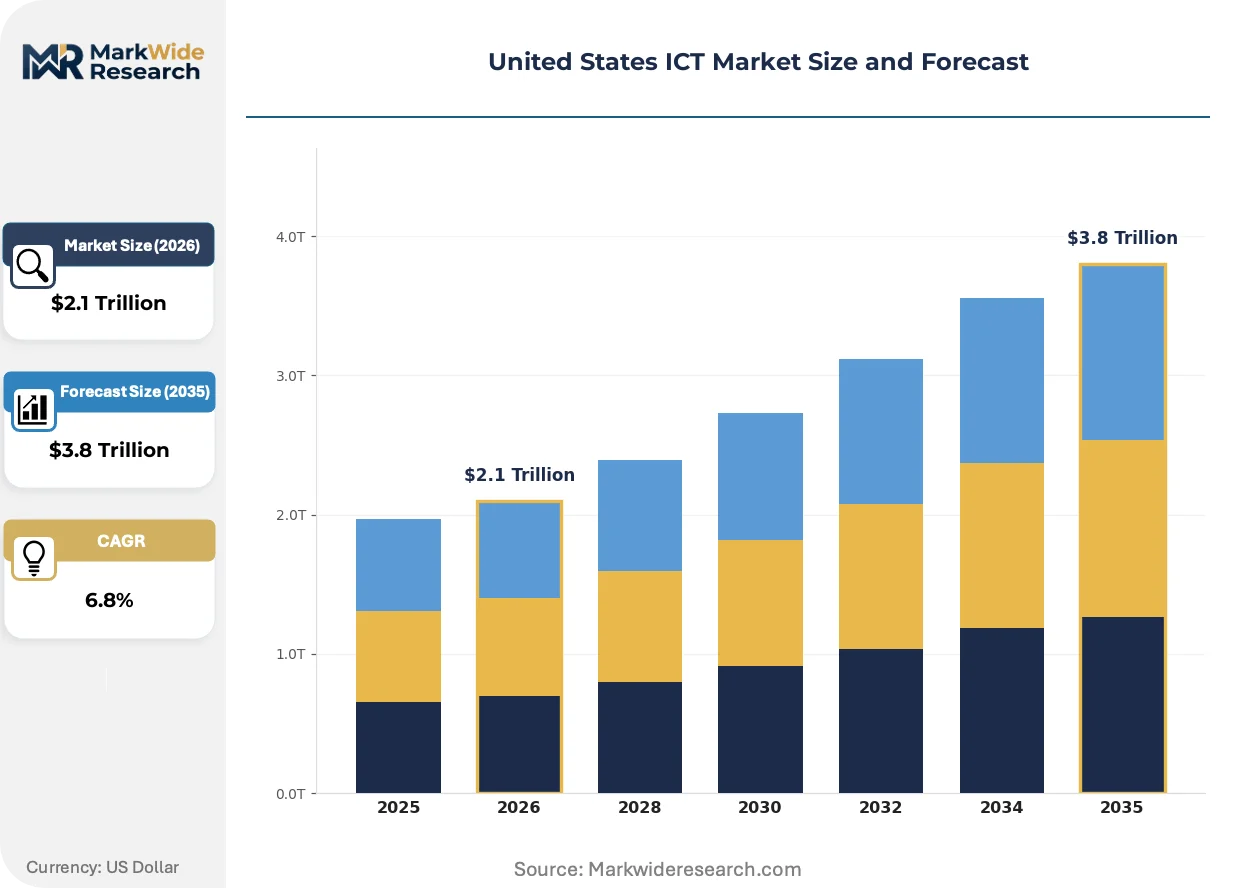
| Market Size in 2026 | $2.1 Trillion |
| Market Size in 2035 | $3.8 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Networking End User: Government, Education, Healthcare, Enterprises Technology: Cloud Computing, IoT, AI, Cybersecurity Sales Channel: Direct Sales, Distributors, Online Sales, Resellers |
| Companies Covered | IBM Corporation, Oracle Corporation, Microsoft Corporation, Intel Corporation, Cisco Systems Inc., Amazon Web Services (Amazon.com Inc.), Apple Inc., Cognizant Technology Solutions Corporation, Google LLC (Alphabet Inc.), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States ICT Market Evolving Landscape
Generative AI capabilities are compressing software development cycles and reconfiguring enterprise productivity tool categories. Federal procurement officers and commercial CIOs are simultaneously reassessing vendor roadmaps and internal reskilling priorities.
Software-defined networking is digitizing enterprise WAN architecture by abstracting hardware control planes into programmable overlays. Financial services firms and healthcare systems are adopting SASE frameworks at accelerated cadences. This transition is digitizing traffic management and security policy enforcement while compressing router and firewall refresh cycles.
FCC spectrum allocation rules are restructuring wireless infrastructure investment timelines by auctioning 2.5 GHz and 3.45 GHz bands for 5G deployment. Tower companies and mobile network operators are redirecting capital toward mid-band coverage densification. Rural broadband subsidy programs are pulling equipment procurement toward open RAN architectures.
Enterprise buyers are consolidating software vendor relationships around integrated platform suites rather than best-of-breed point solutions. Procurement teams in Fortune 500 firms are negotiating enterprise-wide licensing agreements with Microsoft, Salesforce, and ServiceNow. This concentration is most visible in California and New York headquarters locations where CIOs prioritize vendor reduction over feature depth.
United States ICT Market Segmentation
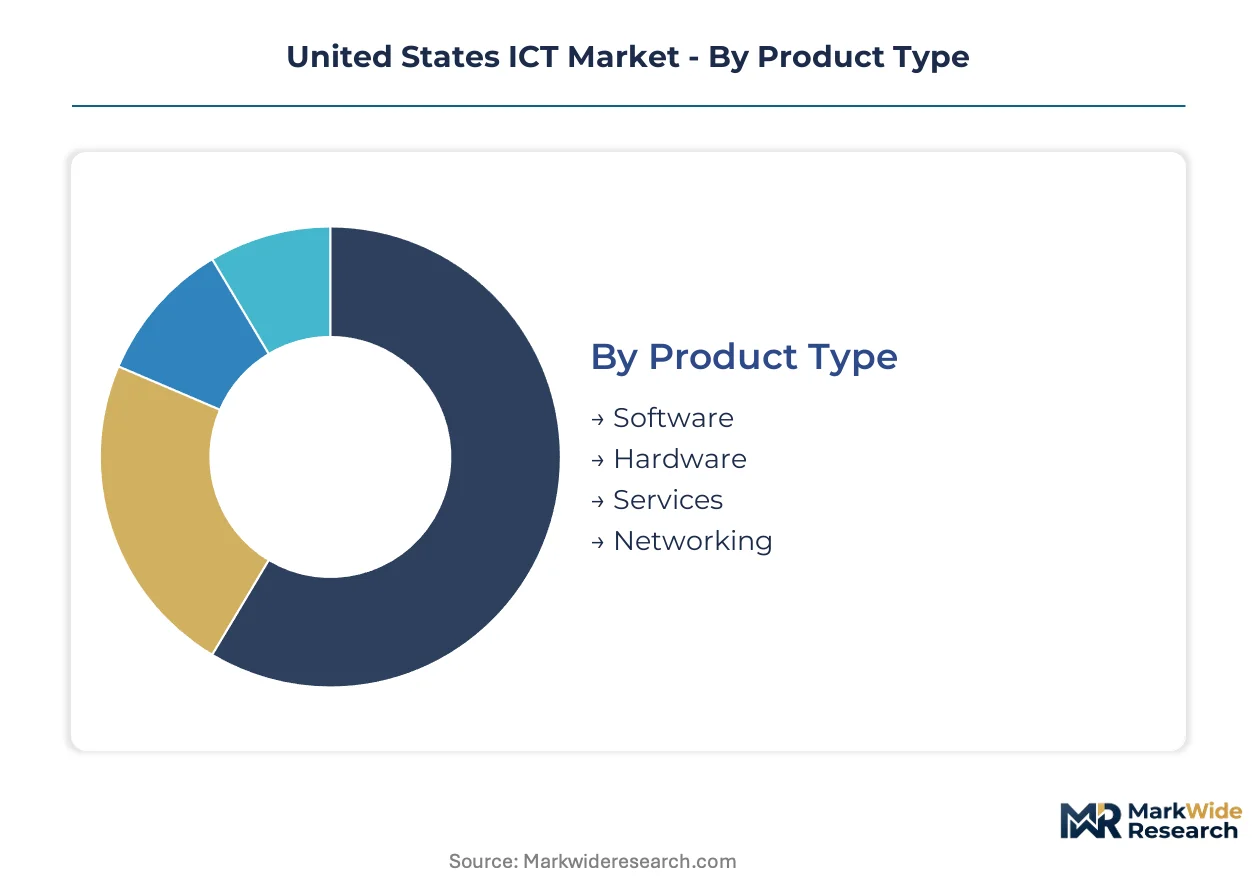
Segmentation in the United States ICT market reveals distinct procurement rhythms and margin structures across product categories, end-user verticals, and delivery mechanisms. Each dimension carries different renewal cycles, compliance burdens, and vendor concentration patterns that shape go-to-market economics.
Product Type:
Cycle times vary dramatically across this dimension—hardware refreshes compress to 3-5 year intervals while services contracts extend across multi-year engagements with annual true-ups.
- Software:Cloud-native applications and AI-integrated suites now dominate enterprise procurement. Federal agencies under FedRAMP mandates and healthcare systems in Texas and Florida are consolidating around subscription platforms that embed automated compliance tooling.
- Hardware:Server, storage, and endpoint equipment face compressed margins as hyperscale buyers internalize direct procurement. Semiconductor supply constraints from East Asian foundries continue shaping domestic availability for enterprise data center builds.
- Services:Systems integration and managed services capture value from cloud migration complexity. Federal contractors in Northern Virginia command premium pricing for zero-trust implementation and FedRAMP certification support.
- Networking:Software-defined WAN and SASE architectures are displacing traditional router refresh cycles. Financial services firms in New York and Chicago are accelerating adoption of programmable network overlays.
Hardware dominates installed base by revenue volume. Software is where expansion concentrates as enterprises shift capital expenditure to operational expenditure models.
End User:
Procurement sophistication and compliance requirements create four distinct customer tiers with varying contract structures and sales cycle lengths.
- Government:Federal, state, and local agencies operate under FedRAMP, FISMA, and state-level data privacy mandates. Defense and civilian cloud procurement is consolidating around authorized vendors with established compliance infrastructure.
- Education:K-12 districts and university systems leverage E-rate subsidies for connectivity investments. California and Texas public university systems are piloting AI-enabled learning platforms at scale.
- Healthcare:HIPAA-covered entities and business associates face intensified OCR enforcement on data breach notifications. Hospital systems in Pennsylvania and Ohio are consolidating electronic health record platforms around cloud-hosted alternatives.
- Enterprises:Fortune 500 firms in financial services, manufacturing, and retail drive platform consolidation. Procurement teams in California and New York headquarters negotiate enterprise-wide licensing with reduced vendor counts.
Enterprises dominate current spending volume. Government represents the steepest expansion trajectory as modernization mandates accelerate procurement timelines.
Technology:
Technology segments align with distinct infrastructure layers, each carrying different integration complexity and talent scarcity profiles.
- Cloud Computing:Public, private, and hybrid deployments now underpin most enterprise workloads. Northern Virginia and California Bay Area data center corridors concentrate hyperscale capacity expansion.
- IoT:Industrial sensor networks and connected device fleets require edge computing convergence. Manufacturing verticals in Michigan and Ohio are deploying predictive maintenance systems at scale.
- AI:Machine learning platforms and generative AI capabilities are compressing software development cycles. Financial services and healthcare buyers are embedding predictive analytics into core workflows.
- Cybersecurity:Zero-trust architecture mandates from NIST are reconfiguring federal contractor infrastructure. FedRAMP-certified security engineers command compensation premiums that constrain delivery velocity.
Cloud Computing anchors current infrastructure investment. AI is climbing the fastest as enterprise buyers reassess vendor roadmaps and internal reskilling priorities.
Sales Channel:
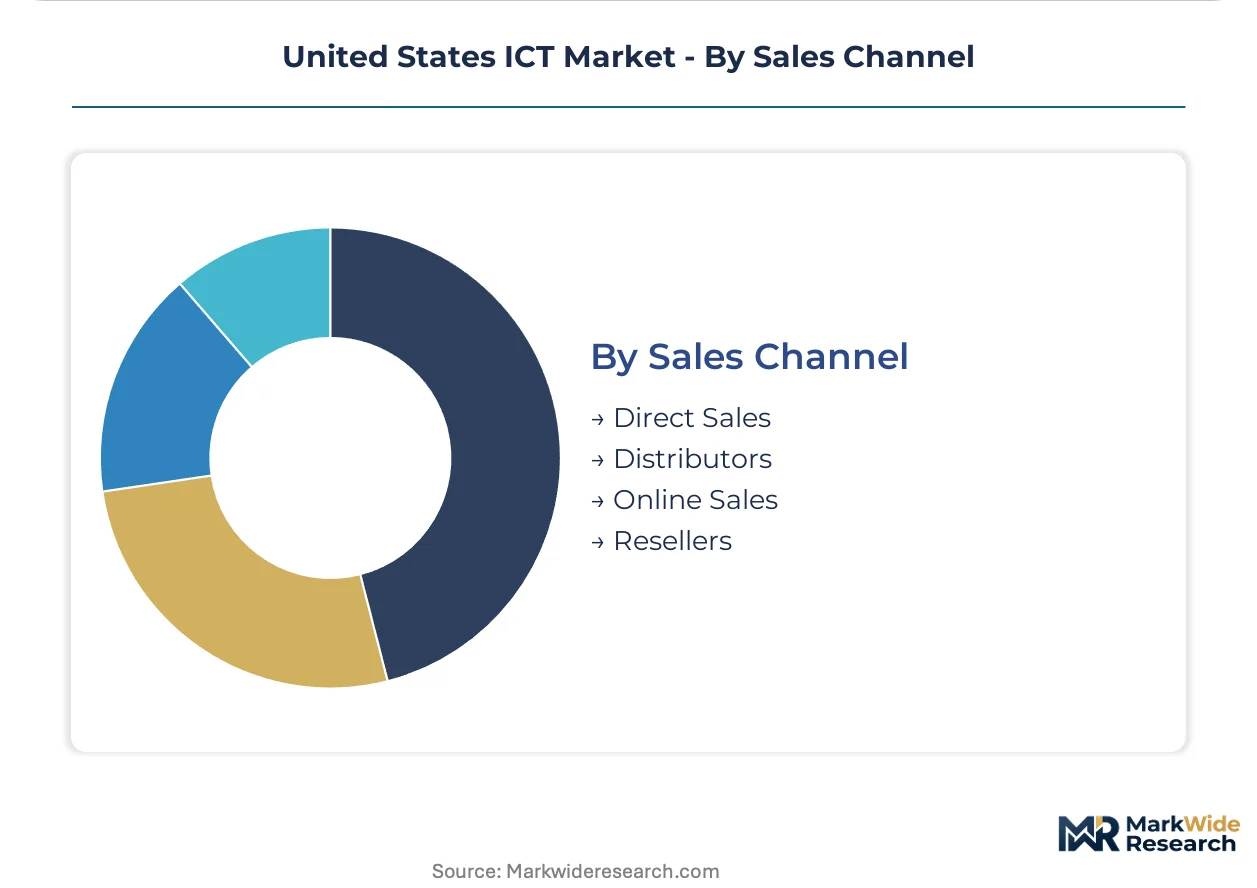
Channel economics reflect customer scale and solution complexity, with direct relationships capturing the largest accounts and partner networks extending geographic reach.
- Direct Sales:Vendor field organizations engage Fortune 500 and federal accounts with customized solution architectures. Microsoft, Amazon Web Services, and Oracle maintain dedicated federal sales teams in Washington DC metro.
- Distributors:Broadline and specialty distributors aggregate procurement for mid-market enterprises and state government accounts. Ingram Micro and TD Synnex maintain inventory positioning for rapid hardware fulfillment.
- Online Sales:Self-service portals capture standardized software subscriptions and cloud capacity. Small and medium businesses in dispersed geographies default to digital procurement for speed.
- Resellers:Value-added resellers provide implementation services and local support relationships. Regional systems integrators in Texas and Georgia specialize in vertical-specific compliance requirements.
Direct Sales captures the largest contract values. Resellers are gaining share fastest as solution complexity drives demand for localized implementation expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in Northern Virginia and California demonstrate low price elasticity for FedRAMP-authorized cloud services, while state governments in the Midwest and Southeast remain highly sensitive to per-seat licensing costs. This demand-elasticity contrast shapes vendor go-to-market economics across sub-regional corridors.
California Bay Area
Hyperscale data center operators and AI-native startups drive infrastructure investment above 50kW per rack density thresholds. CPUC electricity rate structures and CEQA environmental review processes extend facility permitting timelines to 18-24 months. Santa Clara County and San Francisco anchor cloud capacity expansion with specialized liquid-cooling deployments.
Northern Virginia
Federal cloud procurement consolidation and defense contractor migration mandates concentrate demand in Loudoun and Prince William counties. FedRAMP authorization requirements filter vendor participation while elevating compliance infrastructure as a competitive barrier. Ashburn and Manassas data center clusters represent the densest fiber and power interconnection points in the eastern United States.
Texas Triangle
Enterprise headquarters relocations from California and New York pull software licensing volume into Dallas-Fort Worth, Austin, and Houston metros. State-level data privacy statutes remain less prescriptive than California CCPA, reducing compliance tooling procurement for mid-market buyers. Austin's technology corridor concentrates AI-integrated software suite adoption across financial services and healthcare verticals.
New York Metro
Financial services firms in Manhattan and Jersey City drive SASE architecture adoption and zero-trust network segmentation. NYDFS cybersecurity regulations mandate multi-factor authentication and encryption standards that elevate procurement specifications for cloud access brokers. Wall Street headquarters locations prioritize vendor consolidation over feature depth in enterprise licensing negotiations.
Pacific Northwest
Cloud infrastructure engineering talent concentration in Seattle and Portland sustains regional competitive positioning for hyperscale operators. Washington State's data center tax incentive program expires in 2026, compressing investment decision timelines for facility developers. Quincy and Umatilla anchor eastern Washington's low-cost hydroelectric-powered server farm clusters.
United States ICT Market Competitive Landscape
Capability concentration sits with specialized systems integrators possessing FedRAMP certification infrastructure; scale advantage sits with hyperscale cloud operators amortizing data center investments across global workloads. The vendor base stratifies into three tiers: compliance-heavy federal contractors, platform-scale cloud providers, and vertical-specific software specialists. Dominant competitive moves include strategic partnerships to accelerate authorization timelines and portfolio diversification into adjacent cybersecurity services.
Within the platform-scale tier, Microsoft Corporation and Amazon Web Services occupy positions anchoring hybrid and public cloud workload capture respectively. Oracle Corporation exemplifies the database-to-cloud migration specialist archetype, sustaining high-margin support contract structures. IBM Corporation represents the systems integrator archetype with entrenched federal contracting relationships. These three entities illustrate how vendor positioning fragments across infrastructure layers rather than consolidating around unified stacks.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Microsoft Corporation |
| Intel Corporation |
| Cisco Systems Inc. |
| Amazon Web Services (Amazon.com Inc.) |
| Apple Inc. |
| Cognizant Technology Solutions Corporation |
| Google LLC (Alphabet Inc.) |
| Others |
Value Network & Pricing Analysis
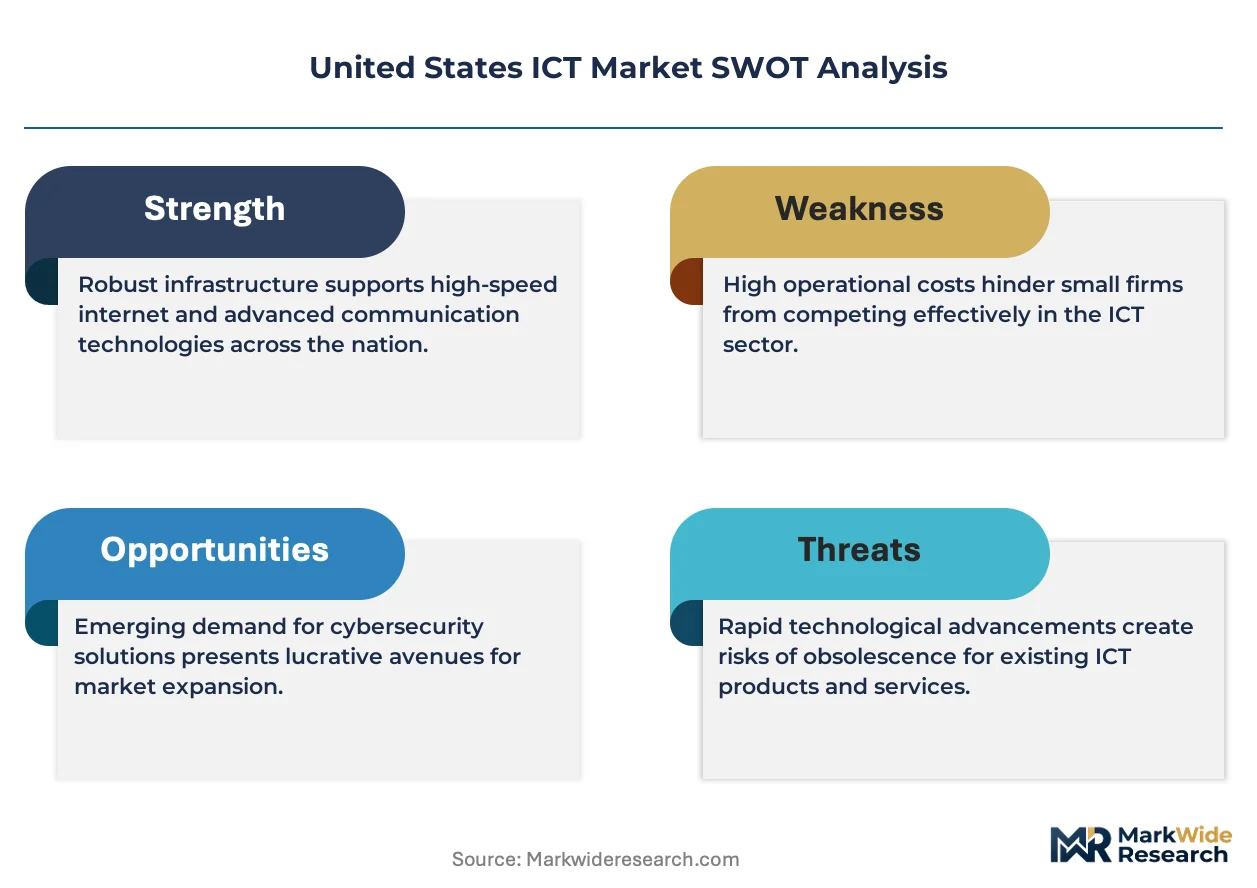
Northern Virginia's hyperscale data center corridor concentrates cloud capacity expansion, concentrating pricing power among FedRAMP-authorized vendors while compressing margins for uncertified competitors. Federal procurement consolidation around authorized providers elevates compliance infrastructure as a cost component passed through to agency buyers.
Pricing Analysis
Extended support and managed service contracts drive lifetime value for enterprise software vendors. Subscription-tiered pricing stratifies across premium FedRAMP-authorized tiers, standard commercial SaaS, and economy self-service portals. Cost compression in hardware categories stems from hyperscale buyers internalizing direct procurement. State government buyers in the Midwest exhibit highest price sensitivity to per-seat licensing, while defense contractors in Northern Virginia demonstrate lowest elasticity for authorized cloud services.
Supply Chain Analysis
Tariff exposure between the United States and China dominates semiconductor supply risk for domestic ICT infrastructure. Advanced logic and memory fabrication draws from Taiwan, South Korea, and China, with lithography equipment and rare earth elements feeding from concentrated East Asian sources. Single-source vulnerability in EUV lithography systems constrains domestic capacity scaling. Distribution runs through hyperscale direct procurement for enterprise buyers and value-added reseller networks for mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise buyer consolidation around integrated platform suites has shifted negotiating leverage toward Fortune 500 procurement teams, fragmenting vendor pricing power across the ICT stack.
For Market Incumbents: Pre-empt margin erosion in perpetual software sales by accelerating subscription platform transitions before federal agencies complete FedRAMP migration. Invest in zero-trust certification infrastructure to defend against emerging compliance-heavy systems integrators. Channel control through exclusive federal contracting relationships in Washington DC metro sustains pricing power.
For New Entrants and Emerging Players: State-level data privacy compliance tooling for Virginia and Colorado represents the most penetrable entry point for legal-tech vendors. Edge computing convergence with 5G in Michigan and Ohio manufacturing corridors offers second white-space target. Go-to-market through regional systems integrators specializing in vertical-specific compliance requirements bypasses direct competition with hyperscale platforms.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because FedRAMP authorization timelines create durable moats around certified vendors. Acquisition targets should screen for established federal contracting relationships and zero-trust implementation capabilities. Watch NIST AI governance standard finalization as signal for compliance tooling demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure anchors hybrid workloads across federal and commercial segments. |
| Strategic Partnership | FedRAMP authorization accelerators compress 12-18 month certification timelines. |
| Acquisition of Specialist Firm | Zero-trust implementers in Northern Virginia command premium valuation multiples. |
| Geographic Expansion | Texas Triangle headquarters relocations pull software licensing volume from coastal metros. |
| Product Launch | AI-embedded compliance tooling addresses California CCPA amendment requirements. |
Research Methodology
A standing panel of federal procurement officers, cloud platform engineers, systems integration specialists, and cybersecurity compliance leads provided ongoing calibration throughout the study period. Primary interviews with vendor sales executives and IT procurement directors at Fortune 500 firms combined with secondary validation from SEC filings, hyperscaler capital expenditure disclosures, and FCC spectrum auction records. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Scenario-bracketing around FedRAMP authorization velocity and semiconductor supply normalization shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs were derived from fitted growth curves applied to disclosed vendor revenue trajectories and federal IT budget appropriations.
Stress conditions across tariff escalation timelines, FedRAMP backlog clearance rates, and hyperscale data center permitting delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compliance cost trajectories and workforce pipeline constraints. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Account Based Marketing Market
Digital Solutions
North America IT Asset Disposition Market
Digital Solutions
Decision Support System Market
Digital Solutions
North America 3D Rendering Services Market
Digital Solutions
Customer-To-Customer (C2C) Community Market
Digital Solutions
Game Engines Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
Boat Navigation Software Market
Digital Solutions
Revenue Management Software Market
Digital Solutions
North America Online Dating Services Market
Digital Solutions
Electronic Data Interchange [EDI] Solution Market
Digital Solutions
Canada Digital Twin Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Global DDI Market
Digital Solutions
Legaltech Market
Digital Solutions
System Integrator Market