
 Mobile Tracking Solution Market | 2026-2036
Mobile Tracking Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Tracking Solution Market Outlook
Software-defined subscription tiers is broadening what fleet operators purchase, shifting hardware margins toward recurring analytics revenue. Verizon Communications Inc. leverages its cellular network density to bundle connectivity with tracking dashboards. CalAmp Corp. anchors its position through edge-computing telematics hardware that feeds cloud platforms. Trimble Inc. specializes in precision agriculture and construction tracking applications where GPS correction services command premium pricing.
Mobile tracking solutions integrate location sensors, wireless modems, and cloud software to monitor vehicle, asset, or personnel position in real time, typically achieving GPS accuracy within 3-5 meters under open sky conditions. These systems serve commercial fleets, supply chains, and public safety agencies by reducing theft, optimizing routes, and automating compliance documentation. Fleet Management applications lead in revenue contribution due to fuel-cost sensitivity and driver-hour regulations across logistics operators. GPS technology dominates installed volumes, though Bluetooth and Wi-Fi hybrid architectures are gaining traction in warehouse and last-yard environments where satellite signals degrade. Data Analytics services capture expanding margin pools as customers demand predictive maintenance and carbon-emission reporting beyond raw location feeds.
The FCC governs device certification and spectrum use for cellular-enabled trackers in the United States, while the EU AI Act and GDPR impose algorithmic transparency and consent requirements on automated location profiling across European deployments. California's CCPA extends similar data-rights obligations, compelling vendors to architect region-specific data residency and deletion capabilities. Stakeholders must monitor evolving cross-border data-localization mandates to determine whether centralized cloud architectures or federated edge-processing investments offer sustainable compliance pathways.
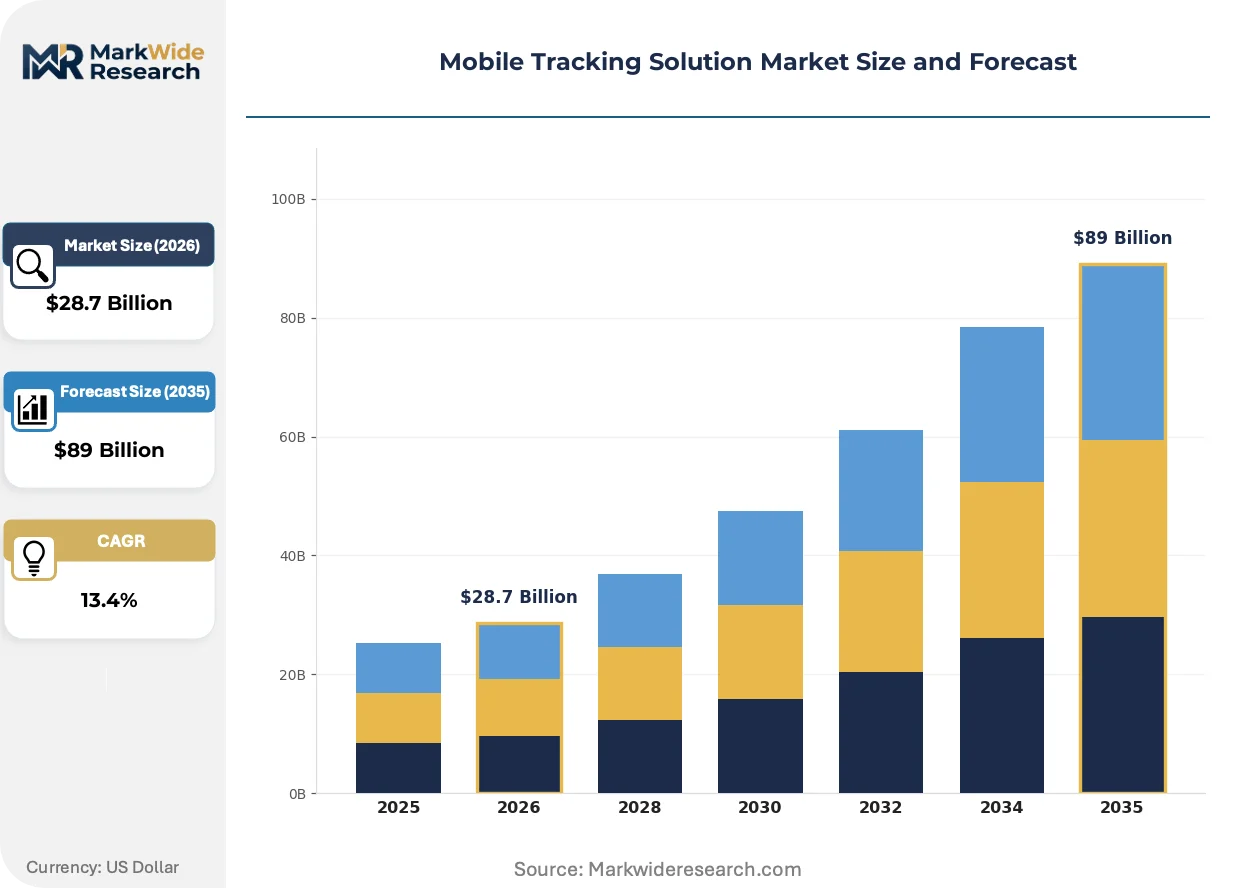
Market Dynamics
Fleet operators now demand predictive analytics layered atop raw location feeds, compressing hardware margins while elevating recurring software revenue as the dominant profit pool. This structural shift from device sales to subscription intelligence services is redrawing competitive boundaries across the mobile tracking value chain.
Growth Catalysts
- FCC E911 mandate:Cellular-enabled trackers require precise location capabilities, forcing device upgrades across public safety and commercial fleets in the United States.
- Automotive logistics corridor:Germany's OEM inbound parts networks require real-time asset visibility from tier-2 suppliers through final assembly gates.
- Edge-computing hardware:On-device processing reduces latency for critical alerts while lowering cellular data transmission costs for fleet managers.
Market Restraints
- Semiconductor supply concentration:GPS receiver chip fabrication clusters in Taiwan create vulnerability for tracker manufacturers facing allocation constraints.
- GDPR location-data friction:Cross-border fleet operations face consent management complexity when vehicles traverse multiple European jurisdictions.
- Battery chemistry volatility:Lithium-ion cell price swings directly impact portable tracker unit economics and margin stability.
Strategic Opportunities
- Carbon-emission reporting mandate:EU CSRD requirements create demand for fuel-consumption analytics bundled with location services.
- Bluetooth-Wi-Fi hybrid architectures:Warehouse and last-yard environments where satellite signals degrade offer expansion beyond traditional GPS-dominant applications.
- India logistics modernization:National highway corridor digitization and GST compliance enforcement drive fleet tracking adoption among domestic trucking operators.
Industry Challenges
- RF engineering talent scarcity:Cellular modem optimization and antenna design expertise concentrates among semiconductor vendors, limiting in-house hardware development capabilities for mid-tier tracker manufacturers.
- Legacy telematics integration:Fleet operators with embedded J1939 or OBD-II systems face protocol translation complexity when layering cloud analytics platforms atop existing vehicle bus architectures.
- Multi-jurisdiction certification timelines:FCC, CE marking, and carrier-specific PTCRB approvals create 9-14 month product launch cycles that compress first-mover advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Tracking Solution Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $89 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Fleet Management, Personal Tracking, Asset Tracking, Logistics Management Technology: GPS, RFID, Bluetooth, Wi-Fi End User: Logistics Companies, Transportation Providers, Retailers, Government Agencies Service Type: Real-time Tracking, Data Analytics, Reporting, Software Integration |
| Companies Covered | Verizon Communications Inc., ORBCOMM Inc., Spireon, Inc., CalAmp Corp., Cisco Systems, Inc., AT&T Inc., TomTom N.V., Trimble Inc., Sierra Wireless, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Tracking Solution Market Strategic Shifts
Software-defined functionality is dissolving the boundary between hardware and services, enabling fleet operators to purchase capabilities as consumable features rather than capital equipment. This architectural shift is compressing traditional device margins while expanding addressable revenue per installed unit.
Bluetooth and Wi-Fi positioning is overtaking GPS-dominant architectures in indoor and dense urban environments where satellite signal multipath creates location uncertainty. Warehouse operators and last-mile delivery fleets are adopting hybrid sensor fusion at accelerating pace. The structural consequence is fragmenting the tracker hardware market into specialized environment-optimized variants rather than universal outdoor-dominant devices.
Europe's GDPR and AI Act are imposing algorithmic transparency requirements on automated location profiling systems deployed across member states. Fleet analytics platforms must now document decision logic for route optimization and driver scoring models. Commercial fleet operators in Germany and France are responding by demanding vendor-provided compliance documentation as a procurement prerequisite.
Buyer purchasing patterns are compressing from multi-year capital leases toward month-to-month software subscriptions with hardware included as a service element. Logistics operators in North America are unbundling device ownership from data analytics access, treating location intelligence as an operational expense rather than balance-sheet investment. This shift is most pronounced among mid-sized fleet operators with 50-500 vehicles seeking to avoid technology obsolescence risk.
Mobile Tracking Solution Market Segmentation
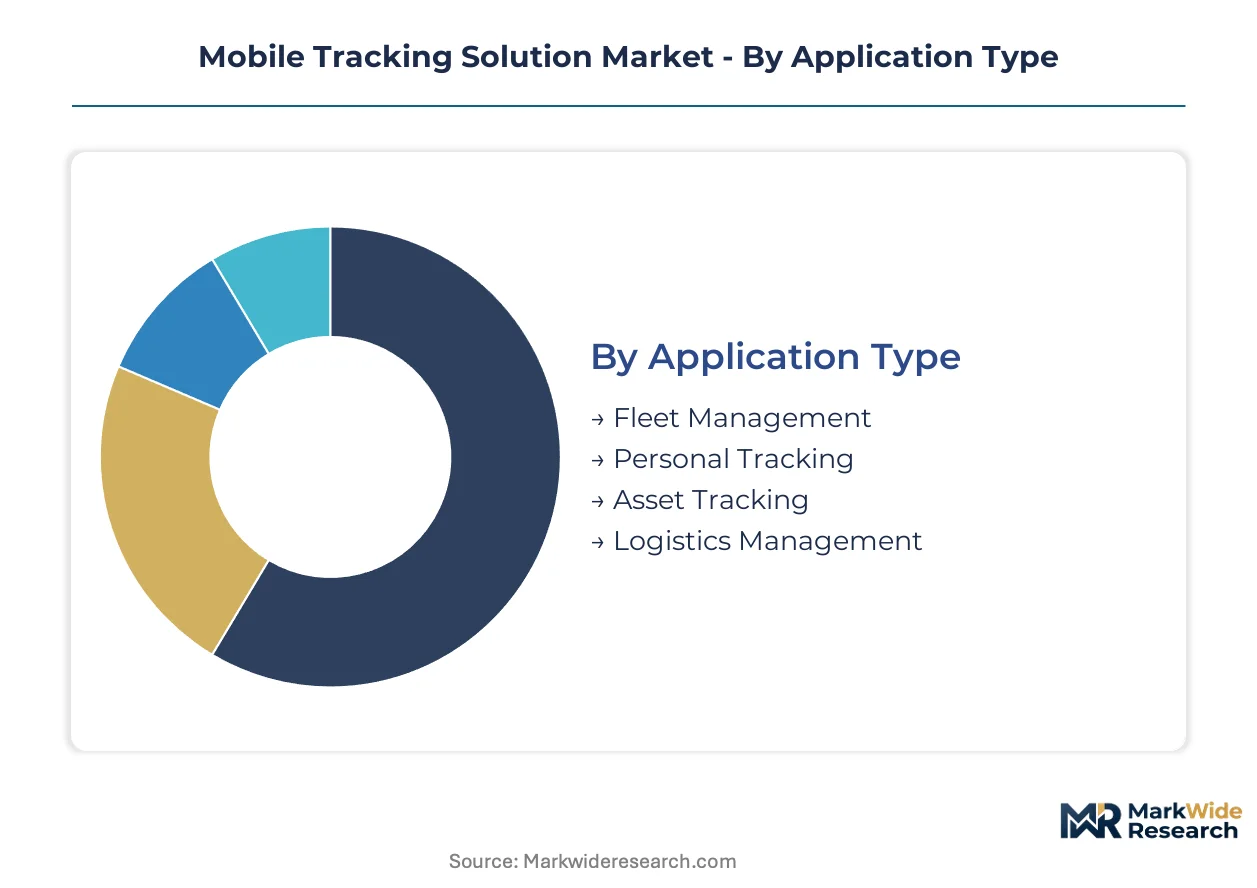
Segmentation reveals how capital deployment, technical requirements, and regulatory exposure vary across use cases in mobile tracking. Buyers with different operational scales and compliance obligations select fundamentally different solution architectures.
Application Type:
Fleet Management demands the heaviest upfront capital, requiring vehicle-installed hardware, cellular connectivity contracts, and cloud platform subscriptions at scale.
- Fleet Management:Systems integrate OBD-II or J1939 vehicle bus interfaces with cellular modems and cloud dashboards for fuel monitoring, route optimization, and driver-hour compliance. Demand concentrates among North American logistics operators facing FMCSA ELD mandates and diesel cost volatility.
- Asset Tracking:Battery-powered or solar-harvesting devices monitor non-powered equipment such as shipping containers, construction machinery, and agricultural implements. German automotive OEMs drive adoption across tier-2 supplier inbound parts networks where inventory visibility reduces line-down risk.
- Personal Tracking:Wearable or pocket-sized devices serve lone-worker safety, elderly care, and recreational applications with lower hardware margins but higher unit volumes.
- Logistics Management:Multi-modal platforms coordinate tracking across warehouse, yard, and in-transit environments through unified visibility layers.
Most installed capacity flows through Fleet Management. Expansion is steepest in Asset Tracking.
Technology:
Technology selection determines antenna complexity, power budgets, and indoor-outdoor performance tradeoffs that shape total cost of ownership.
- GPS:Satellite-based positioning achieves 3-5 meter accuracy under open sky through multi-constellation receivers processing GPS, GLONASS, Galileo, and BeiDou signals. Outdoor-dominant applications in agriculture, mining, and long-haul trucking anchor volume demand despite signal degradation in urban canyons and covered structures.
- Bluetooth:Low-energy beacons enable proximity detection and indoor positioning through received signal strength indicators and angle-of-arrival calculations. Warehouse operators in the United States deploy mesh networks for last-yard pallet location where satellite signals cannot penetrate.
- RFID:Passive and active radio-frequency identification supports high-throughput gate reads and item-level inventory tracking without battery dependence for passive tags.
- Wi-Fi:Access point fingerprinting and time-of-flight ranging provide indoor positioning accuracy competitive with Bluetooth in retail and logistics facilities with existing wireless infrastructure.
GPS dominates cumulative installed base. Bluetooth is gaining share fastest in hybrid indoor-outdoor deployments.
End User:
End user category dictates procurement sophistication, integration complexity, and compliance documentation requirements.
- Logistics Companies:Third-party carriers and freight brokers require multi-tenant platforms supporting customer-specific data segregation and API integrations with shipper TMS systems.
- Transportation Providers:Bus, rail, and ride-hail operators prioritize passenger-facing arrival predictions and regulatory compliance documentation for DOT or equivalent national regulators.
- Retailers:Omnichannel fulfillment networks track last-mile delivery fleets and high-value merchandise through unified inventory visibility systems.
- Government Agencies:Public safety, defense, and municipal fleet operators mandate FIPS 140-2 encryption or national equivalents and domestic data residency for sensitive personnel location data.
Logistics Companies represent the largest addressable spend. Government Agencies show the steepest expansion trajectory as defense and emergency services modernize.
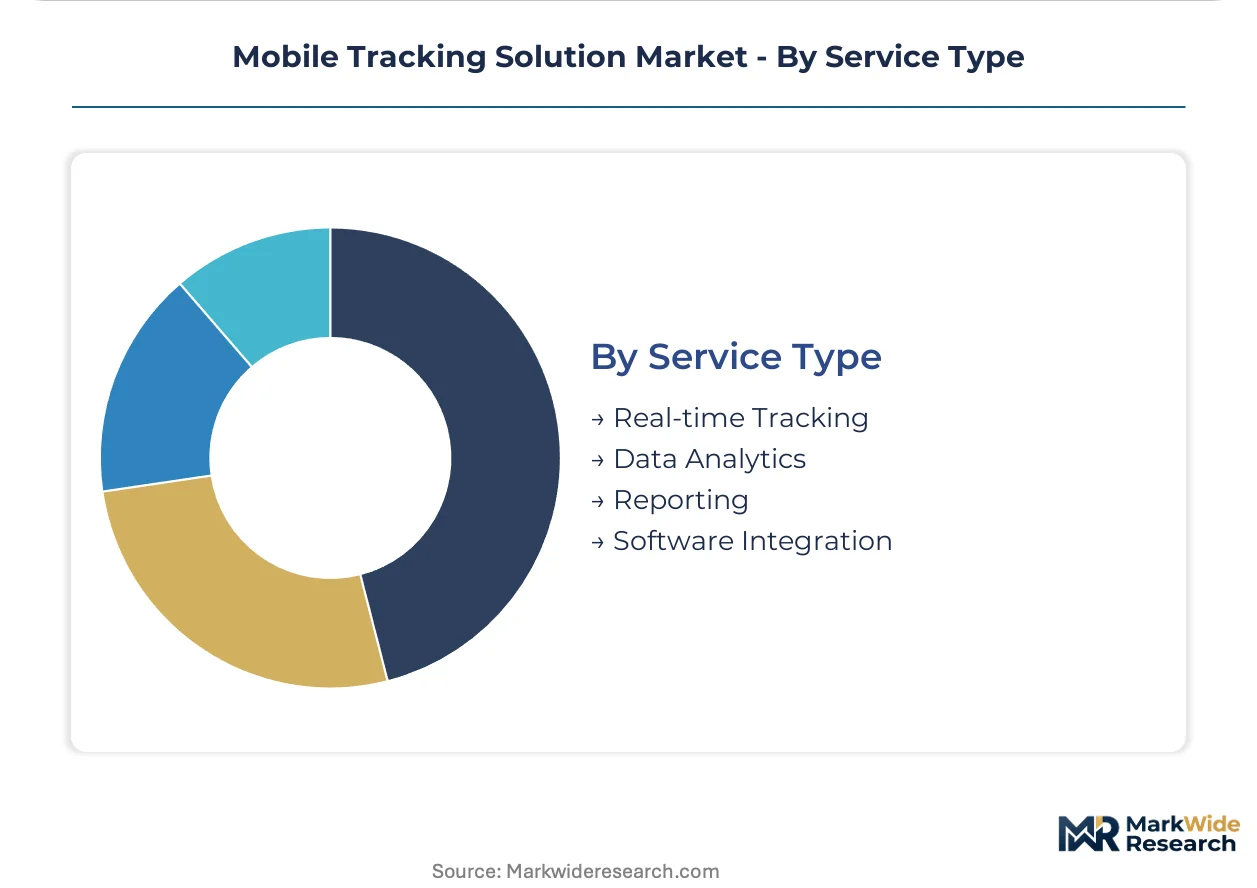
Service Type:
Service layering determines recurring revenue durability and customer switching costs beyond initial hardware deployment.
- Real-time Tracking:Continuous location streaming via cellular or satellite backhaul supports theft recovery, geofence alerts, and dispatch optimization with sub-minute latency requirements.
- Data Analytics:Predictive maintenance models, fuel efficiency scoring, and carbon-emission calculations extract value from accumulated location and sensor history.
- Reporting:Automated compliance documentation for hours-of-service, temperature excursion, or chain-of-custody requirements reduces administrative labor for regulated operators.
- Software Integration:API connectivity and pre-built connectors embed tracking data into ERP, TMS, and warehouse management systems without custom development.
Real-time Tracking commands the greatest share of current service spending. Data Analytics is climbing the fastest as fuel-cost sensitivity and CSRD reporting obligations intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive logistics corridor demands tighter inbound parts visibility than Brazil's fragmented trucking sector, where enforcement gaps slow fleet digitization despite highway corridor investments.
United States
Logistics operators with 50-500 vehicles drive subscription-based tracking adoption to avoid technology obsolescence risk. The FCC's E911 mandate forces device upgrades across public safety and commercial fleets. Dallas-Fort Worth anchors North American telematics platform development as cellular network density enables bundled connectivity-dashboard offerings.
Germany
OEMs require real-time asset tracking from tier-2 suppliers through final assembly gates. The EU AI Act and GDPR impose algorithmic transparency requirements on automated location profiling systems. Stuttgart's automotive logistics corridor concentrates demand for predictive maintenance analytics and carbon-emission reporting bundled with location services.
India
National highway corridor digitization and GST compliance enforcement accelerate fleet tracking adoption among domestic trucking operators. TRAI governs spectrum allocation for cellular-enabled trackers while the central bank monitors payment integration for subscription services. Maharashtra's logistics hubs around Mumbai and Pune lead deployment of Bluetooth-Wi-Fi hybrid architectures for warehouse and last-yard environments.
China
Dual carbon goals and logistics modernization programs drive demand for fuel-consumption analytics integrated with fleet management platforms. MIIT sets device certification standards for cellular modems while GB standards govern GPS receiver performance. The Yangtze River Delta manufacturing clusters around Shanghai produce GPS receiver chips and cellular modem components for tracker assembly.
Japan
Precision agriculture and construction applications command premium pricing for GPS correction services. METI oversees industrial IoT standards that shape telematics hardware requirements. The Kanto region around Tokyo hosts system integrators embedding tracking data into ERP and warehouse management systems without custom development.
Mobile Tracking Solution Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with cellular network operators leveraging infrastructure ownership to bundle connectivity while hardware-focused vendors compete on edge-computing capabilities. The vendor base concentrates around three strategic archetypes: network-integrated platform providers, precision-specialized application developers, and modular hardware-component suppliers. Competitive moves center on software-defined subscription tiering and cross-border data-localization compliance architecture.
Within the network-integrated tier, Verizon Communications Inc. and AT&T Inc. anchor positions through cellular density advantages, while CalAmp Corp. exemplifies the edge-computing hardware archetype feeding cloud platforms. Trimble Inc. occupies a precision-specialized position where GPS correction services command premium pricing in agriculture and construction applications.
| Leading Market Players |
|---|
| Verizon Communications Inc. |
| ORBCOMM Inc. |
| Spireon, Inc. |
| CalAmp Corp. |
| Cisco Systems, Inc. |
| AT&T Inc. |
| TomTom N.V. |
| Trimble Inc. |
| Sierra Wireless, Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive cellular modem production by semiconductor vendors anchors both component availability and subscription pricing power for integrated platform providers. This vertical control over wireless connectivity modules lets network operators bundle hardware with recurring analytics services while squeezing standalone device manufacturers on margin.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for GPS receiver chipsets and cellular modem components. Subscription-based SaaS tiering dominates revenue models, with pricing stratifying across premium fleet analytics, standard real-time tracking, and economy hardware-only tiers. Cost compression in entry-level hardware is intensifying because Taiwanese foundry allocation constraints limit supply elasticity. Mid-sized fleet operators with 50-500 vehicles show greatest price sensitivity, while government agencies mandate FIPS 140-2 encryption regardless of cost premium.
Supply Chain Analysis
GPS receiver chip fabrication rests on Taiwanese semiconductor foundries, Chinese PCB assembly houses, and South Korean memory suppliers. Raw material dependencies span lithium-ion cells for portable trackers, multi-constellation GNSS receivers, and ceramic antenna substrates. Single-source vulnerability concentrates in 5G modem silicon where Qualcomm and MediaTek dominate design wins. Distribution runs through cellular carrier direct sales, specialized telematics distributors, and OEM embedded procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Fleet operators now demand predictive maintenance analytics and CSRD-compliant carbon reporting as procurement prerequisites, elevating subscription intelligence over commodity hardware.
For Market Incumbents: Anticipate Bluetooth-Wi-Fi hybrid architectures displacing GPS-dominant devices in warehouse and last-yard environments. Defensive moves require edge-computing R&D investment to preserve hardware differentiation, plus certification pre-positioning for EU AI Act algorithmic transparency mandates. Channel control through carrier partnership exclusivity offers margin protection against modular hardware commoditization.
For New Entrants and Emerging Players: Systems integrators serving Germany's automotive logistics corridor represent the most accessible channel partner type for market entry. White-space targets include tier-2 supplier inbound parts tracking and India GST compliance enforcement among domestic trucking operators. A software-first go-to-market angle—selling analytics subscriptions with hardware as a service element—sidesteps capital-intensive device manufacturing.
For Investors and Strategic Acquirers: Roll-up economics work for precision-specialized application developers because customer switching costs rise with embedded ERP integration depth. Five-to-ten year viability favors vendors with federated edge-processing architectures that satisfy cross-border data-localization mandates. The signal to watch is carrier bundling intensity: accelerated Verizon or AT&T platform consolidation would compress standalone hardware valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies warehouse, yard, and in-transit visibility layers for omnichannel logistics operators. |
| Strategic Partnership | Cellular carrier bundling embeds tracking dashboards into connectivity contracts at scale. |
| Acquisition of Specialist Firm | Precision agriculture GPS correction services command premium pricing in niche applications. |
| Geographic Expansion | India's highway corridor digitization and GST enforcement create fleet tracking demand acceleration. |
| Product Launch | Bluetooth-Wi-Fi hybrid architectures penetrate indoor environments where satellite signals degrade. |
Study Parameters
Bottom-up fleet operator modeling reconciled against top-down semiconductor shipment tracking forms the analytical core of this study. Primary interviews with fleet management directors, telematics platform engineers, cellular carrier enterprise sales leads, and automotive logistics procurement managers combined with secondary validation from FCC device certification databases, ETSI standards filings, carrier PTCRB approval records, and customs trade data for tracker hardware imports.
Input-output matrices map GPS receiver chip volumes through cellular modem integration to installed base estimates across application segments. Segmentation dimensions span fleet size tier, deployment environment, technology architecture, and regional regulatory cluster. CAGRs derive from unit economics modeling of subscription revenue per installed device against hardware replacement cycles. Forecast inputs incorporate TRAI spectrum allocation timelines and EU CSRD reporting mandate compliance deadlines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion cell price volatility and Taiwan semiconductor foundry capacity allocation. Forecasts reflect documented assumptions about cellular network densification pace and edge-computing adoption curves. A small set of named triggers—GDPR enforcement actions, FCC spectrum reallocation, and India logistics corridor completion rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Workforce Productivity Systems Market
Digital Solutions
Europe API Management Market
Digital Solutions
Tablet Based E-Detailing Market
Digital Solutions
UK and Germany Diet and Nutrition Apps Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Middle East Smart Card Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
Global Smart Lecture Capture System Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market
Digital Solutions
Product Engineering Services Market
Digital Solutions
Saudi Arabia Digital Twin Market
Digital Solutions
Global Work Order Management Systems Market
Digital Solutions
Data Governance Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Space and Workplace Management Software Market