
 Europe Operational Intelligence Market | 2026-2036
Europe Operational Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Operational Intelligence Market Foresight
Enterprise-grade real-time analytics is redrawing competitive boundaries in the Europe Operational Intelligence Market. SAP SE leverages deep ERP integration to anchor industrial deployments across German manufacturing corridors. Splunk Inc specializes in machine data ingestion, dominating security-adjacent operational monitoring for European financial institutions.
Operational intelligence encompasses the continuous capture, correlation, and visualization of live business events to enable immediate decision-making, typically processing sub-second data streams from sensors, applications, and transactional systems. Its primary purpose is to compress the latency between operational anomaly detection and corrective action in mission-critical environments. Software solutions lead the solution segment due to recurring license economics and embedded AI modules, while edge computing represents the fastest-expanding technology category as latency-sensitive manufacturing use cases multiply. Predictive maintenance commands disproportionate margin attention within applications, given the high cost of unplanned downtime in European process industries.
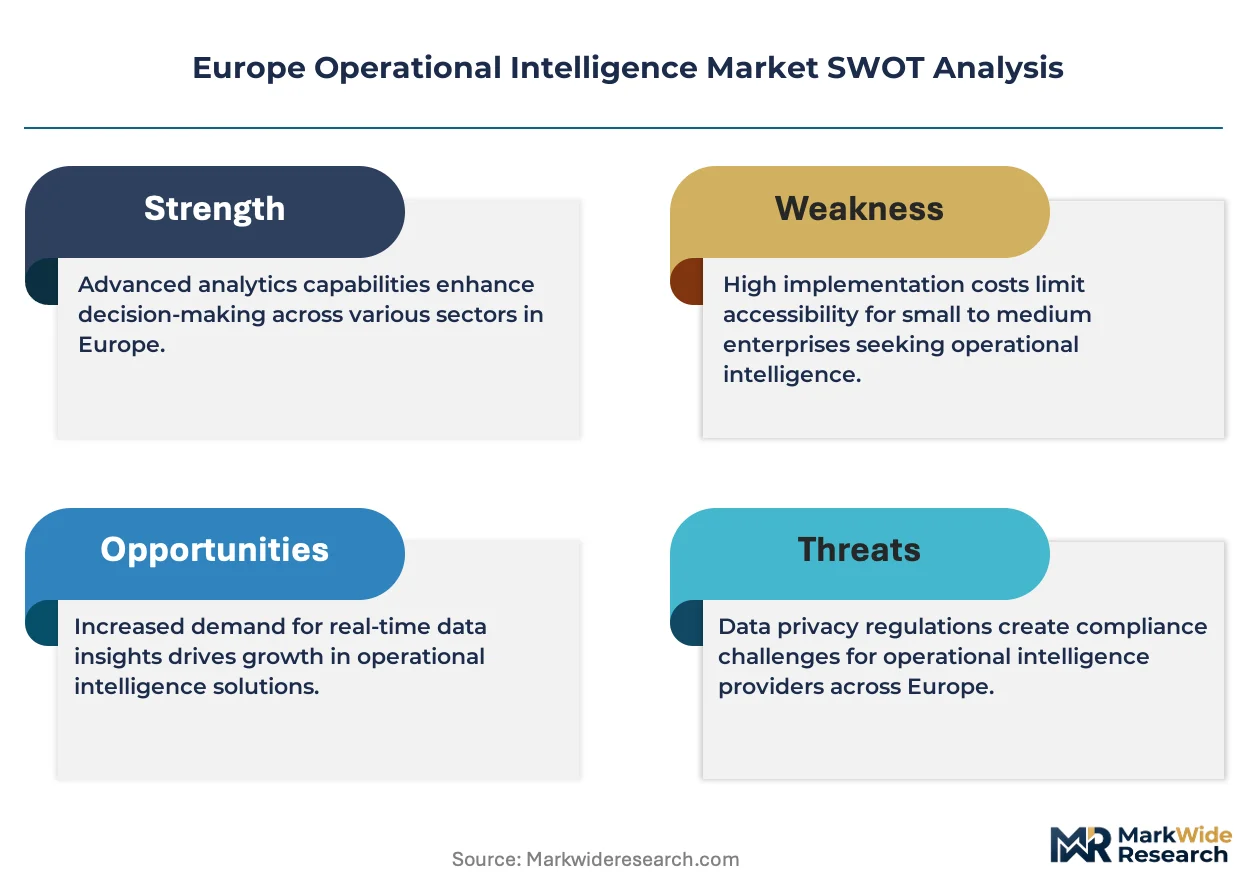
The EU AI Act imposes risk-tiered compliance obligations on automated operational decision systems, directly shaping product roadmaps for vendors serving European regulated industries. EMA pharmacovigilance guidelines and GDPR data governance standards further constrain how healthcare and cross-sector operators may deploy real-time patient or consumer analytics. Stakeholders must weigh algorithmic explainability investments against performance latency trade-offs as enforcement mechanisms mature.
Market Dynamics
The EU AI Act is decomposing legacy operational decision architectures across European process industries, forcing vendors to rebuild platforms around algorithmic explainability rather than pure predictive accuracy. German automotive manufacturers now demand real-time dashboards that expose model logic to plant-floor engineers.
Growth Catalysts
- EU AI Act compliance mandates:Risk-tiered obligations for automated operational systems are accelerating procurement of explainable AI modules in French energy infrastructure and Dutch manufacturing clusters.
- Edge computing latency reduction:Sub-10 millisecond processing requirements on German production lines are pulling distributed analytics hardware into brownfield facility upgrades.
- Predictive maintenance cost avoidance:Unplanned downtime penalties in European process industries are concentrating software spending on vibration sensor networks and thermal imaging integration.
Market Restraints
- GDPR data residency friction:Cross-border operational data flows between German plants and centralized cloud analytics hubs face consent-chain verification delays.
- Semiconductor supply concentration:Edge device manufacturing depends on Taiwan-based foundry capacity, creating 16-24 week lead time volatility for industrial gateway hardware.
- Legacy ERP integration debt:SAP-centric German manufacturing corridors require expensive middleware layers to connect 1990s-era production databases with streaming analytics platforms.
Strategic Opportunities
- Netherlands predictive maintenance white space:Offshore wind turbine operators lack integrated blade monitoring systems, creating vendor entry points for vibration-acoustic fusion platforms.
- EU Green Deal carbon tracking mandates:Real-time emissions monitoring requirements are opening procurement channels for operational intelligence vendors in cement and steel verticals.
- Digital twin convergence with operational intelligence:French aerospace suppliers are blending physics-based simulation with live production data to compress prototype validation cycles.
Industry Challenges
- Industrial data science talent scarcity:European manufacturers compete with fintech salaries for engineers capable of bridging OT-IT security boundaries and deploying containerized analytics at scale.
- CE marking timeline compression:Hardware-enabled operational intelligence platforms face 12-18 month conformity assessment delays under evolving MDR and machinery directive interpretations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Operational Intelligence Market |
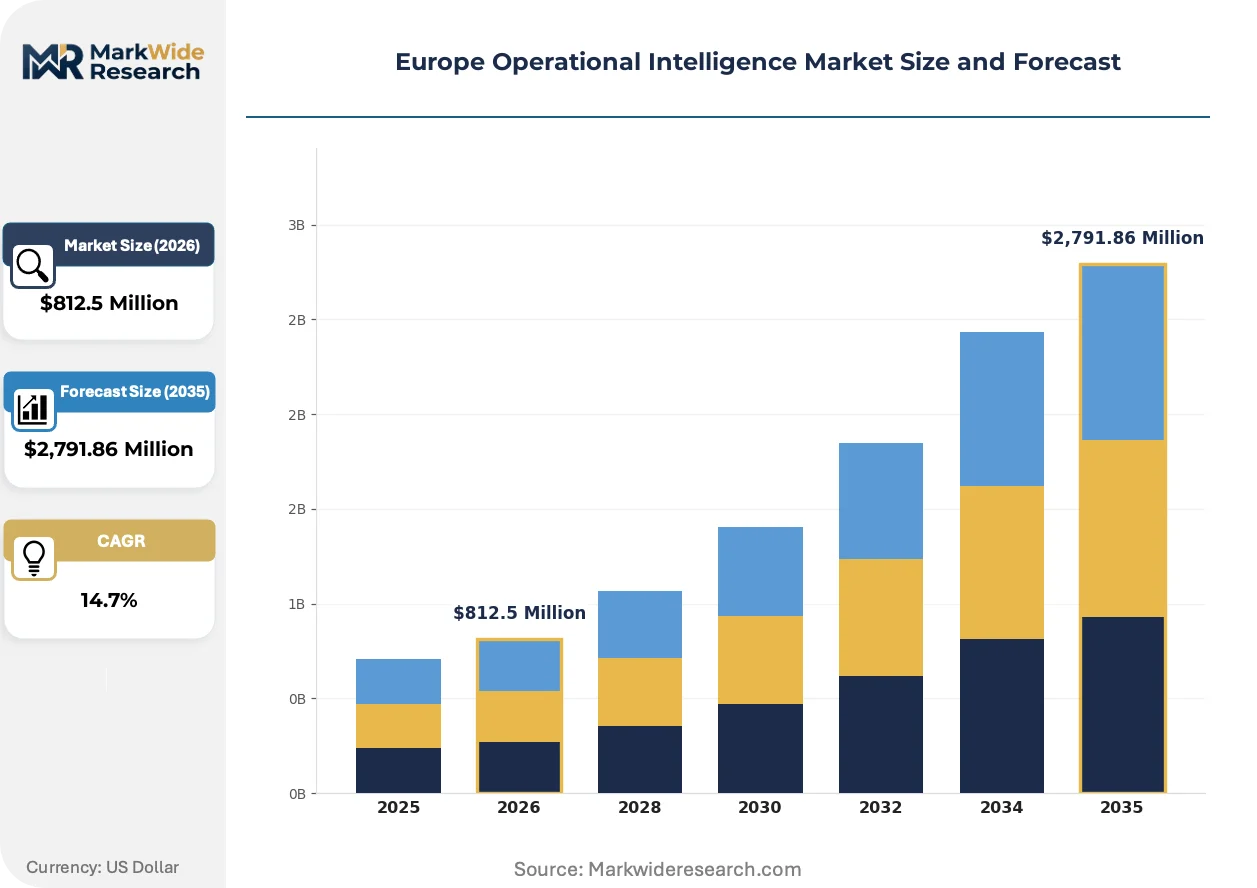
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $2,791.86 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Data Analytics, Cloud Computing, Edge Computing Application: Supply Chain Management, Fraud Detection, Business Process Optimization, Predictive Maintenance End User: Manufacturing, Retail, Healthcare, Telecommunications Solution: Software, Consultancy, Managed Services, Integration Services |
| Companies Covered | Software AG, Splunk Inc, SAP SE, Industrial And Financial Systems Ab (IFS), Open Text Corporation, IBM, Schneider Electric SE, Turnberry Solutions, Honeywell International Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Operational Intelligence Market Shifts & Advancements
Streaming analytics architectures are fragmenting across deployment topologies as European manufacturers weigh cloud economics against sovereign data requirements. The tension between centralized model training and edge inference is reshaping vendor roadmaps and buyer procurement criteria.
Digital twin technology is decomposing monolithic manufacturing execution systems into modular, event-driven microservices. German automotive suppliers are deploying lightweight twin instances on production-line gateways to enable real-time quality deviation detection without cloud round-trips. This decomposition is compressing the traditional MES vendor lock-in cycle and opening substitution pathways for specialized operational intelligence platforms.
The EU AI Act's risk classification framework is redrawing product development priorities for vendors serving European regulated industries. High-risk operational decision systems now require human-in-the-loop validation protocols and documented training data provenance. Healthcare and financial services deployments face the steepest compliance curve, with pharmacovigilance teams at EMA-inspected sites rebuilding real-time adverse event detection around auditable decision trails.
Outcome-based contracting is displacing perpetual license models in French and Dutch energy infrastructure procurement. Asset operators now demand operational intelligence vendors tie fees to measurable uptime improvements or maintenance cost reductions rather than software seat counts. This shift concentrates vendor risk on algorithmic performance guarantees and is visible most acutely in offshore wind and district heating network modernization programs.
Europe Operational Intelligence Market Segmentation
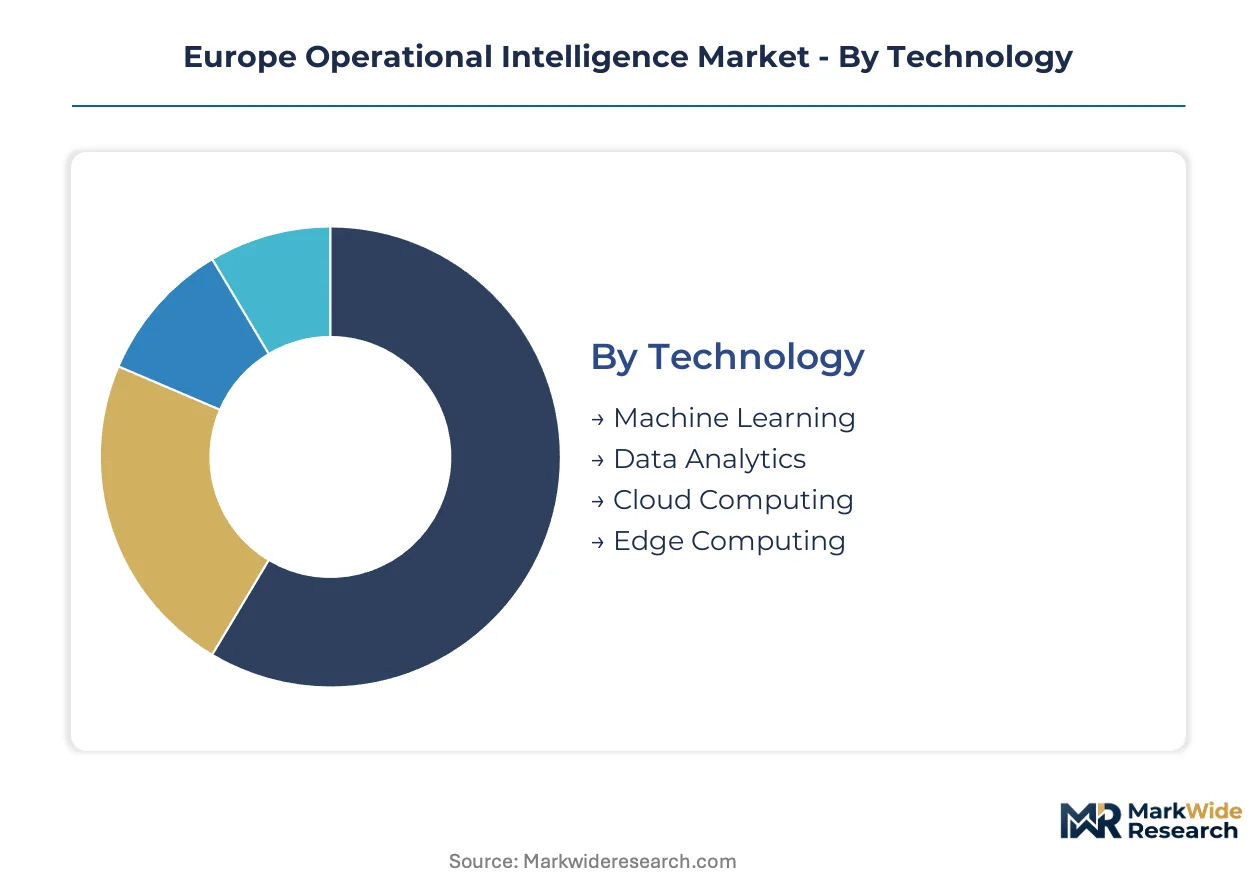
Segmentation in the Europe Operational Intelligence Market reveals where vendor investments concentrate and which compliance architectures buyers prioritize. Technology choices determine latency tolerance, while application focus shapes regulatory exposure under the EU AI Act.
Technology:
Margin pools concentrate in edge infrastructure deployments where sub-millisecond processing commands premium pricing from German automotive lines.
- Machine Learning:Algorithmic models process streaming operational data to flag anomalies and automate classification decisions. French energy operators deploy these for predictive load balancing under EMA pharmacovigilance-aligned audit requirements.
- Edge Computing:Distributed processing nodes execute inference locally on production-line gateways, eliminating cloud round-trip latency. Dutch offshore wind operators demand these for turbine vibration monitoring where connectivity drops exceed 40% of operational hours.
- Data Analytics:Correlation engines aggregate multi-source operational feeds into unified dashboards.
- Cloud Computing:Centralized training and model versioning infrastructure supports hybrid deployments.
The dominant share belongs to Machine Learning, while Edge Computing is closing the gap fastest.
Application:
Cost avoidance metrics in process industries concentrate procurement attention on downtime prevention use cases.
- Predictive Maintenance:Vibration, thermal, and acoustic sensor fusion enables failure prediction before functional degradation. German automotive stamping plants tie vendor contracts to measurable line-availability improvements, with penalties for false-negative detection rates.
- Supply Chain Management:Real-time inventory positioning and demand-signal processing compress replenishment cycles. Dutch retail distribution centers deploy these systems to synchronize automated storage retrieval with last-mile carrier scheduling.
- Fraud Detection:Pattern recognition flags anomalous transactional sequences for investigation.
- Business Process Optimization:Workflow mining identifies bottleneck stages for reengineering.
Predictive Maintenance captures the largest contract values, though Supply Chain Management is expanding most quickly.
End User:
Customer maturity varies sharply across verticals, with regulated industries demanding documented algorithmic provenance.
- Manufacturing:Production-line deployments integrate with legacy MES and ERP systems through expensive middleware layers. German automotive corridors represent the densest concentration of real-time quality deviation detection implementations.
- Healthcare:Patient monitoring and adverse event detection require EMA-inspected audit trails. French hospital networks rebuild operational intelligence around human-in-the-loop validation protocols mandated by pharmacovigilance guidelines.
- Retail:Demand forecasting and inventory optimization drive adoption.
- Telecommunications:Network performance monitoring and predictive capacity planning dominate use cases.
Manufacturing holds the deepest installed base, while Healthcare is gaining share fastest.
Solution:
Recurring revenue models dominate vendor strategies, though outcome-based contracting is displacing seat-count pricing in energy infrastructure.
- Software:Licensed platforms with embedded AI modules and streaming analytics engines anchor most deployments. French and Dutch asset operators increasingly demand uptime-linked fee structures rather than perpetual licenses.
- Managed Services:Outsourced monitoring and model retraining offload operational burden from thin-staffed European manufacturers. German mid-cap automotive suppliers favor these arrangements to access scarce industrial data science talent without competing on fintech salaries.
- Consultancy:Advisory engagements for architecture design and compliance readiness.
- Integration Services:Middleware development connecting legacy systems to modern streaming platforms.
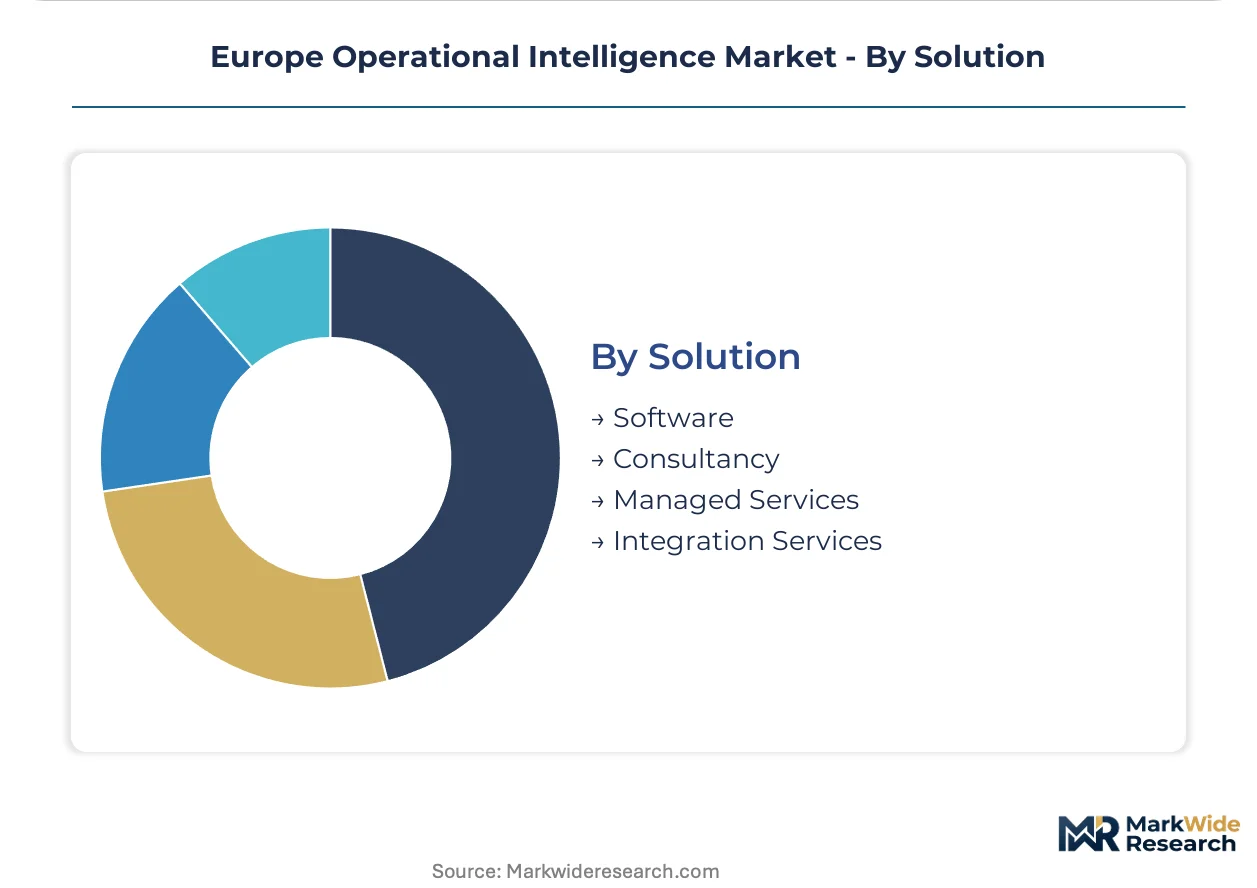
Software retains the dominant revenue share, while Managed Services is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor concentration clusters around German industrial automation corridors and Dutch energy infrastructure hubs. French aerospace and healthcare verticals drive specialized compliance requirements. Spanish and Italian manufacturing regions present fragmented upgrade opportunities amid legacy system heterogeneity.
Germany
Automotive stamping plants and chemical process operators anchor regional demand for sub-10 millisecond edge analytics. The EU AI Act mandates explainable model logic disclosure for high-risk operational decision systems. Stuttgart and Wolfsburg manufacturing corridors deploy real-time quality deviation detection on production-line gateways.
France
Aerospace suppliers and hospital networks drive procurement of auditable decision trails and human-in-the-loop validation protocols. EMA pharmacovigilance guidelines constrain real-time patient monitoring deployments. Toulouse aerospace cluster blends physics-based simulation with live production data for prototype validation compression.
Netherlands
Offshore wind turbine operators and district heating networks concentrate demand for vibration-acoustic fusion platforms. Outcome-based contracting tied to uptime improvements displaces perpetual software licenses. Rotterdam port logistics and Eindhoven high-tech manufacturing deploy predictive maintenance for automated storage retrieval synchronization.
United Kingdom
Financial services operational monitoring and North Sea energy infrastructure drive security-adjacent analytics procurement. GDPR consent-chain verification delays cross-border data flows to centralized cloud hubs. London fintech salaries drain industrial data science talent from Midlands manufacturing automation programs.
Italy
Luxury textile machinery and food processing equipment manufacturers present brownfield integration opportunities. CE marking timeline compression under evolving machinery directive interpretations delays hardware-enabled platform launches. Emilia-Romagna packaging machinery cluster trials edge computing for real-time line optimization.
Europe Operational Intelligence Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European operational intelligence landscape. Deep ERP integration specialists command premium pricing in German manufacturing corridors, while machine data ingestion vendors dominate security-adjacent financial services deployments. Three archetypes structure competition: legacy platform extenders, streaming analytics pure-plays, and industrial automation incumbents. M&A activity concentrates on edge computing capabilities and explainable AI module acquisitions, while strategic partnerships bridge OT-IT security boundaries for mid-cap manufacturers.
Within the legacy platform extender tier, SAP SE and Software AG exemplify ERP-anchored competition. Splunk Inc occupies a position among streaming analytics specialists serving regulated industries. Schneider Electric SE and Honeywell International Inc represent industrial automation incumbents leveraging brownfield facility relationships.
| Leading Market Players |
|---|
| Software AG |
| Splunk Inc |
| SAP SE |
| Industrial And Financial Systems Ab (IFS) |
| Open Text Corporation |
| IBM |
| Schneider Electric SE |
| Turnberry Solutions |
| Honeywell International Inc |
| Others |
Supply & Pricing Matrix
Sixteen-to-twenty-four-week lead times for industrial gateway hardware concentrate pricing power with Taiwan-based foundry operators and compress margin buffers for European systems integrators deploying edge analytics across German automotive corridors.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for operational intelligence platforms serving European regulated industries. Three-tier pricing structure across premium, standard, and economy levels separates explainable AI modules with full audit trails from black-box predictive tools. Certification level under EMA pharmacovigilance-aligned requirements commands substantial premiums in French healthcare deployments. Cost compression in standard-tier software subscriptions is intensifying because outcome-based contracting shifts vendor risk onto performance guarantees. Mid-cap German automotive suppliers exhibit highest price sensitivity, while Dutch offshore wind operators with uptime-linked procurement budgets show lowest sensitivity.
Supply Chain Analysis
Taiwan and South Korea anchor semiconductor fabrication for edge device processors deployed in European manufacturing analytics. Germany and the Netherlands supply precision sensor hardware and industrial automation components. Raw material dependencies span silicon wafers, rare earth magnets for vibration sensors, and specialized thermal imaging substrates. Single-source vulnerability concentrates in Taiwan-based foundry capacity for industrial-grade inference chips. Distribution runs through specialized industrial automation distributors with deep OT-IT integration expertise serving brownfield facility upgrades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed services revenue layers are expanding faster than perpetual software licenses as European manufacturers outsource model retraining and monitoring to access scarce industrial data science talent without competing on fintech salaries.
For Market Incumbents: Compound defensive positioning through explainable AI module acquisitions and edge computing capability extensions. Streaming analytics pure-plays threaten ERP-anchored vendors in German manufacturing corridors where middleware integration debt creates substitution vulnerability. Prioritize backward integration into sensor hardware supply through partnerships with Netherlands-based vibration monitoring specialists. For New Entrants and Emerging Players: Anchor in Netherlands offshore wind predictive maintenance white space where integrated blade monitoring systems remain underpenetrated. District heating network modernization programs in Dutch urban clusters present adjacent expansion pathways. Lead with outcome-based contracting models tied to measurable uptime improvements rather than seat-count pricing. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because operational intelligence platforms embed deeply into mission-critical production environments with high switching costs. Target acquisition profiles center on edge computing specialists with proven OT-IT security boundary capabilities. Watch for inflection when EU AI Act enforcement mechanisms mature and high-risk system compliance spending accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Edge Computing Specialist | Addresses sub-10 millisecond latency requirements in German automotive stamping plants. |
| Strategic Partnership for OT-IT Integration | Bridges security boundaries for mid-cap manufacturers lacking in-house industrial data science talent. |
| Platform Integration with Legacy ERP | Reduces middleware costs for SAP-centric German manufacturing corridor deployments. |
| Product Launch of Explainable AI Module | Meets EU AI Act risk-tiered compliance obligations for high-risk operational decision systems. |
| Geographic Expansion into Netherlands Energy Infrastructure | Captures offshore wind turbine monitoring contracts shifting to outcome-based pricing. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with operational technology directors, plant engineers, and procurement leads at German automotive suppliers and Dutch energy operators, and secondary validation against EMA pharmacovigilance guidelines, EU AI Act implementation documents, and hyperscaler edge computing capex disclosures. Bottom-up and top-down triangulation cross-checked vendor revenue estimates against industrial automation spending patterns.
Across the analysis window, the forecast framework modeled technology deployment modes, application maturity tiers, end-user verticals, and solution delivery models. CAGRs were derived from segment-level growth rate blending. Industry-specific inputs included edge device shipment trajectories from Taiwan-based foundry output and predictive maintenance software contract value trends in French process industries.
Material uncertainties — EU AI Act enforcement timing, semiconductor supply volatility, and GDPR cross-border data flow restrictions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance investment trajectories and legacy system integration cost curves. Recalibration cycles align with material shifts in EU AI Act implementation guidance and edge hardware supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Legal Analytics Market
Analytics
Global Analytics Software Market
Analytics
Greece ICT Market
Analytics
Digital Analytics Solutions Market
Analytics
Drone Analytics Software Market
Analytics
North America Speech Analytics Market
Analytics
Iraq ICT Market
Analytics
Multi-Touch Attribution Market
Analytics
Big Data Analytics in Automotive Market
Analytics
United States Geospatial Analytics Market
Analytics
Analytics Sandbox Market
Analytics
Data Wrangling Market
Analytics
Content Intelligence Market
Analytics
Datacenter Analytics Market
Analytics
Content Analytics Software Market
Analytics
Global E-Commerce Analytics Software Market