
 Retail Warehouse Management Systems Market | 2026-2036
Retail Warehouse Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Warehouse Management Systems Market Analytics
Market Context with Strategic Players
China is tilting toward smart logistics infrastructure as domestic retailers expand automated fulfillment campuses. SAP Extended Warehouse Management leverages deep ERP integration to anchor enterprise-grade deployments across Asian manufacturing hubs. Manhattan Associates competes through real-time inventory intelligence that sustains high-velocity omnichannel operations for North American retail chains. Oracle Warehouse Management specializes in cloud-native architectures that extend distributed warehouse networks without on-premises overhead.
Technical Definition and Structural Segments
Retail Warehouse Management Systems constitute integrated software-hardware platforms that coordinate inventory movement, labor allocation, and order fulfillment through barcode scanning, RFID tracking, and algorithmic slotting optimization within distribution centers. These systems primarily serve to minimize stockouts, reduce picking errors, and synchronize last-mile delivery with real-time demand signals. Cloud-Based deployment is capturing the fastest expansion as retailers abandon capital-intensive server farms for elastic SaaS models that scale with seasonal volume spikes. Software modules command the deepest margin pools where subscription pricing for inventory tracking and labor management functionality generates recurring revenue. Hardware segments face commoditization pressure as sensor costs decline and buyers prioritize platform-agnostic device compatibility.
Regulatory Frame and Forward-Looking Close
The EU AI Act imposes algorithmic transparency requirements on automated demand forecasting modules, while GDPR restricts how European retailers process worker productivity data captured through labor management functionality. China's SAMR enforces data localization rules that mandate on-premises or sovereign-cloud architectures for warehouse operators processing consumer transaction records. Stakeholders must monitor how divergent data governance regimes fragment platform architectures and force vendors to maintain parallel compliance engineering tracks.
Market Dynamics
E-commerce fulfillment velocity requirements are compressing warehouse automation deployment cycles from multi-year ERP integrations to modular SaaS rollouts that retailers activate within quarters.
Growth Catalysts
- EU AI Act compliance mandates:European retailers accelerate replacement of black-box demand forecasting modules with auditable algorithmic systems to satisfy algorithmic transparency requirements.
- RFID sensor cost deflation:Item-level tracking economics now pencil out for mid-market apparel retailers, expanding addressable buyer base beyond enterprise accounts.
- China's smart logistics infrastructure push:Domestic retailers construct automated fulfillment campuses with sovereign-cloud WMS architectures to satisfy SAMR data localization rules.
Market Restraints
- GPU and edge compute hardware shortages:Vision-guided robotics deployments stall as NVIDIA Jetson modules face 26-week lead times, throttling warehouse automation rollouts.
- GDPR worker productivity data restrictions:European labor management modules cannot deploy keystroke-level monitoring that drives optimization algorithms in North American facilities.
- Legacy mainframe integration debt:ERP systems running on AS/400 architectures resist API-native WMS connectivity, forcing costly middleware layers.
Strategic Opportunities
- Cold chain pharmaceutical distribution:Temperature-validated WMS modules capture premium pricing from specialty pharma 3PLs facing FDA DSCSA serialization deadlines.
- India's PLI scheme for logistics infrastructure:Domestic warehousing automation incentives attract WMS vendors to establish localized cloud data centers.
- Computer vision and digital twin convergence:Real-time warehouse simulation layers enable predictive congestion management before physical bottlenecks form.
Industry Challenges
- Industrial control systems cybersecurity certification:IEC 62443 compliance timelines extend 14-18 months, delaying go-live dates for connected warehouse networks.
- SCADA-WMS protocol translation complexity:Material handling equipment running proprietary fieldbus standards resist seamless integration with cloud-native inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Warehouse Management Systems Market |
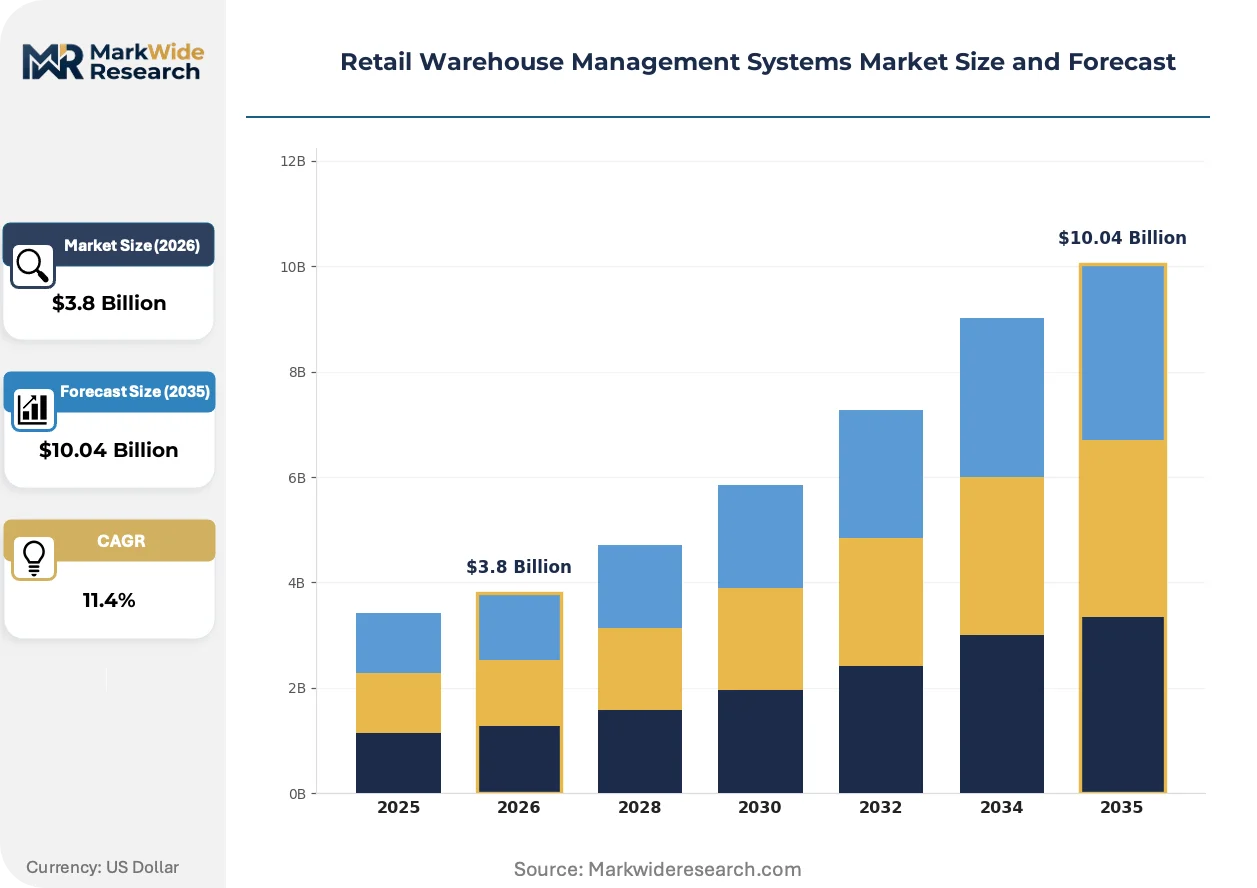
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Integration Customer Type: Small Retailers, Large Retailers, E-commerce Platforms, Wholesalers Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Functionality: Inventory Tracking, Order Management, Reporting Tools, Labor Management |
| Companies Covered | SAP Extended Warehouse Management, Oracle Warehouse Management, Manhattan Associates, Körber Supply Chain, Softeon Warehouse Management System, Blue Yonder, Infor Warehouse Management System, Deposco, Microsoft Dynamics 365 Supply Chain Management, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Warehouse Management Systems Market Evolving Landscape
Algorithmic orchestration layers are displacing rule-based warehouse control systems as machine learning inference moves from cloud batch jobs to edge real-time decision nodes.
Autonomous mobile robots equipped with LiDAR and computer vision are collapsing the labor cost advantage of offshore fulfillment centers against domestic automated facilities. Third-party logistics providers in Germany and the United States deploy these systems at 300-unit fleet scales within single distribution campuses. The technology is collapsing the traditional tradeoff between labor arbitrage and capital intensity in site selection decisions.
China's SAMR enforcement of data localization for consumer transaction records is fragmenting cloud WMS architectures into sovereign instances. Warehouse operators processing cross-border e-commerce orders must maintain parallel data residency configurations. European retailers with Chinese fulfillment operations face the steepest compliance engineering burden as GDPR extraterritoriality conflicts with on-premises mandates.
Subscription pricing for warehouse management functionality is displacing perpetual license models as retailers prioritize OpEx predictability over capital allocation flexibility. Mid-market grocery chains and specialty apparel brands drive this shift, demanding elastic capacity scaling for seasonal volume spikes. The United States exhibits the fastest contract structure conversion as interest rate sensitivity elevates working capital optimization priorities.
Retail Warehouse Management Systems Market Segmentation
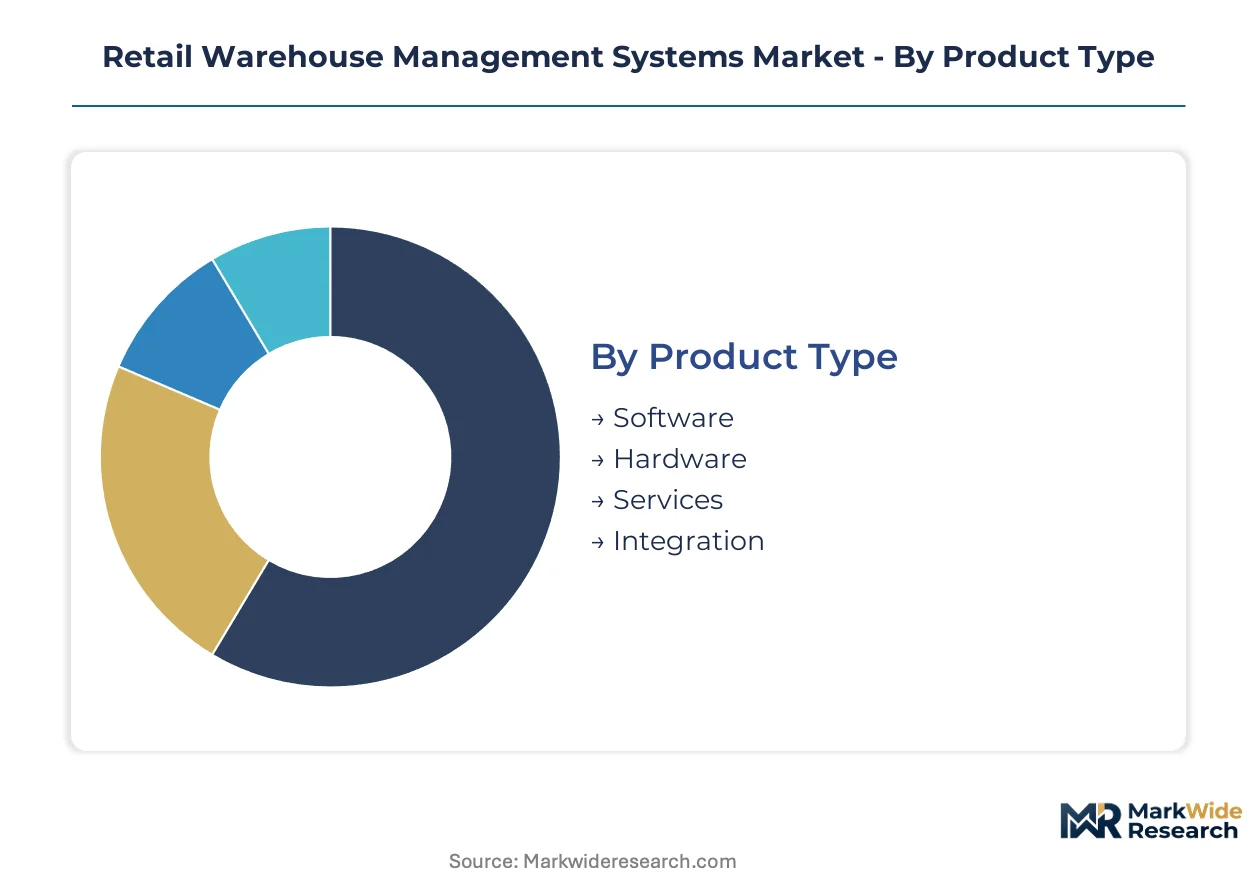
Warehouse management platforms fragment across technical architectures, buyer scale, and functional depth. Procurement patterns diverge sharply between capital-constrained mid-market operators and enterprise retailers optimizing omnichannel fulfillment velocity.
Product Type:
Mature license models coexist with emerging subscription architectures as buyers recalibrate total cost of ownership calculations.
- Software:Modular inventory tracking, labor optimization, and slotting algorithms deploy through perpetual licenses or recurring SaaS contracts. North American grocery chains and apparel retailers drive demand for cloud-native WMS cores that integrate with ERP systems without middleware layers.
- Hardware:Barcode scanners, RFID readers, and edge compute nodes for vision-guided robotics constitute the physical sensing layer. GPU and edge module shortages from NVIDIA Jetson supply constraints are throttling deployment timelines for automated fulfillment campuses in Germany and the United States.
- Services:Implementation consulting, change management, and ongoing technical support surround core platform deployments.
- Integration:Custom API development and legacy system connectivity bridge cloud-native WMS architectures with AS/400 mainframe environments.
Software retains volume leadership; integration holds the steepest expansion curve as ERP connectivity complexity escalates.
Customer Type:
Cost tier stratification separates self-service deployments from enterprise-grade implementations requiring dedicated implementation teams.
- Large Retailers:Omnichannel operators with 50-plus distribution nodes demand real-time inventory visibility across owned and third-party fulfillment networks. Walmart-scale deployments in the United States and Carrefour operations in France anchor enterprise WMS revenue pools.
- E-commerce Platforms:Pure-play digital retailers and marketplace operators prioritize elastic capacity scaling for seasonal demand spikes. Shein and Temu fulfillment networks in China deploy sovereign-cloud architectures to satisfy SAMR data localization mandates.
- Small Retailers:Regional chains and independent operators adopt lightweight SaaS modules without dedicated IT staff.
- Wholesalers:B2B distributors serving fragmented retail endpoints require lot-tracking and expiration-date management functionality.
Large retailers dominate current procurement volume; e-commerce platforms are expanding most quickly as cross-border fulfillment networks multiply.
Deployment:
Volume concentration favors established on-premises installations while margin expansion concentrates in elastic delivery models.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server farm capital expenditure and enable automatic feature updates. European retailers accelerate migration to satisfy GDPR data residency requirements through EU-sovereign cloud regions.
- SaaS:Function-specific subscriptions for inventory tracking or labor management modules allow incremental capability expansion. Mid-market specialty apparel brands in the United States prefer this procurement structure for working capital predictability.
- On-Premises:Single-tenant installations behind corporate firewalls persist in defense-adjacent and critical infrastructure warehousing.
- Hybrid:Mixed architectures maintain sensitive transaction processing on-premises while pushing analytics workloads to public cloud.
On-premises retains installed base dominance; cloud-based deployment is gaining share fastest as vendor roadmaps deprecate perpetual license maintenance.
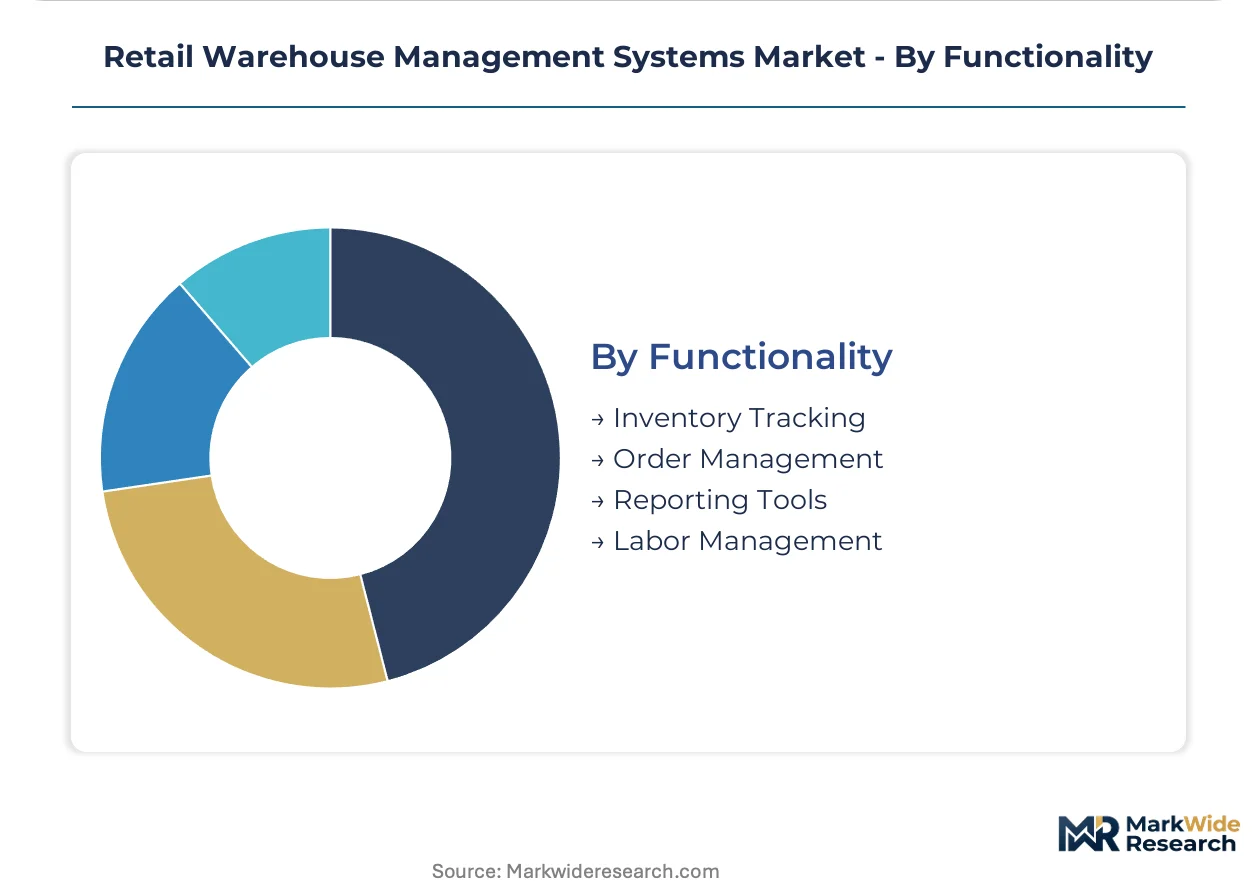
Functionality:
Application criticality separates table-stakes capabilities from premium modules commanding subscription pricing power.
- Inventory Tracking:Real-time stock visibility through barcode, RFID, and computer vision enables automated replenishment triggers. Item-level RFID economics now pencil out for mid-market apparel retailers as sensor costs deflate below unit-level tracking thresholds.
- Labor Management:Workforce optimization algorithms assign picking tasks, measure productivity, and forecast staffing requirements. GDPR restrictions on keystroke-level monitoring in European facilities constrain algorithmic sophistication relative to North American deployments.
- Order Management:Omnichannel order orchestration routes customer requests to optimal fulfillment nodes.
- Reporting Tools:Operational dashboards and compliance documentation modules satisfy internal audit and regulatory filing requirements.
Inventory tracking commands the deepest margin pools; labor management faces the steepest regulatory fragmentation across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling infrastructure underwrites the Netherlands' role as Europe's primary distribution gateway for cross-border retail fulfillment networks.
United States
E-commerce fulfillment velocity demands drive automated warehouse deployments across the Midwest distribution corridor. OSHA workplace safety standards intersect with state-level data privacy laws in California and Illinois, complicating labor management algorithm deployment. The Chicago-Indianapolis-Columbus freight triangle anchors the densest concentration of omnichannel distribution campuses.
Germany
Industrial machinery exports sustain demand for precision inventory tracking in Baden-Württemberg manufacturing hubs. The EU AI Act's algorithmic transparency requirements force retailers to replace black-box demand forecasting modules with auditable systems. The Rhine-Ruhr logistics cluster hosts the highest density of automated fulfillment centers serving pan-European retail networks.
China
Domestic e-commerce platforms construct automated fulfillment campuses at scale to serve cross-border trade corridors. SAMR data localization mandates require sovereign-cloud WMS architectures for operators processing consumer transaction records. The Yangtze River Delta concentration around Shanghai and Hangzhou leads smart logistics infrastructure investment.
India
Third-party logistics providers expand warehouse automation to serve fragmented retail endpoints in tier-two cities. The PLI scheme for logistics infrastructure attracts WMS vendors to establish localized cloud data centers. The Delhi-Mumbai Industrial Corridor anchors the fastest-growing concentration of automated distribution facilities.
United Kingdom
Post-Brexit customs complexity drives demand for inventory visibility across UK-EU fulfillment networks. GDPR data residency requirements accelerate migration to EU-sovereign cloud regions for cross-border operations. The Midlands logistics golden triangle around Birmingham, Leicester, and Nottingham hosts the densest warehouse automation cluster.
Retail Warehouse Management Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the hardware sensing layer. The vendor landscape consolidates around enterprise-grade suites with deep ERP integration, while mid-market SaaS entrants fragment the lower tier. Two archetypes dominate: legacy ERP extenders leveraging installed base relationships, and cloud-native challengers selling elastic capacity to seasonal operators. Competitive moves center on API ecosystem expansion and sovereign-cloud partnership structures for data localization compliance.
Among ERP-anchored platform providers, SAP Extended Warehouse Management and Oracle Warehouse Management occupy positions representing the integrated-suite archetype, while Manhattan Associates exemplifies the specialized WMS pure-play model. These three entities anchor the competitive structure without exhausting its variation.
| Leading Market Players |
|---|
| SAP Extended Warehouse Management |
| Oracle Warehouse Management |
| Manhattan Associates |
| Körber Supply Chain |
| Softeon Warehouse Management System |
| Blue Yonder |
| Infor Warehouse Management System |
| Deposco |
| Microsoft Dynamics 365 Supply Chain Management |
| Others |
Value Network & Pricing Analysis
Overcapacity in cloud-native WMS infrastructure across North American hyperscaler regions is compressing subscription pricing for mid-market SaaS tiers while concentrating margin capture among vendors with sovereign-cloud deployment capabilities. This utilization imbalance rewards elastic pricing architectures and penalizes fixed-cost perpetual license models that cannot absorb seasonal volume volatility.
Pricing Analysis
GDPR and the EU AI Act dictate the pricing tier structure across European deployments, where compliance-engineered modules command premium positioning against standard inventory tracking functionality. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-cloud configurations with full algorithmic audit trails from multi-tenant SaaS offerings with limited labor management depth. Price differentiation hinges on data residency certification grade and after-sales implementation support intensity. Cost compression in the standard tier is intensifying because GPU shortages are forcing hardware-software bundling concessions. Small retailers exhibit the highest price sensitivity, while large omnichannel operators prioritize total cost of ownership predictability over per-seat economics.
Supply Chain Analysis
Edge compute modules and RFID sensor arrays feed from concentrated manufacturing footprints in Taiwan, China, and South Korea, where semiconductor fabrication and electronics assembly anchor component availability. NVIDIA Jetson GPU supply, UHF RFID inlays, and industrial-grade barcode scanners constitute critical input dependencies for vision-guided robotics deployments. Single-source vulnerability around advanced GPU modules creates 26-week procurement bottlenecks that throttle automated fulfillment campus rollouts. Distribution runs through direct vendor-to-integrator channels for enterprise deployments, with cloud-native platforms delivering via API-first marketplace structures to mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from integration services and sovereign-cloud compliance engineering is expanding faster than hardware sensor sales, positioning the market as a service-attach opportunity where professional services margins offset commoditization pressure in the device layer.
For Market Incumbents: Insulate enterprise relationships by embedding deeper into ERP ecosystems through pre-certified API connectors that reduce AS/400 mainframe integration friction. Acquire specialized computer vision startups to close capability gaps against cloud-native challengers deploying digital twin simulation layers. Vertical integration into sovereign-cloud infrastructure partnerships defends margin position against pure-play SaaS entrants undercutting on implementation timelines. For New Entrants and Emerging Players: Pursue mid-market grocery chains and specialty apparel brands in the United States that prioritize OpEx predictability over capital flexibility and lack dedicated IT staff for on-premises maintenance. India's PLI scheme for logistics infrastructure offers the most penetrable geography, where localized cloud data centers satisfy data residency requirements without incumbent legacy integration debt. A channel partnership model with third-party logistics providers accelerates referenceability before direct enterprise sales investment. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-technology play because divergent data governance regimes across GDPR, EU AI Act, and China's SAMR are fragmenting platform architectures and forcing sustained parallel engineering investment. Acquisition targets should display sovereign-cloud deployment capabilities alongside vertical-specific certification depth in cold chain pharmaceutical or defense-adjacent warehousing. The signal to watch is regulatory enforcement velocity in cross-border e-commerce data localization, which would accelerate replacement cycles for non-compliant legacy installations.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign-Cloud Partnership Structure | Enables SAMR and GDPR compliance without parallel platform engineering tracks. |
| API Ecosystem Expansion | Reduces middleware costs for AS/400 mainframe integration in legacy retail environments. |
| Computer Vision Acquisition | Closes capability gaps against digital twin simulation and predictive congestion management. |
| Vertical SaaS Specialization | Captures premium pricing from cold chain pharmaceutical 3PLs facing FDA DSCSA deadlines. |
| Regional Cloud Data Center Buildout | Satisfies India's PLI scheme incentives and data localization requirements for cross-border fulfillment. |
Research Methodology
A spread of perspectives from warehouse operations directors, third-party logistics procurement leads, cloud platform engineers, and ERP integration specialists converged on the working assumptions driving segmentation boundaries and growth trajectory estimates. Primary fieldwork combined structured interviews with secondary validation against SEC filings from publicly traded supply chain software vendors, hyperscaler capex disclosures, customs records for RFID and edge compute hardware imports, and EU regulatory filings documenting AI Act implementation timelines. Bottom-up sizing of individual customer deployments triangulated against top-down market aggregation from vendor revenue disclosures.
Demand-supply balance framing anchored the analytical framework across the analysis window, with modeled dimensions spanning deployment architecture, customer scale tier, functional module depth, and regional regulatory cluster. Deployment model segmentation captured cloud-native SaaS elasticity against hybrid and on-premises persistence. Organization size stratification separated self-service mid-market adoption from enterprise-grade implementation complexity. CAGRs derived from installed base growth rates, replacement cycle compression, and net new customer acquisition velocity across omnichannel retail and pure-play e-commerce fulfillment networks.
Macroeconomic conditions sit as an overlay; deviation in interest rate sensitivity affecting working capital optimization priorities, or prolonged GPU supply constraints extending automation deployment timelines, would shift the trajectory from base-case assumptions. Cross-checking against third-party logistics provider capex announcements and retail distribution center construction permits is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Defense IT Spending Market
Digital Solutions
Infrastructure As Code (Iac) Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
Online Home Service Market
Digital Solutions
Europe Smart Government Market
Digital Solutions
Digital Check Scanning Solutions Market
Digital Solutions
Ediscovery Market
Digital Solutions
Desktop Virtualization in Manufacturing Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
France ICT Market
Digital Solutions
North America API Management Market
Digital Solutions
North America Digital Signage Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market
Digital Solutions
Global Client Virtualization Market
Digital Solutions
North America Data Virtualization Market