
 Data Monetization Solutions for Life Science Companies Market | 2026-2036
Data Monetization Solutions for Life Science Companies Market Size, Share, and Industry Trends Forecast 2026-2036
Data Monetization Solutions for Life Science Companies Market Analytics
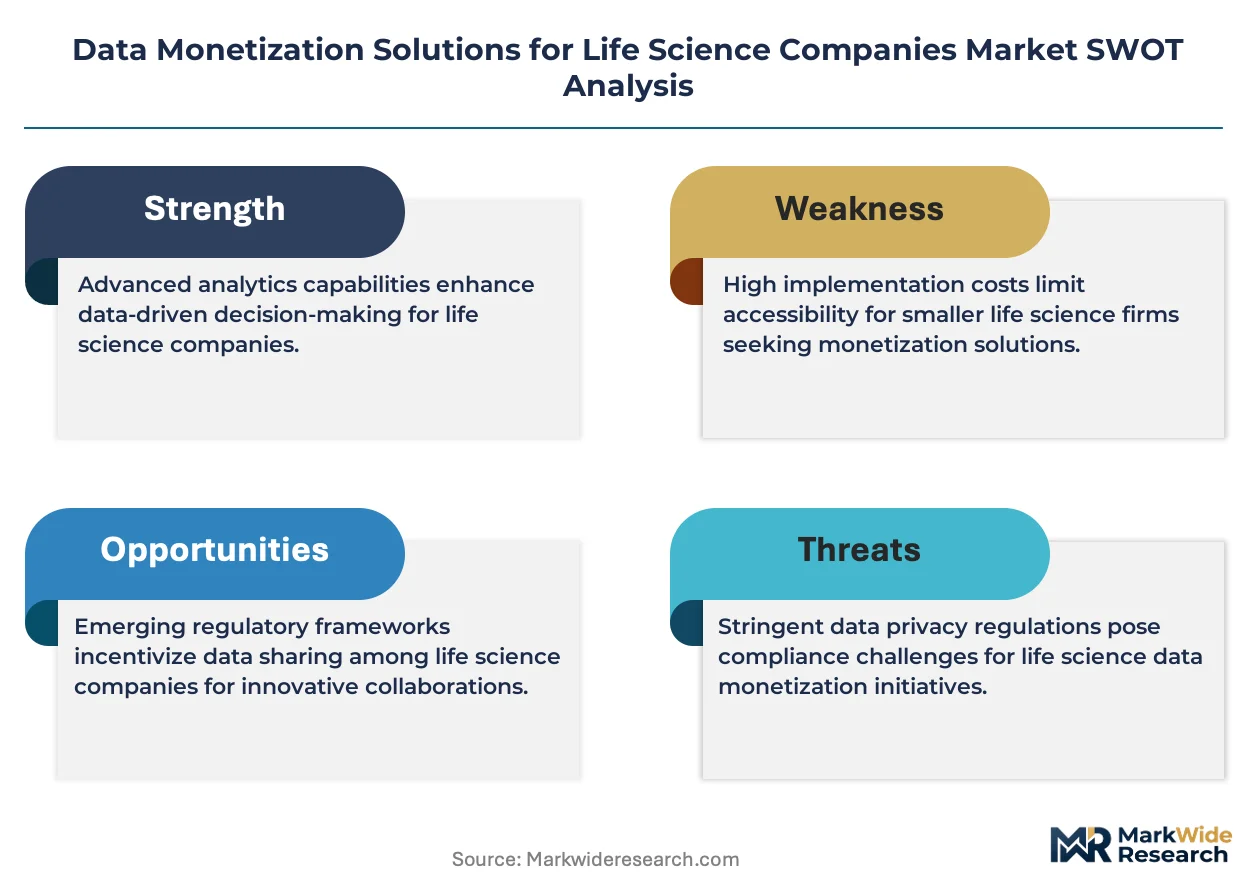
Platform licensing revenue is rewriting how life science technology vendors capture value from intellectual property. Microsoft Corporation leverages its cloud infrastructure to anchor enterprise-scale data federation across health systems. IQVIA sustains dominance in real-world data aggregation through its proprietary investigator networks and regulatory-grade datasets. Oracle Corporation competes by extending database architectures into vertically integrated clinical and commercial analytics stacks.
Data monetization solutions for life science companies encompass platforms, services, and technologies that transform raw health data into commercially actionable assets through de-identification, aggregation, and analytical modeling. These systems typically process structured and unstructured inputs from electronic health records, claims databases, genomics repositories, and wearable devices to generate evidence packages for pricing negotiations, trial design optimization, and market access strategy. Data analytics services within the service type dimension command the deepest margin pools due to high labor specialization and recurring advisory engagements, while AI within the technology dimension grows fastest as large language models automate evidence synthesis and regulatory submission preparation. Cloud computing anchors infrastructure spending across all segments, though blockchain remains nascent outside of supply chain traceability pilots.
FDA 21st Century Cures Act mandates on interoperability and the European Medicines Agency's data transparency policies under the Clinical Trials Regulation shape product development roadmaps and market access requirements for vendors serving multinational sponsors. HIPAA compliance frameworks in the United States and GDPR constraints in Europe create divergent data governance architectures that vendors must navigate simultaneously. Stakeholders must decide whether to build jurisdiction-specific platforms or pursue unified architectures with modular privacy controls as regulatory fragmentation intensifies.
Market Dynamics
The FDA's 21st Century Cures Act interoperability mandates are forcing life science vendors to rebuild data architectures around FHIR standards, compressing legacy platform lifecycles and redistributing competitive advantage toward cloud-native infrastructure providers.
Growth Catalysts
- Real-world evidence mandates:FDA guidance on RWE for regulatory submissions drives pharmaceutical sponsors toward integrated data platforms that aggregate de-identified patient records across health systems.
- Cloud infrastructure maturation:Microsoft Azure and Amazon Web Services health data lakes enable federated analytics without raw data movement, lowering compliance barriers for multi-site studies.
- Health system consolidation:United States hospital mergers create unified data pools spanning millions of patients, increasing the commercial value of single-contract analytics partnerships.
Market Restraints
- GDPR-HIPAA divergence:European data portability requirements conflict with US de-identification safe harbors, forcing vendors to maintain parallel governance architectures that inflate engineering overhead.
- Genomic data storage costs:Petabyte-scale whole-genome sequencing repositories face 40-60% annual storage cost escalations that squeeze margin on fixed-price platform contracts.
- Investigator network concentration:IQVIA's proprietary site relationships and Cerner's EHR footprint create bottlenecks for new entrants seeking regulatory-grade data provenance.
Strategic Opportunities
- Wearable-derived digital endpoints:Apple Watch and Fitbit continuous monitoring data streams open new pharmacovigilance and adherence analytics products for cardiovascular and metabolic therapeutic areas.
- EMA Clinical Trials Information System:The European Medicines Agency's mandatory disclosure requirements create demand for automated redaction and transparency workflow tools.
- AI-enabled evidence synthesis:Large language models automating systematic literature review and regulatory submission drafting represent uncontracted white space in biopharma R&D operations.
Industry Challenges
- FHIR implementation expertise:Shortage of engineers fluent in Fast Healthcare Interoperability Resources standards delays platform modernization timelines for mid-tier vendors.
- Multi-jurisdiction consent management:Tracking patient authorization revocations across state, federal, and international boundaries requires costly re-architecture of audit trail systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Monetization Solutions for Life Science Companies Market |
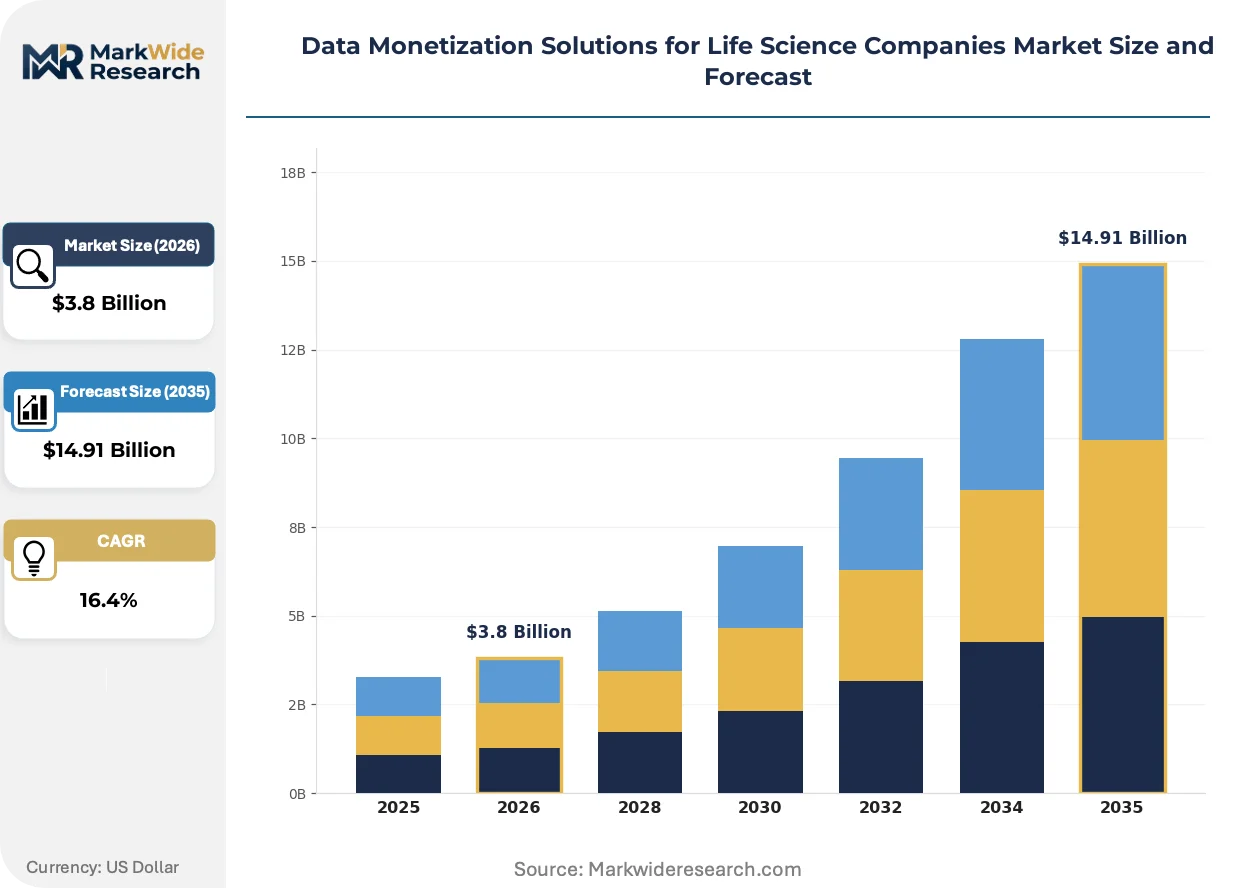
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Analytics, Data Sharing, Market Access, Data Solutions Technology: Blockchain, AI, Cloud Computing, Machine Learning End User: Pharmaceuticals, Biotech Firms, Contract Research Organizations, Medical Devices Application: Clinical Trials, Drug Development, Market Research, Patient Insights |
| Companies Covered | Oracle Corporation, Microsoft Corporation, Salesforce, Inc., SAP SE, SAS Institute Inc., IQVIA, Parexel International, Tempus, Clarivate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Monetization Solutions for Life Science Companies Market Evolving Landscape
Generative AI and federated learning architectures are collapsing the traditional trade-off between data utility and privacy protection, enabling new commercial models that were technically infeasible under centralized analytics paradigms.
Large language models trained on biomedical literature and clinical trial protocols are collapsing the labor intensity of systematic review and regulatory document preparation. Contract research organizations at IQVIA and Syneos Health are piloting GPT-4 derivatives for protocol amendment drafting and informed consent simplification. This compression of professional services hours threatens traditional time-and-materials pricing for evidence generation.
The European Medicines Agency's Clinical Trials Regulation transparency provisions require sponsors to publish clinical study reports and raw data packages within fixed post-approval windows. This mandate accelerates demand for automated de-identification pipelines and structured data transformation tools. Mid-sized biotechs lacking in-house compliance infrastructure represent the fastest-adopting segment for outsourced transparency management services.
Biopharma procurement teams are consolidating vendor relationships around full-stack data partners capable of spanning ingestion, analytics, and regulatory submission. This preference compression disadvantages point-solution providers lacking cloud infrastructure or investigator network assets. The shift is most pronounced in oncology and rare disease therapeutic areas where trial complexity demands integrated evidence ecosystems.
Data Monetization Solutions for Life Science Companies Market Segmentation
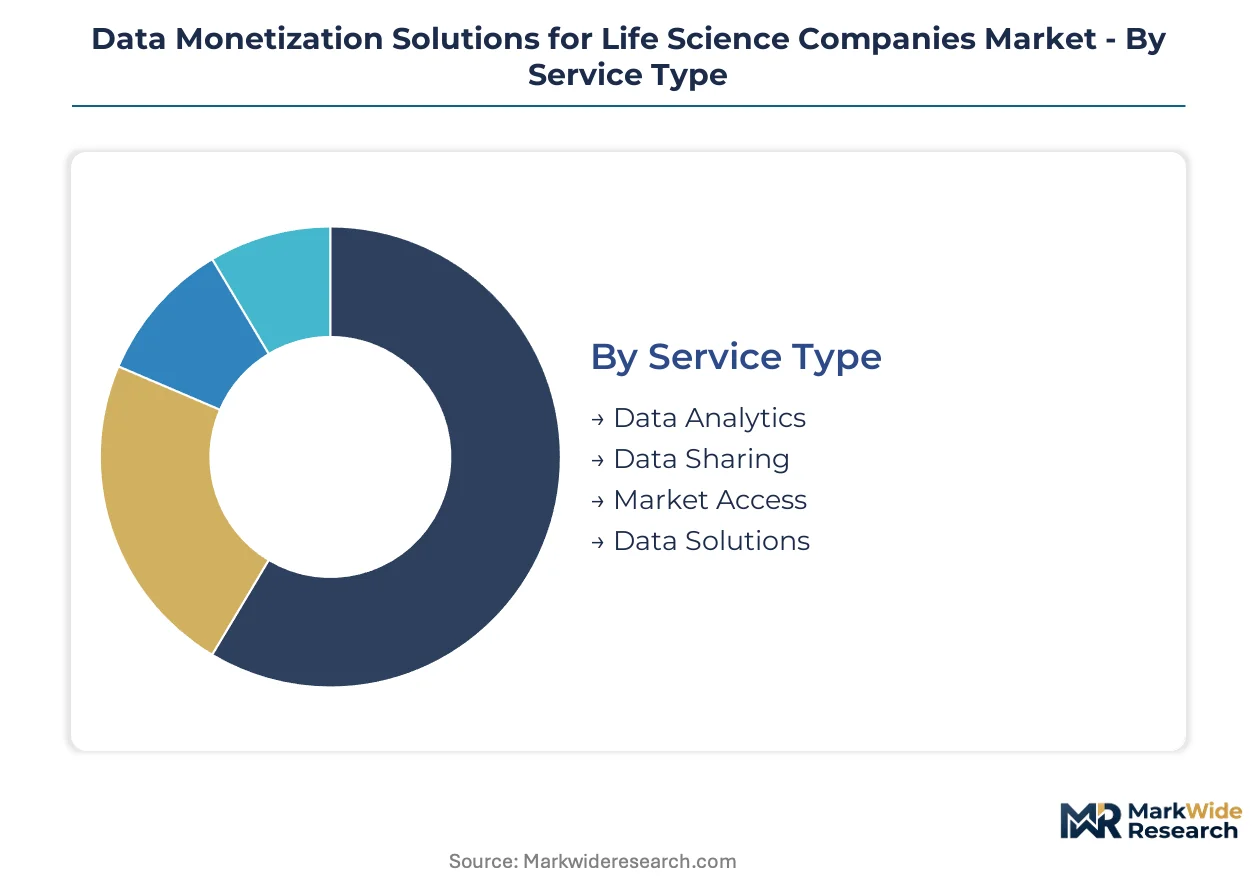
Segmentation in life science data monetization reflects divergent buyer economics across evidence generation workflows. Pharmaceutical sponsors prioritize regulatory-grade provenance while biotechs favor modular, pay-as-you-scale architectures. Technology choices cascade into compliance obligations that reshape total cost of ownership across deployment models.
Service Type:
Use-case spectrum spans from episodic advisory engagements to perpetual platform licenses anchored in enterprise data lakes.
- Data Analytics:Statistical modeling and evidence synthesis services process de-identified EHR and claims data to generate real-world evidence packages for FDA submissions. Demand concentrates among mid-cap biotechs lacking in-house biostatistics teams, driven by compressed trial timelines and investor pressure for faster regulatory milestones.
- Data Sharing:Federated query platforms enable multi-site analytics without raw data movement, reducing HIPAA compliance exposure. Hospital systems in the United States favor this model as consolidation creates unified patient pools spanning millions of lives, though GDPR divergence complicates European deployment architectures.
- Market Access:Payer negotiation support and health technology assessment submissions leverage aggregated outcomes data to justify pricing. Compact treatment—contract research organizations bundle these services with clinical trial execution to capture downstream commercialization budgets.
- Data Solutions:End-to-end platforms spanning ingestion, harmonization, and analytics. Compact treatment—full-stack vendors like IQVIA and Oracle anchor procurement consolidation trends in oncology therapeutic areas.
Established volume favors Data Analytics; emerging adoption favors Data Sharing.
Technology:
Cost tier structures separate infrastructure-heavy deployments from algorithmic layers commanding premium pricing.
- Cloud Computing:Azure and AWS health data lakes provide elastic storage and compute for petabyte-scale genomic repositories. Pharmaceutical sponsors anchor spending here as whole-genome sequencing volumes escalate storage obligations faster than on-premise capacity planning allows.
- AI:Large language models automate systematic literature review, protocol amendment drafting, and regulatory submission preparation. Biotech procurement teams pilot these tools to compress professional services hours, threatening traditional time-and-materials pricing for evidence generation workflows.
- Machine Learning:Predictive models for patient stratification and site selection optimize trial enrollment velocity. Compact treatment—embedded within broader analytics platforms rather than standalone procurement categories.
- Blockchain:Distributed ledger pilots concentrate in supply chain traceability and consent management audit trails. Compact treatment—regulatory-grade provenance requirements remain unmet by current throughput limitations.
Cloud Computing captures the deepest margin pools; AI climbs the fastest as automation displaces labor-intensive document preparation.
End User:
Customer type determines procurement sophistication and contract structure preferences across the buyer base.
- Pharmaceuticals:Top-20 sponsors demand regulatory-grade data provenance, investigator network access, and multi-jurisdiction compliance infrastructure. FDA real-world evidence mandates drive integrated platform consolidation, favoring vendors with established site relationships and historical trial data repositories.
- Biotech Firms:Venture-backed developers prioritize modular, consumption-based pricing to preserve runway. Cloud-native entrants capture share here by eliminating upfront license fees and offering per-study analytics pricing.
- Contract Research Organizations:IQVIA and Syneos Health internalize data monetization capabilities to defend margin compression from AI automation. Compact treatment—vertical integration threatens independent platform vendors lacking trial execution assets.
- Medical Devices:Post-market surveillance and real-world performance monitoring generate demand for continuous data streams. Compact treatment—wearable-derived endpoints in cardiovascular and metabolic categories expand addressable use cases.
Pharmaceuticals dominate current spending; biotech firms represent the steepest expansion trajectory as platform accessibility improves.
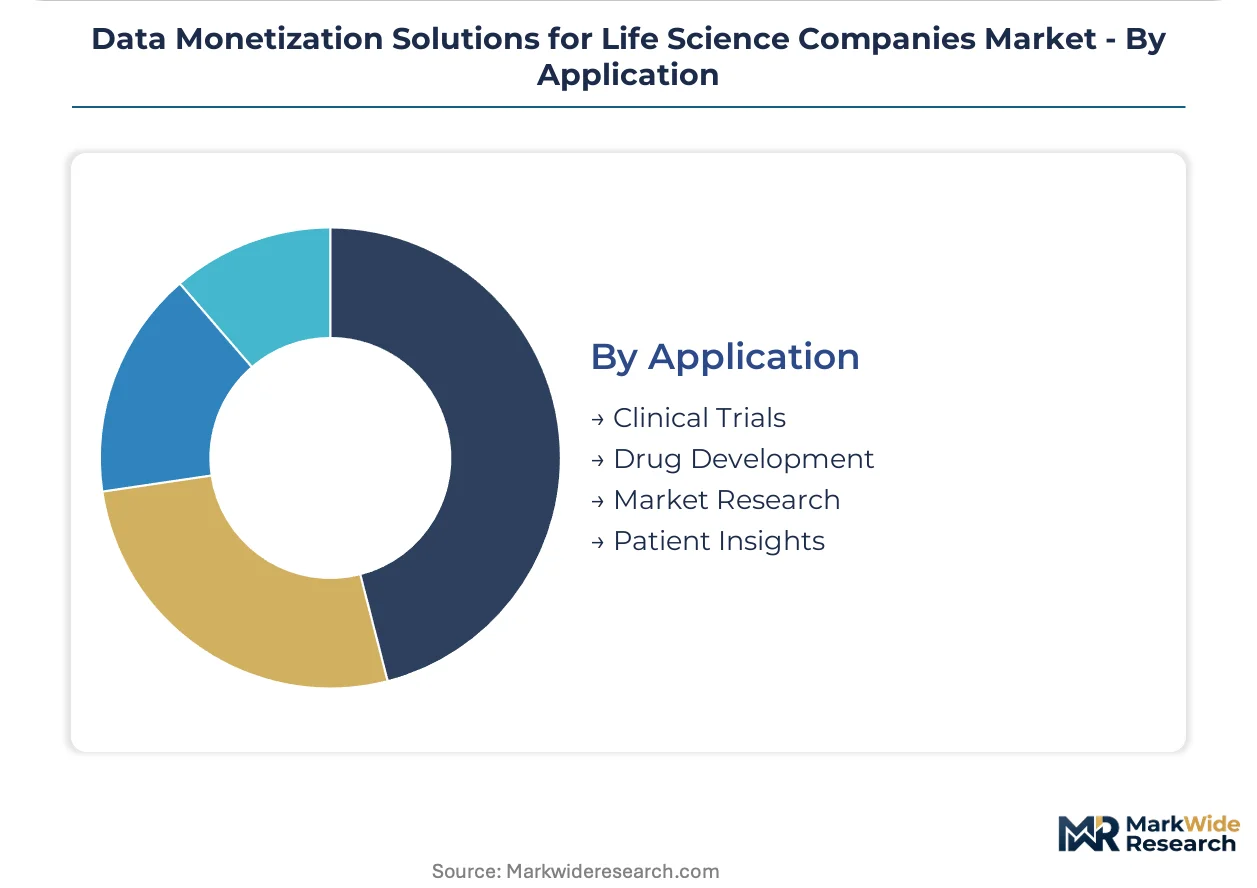
Application:
Maturity gradient separates established clinical workflows from emerging commercial intelligence categories.
- Clinical Trials:Patient recruitment optimization, site feasibility scoring, and digital endpoint validation anchor established demand. EMA Clinical Trials Regulation transparency mandates accelerate automated redaction and structured data transformation tooling procurement.
- Drug Development:Target identification and biomarker discovery leverage multi-omic data integration. Genomic data storage cost escalations squeeze margin on fixed-price contracts, favoring vendors with cloud infrastructure scale.
- Market Research:Competitive intelligence and prescriber segmentation utilize aggregated claims and formulary data. Compact treatment—procurement consolidation subsumes this category into broader commercial analytics suites.
- Patient Insights:Adherence monitoring and patient-reported outcome collection through wearable devices. Compact treatment—regulatory validation of digital endpoints remains incomplete outside cardiovascular therapeutic areas.
Clinical Trials command established procurement budgets; Patient Insights gain share fastest as continuous monitoring technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States sponsors prioritize regulatory-grade provenance and investigator network scale. European buyers emphasize GDPR-compliant federated architectures. Asian markets favor modular, consumption-based pricing to preserve biotech runway.
United States
FDA real-world evidence mandates and health system consolidation drive platform adoption. The 21st Century Cures Act interoperability provisions force FHIR-standard rebuilds. Greater Boston anchors clinical data science clusters where de-identification pipelines process millions of patient records.
Germany
EMA Clinical Trials Regulation transparency requirements accelerate automated redaction tooling procurement. GDPR constraints favor federated query models over centralized data lakes. The Rhine-Ruhr corridor hosts compliance architecture specialists serving multinational sponsors.
Switzerland
Pharmaceutical headquarters concentration creates demand for multi-jurisdiction governance frameworks. Swissmedic alignment with EMA standards simplifies European market access preparation. Basel anchors regulatory-grade data provenance operations for top-20 sponsors.
United Kingdom
NHS Digital restructuring creates unified national datasets attractive to commercial analytics vendors. MHRA post-Brexit regulatory autonomy diverges from EMA pathways, complicating platform architectures. London's health tech corridor concentrates AI-enabled evidence synthesis startups.
India
CDSCO digital health guidelines and cost-sensitive biotech procurement favor cloud-native, per-study pricing models. The country's investigator network expansion supports regulatory-grade data collection. Hyderabad and Bengaluru anchor clinical data management outsourcing clusters.
Data Monetization Solutions for Life Science Companies Market Competitive Landscape
Capability concentration sits with established data aggregators possessing investigator networks and historical trial repositories; scale advantage sits with cloud infrastructure providers offering elastic storage and federated analytics. The market structure reflects tiered specialization rather than consolidation. Three archetypes dominate: full-stack platform vendors, cloud-native analytics entrants, and contract research organizations internalizing data capabilities. Competitive moves center on procurement consolidation around integrated evidence ecosystems and AI automation compressing professional services margins.
Among cloud infrastructure providers, Microsoft Corporation exemplifies the scale-driven archetype through enterprise data federation capabilities. IQVIA occupies a position representing established data aggregation with proprietary site relationships. Oracle Corporation sits within the full-stack platform tier, extending database architectures into vertically integrated clinical and commercial stacks.
| Leading Market Players |
|---|
| Oracle Corporation |
| Microsoft Corporation |
| Salesforce, Inc. |
| SAP SE |
| SAS Institute Inc. |
| IQVIA |
| Parexel International |
| Tempus |
| Clarivate |
| Others |
Value Network & Pricing Analysis
Greater Boston's clinical data science clusters anchor North American capacity for de-identification pipelines and regulatory-grade evidence generation, concentrating cloud infrastructure spend among pharmaceutical sponsors and compressing margin pools for mid-tier vendors lacking federated analytics scale.
Pricing Analysis
Long-term platform licensing contracts dominate enterprise procurement, though project-based analytics engagements capture share among runway-constrained biotechs. Three-tier pricing structure across premium, standard, and economy levels separates full-stack vendors with investigator networks from modular cloud-native entrants. Cost compression in genomic data storage is intensifying because petabyte-scale whole-genome sequencing repositories face escalating annual obligations. Biotech firms exhibit highest price sensitivity due to venture financing cycles, while top-20 pharmaceutical sponsors prioritize regulatory-grade provenance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hardware-dependent genomic sequencing infrastructure. Cloud computing capacity concentrates in the United States, Ireland, and Singapore, with AWS and Azure health data lakes drawing from these hubs. The technology stack rests on specialized GPUs, FHIR-standard middleware, and proprietary investigator network access. Distribution runs through direct enterprise sales teams and strategic partnerships with contract research organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Life science data monetization sits in early-cycle expansion as FDA real-world evidence mandates force pharmaceutical sponsors toward integrated platforms faster than legacy vendor roadmaps can accommodate.
For Market Incumbents: Pre-empt cloud-native entrants by embedding AI automation into evidence synthesis workflows before large language models commoditize systematic literature review services. Consolidate investigator network access through exclusive site partnerships, as IQVIA's proprietary relationships already create data provenance bottlenecks for competitors. Prioritize FHIR implementation expertise acquisition to compress platform modernization timelines for health system clients facing 21st Century Cures Act deadlines. For New Entrants and Emerging Players: India's CDSCO-aligned biotech procurement environment offers the steepest penetration trajectory for consumption-based, per-study pricing models that preserve venture runway. Target mid-sized European biotechs lacking in-house EMA Clinical Trials Regulation compliance infrastructure with automated redaction and transparency workflow tools. Lead with wearable-derived digital endpoints in cardiovascular therapeutic areas where regulatory validation pathways remain incomplete and incumbent platforms hold weaker positions. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical IT divisions and health system innovation labs possessing dormant FHIR-compliant data architectures but lacking commercialization infrastructure. Position holdings for a 5-10 year window where AI-enabled evidence synthesis displaces traditional professional services hours and reshapes vendor economics. Monitor FDA guidance publication velocity on digital endpoints as the signal indicating when wearable-derived data streams achieve regulatory-grade status and unlock premium pricing tiers.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Standard Platform Migration | 21st Century Cures Act mandates force health system clients toward cloud-native interoperability architectures. |
| AI-Enabled Evidence Synthesis | Large language models automate systematic literature review and compress traditional time-and-materials pricing for CRO services. |
| Investigator Network Consolidation | Exclusive site partnerships create regulatory-grade data provenance barriers against cloud-native analytics entrants. |
| Wearable-Derived Endpoint Development | Apple Watch and Fitbit continuous monitoring data streams open pharmacovigilance products in cardiovascular therapeutic areas. |
| EMA Transparency Workflow Automation | Clinical Trials Regulation mandatory disclosure windows create demand for automated redaction pipelines among mid-sized biotechs. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration across primary interview cycles. These practitioner inputs combined with FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary database audits through bottom-up and top-down triangulation. Secondary validation drew from SEC disclosures of publicly traded platform vendors and hyperscaler health cloud capex announcements.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning service type, technology tier, end user archetype, and therapeutic area application. CAGRs derived from modeled adoption curves for real-world evidence platforms and cloud infrastructure spend trajectories. Forecast inputs incorporated FDA guidance publication schedules, health system consolidation velocity, and genomic data storage cost escalations.
Practitioners should monitor FDA digital endpoint validation decisions and EMA transparency enforcement patterns for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Enterprise Mobility Market
Digital Solutions
Kenya ICT Market
Digital Solutions
Water Level and Storage Monitoring Software Market
Digital Solutions
Electronic Records Management Solutions Market
Digital Solutions
Global Software Defined Everything (SDE) Market
Digital Solutions
US Customer Communication Management (CCM) Market
Digital Solutions
Global Surface Computing Market
Digital Solutions
Global Enterprise Mobility Management (EMM) Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Asia-Pacific Route Optimization Software Market
Digital Solutions
Cloud Manufacturing Execution System (MES) Market
Digital Solutions
Contactless Ticketing Ics Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
Web Performance Optimization (WPO) Solution Market
Digital Solutions
Global Domain and Hosting Market
Digital Solutions
API Management Market