
 Component (Document) Content Management System Market | 2026-2036
Component (Document) Content Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Component (Document) Content Management System Market Outlook
Subscription-based software-defined feature layers is restructuring how component content management capabilities are monetized, shifting perpetual licenses toward recurring revenue models. Adobe leverages its creative cloud infrastructure to extend document authoring workflows into structured component management. OpenText anchors enterprise deployments through deep integration with existing content repositories and governance frameworks. IXIASOFT specializes in DITA-native architectures that dominate technical documentation verticals requiring granular content reuse.
A Component (Document) Content Management System is a software platform that decomposes documents into modular, reusable information components governed by XML-based schemas such as DITA or custom metadata taxonomies, enabling single-source publishing across multiple output formats. Its primary commercial purpose is to eliminate content redundancy, ensure version consistency, and accelerate regulatory submission timelines for organizations managing high-volume documentation. Cloud-based deployments now capture the fastest expansion as enterprises retire on-premises infrastructure, while hybrid architectures retain stronghold status among financial services firms with data residency requirements. AI-powered technology segments are drawing disproportionate R&D investment as vendors embed generative capabilities for automated component tagging and semantic assembly.
FDA 21 CFR Part 11 electronic records requirements and the EU AI Act's documentation traceability mandates are reshaping product roadmaps toward audit-ready component lineage. ISO 27001 and SOC 2 Type II certifications have become baseline market access credentials rather than differentiators for vendor selection. Stakeholders must evaluate whether their current platforms can map individual content components to automated compliance evidence chains without manual reconstruction.
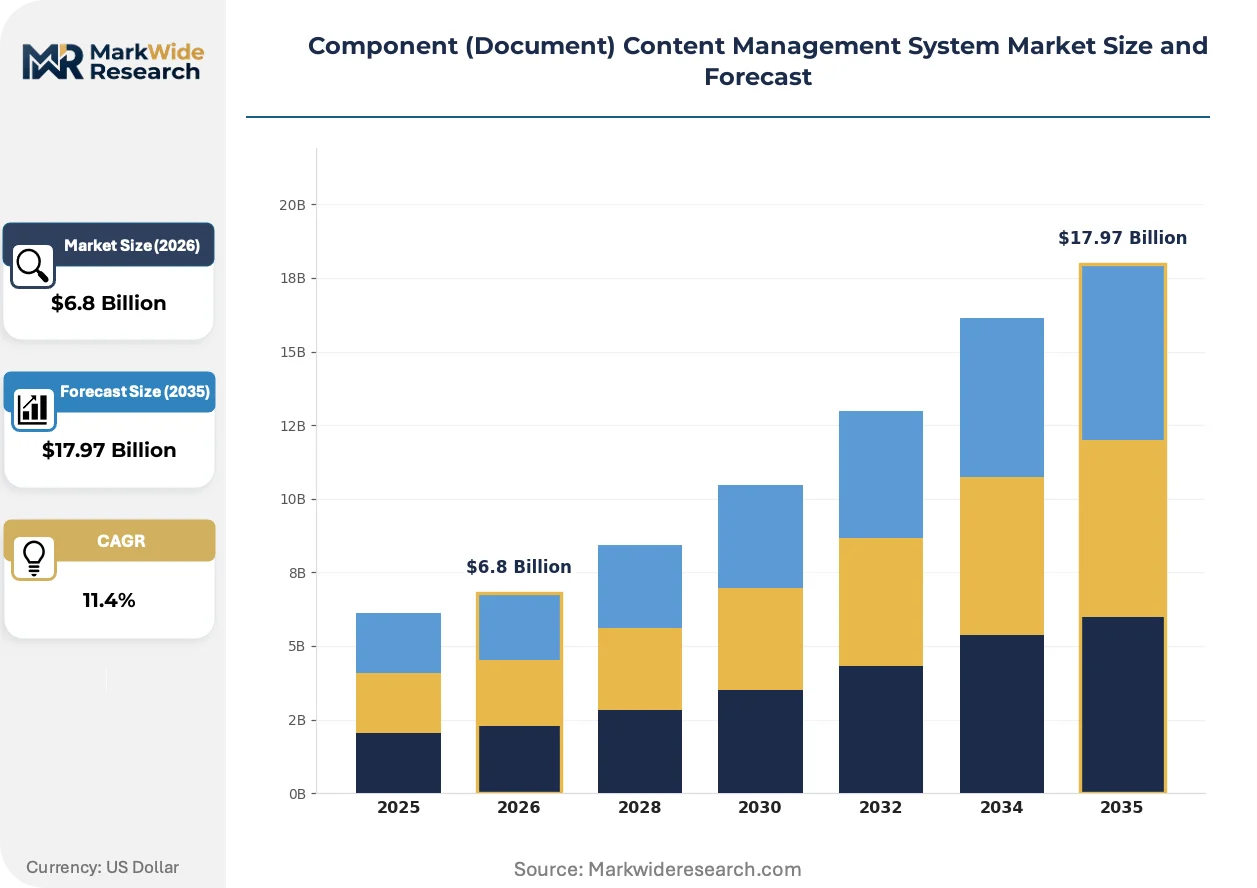
Market Dynamics
Cloud migration mandates under the EU AI Act and FDA digital submission guidelines are compressing platform replacement cycles, forcing enterprises to retire legacy on-premises systems before depreciation schedules complete.
Growth Catalysts
- EU AI Act documentation traceability:Healthcare providers in Germany and France must maintain auditable component lineage for algorithmic decision systems, driving demand for structured content repositories.
- Industrial equipment complexity:German automotive and machinery manufacturers require component-level traceability for aftermarket service documentation, creating pull for DITA-native architectures.
- XML schema standardization:DITA and custom metadata taxonomies now govern technical documentation across regulated industries, enabling single-source publishing and accelerating regulatory submission timelines.
Market Restraints
- Data residency requirements:Financial services firms in Switzerland and Germany retain hybrid architectures due to national banking secrecy laws, slowing pure cloud adoption.
- Legacy system entrenchment:Enterprises with decades of unstructured document repositories face prohibitive migration costs for content deconstruction and metadata tagging.
- Skills scarcity:The shortage of information architects proficient in DITA specialization and taxonomic design constrains implementation velocity for complex deployments.
Strategic Opportunities
- Generative AI integration:Automated component tagging and semantic assembly capabilities are expanding into pharmaceutical labeling workflows, reducing manual curation overhead.
- Medical device vertical:FDA 21 CFR Part 11 compliance requirements for electronic records create dedicated demand for audit-ready component lineage systems.
- Subscription monetization:Perpetual license holders represent a conversion base for recurring revenue models as vendors restructure pricing around software-defined feature layers.
Industry Challenges
- ISO 27001 certification timelines:Vendors must maintain SOC 2 Type II and ISO 27001 credentials as baseline market access requirements, extending sales cycles.
- Semantic interoperability gaps:Mapping proprietary content components to automated compliance evidence chains without manual reconstruction remains technically unresolved.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Component (Document) Content Management System Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-based, Cloud-based, On-premises, Hybrid Deployment Model: Private Cloud, Public Cloud, Multi-tenant, Single-tenant End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Technology: AI-powered, Blockchain, Workflow Automation, Optical Character Recognition |
| Companies Covered | Adobe, IXIASOFT, OpenText, Vasont Systems, Author-it, Documoto, Bluestream, Dakota Systems, Paligo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Component (Document) Content Management System Market Strategic Shifts
Generative AI capabilities are embedding into core platform architectures, reshaping how content components are tagged, assembled, and validated across regulated documentation workflows.
Large language models trained on DITA schemas are expanding into automated component classification and relationship mapping. Pharmaceutical and medical device manufacturers in the United States and Germany are piloting these systems for regulatory submission preparation. This capability compression is reducing manual curation cycles from weeks to days for complex documentation sets.
The EU AI Act's documentation traceability mandates are forcing platform vendors to embed immutable audit logs at the component level. Industrial equipment manufacturers in Germany must now demonstrate lineage for every technical specification referenced in AI-driven maintenance systems. Vendors are responding with blockchain-anchored provenance features designed for cross-border regulatory acceptance.
Buyer procurement patterns are compressing vendor evaluation cycles as compliance deadlines harden. Healthcare systems in France and the Netherlands now prioritize pre-certified platforms with existing FDA or EMA submission track records over custom configurations. This preference shift favors established vendors with documented regulatory acceptance over emerging entrants.
Component (Document) Content Management System Market Segmentation
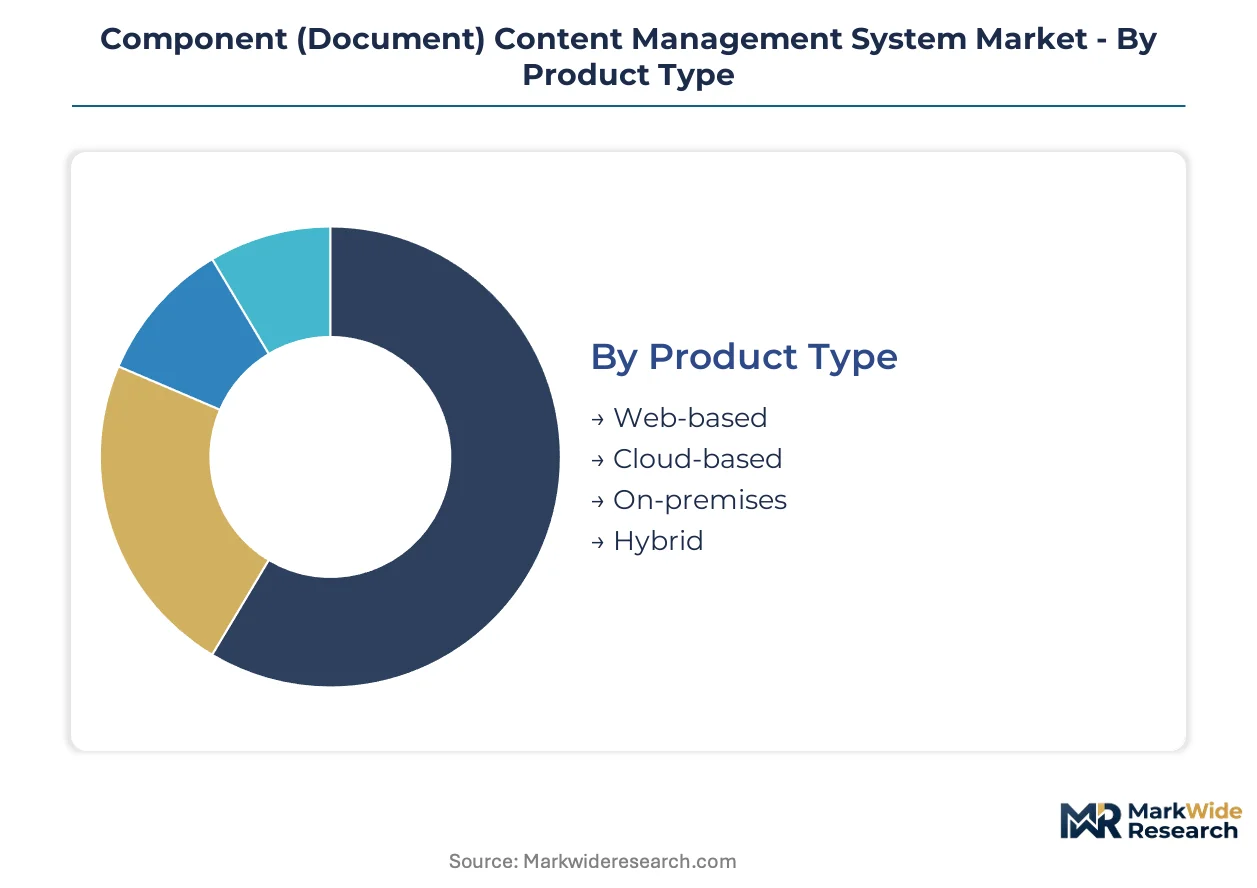
Segmentation in the Component (Document) Content Management System market reveals how deployment architectures, user scale, and technology sophistication create distinct commercial battlegrounds. Vendors must align platform capabilities with specific compliance requirements and infrastructure constraints rather than pursuing undifferentiated positioning.
Product Type:
Supply concentration among cloud infrastructure providers shapes how product delivery models compete for enterprise procurement budgets.
- Cloud-based:Fully managed SaaS platforms eliminate capital expenditure for hardware and reduce IT operational overhead. Healthcare systems in Germany and France favor these deployments for EU AI Act compliance, where vendors assume responsibility for audit log maintenance and security patching.
- Hybrid:Architectures split sensitive content storage on-premises while leveraging cloud processing for non-critical workflows. Swiss and German financial institutions retain this model under banking secrecy laws that prohibit pure public cloud for client documentation.
- Web-based:Browser-accessible platforms with minimal local installation requirements serve distributed teams with limited IT support.
- On-premises:Self-hosted installations persist in defense and intelligence sectors with air-gapped security mandates.
Cloud-based deployments absorb the bulk of installed capacity; hybrid architectures are expanding most quickly among regulated industries with data residency requirements.
Deployment Model:
Cost tier differentiation separates enterprise-grade isolation from multi-tenant economies of scale.
- Private Cloud:Dedicated infrastructure instances deliver single-tenant isolation with cloud-like operational models. Pharmaceutical manufacturers in the United States deploy these for FDA 21 CFR Part 11 validation, where shared environments complicate audit trail integrity.
- Multi-tenant:Shared resource pools drive per-seat pricing below private alternatives. Mid-market technical documentation teams in France and the Netherlands accept standardized configurations to accelerate procurement timelines.
- Public Cloud:Hyperscaler-hosted deployments leverage existing enterprise cloud contracts and identity federation.
- Single-tenant:Physically isolated instances serve organizations with explicit contractual prohibitions on resource commingling.
Multi-tenant configurations dominate new subscription volume; private cloud deployments command premium pricing for compliance-critical use cases.
End User:
Application complexity scales directly with organizational size and documentation volume.
- Large Enterprises:Global manufacturers with distributed engineering teams require component-level reuse across thousands of product variants. German automotive suppliers deploy DITA-native systems to synchronize technical documentation across assembly plants in multiple countries.
- SMEs:Mid-sized organizations prioritize rapid implementation over customization. Regional medical device distributors in the United States adopt pre-configured templates for FDA submission packages rather than building bespoke workflows.
- Government Agencies:Public sector procurement emphasizes FedRAMP or equivalent security certifications over feature breadth.
- Educational Institutions:Universities manage research documentation and grant compliance with limited dedicated IT staffing.
Large enterprises contribute the majority of annual contract value; SMEs are climbing the fastest as vendors introduce tiered pricing for entry-level configurations.
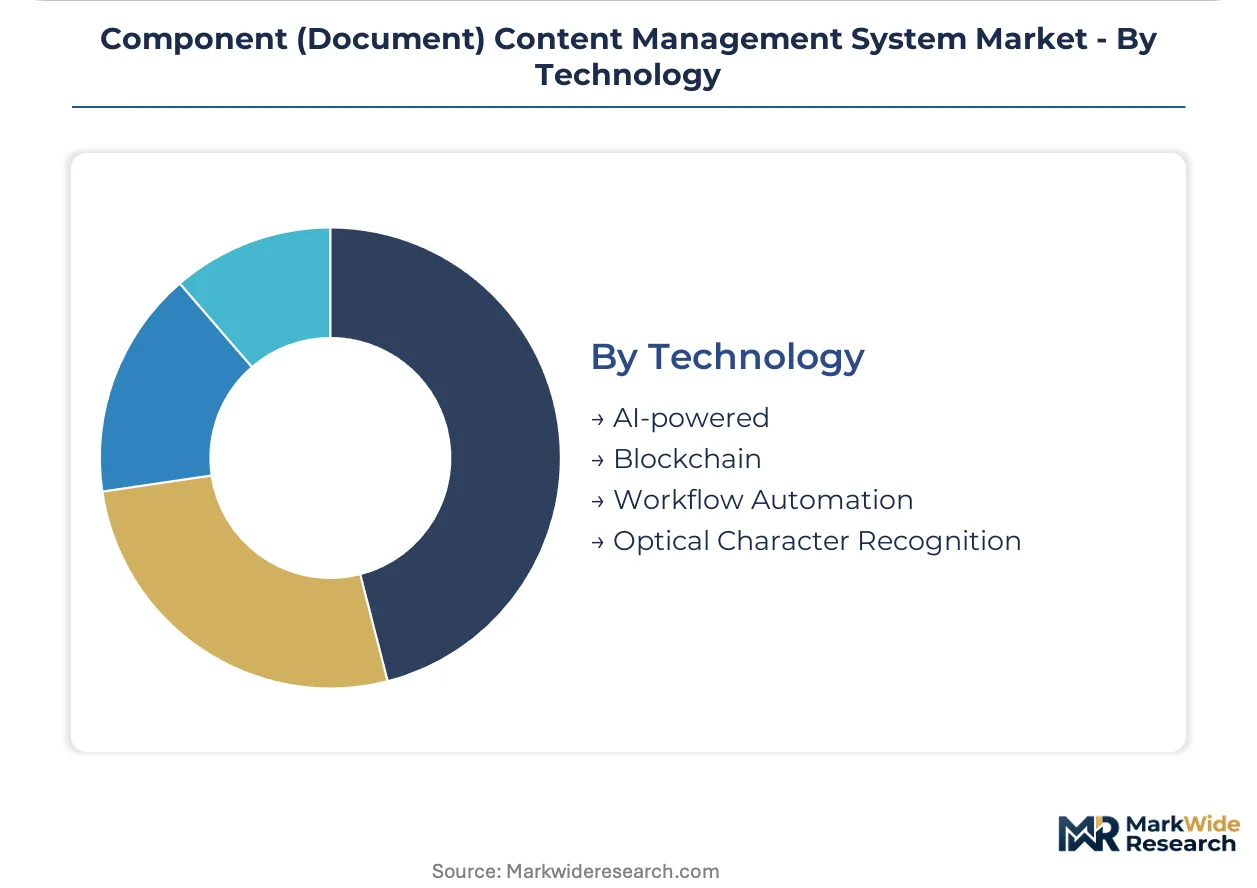
Technology:
Customer sophistication separates early AI adopters from organizations prioritizing proven automation.
- AI-powered:Machine learning models trained on DITA schemas automate component classification and relationship mapping. Pharmaceutical labeling teams in Germany pilot these systems to compress regulatory submission preparation from weeks to days.
- Workflow Automation:Rules-based orchestration engines route content through approval chains with conditional logic. Medical device manufacturers rely on these proven systems for FDA traceability requirements where AI decisions resist audit reconstruction.
- Blockchain:Immutable provenance logs address EU AI Act documentation lineage mandates for algorithmic decision systems.
- Optical Character Recognition:Legacy document digitization bridges paper archives to structured component repositories.
Workflow automation retains the largest installed base; AI-powered capabilities are gaining share fastest as vendors integrate generative models into core platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software vendors concentrate engineering capacity in the United States and Germany while consumption spreads across regulated industries in France, Switzerland, and Japan. Cloud infrastructure investments favor hyperscaler regions with established data center footprints. Procurement decisions increasingly hinge on pre-existing regulatory certifications rather than feature comparisons.
United States
FDA 21 CFR Part 11 electronic records mandates drive pharmaceutical and medical device manufacturers toward audit-ready component lineage systems. The agency's digital submission guidelines compress platform replacement timelines for legacy document repositories. Boston's medical technology cluster hosts pilot deployments of AI-powered component classification for regulatory submission preparation.
Germany
Industrial equipment manufacturers require component-level traceability for aftermarket service documentation under EU AI Act documentation lineage requirements. KBA vehicle type approval processes intersect with algorithmic maintenance system documentation needs. Stuttgart's automotive supplier ecosystem deploys DITA-native architectures to synchronize technical documentation across multinational assembly networks.
Switzerland
Banking secrecy laws under national financial regulations prohibit pure public cloud deployment for client documentation, sustaining hybrid architecture demand. Swissmedic pharmaceutical oversight creates parallel requirements for electronic records traceability. Zurich's private banking sector retains on-premises content storage while leveraging cloud processing for non-critical workflow orchestration.
France
Healthcare systems prioritize pre-certified platforms with existing EMA submission track records over custom configurations as EU AI Act compliance deadlines approach. ANSM pharmaceutical oversight reinforces documentation traceability requirements for algorithmic decision systems. Paris-based hospital networks accelerate procurement cycles for structured content repositories with embedded immutable audit logs.
Japan
PMDA pharmaceutical review procedures emphasize electronic submission formats that favor XML-schema governance for regulatory documentation. METI industrial digitization programs promote component content management adoption among precision equipment manufacturers. Osaka's medical device production corridor integrates structured content repositories with existing quality management system infrastructure.
Component (Document) Content Management System Market Competitive Environment
Capital-heavy platform developers compete with asset-light specialized architects for enterprise procurement budgets. The vendor landscape organizes around three strategic tiers: hyperscaler-integrated suites, DITA-native specialists, and vertical workflow optimizers. Consolidation pressure intensifies as compliance certification costs favor scaled incumbents with existing audit infrastructure. Dominant competitive moves include strategic partnerships with cloud infrastructure providers and technology licensing arrangements for AI-powered component classification capabilities.
Within the creative cloud infrastructure tier, Adobe leverages existing subscriber relationships to extend document authoring workflows into structured component management. OpenText anchors enterprise deployments through integration with established content governance frameworks. IXIASOFT occupies a specialist position exemplifying DITA-native architecture dominance in technical documentation verticals requiring granular content reuse protocols.
| Leading Market Players |
|---|
| Adobe |
| IXIASOFT |
| OpenText |
| Vasont Systems |
| Author-it |
| Documoto |
| Bluestream |
| Dakota Systems |
| Paligo |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure cost indices from hyperscaler providers cascade through component content management system pricing tiers, compressing margins for on-premises vendors while enabling SaaS-native platforms to capture volume through subscription elasticity. German industrial buyers absorb premium pricing for DITA-native architectures with embedded EU AI Act compliance modules, whereas mid-market technical documentation teams in France gravitate toward standardized multi-tenant configurations.
Pricing Analysis
Margin tightening in perpetual-license tiers reflects accelerated conversion pressure toward recurring SaaS models as vendors restructure feature monetization around software-defined layers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated private cloud deployments from multi-tenant SaaS and entry-level web-based access. Cost compression in standard tiers intensifies because hyperscaler infrastructure commoditizes base compute resources. SMEs exhibit highest price sensitivity, prioritizing rapid procurement over customization; pharmaceutical manufacturers demonstrate lowest sensitivity, accepting premium pricing for audit-ready component lineage.
Supply Chain Analysis
EU data sovereignty mandates under GDPR and national banking secrecy laws reshape sourcing patterns for cloud infrastructure, compelling vendors to establish dedicated regional instances. Engineering capacity concentrates in the United States, Germany, and India, with DITA specialization expertise clustering in Montreal and Stuttgart. Platform development draws from open-source XML parsing libraries, hyperscaler compute APIs, and specialized information architecture consulting pools. Single-source vulnerability persists in DITA-trained talent pipelines, constraining implementation velocity. Distribution runs through direct enterprise sales teams for large accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Component content management systems occupy a technology-transition phase where AI-powered semantic assembly displaces rules-based workflow automation as the primary value proposition. Generative capabilities for automated component tagging and relationship mapping now separate procurement winners from legacy platform defenders.
For Market Incumbents: Cement regulatory certification moats by accelerating ISO 27001 and SOC 2 Type II credential maintenance as baseline market access requirements rather than differentiators. Deepen vertical integration into information architecture training pipelines to address DITA specialization scarcity constraining implementation velocity. Defend against AI-native entrants by embedding generative models into core platform architectures before deprecation of rules-based systems accelerates.
For New Entrants and Emerging Players: Begin with SME technical documentation verticals in France and the Netherlands, where procurement cycles compress toward pre-certified platforms and buyer sophistication lags enterprise adopters. Target medical device distributors seeking FDA 21 CFR Part 11 compliance without bespoke workflow investment. Pursue channel partnerships with existing content governance consultants to bypass direct sales infrastructure requirements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor DITA-native specialists with established pharmaceutical submission track records in Germany and the United States, where EU AI Act deadlines force platform replacement regardless of depreciation schedules. Long-term viability hinges on generative AI integration depth and regulatory certification maintenance infrastructure. Watch for inflection when pharmaceutical labeling teams compress submission preparation timelines from weeks to days, signaling capability maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Integration | Automated component tagging reduces pharmaceutical labeling curation cycles for FDA submissions. |
| Regulatory Certification Investment | ISO 27001 and SOC 2 Type II credentials become baseline procurement filters under EU AI Act mandates. |
| Vertical Partnership Formation | Collaboration with Stuttgart automotive suppliers embeds component traceability into aftermarket service documentation. |
| Hybrid Architecture Expansion | Swiss banking secrecy compliance sustains demand for split on-premises storage with cloud processing. |
| DITA Talent Pipeline Development | Information architecture training programs address skills scarcity constraining German industrial deployments. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across information architects, pharmaceutical regulatory affairs leads, enterprise IT procurement officers, and technical documentation managers. Bottom-up sizing triangulated against top-down market validation using FDA 21 CFR Part 11 guidance documents, EMA submission format specifications, EU AI Act implementation texts, and hyperscaler infrastructure capex disclosures.
Segment-level modeling deployed deployment architecture, organization scale, vertical application, technology sophistication, and regional regulatory cluster as primary dimensions. CAGRs derived from installed base evolution, replacement cycle compression under compliance mandates, and subscription conversion trajectories. Forecast inputs incorporated AI capability adoption curves, DITA standardization penetration rates, and cloud infrastructure cost elasticity assumptions.
Underlying measurement precision varies by segment; cloud-based deployments carry tighter precision than hybrid architectures due to vendor disclosure practices. Forecasts reflect assumptions around regulatory deadline adherence, skills pipeline development, and hyperscaler pricing stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Bangladesh ICT Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market
Digital Solutions
Global Tag Management System Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
Service Virtualization Market
Digital Solutions
Super Apps Market
Digital Solutions
Germany Content Services Platform Market
Digital Solutions
Inventory Management Market
Digital Solutions
Multicarrier Parcel Management Solutions Software Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Global Web Hosting Service Market
Digital Solutions
Digital BSS Market