
 Polyvinyl Alcohol (PVA) Films Market | 2026-2036
Polyvinyl Alcohol (PVA) Films Market Size, Share, and Industry Trends Forecast 2026-2036
Polyvinyl Alcohol (PVA) Films Market Analysis
Direct-to-manufacturer supply is narrowing as regional distributors lose share to specialized polymer traders with technical service capabilities. Kuraray Co., Ltd. leverages captive polyvinyl alcohol resin production to control raw material quality across its film lines. Sekisui Chemical Co., Ltd. sustains dominance in high-purity pharmaceutical films through proprietary casting technology. MonoSol LLC competes aggressively in North American detergent pod packaging with dedicated extrusion capacity.
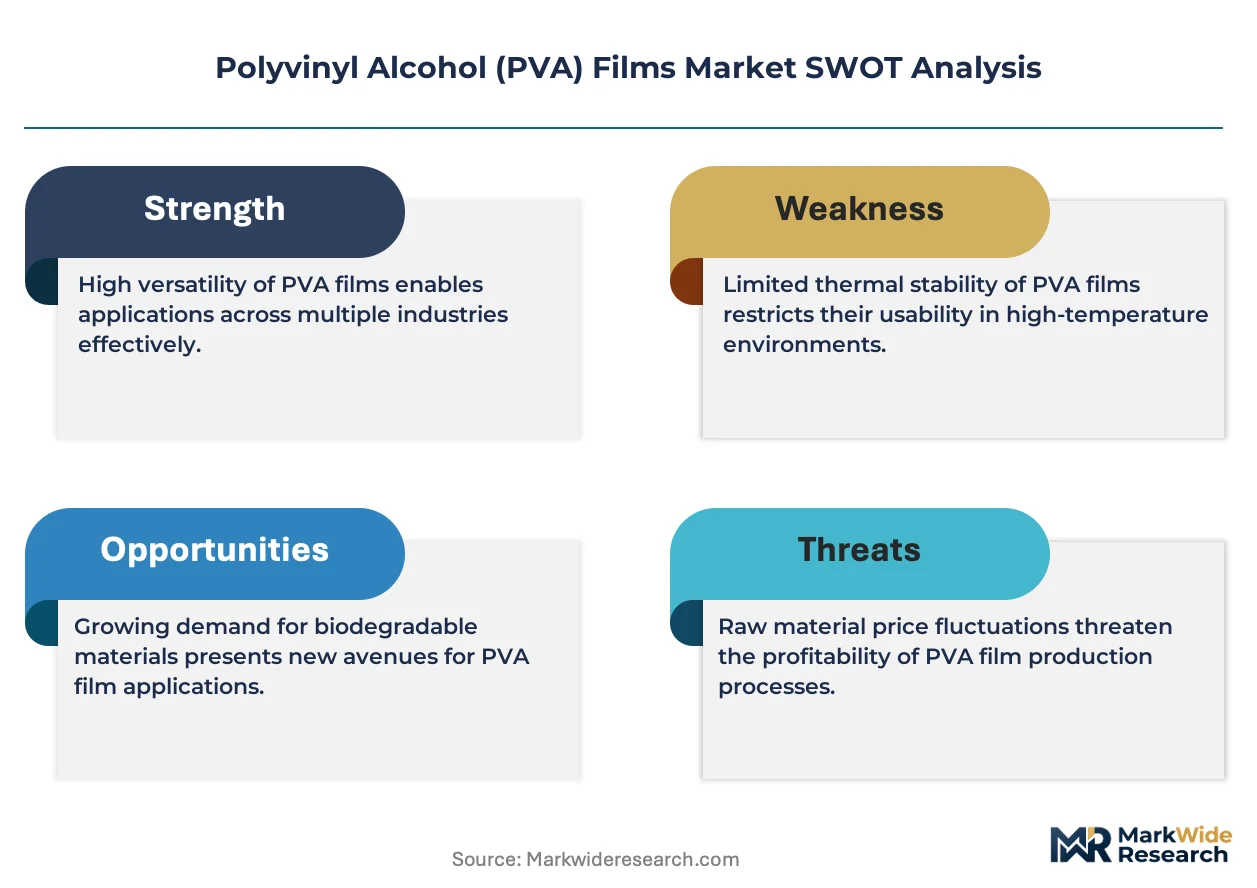
Polyvinyl alcohol films are synthetic polymer membranes manufactured by casting or extruding partially hydrolyzed polyvinyl alcohol resin, typically exhibiting tensile strength of 20-60 MPa and complete water solubility above specific temperature thresholds. These films function primarily as protective barriers, controlled-release layers, and process aids across packaging, pharmaceutical, and industrial applications. Water-soluble films anchor the value pool due to concentrated demand from unit-dose detergent and agrochemical packaging, while biodegradable variants gain structural importance as brand owners face extended producer responsibility mandates. Pharmaceutical film coating applications generate premium margins compared to standard packaging grades, reflecting stringent purity and traceability requirements.
The US EPA regulates volatile organic compound emissions from solvent-based coating processes, indirectly steering film manufacturers toward aqueous PVA formulations. REACH compliance in Europe constrains residual monomer levels in food-contact and medical-grade films, raising technical barriers for non-European suppliers. China's GB standards for packaging materials enforce specific migration limits that shape export-oriented production protocols. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to build regional compounding capacity or deepen toll-manufacturing partnerships.
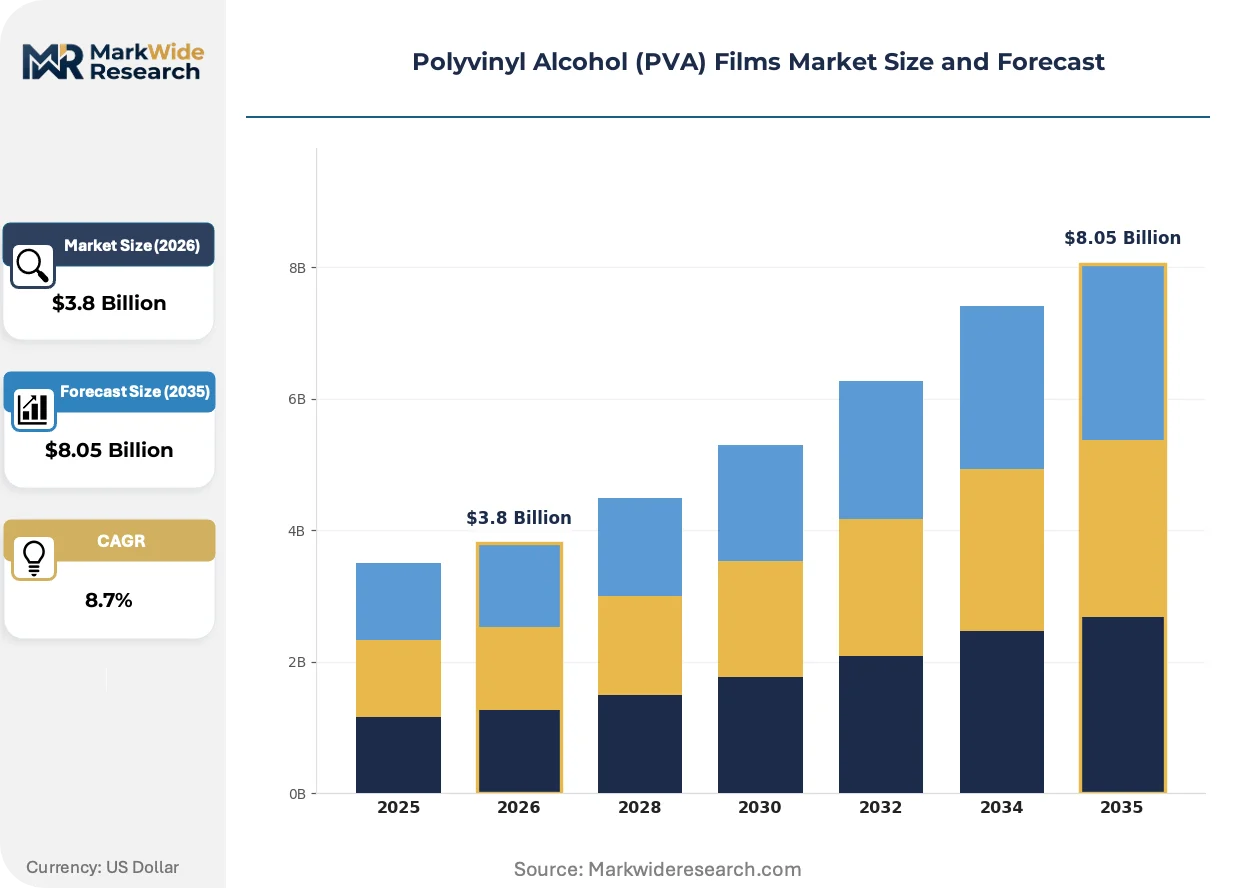
Market Dynamics
Europe's Single-Use Plastics Directive is forcing rapid material substitution across consumer packaging, concentrating investment in aqueous extrusion capacity and pharmaceutical-grade casting lines as manufacturers race to preempt extended producer responsibility mandates.
Growth Catalysts
- REACH compliance thresholds:Residual monomer limits in food-contact and medical-grade films are accelerating technical upgrades among European compounders, creating captive demand for high-purity resin.
- Unit-dose detergent packaging:Consumer goods manufacturers are replacing conventional plastic pods with water-soluble formats to meet retailer sustainability commitments.
- China:Domestic producers are scaling pharmaceutical-grade film capacity specifically for export markets, reshaping regional supply balances.
Market Restraints
- Vinyl acetate monomer volatility:Feedstock price swings compress margin predictability for non-integrated film extruders lacking captive resin supply.
- Japan and Germany supply concentration:Proprietary casting technology for high-purity pharmaceutical films remains concentrated among limited specialized polymer traders.
- Polyethylene barrier films:Lower-cost conventional plastics retain structural preference in non-regulated industrial wrapping applications.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO traceability requirements for solid-dose formulations are opening demand for imported coating-grade films.
- Agrochemical unit-dose:Water-soluble packaging for crop protection chemicals remains underpenetrated relative to detergent applications.
- EU Green Deal carbon accounting:Biodegradable PVA variants gain structural importance as brand owners face Scope 3 disclosure obligations.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA validation protocols for film coating applications extend commercialization cycles by 18-24 months.
- Casting technician scarcity:Specialized polymer film process engineering expertise concentrates among aging workforces in Japan and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyvinyl Alcohol (PVA) Films Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Soluble, Biodegradable, Coating, Adhesives End User: Packaging, Textile, Agriculture, Pharmaceuticals Application: Film Coating, Protective Film, Release Film, 3D Printing Form: Sheets, Granules, Powders, Films |
| Companies Covered | Kuraray Co., Ltd., Sekisui Chemical Co., Ltd., Mitsubishi Chemical Group Corporation, Aicello Corporation, Nippon Synthetic Chemical Industry Co., Ltd., MonoSol LLC, Chang Chun Group, Jiangmen Proudly Water-Soluble Plastic Co., Ltd., Foshan Polyva Materials Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyvinyl Alcohol (PVA) Films Market Emerging Trajectories
Digital process control systems are virtualizing quality assurance workflows across casting and extrusion lines, compressing batch-to-batch variation while enabling real-time regulatory documentation for pharmaceutical customers.
Multi-layer co-extrusion with ethylene vinyl alcohol is virtualizing barrier performance in unit-dose packaging, allowing detergent manufacturers to match shelf-life specifications of conventional plastics. European consumer goods brands are adopting these structures fastest. The technology is virtualizing the technical compromise between solubility speed and moisture protection.
EPA volatile organic compound regulations for solvent-based coating processes are steering film manufacturers toward aqueous PVA formulations. Industrial laundries and textile treatment facilities face compliance deadlines. North American packaging converters are retrofitting drying systems to accommodate water-borne chemistries.
Brand-owner sustainability scorecards are compressing supplier qualification cycles, favoring polymer traders with technical service capabilities over traditional regional distributors. Procurement teams at multinational consumer goods companies now mandate carbon footprint documentation. This pattern is most visible in Germany and France where retailer private-label commitments drive upstream specification changes.
Polyvinyl Alcohol (PVA) Films Market Segmentation
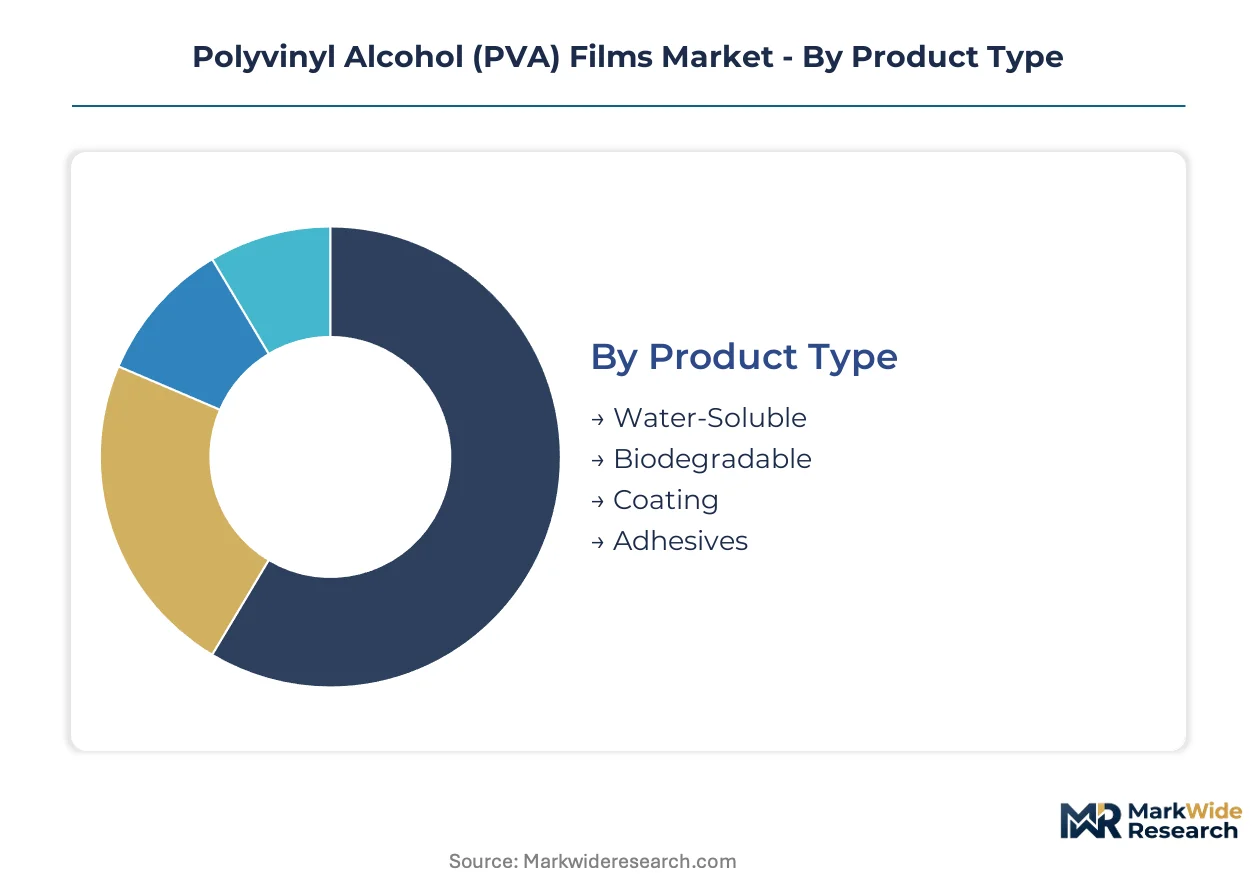
PVA film performance varies sharply across formulation chemistry and downstream processing requirements. Segmentation reveals how water solubility specifications, barrier properties, and regulatory compliance tiers create distinct value pools with divergent margin structures.
Product Type:
Water-soluble formats anchor the value pool, while biodegradable variants gain structural importance under extended producer responsibility mandates.
- Water-Soluble:Cast or extruded from partially hydrolyzed resin with tensile strength of 20-60 MPa and complete dissolution above temperature thresholds. Detergent pod packaging in Germany and France concentrates demand as retailers enforce plastic reduction commitments.
- Biodegradable:Engineered for microbial decomposition in wastewater treatment and soil environments. EU Green Deal carbon accounting obligations are accelerating brand-owner procurement of these variants for Scope 3 disclosure compliance.
- Coating:Pharmaceutical-grade formulations for solid-dose tablet film coating.
- Adhesives:Water-borne bonding layers for paper and textile lamination.
The dominant share belongs to Water-Soluble, while Biodegradable is closing the gap fastest.
End User:
Packaging applications generate volume, but pharmaceutical customers command premium pricing through purity and traceability requirements.
- Packaging:Unit-dose detergent pods, agrochemical sachets, and food-contact films. China's domestic producers are scaling capacity specifically for export markets, reshaping regional supply balances.
- Pharmaceuticals:Tablet film coating, capsule sealing, and transdermal delivery systems. FDA and EMA validation protocols extend commercialization cycles by 18-24 months, creating defensible margin premiums for qualified suppliers.
- Textile:Warp sizing and temporary bonding applications in yarn processing.
- Agriculture:Seed tape matrices and controlled-release fertilizer coatings.
Packaging commands the largest volume position, though Pharmaceuticals delivers the steepest expansion trajectory in value terms.
Application:
Functional requirements range from passive barrier protection to active controlled-release engineering across processing environments.
- Film Coating:Applied as thin functional layers to modify dissolution, appearance, or stability of solid-dose pharmaceuticals. CDSCO traceability requirements in India are opening import demand for coating-grade films from qualified suppliers.
- Protective Film:Temporary surface barriers for electronics, glass, and metal processing. Industrial laundries and textile treatment facilities face EPA volatile organic compound compliance deadlines, steering procurement toward aqueous PVA formats.
- Release Film:Non-stick interlayers for composite manufacturing and adhesive processing.
- 3D Printing:Dissolvable support structures for complex geometries in additive manufacturing.
Film Coating holds the revenue concentration, with Protective Film expanding most quickly through sustainability-driven material substitution.
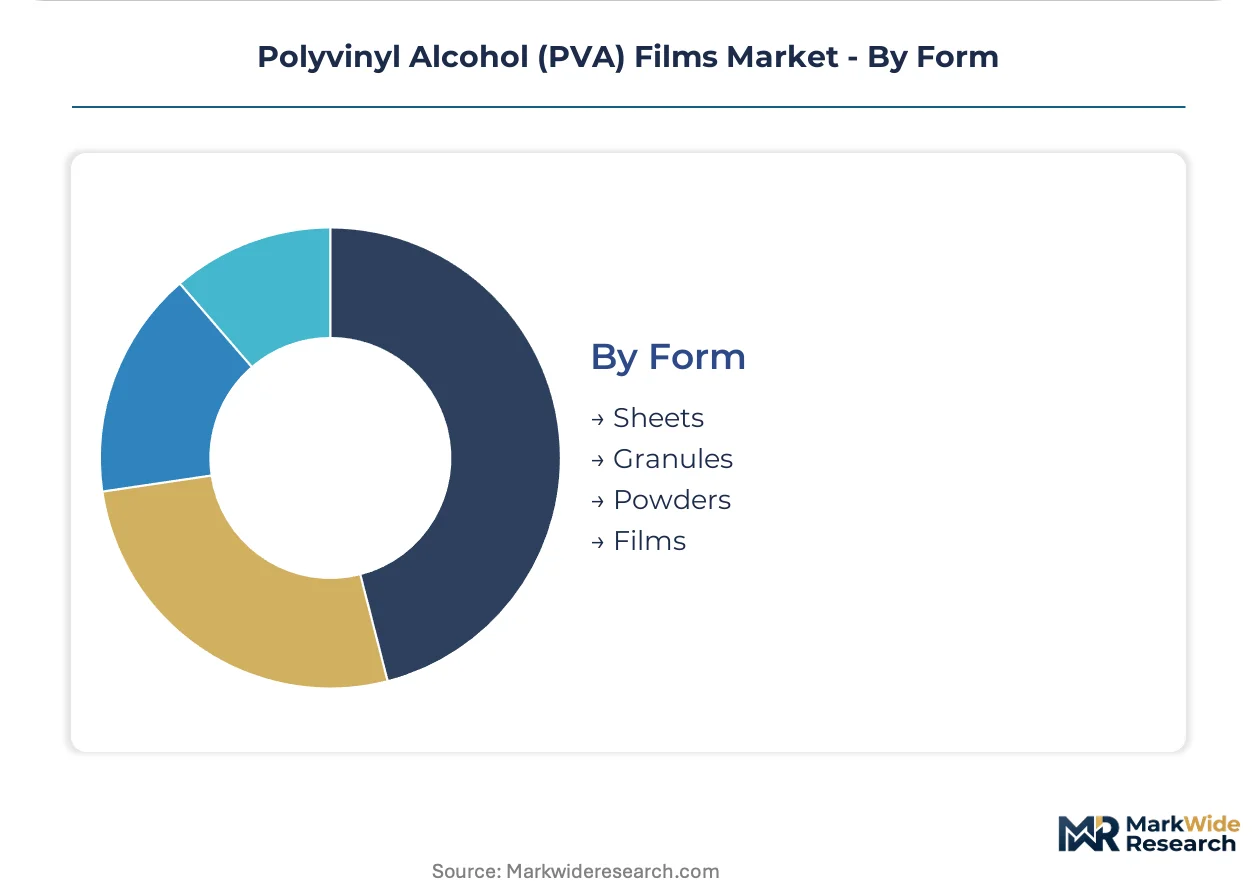
Form:
Physical presentation determines processing compatibility across casting, extrusion, and dissolution workflows.
- Films:Pre-formed membranes supplied in rolls or cut sheets for direct conversion. Multi-layer co-extrusion with ethylene vinyl alcohol is virtualizing barrier performance in European detergent packaging, matching shelf-life specifications of conventional plastics.
- Sheets:Flat-stock formats for die-cutting and thermoforming operations.
- Granules:Pelletized resin for reconstitution and custom compounding.
- Powders:Fine particulate for dissolution-based application systems.
Films dominate current offtake, while Granules are gaining share fastest among compounders seeking formulation flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European compounders command pricing premiums against Chinese export volumes due to REACH-mandated purity certifications, while Japanese and German technical-grade producers defend margin positions through proprietary casting capabilities unavailable elsewhere.
United States
Unit-dose detergent packaging at Procter & Gamble and Reckitt Benckiser facilities drives aqueous PVA formulation demand. EPA volatile organic compound regulations for solvent-based coating processes steer industrial laundries toward water-borne film systems. Cincinnati and Chicago packaging corridors host retrofitting campaigns for extrusion lines handling water-soluble pod formats.
Germany
Henkel and BASF consumer goods divisions enforce plastic-reduction commitments across European supply chains. Extended producer responsibility frameworks under EU Green Deal carbon accounting obligations accelerate biodegradable PVA procurement. Düsseldorf and Ludwigshafen chemical clusters concentrate multi-layer co-extrusion capacity for barrier-performance detergent films.
China
Domestic producers scale pharmaceutical-grade film capacity targeting FDA and EMA validation for export markets. GB standards for packaging materials enforce migration limits that reshape production protocols for foreign-bound shipments. Yangtze River Delta facilities in Jiangsu and Zhejiang provinces anchor water-soluble film extrusion expansion.
Japan
Proprietary casting technology for high-purity pharmaceutical films remains concentrated among specialized polymer traders with decades of process engineering expertise. METI industrial standards reinforce technical barriers against non-domestic competitors. Osaka and Nagoya metropolitan areas house aging workforces whose expertise scarcity limits global technology transfer.
India
CDSCO traceability requirements for solid-dose pharmaceutical formulations open import demand for coating-grade films from qualified international suppliers. Domestic generic drug manufacturers expand film-coating operations to serve regulated export markets. Hyderabad and Mumbai pharmaceutical clusters drive specification upgrades for imported PVA materials.
Polyvinyl Alcohol (PVA) Films Market Vendor Landscape
Integrated resin-to-film producers and specialized casting specialists split the market into distinct capability tiers. Japanese and German players dominate high-purity pharmaceutical segments through proprietary process knowledge, while Chinese extruders capture volume positions in standard packaging grades. Three strategic archetypes prevail: captive resin integrators, technology-licensed regional compounders, and toll-manufacturing specialists. Competitive dynamics center on backward integration into polyvinyl alcohol resin supply and pharmaceutical-grade certification acquisition.
Among Japanese chemical conglomerates, Kuraray Co., Ltd. and Sekisui Chemical Co., Ltd. exemplify the integrated archetype through captive control of upstream resin quality. MonoSol LLC occupies a position as the North American detergent-pod specialist with dedicated extrusion infrastructure. These three anchors demonstrate how geographic concentration of casting expertise creates defensible positions against commoditized competition.
| Leading Market Players |
|---|
| Kuraray Co., Ltd. |
| Sekisui Chemical Co., Ltd. |
| Mitsubishi Chemical Group Corporation |
| Aicello Corporation |
| Nippon Synthetic Chemical Industry Co., Ltd. |
| MonoSol LLC |
| Chang Chun Group |
| Jiangmen Proudly Water-Soluble Plastic Co., Ltd. |
| Foshan Polyva Materials Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion during peak export seasons amplifies freight cost volatility for Chinese PVA film extruders, compressing margins on standard-grade detergent packaging while Japanese and German producers leverage proprietary casting technology to sustain premium pricing for pharmaceutical-grade material.
Pricing Analysis
The customization-premium spread between configured-to-order pharmaceutical films and standard detergent-grade extrusions runs wide, with FDA and EMA certification tiers commanding substantial markups over commodity water-soluble formats. Price differentiation rests on residual monomer compliance thresholds under REACH and GB standards, with volume scale and geographic delivery cost creating additional stratification. Cost compression in standard packaging grades is intensifying as Chinese producers expand aqueous extrusion capacity. Detergent pod manufacturers exhibit highest price sensitivity, while pharmaceutical contract manufacturers prioritize traceability and batch documentation over unit cost.
Supply Chain Analysis
Export-control regimes limiting proprietary casting equipment transfers from Japan and Germany constrain supply chain reconfiguration, preserving geographic concentration of high-purity pharmaceutical film production. Manufacturing gravity centers on China for standard water-soluble grades, Japan for pharmaceutical casting expertise, and Germany for REACH-certified compounding. Raw material dependencies draw from vinyl acetate monomer supply, partially hydrolyzed PVA resin, and ethylene vinyl alcohol co-extrusion barriers. Single-source vulnerability concentrates in specialized casting technician expertise concentrated among aging workforces in Osaka and Nagoya metropolitan areas. Distribution runs through specialized polymer traders with technical service capabilities, displacing traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story, where REACH and FDA validation protocols create switching costs that protect qualified suppliers from commoditization pressure.
For Market Incumbents: Insulate pharmaceutical-grade margin positions by deepening captive control over vinyl acetate monomer supply and accelerating casting technician knowledge-transfer programs before workforce retirement peaks. Threat substitution from multi-layer co-extrusion barrier films demands continuous R&D investment in dissolution-speed engineering. Priority lever: secure EMA and FDA validation extensions for emerging transdermal delivery applications. For New Entrants and Emerging Players: Pursue agrochemical unit-dose packaging as the most penetrable white-space segment, where water-soluble crop protection sachets remain underdeveloped relative to detergent applications. India's CDSCO traceability requirements for solid-dose pharmaceuticals create import demand for coating-grade films from qualified international suppliers. Go-to-market angle: partner with domestic generic drug manufacturers in Hyderabad and Mumbai to establish regulatory qualification credentials. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized PVA film divisions lacking pharmaceutical-grade certification focus. Long-term viability over the next decade hinges on positioning against extended producer responsibility mandates and Scope 3 carbon accounting obligations. Signal to watch: EU Green Deal procurement scorecard adoption rates among major consumer goods brand owners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Acetate Monomer | Kuraray and Sekisui preserve margin predictability against feedstock volatility through captive resin production. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA validation cycles create 18-24 month competitive moats for qualified coating-grade suppliers. |
| Multi-Layer Co-Extrusion Capacity Expansion | Henkel and BASF procurement teams in Düsseldorf prioritize barrier-performance films matching conventional plastic shelf life. |
| Specialized Polymer Trader Channel Development | Technical service capabilities displace regional distributors as brand-owner sustainability scorecards compress supplier qualification cycles. |
| Casting Technician Workforce Development | Osaka and Nagoya metropolitan expertise scarcity limits global technology transfer and preserves Japanese competitive positioning. |
Methodological Framework
Desk research of customs/trade data, SEC 10-K filings, and ECHA REACH registration databases preceded structured interviews with plant managers at extrusion facilities, procurement leads at detergent and pharmaceutical manufacturers, distribution channel partners, and technical R&D directors at resin suppliers. Primary fieldwork combined with secondary validation through ACC and Cefic industry reports enabled bottom-up capacity assessment and top-down demand triangulation across water-soluble, biodegradable, and pharmaceutical-grade segments.
Assumptions held fixed include current REACH and FDA regulatory thresholds, while vinyl acetate monomer price trajectories and EU Green Deal implementation pace were varied across scenarios. The analytical framework modeled grade tier, end-use industry, packaging format, and regional production hub dimensions throughout the forecast period. CAGRs were derived from segment-level volume build-ups cross-checked against macroeconomic drivers and industry-specific inputs including detergent pod adoption rates and pharmaceutical film-coating capacity expansion.
Sensitivities concentrate around regulatory threshold revisions, feedstock price volatility, and casting technician workforce availability. Forecasts reflect documented assumptions regarding extended producer responsibility mandate timelines and brand-owner sustainability procurement commitments. Material shifts in FDA or EMA validation protocols, or abrupt vinyl acetate monomer supply disruptions, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Printed Plastic Films Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
MOPP Packaging Films Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Japan Plastic Packaging Film Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
Nylon Films Market
Poly film
Bopet Films Market
Poly film
Resealable Films Market
Poly film
Global BOPET Packaging Films Market
Poly film
Poly Coated Paper Market
Poly film
Cellulose Film Packaging Market
Poly film
Forming Films Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
North America Polyimide Films Market
Poly film
Co Extruded Films Market