
 Double Valve Moka Pots Market | 2026-2036
Double Valve Moka Pots Market Size, Share, and Industry Trends Forecast 2026-2036
Double Valve Moka Pots Market Insights
Premium stainless steel construction is reorganizing the competitive landscape for double valve moka pots. Bialetti leverages its heritage manufacturing base in Crusinallo to sustain brand authority across European retail channels. Grosche specializes in certified aluminum sourcing and ethical supply chain positioning that differentiates its catalog in North American specialty stores. Alessi anchors the design-premium segment through architectural collaborations that command shelf placement in Milan and Tokyo.
A double valve moka pot is a pressurized stovetop or electric brewing device employing two sequential pressure-release valves to extract coffee at approximately 1.5 to 2.0 bar, yielding crema-enriched espresso-style output without pump mechanisms. Its primary commercial purpose lies in delivering consistent extraction quality for cafés, restaurants, and households seeking pump-free espresso alternatives. Stovetop and induction product types dominate unit volume, though electric variants capture margin pools in office and hospitality settings where flame restrictions apply. Stainless steel and aluminum material tiers split the market by price positioning, with steel commanding durability premiums and aluminum sustaining accessibility in household and single-serve size categories.
EU REACH and RoHS frameworks govern aluminum alloy composition and surface treatment chemicals, directly affecting foundry supplier qualification and import access for non-European manufacturers. FDA food-contact regulations in the United States and GB standards administered by SAMR in China impose parallel testing requirements on valve seal materials and pressure safety thresholds. Stakeholders must monitor evolving PFAS restrictions under ECHA review, as non-stick interior coatings face substitution pressures that will reshape material specifications and retooling timelines across the supply base.
Market Dynamics
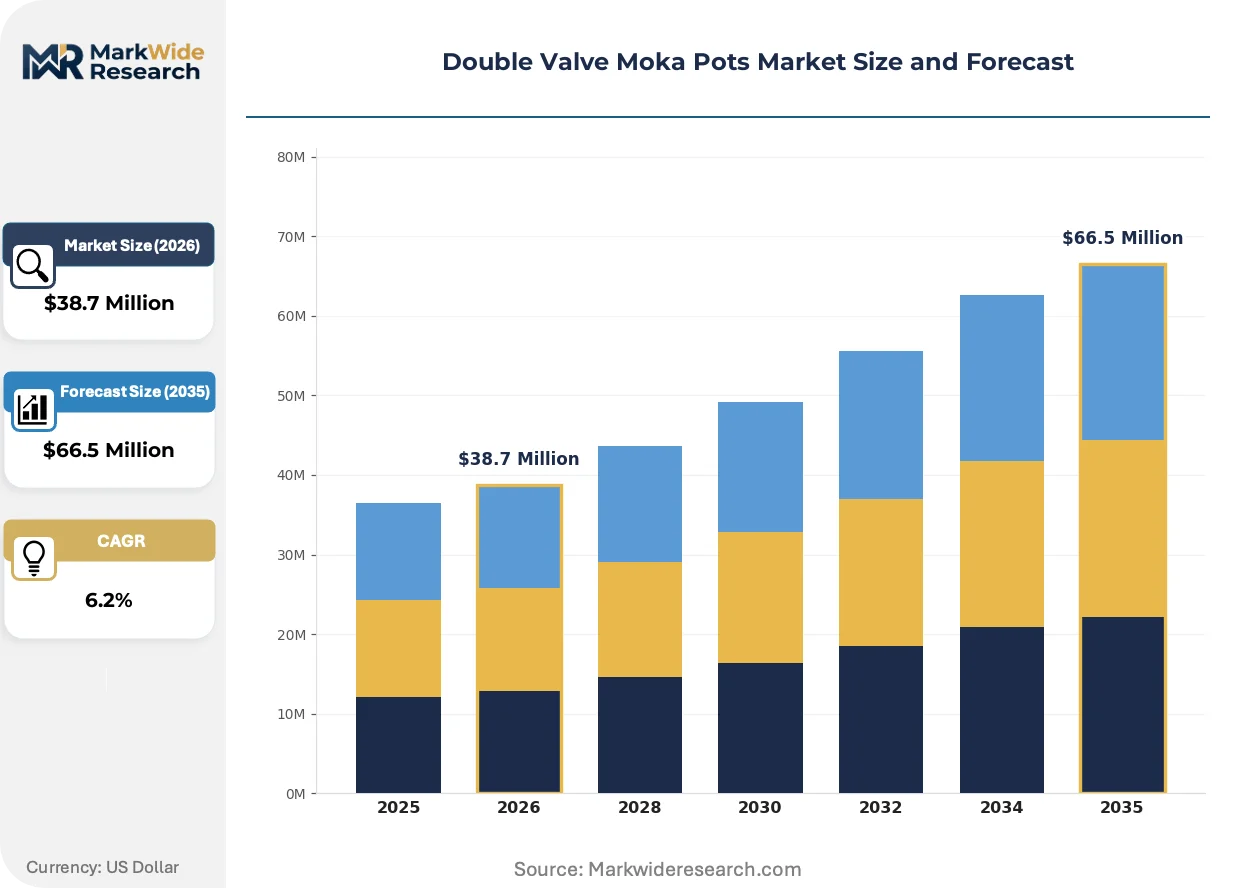
EU REACH compliance on aluminum alloy composition is forcing foundry recertification across European supply chains, while specialty café procurement standards in Milan and Tokyo accelerate equipment upgrade cycles. This regulatory-demand intersection compresses supplier qualification timelines and reshapes competitive access.
Growth Catalysts
- Specialty café equipment upgrades:Third-wave roasting districts in Milan and Tokyo mandate precision extraction tools. Double valve moka pots satisfy crema quality requirements without pump infrastructure.
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon refrigerants redirects commercial kitchen capital toward non-refrigerated brewing equipment. Stovetop and electric moka variants capture displaced investment.
- Induction-compatible stainless steel:Electromagnetic heating adoption in German and Japanese households expands addressable market beyond gas-connected kitchens. Material substitution opens new installation contexts.
Market Restraints
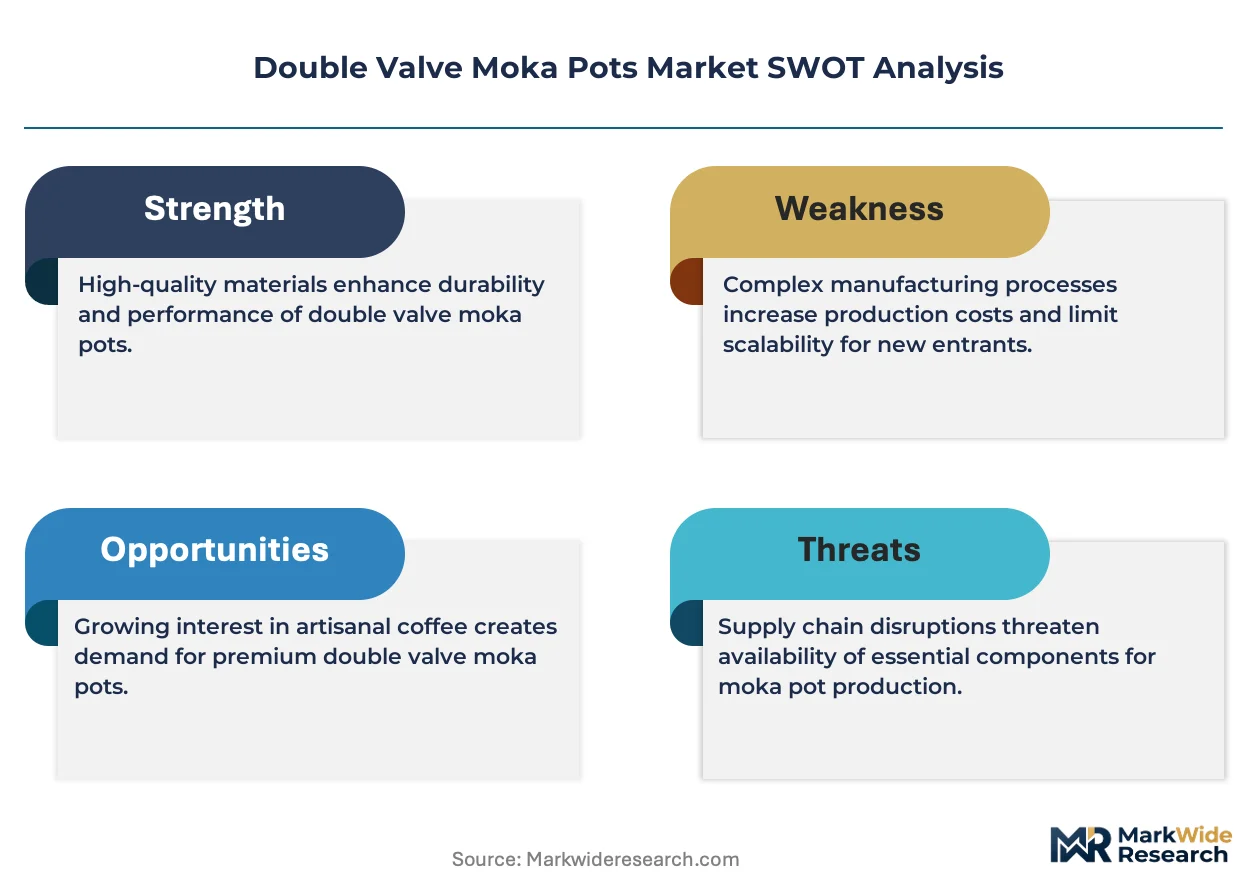
- Aluminum price volatility:LME aluminum fluctuations squeeze margin on entry-tier products. Foundries in Northern Italy face input cost pressure that resists full pass-through to retail.
- Single-supplier valve component concentration:Precision spring and seal manufacturing concentrates in Southern German component houses. Geographic dependency creates bottleneck risk for non-European assemblers.
- Pressure safety certification timelines:GB standards administered by SAMR in China impose extended testing protocols. Market access delays compress effective selling season for new entrants.
Strategic Opportunities
- Office hospitality electrification:Flame-restricted corporate environments in Japan and South Korea drive electric variant demand. This segment commands margin premiums absent from household stovetop categories.
- PFAS-free coating substitution:ECHA review of fluorinated compounds creates first-mover advantage for ceramic-lined alternatives. Suppliers with validated substitute chemistries secure preferential placement.
- Architectural design collaborations:Museum retail and design hotel channels in Copenhagen and Barcelona reward aesthetic differentiation. Limited-edition positioning escapes commodity pricing pressure.
Industry Challenges
- Pressure vessel welding certification:Qualified technicians for double-seam stainless construction remain scarce in emerging manufacturing regions. Training timelines extend production ramp schedules.
- Valve calibration precision:Tolerance consistency between sequential release mechanisms demands specialized metrology. Quality drift at scale triggers warranty exposure and brand erosion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double Valve Moka Pots Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $66.5 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stovetop, Electric, Induction, Travel Material: Aluminum, Stainless Steel, Glass, Copper End User: Households, Cafés, Restaurants, Offices Size: Single Serve, 3-Cup, 6-Cup, 9-Cup |
| Companies Covered | Bialetti, Alessi, De'Longhi, Grosche, Alpha Coffee, Banlee Coffee, Imusa, Pedrini, Ilsa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double Valve Moka Pots Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to redefine product architecture. Manufacturers face simultaneous pressure to eliminate contested compounds while maintaining pressure integrity and thermal efficiency.
Stainless steel construction with integrated thermal cores is displacing traditional aluminum bodies in premium tier positioning. Specialty cafés in Hamburg and Osaka specify full-steel configurations for durability visibility. This material shift compresses the viable supplier base to foundries with precision welding capability, raising entry barriers for aluminum-specialist competitors.
REACH restrictions on chromium(VI) surface treatments are forcing conversion to trivalent passivation processes. Italian and Spanish foundries absorb retooling costs that strain smaller competitors. The compliance burden falls heaviest on entry-price manufacturers lacking captive surface treatment facilities, accelerating consolidation toward vertically integrated producers.
Direct-to-roaster procurement is consolidating equipment specification authority away from traditional hospitality distributors. Roasting collectives in Melbourne and Portland now issue unified equipment standards that bypass wholesale channels. This disintermediation compresses distributor margins while rewarding manufacturers with technical sales capabilities and regional service networks.
Double Valve Moka Pots Market Segmentation
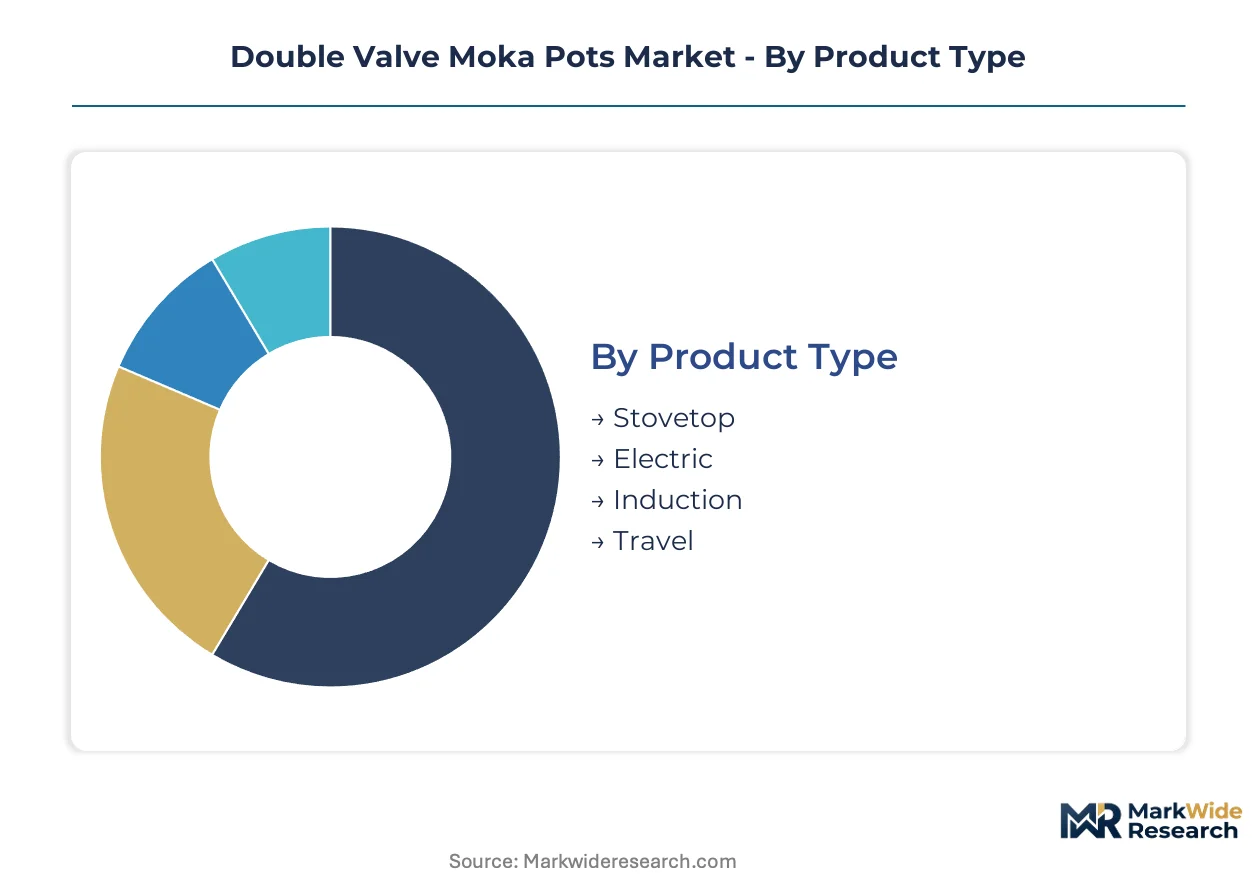
Segmentation in double valve moka pots reflects divergent pressure requirements, thermal conductivity needs, and installation constraints across consumer and commercial contexts. Each dimension carries distinct regulatory exposure and margin architecture.
Product Type:
Stovetop variants dominate domestic Italian and Spanish consumption, while electric and induction types drive export-led growth into flame-restricted Asian markets.
- Stovetop:Traditional gas-heated aluminum or steel construction operating at 1.5-2.0 bar through sequential valve release. Demand concentrates in Southern European households and Milan's specialty cafés where flame infrastructure remains standard and barista ritual commands premium positioning.
- Electric:Self-contained heating element with thermostatic control enabling consistent extraction without open flame. Japanese offices and South Korean corporate hospitality settings mandate this configuration, commanding 40-60% margin premiums over stovetop equivalents due to safety compliance and convenience positioning.
- Induction:Ferromagnetic base compatibility for electromagnetic heating systems. German kitchen renovation cycles and Tokyo apartment upgrades accelerate replacement demand.
- Travel:Compact, lightweight construction for portable brewing. Outdoor retail channels in Switzerland and Austria sustain niche volume.
Stovetop holds the largest share; momentum sits with electric variants in corporate hospitality.
Material:
Cost tiers split sharply between commodity aluminum and certified stainless steel, with copper and glass occupying artisan positioning.
- Aluminum:Cast alloy construction with trivalent chromium passivation under REACH compliance. Entry-price positioning sustains volume in Spanish and Portuguese household markets, though ECHA restrictions on surface treatments compress foundry margins and accelerate supplier consolidation toward captive finishing capabilities.
- Stainless Steel:AISI 304 or 316 construction with precision-welded double seams for pressure integrity. Hamburg and Osaka specialty cafés specify full-steel configurations for durability visibility, with induction compatibility opening German and Japanese household penetration beyond gas-connected kitchens.
- Glass:Borosilicate chamber construction for brewing visibility. Museum retail and design hotel channels in Copenhagen reward aesthetic differentiation.
- Copper:Thermal conductivity optimization through traditional metalworking. Artisan positioning in Italian heritage markets.
Aluminum retains volume leadership; stainless steel is climbing the fastest on certification and durability premiums.
End User:
Customer type determines pressure calibration precision, batch size requirements, and service network expectations.
- Households:Single-serve to 6-cup capacity for daily consumption. Italian and German retail channels dominate procurement.
- Cafés:Third-wave roasting districts in Milan, Tokyo, and Melbourne mandate crema quality without pump infrastructure, consolidating specification authority through direct-to-roaster procurement that bypasses traditional hospitality distributors.
- Restaurants:Front-of-house espresso service in flame-permitted kitchens. Southern European fine dining sustains demand.
- Offices:Flame-restricted environments in Japan and South Korea drive electric variant specification with integrated safety certification.
Households hold the largest share; cafés are gaining share fastest on equipment upgrade cycles.
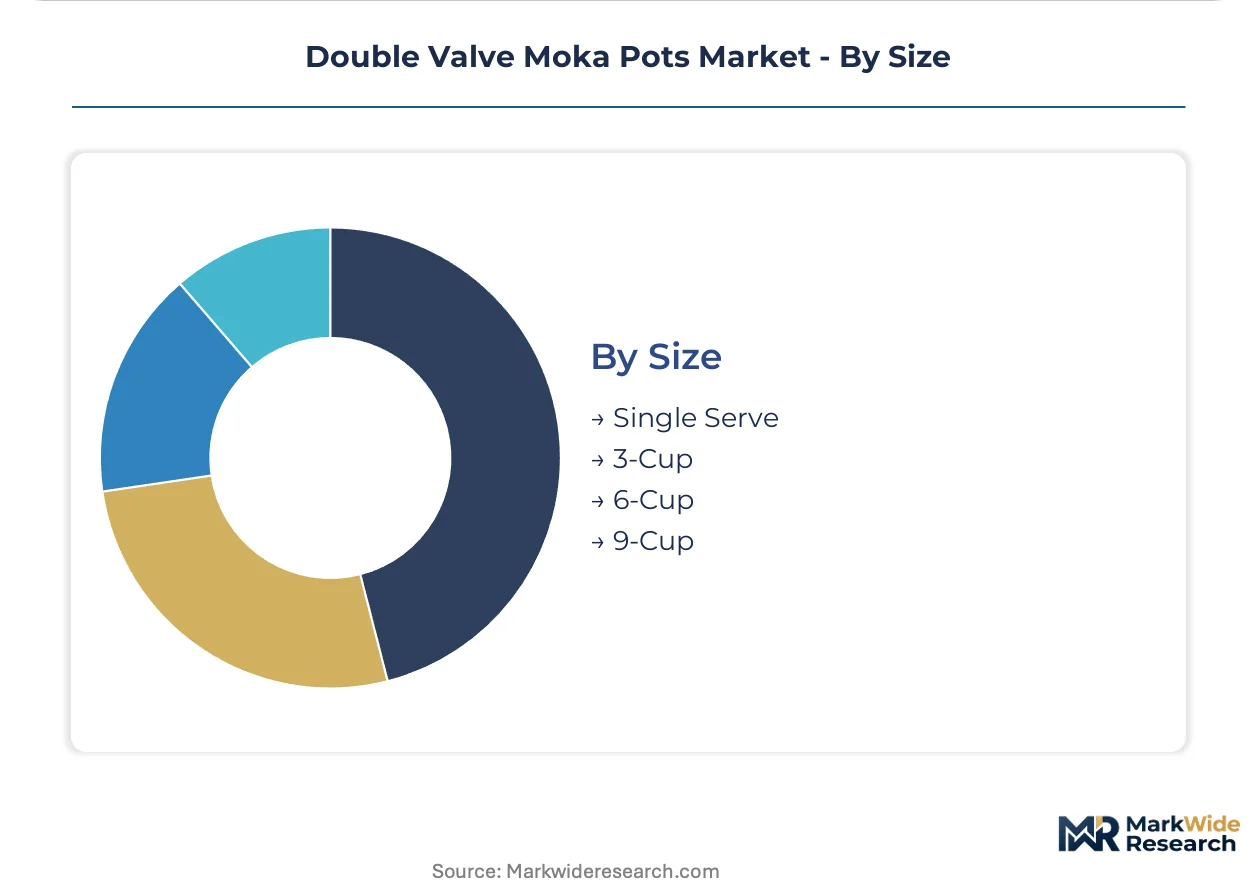
Size:
Volume scale determines valve spring specification, thermal mass, and pressure stabilization dynamics.
- Single Serve:Individual portion brewing with rapid heat-up. Urban Japanese apartments and German single-person households favor compact footprint.
- 3-Cup:Small household or couple configuration. Portuguese and Spanish retail channels sustain baseline volume.
- 6-Cup:Standard family or small café service capacity. Balanced thermal efficiency and pressure stability for most commercial installations.
- 9-Cup:Large batch brewing for restaurant back-of-house or catering. Limited volume on extended heat-up times.
6-Cup holds the largest share; single serve shows steepest expansion trajectory on urbanization and smaller household formation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian households demonstrate the lowest price elasticity for heritage-branded stovetop units, while Spanish and Portuguese consumers gravitate toward entry-tier aluminum alternatives. German and Japanese buyers absorb substantial premiums for induction-compatible stainless steel configurations.
Italy
Milan's specialty coffee corridor drives equipment specification through direct-to-roaster procurement channels. EU REACH compliance on chromium(VI) surface treatments forces trivalent passivation conversion across Lombardy and Piedmont foundries. Crusinallo in Piedmont sustains heritage manufacturing concentration for premium-tier assembly.
Germany
Induction-compatible stainless steel demand accelerates with kitchen renovation cycles in Hamburg and Berlin. KBA-adjacent pressure vessel standards influence safety certification protocols for imported valve assemblies. Bavaria hosts precision component houses supplying Southern German spring and seal manufacturing.
Japan
Tokyo's third-wave roasting district mandates crema quality without pump infrastructure, consolidating specification authority among roasting collectives. METI energy efficiency guidelines shape electric variant thermostatic control requirements. Osaka specialty cafés specify full-steel configurations for durability visibility in front-of-house installations.
United States
North American specialty retail channels prioritize certified aluminum sourcing and ethical supply chain positioning. FDA food-contact regulations impose parallel testing requirements on valve seal materials and pressure safety thresholds. Portland roasting collectives issue unified equipment standards that bypass traditional hospitality distributors.
Spain
Household consumption concentrates in entry-price aluminum segments across Madrid and Barcelona retail channels. ECHA restrictions on surface treatment chemicals compress foundry margins and accelerate supplier consolidation. Catalan foundries absorb retooling costs that strain smaller competitors lacking captive finishing capabilities.
Double Valve Moka Pots Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the double valve moka pots market. Heritage Italian manufacturers anchor premium positioning through design authority and regional manufacturing concentration, while Asian fabricators compete on scale-driven aluminum casting. Three archetypes dominate: vertically integrated heritage brands with captive foundry capacity, specialist ethical-sourcing positioned for North American specialty retail, and scale-oriented aluminum producers serving price-sensitive Southern European household demand. Competitive moves center on PFAS-free coating substitution for ECHA compliance and direct-to-roaster technical sales capability bypassing wholesale channels.
Among Italian heritage manufacturers, Bialetti and Alessi exemplify premium-tier archetypes through design authority and architectural collaboration positioning. De'Longhi represents diversified appliance-scale entry with electric variant capabilities for flame-restricted corporate environments. Grosche occupies the ethical-sourcing specialist position within North American specialty store channels. These three anchors illustrate the tripartite competitive structure: heritage design-premium, diversified appliance-scale, and ethical-specialist positioning.
| Leading Market Players |
|---|
| Bialetti |
| Alessi |
| De'Longhi |
| Grosche |
| Alpha Coffee |
| Banlee Coffee |
| Imusa |
| Pedrini |
| Ilsa |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Lombardy foundries and German valve component houses lock in aluminum alloy supply and insulate premium-tier manufacturers from LME volatility. These contracts simultaneously secure REACH-compliant chromium(VI)-free passivation capacity and stabilize unit economics for stainless steel assembly lines serving Milan and Tokyo specialty cafés.
Pricing Analysis
EU REACH dictates the pricing tier structure across the double valve moka pots market by mandating trivalent chromium surface treatments that stratify production costs. Three-tier pricing structure across premium, standard, and economy levels separates AISI 316 stainless steel configurations with induction compatibility from entry-grade aluminum units. Cost compression in the aluminum tier is intensifying because ECHA retooling requirements eliminate smaller foundries lacking captive finishing facilities. Spanish and Portuguese household buyers exhibit the highest price sensitivity, while German and Japanese specialty café procurement absorbs substantial premiums for certified durability visibility.
Supply Chain Analysis
Strait of Hormuz transit risk underwrites raw material security calculations for aluminum alloy feedstock moving into European foundries. Manufacturing gravity centers on Italy, Germany, and China, with precision valve springs and seals drawing from Southern German component houses. Supply chain risk concentrates in single-source dependency for calibrated spring manufacturing. Distribution runs through direct-to-roaster procurement channels that disintermediate traditional hospitality wholesalers in Melbourne and Portland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment specification authority is migrating toward roasting collectives that function as platform gatekeepers, with interoperability demands across brewing protocols reshaping manufacturer-roaster relationships.
For Market Incumbents: Compound design authority through architectural collaborations that command museum retail placement in Copenhagen and Barcelona. Deepen backward integration into captive trivalent chromium passivation facilities before ECHA enforcement tightens. Threat substitution from PFAS-free ceramic coating specialists demands preemptive chemistry validation investments. For New Entrants and Emerging Players: Anchor in the electric variant segment serving flame-restricted Japanese and South Korean corporate hospitality environments. This white-space target commands margin premiums absent from saturated stovetop household categories. Penetrate through technical sales capabilities that bypass wholesale distributor layers and engage roasting collective procurement committees directly. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated heritage manufacturers with captive Lombardy foundry capacity and REACH-certified surface treatment infrastructure. Long-term viability across the analysis window favors suppliers with direct-to-roaster technical service networks over distributor-dependent competitors. Watch for PFAS restriction finalization under ECHA review as the signal indicating coating substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Substitution | ECHA-compliant ceramic linings secure preferential placement ahead of fluorinated compound restrictions. |
| Direct-to-Roaster Technical Sales | Bypassing wholesale channels captures specification authority from roasting collectives in Melbourne and Portland. |
| Backward Integration into Surface Treatment | Captive trivalent chromium passivation insulates margins from foundry consolidation pressures under REACH. |
| Electric Variant Certification Investment | METI-compliant thermostatic controls open flame-restricted Japanese corporate hospitality procurement. |
| Architectural Design Collaboration | Museum retail partnerships in Copenhagen and Barcelona escape commodity pricing through aesthetic differentiation. |
Research Methodology
Operator-level perspectives from specialty café equipment buyers, foundry operations managers, valve component procurement leads, and roasting collective technical directors anchored the qualitative base. Secondary validation drew from EU REACH substance restriction databases, SAMR GB standard filings, ECHA PFAS review documentation, and Italian foundry association capacity surveys. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, material tier, end-user segment, and regional regulatory cluster dimensions.
Sensitivity analysis tested forecast robustness across aluminum price volatility bands, REACH enforcement timing scenarios, and roasting collective procurement consolidation rates. Segmentation modeling spanned stovetop-electric-induction product architecture, stainless steel-aluminum-copper material grades, household-café-office end-user contexts, and single-serve through 9-cup capacity tiers. CAGRs derived from equipment replacement cycle analysis, specialty café expansion trajectories, and induction kitchen penetration curves.
Decision-makers should treat outputs as directional under sustained EU F-Gas Regulation phase-down and ECHA surface treatment compliance assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as PFAS restriction finalization timelines and roasting collective procurement standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Yerba Mate Market
Beverages
Morocco Bottled Water Market
Beverages
Global Electrolyte Drinks Market
Beverages
South America Mate Market
Beverages
Europe Animal-Based Food and Beverage Market
Beverages
Japan Kombucha Market
Beverages
Europe Bottled Water Market
Beverages
Sparkling Bottled Water Market
Beverages
Global Soda Maker Market
Beverages
US Bubble Tea Market
Beverages
Soft Serves Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Coconut Water Market
Beverages
Commercial Sparkling Water Dispenser Market
Beverages
Saudi Arabia Food & Beverage Market
Beverages
Europe Probiotic Drinks Market