
 Beverage Stabilizer Market | 2026-2036
Beverage Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Stabilizer Market Analysis
The gap between premium clean-label stabilizers and commodity synthetic grades is broadening as formulation costs diverge sharply. Cargill, Incorporated leverages its agricultural supply chain to anchor natural stabilizer sourcing across North America. Tate & Lyle differentiates through specialty texturant R&D intensity in beverage applications. Kerry Group competes on integrated flavor-stabilizer systems for dairy beverage processors.
Beverage stabilizers comprise hydrocolloids, gums, pectins, and modified starches that maintain suspension, prevent phase separation, and preserve viscosity within specified shear-thinning parameters across shelf life. Their primary commercial purpose is to extend product stability in ready-to-drink formulations subjected to thermal processing and extended distribution cycles. Natural stabilizers command expanding margin pools as clean-label mandates intensify, while synthetic stabilizers retain volume dominance in cost-sensitive soft drink applications. Emulsifiers represent the fastest-growing product category, propelled by plant-based dairy beverage proliferation requiring lipid-protein stabilization.
EFSA evaluates novel food additive safety while REACH governs chemical substance registration for synthetic stabilizer imports into Europe. FDA GRAS determinations and FSSAI food additive approvals shape cross-border formulation compliance for multinational beverage manufacturers. Stakeholders must monitor evolving clean-label definitions across regulators to anticipate reformulation timelines and raw material qualification requirements.
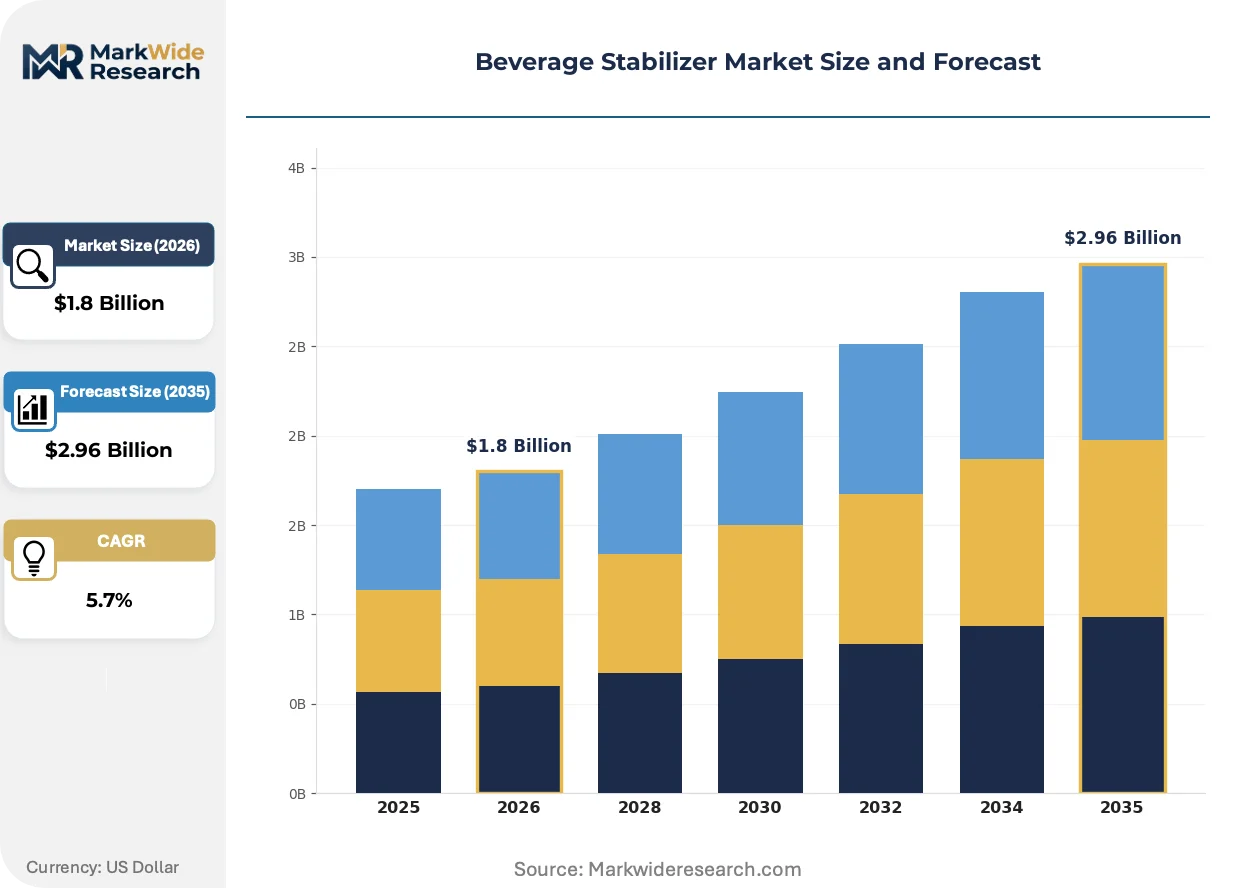
Market Dynamics
Clean-label procurement mandates from EFSA are compressing synthetic stabilizer margins while expanding natural hydrocolloid premiums, forcing beverage manufacturers into accelerated reformulation cycles across European dairy and plant-based beverage lines.
Growth Catalysts
- EFSA Clean-Label Guidelines:Tightening formulation standards in Europe are compelling dairy processors to adopt premium natural stabilizers, expanding addressable margin pools for hydrocolloid suppliers.
- Plant-Based Dairy Proliferation:Lipid-protein stabilization demands in oat, almond, and pea-based beverages are accelerating emulsifier category expansion faster than traditional dairy applications.
- German Processing Cluster:Concentrated dairy beverage manufacturing in Bavaria and North Rhine-Westphalia is anchoring premium stabilizer procurement volumes and technical service intensity.
Market Restraints
- Locust Bean Gum Volatility:Weather-dependent harvests in Mediterranean growing regions create raw material price swings that compress natural stabilizer margins unpredictably.
- REACH Registration Burden:Synthetic stabilizer imports into Europe face escalating compliance costs and timeline uncertainty for novel chemical substance approvals.
- Carrageenan Substitution Pressure:Clean-label marketing has driven beverage brands toward pectin and gellan gum alternatives, eroding traditional seaweed-derived stabilizer volumes.
Strategic Opportunities
- Indian FSSAI Alignment:Multinational manufacturers can leverage harmonized food additive approvals to streamline cross-border formulation for India's expanding ready-to-drink beverage market.
- Precision Fermentation:Cell-cultured hydrocolloids and enzymatically modified starches are converging to create novel texturants with tailored shear-thinning profiles.
- D2C Functional Beverages:Direct-to-consumer channels for protein-fortified and gut-health drinks are bypassing traditional retail gatekeepers and demanding customized stabilizer systems.
Industry Challenges
- Clean-Label Definition Fluidity:Evolving consumer and regulatory interpretations of "natural" create qualification uncertainty for stabilizer portfolios across EFSA, FDA, and FSSAI jurisdictions.
- Reformulation Capex Burden:Thermal processing line modifications and extended shelf-life testing protocols require capital deployment that mid-tier beverage brands struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Stabilizer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Stabilizers, Natural Stabilizers, Emulsifiers, Thickening Agents End User: Food & Beverage Manufacturers, Retailers, Private Label Brands, Beverage Startups Application: Juice, Soft Drinks, Dairy Beverages, Alcoholic Beverages Distribution Channel: Online Sales, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Cargill, Incorporated, Tate & Lyle, Ingredion Incorporated, CP Kelco, Palsgaard, Kerry Group, BASF SE, Ashland, Glanbia plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Stabilizer Market Emerging Trajectories
Formulation science is pivoting from single-ingredient stabilization toward integrated texture systems that combine multiple hydrocolloid functionalities, driven by complex beverage matrices with protein, fiber, and lipid co-delivery requirements.
Enzymatic starch modification is decentralizing texturant production by enabling beverage manufacturers to generate tailored viscosity profiles in-house from native starch feedstocks. Mid-sized dairy processors in the Netherlands and Denmark are piloting continuous enzymatic systems that reduce reliance on pre-hydrolyzed modified starch suppliers. This technology is decentralizing supply chain control and compressing lead times for new product development cycles.
REACH authorization requirements for synthetic stabilizers are tightening import pathways into European manufacturing facilities. ECHA's expanding candidate list of substances of very high concern is forcing reformulation of legacy beverage products using acetylated distarch adipate and other modified starches. German and French beverage conglomerates are accelerating natural stabilizer qualification timelines to preempt authorization denials.
Specification-driven procurement is consolidating buyer power among multinational beverage manufacturers who now demand integrated stabilizer-emulsifier-flavor systems rather than commodity ingredients. Tier-one dairy processors in Germany are shifting from spot purchasing to multi-year formulation partnerships with technical suppliers. This behavioral shift is most visible in Bavaria's plant-based beverage cluster, where procurement teams prioritize single-source accountability over ingredient cost minimization.
Beverage Stabilizer Market Segmentation
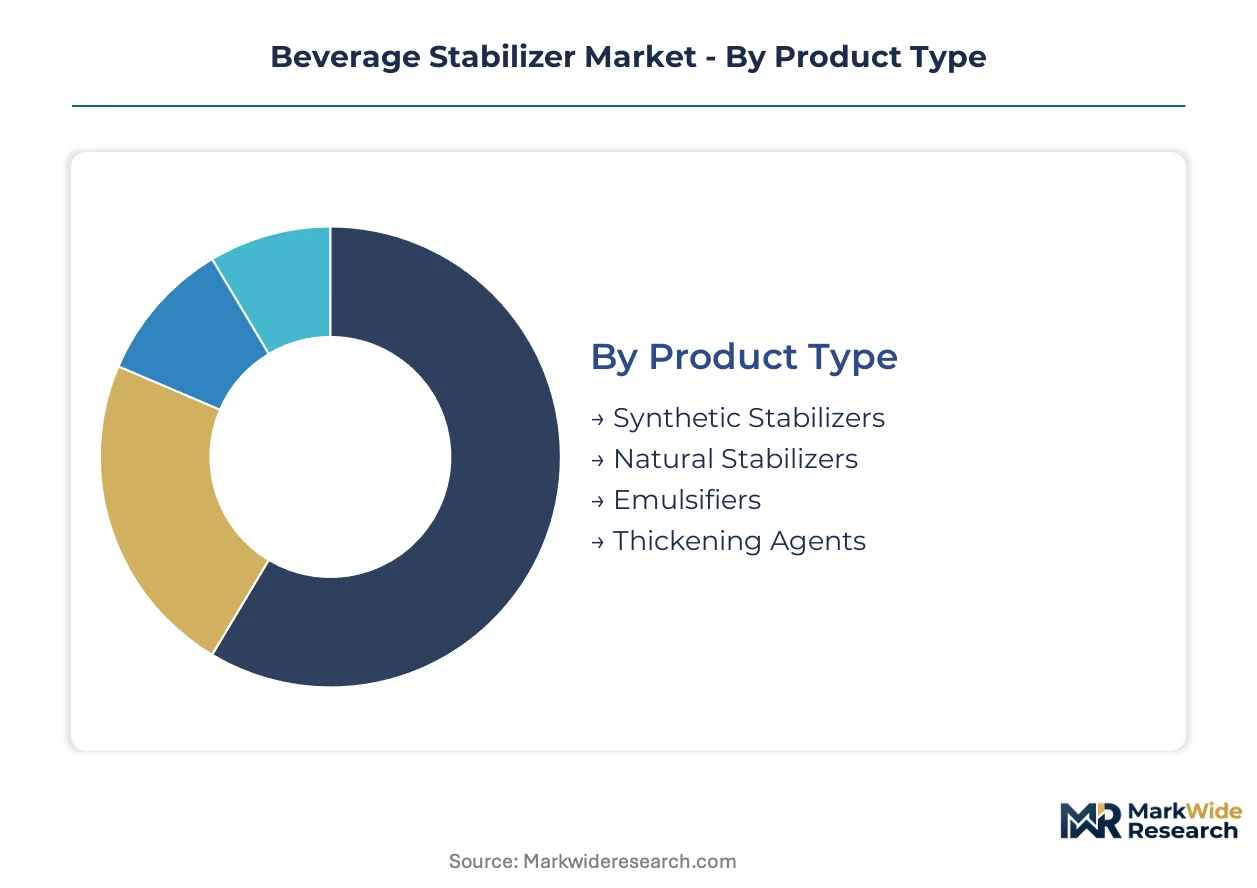
Beverage stabilizer procurement patterns diverge sharply across product grades and customer sophistication tiers. Reformulation cycles triggered by EFSA clean-label mandates are accelerating segment migration from synthetic to natural alternatives.
Product Type:
Upgrade cycles from commodity synthetics to premium natural grades are compressing legacy margin pools while expanding hydrocolloid premiums.
- Natural Stabilizers:Hydrocolloids, gums, and pectins derived from botanical and seaweed sources deliver clean-label compliance for dairy and plant-based formulations. German dairy processors in Bavaria anchor procurement volumes as EFSA guidelines tighten, with locust bean gum and gellan gum commanding technical service intensity.
- Emulsifiers:Lipid-protein stabilization systems combine surfactant functionality with shear-thinning control for oat, almond, and pea-based beverages. Plant-based dairy proliferation in North Rhine-Westphalia is driving specification-driven partnerships with integrated suppliers.
- Synthetic Stabilizers:Chemically modified starches and cellulose derivatives retain cost-sensitive soft drink applications despite REACH registration burdens.
- Thickening Agents:Modified starches and xanthan gum provide viscosity control in thermally processed ready-to-drink lines.
Synthetic stabilizers sit at the top of the volume ranking, with natural stabilizers climbing the fastest.
End User:
Customer sophistication tiers separate specification-driven multinationals from price-sensitive spot buyers.
- Food & Beverage Manufacturers:Tier-one processors demand integrated stabilizer-emulsifier-flavor systems with multi-year technical partnerships.
- Private Label Brands:Retail-controlled formulations prioritize cost-optimized stabilizer blends with acceptable shelf-life performance.
- Beverage Startups:Direct-to-consumer protein-fortified and gut-health drinks require customized stabilizer systems bypassing traditional retail gatekeepers.
- Retailers:Private label procurement teams balance clean-label marketing claims against ingredient cost minimization.
Food and beverage manufacturers dominate procurement value, with beverage startups expanding most quickly.
Application:
Application complexity escalates with protein, fiber, and lipid co-delivery requirements in functional formulations.
- Dairy Beverages:Thermal processing and extended distribution cycles demand suspension stability and phase separation prevention across UHT and ESL product lines.
- Soft Drinks:Cost-optimized synthetic stabilizers maintain carbonation stability and cloud suspension in high-volume production.
- Juice:Pulp suspension and cloud stability requirements vary with pasteurization intensity and pulp content specifications.
- Alcoholic Beverages:Ethanol tolerance and chill haze prevention drive specialized stabilizer selection in beer and ready-to-drink cocktails.
Soft drinks lead absolute volume, with dairy beverages gaining share fastest.
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements.
- Direct Sales:Multinational manufacturers negotiate multi-year formulation partnerships with technical suppliers for integrated texture systems.
- Distributors:Mid-tier processors rely on regional distributors for standard hydrocolloid grades with shorter lead times.
- Online Sales:Small-batch beverage startups procure specialty stabilizers through digital channels with technical documentation access.
- Wholesalers:Commodity synthetic stabilizers flow through traditional wholesale networks serving cost-sensitive applications.
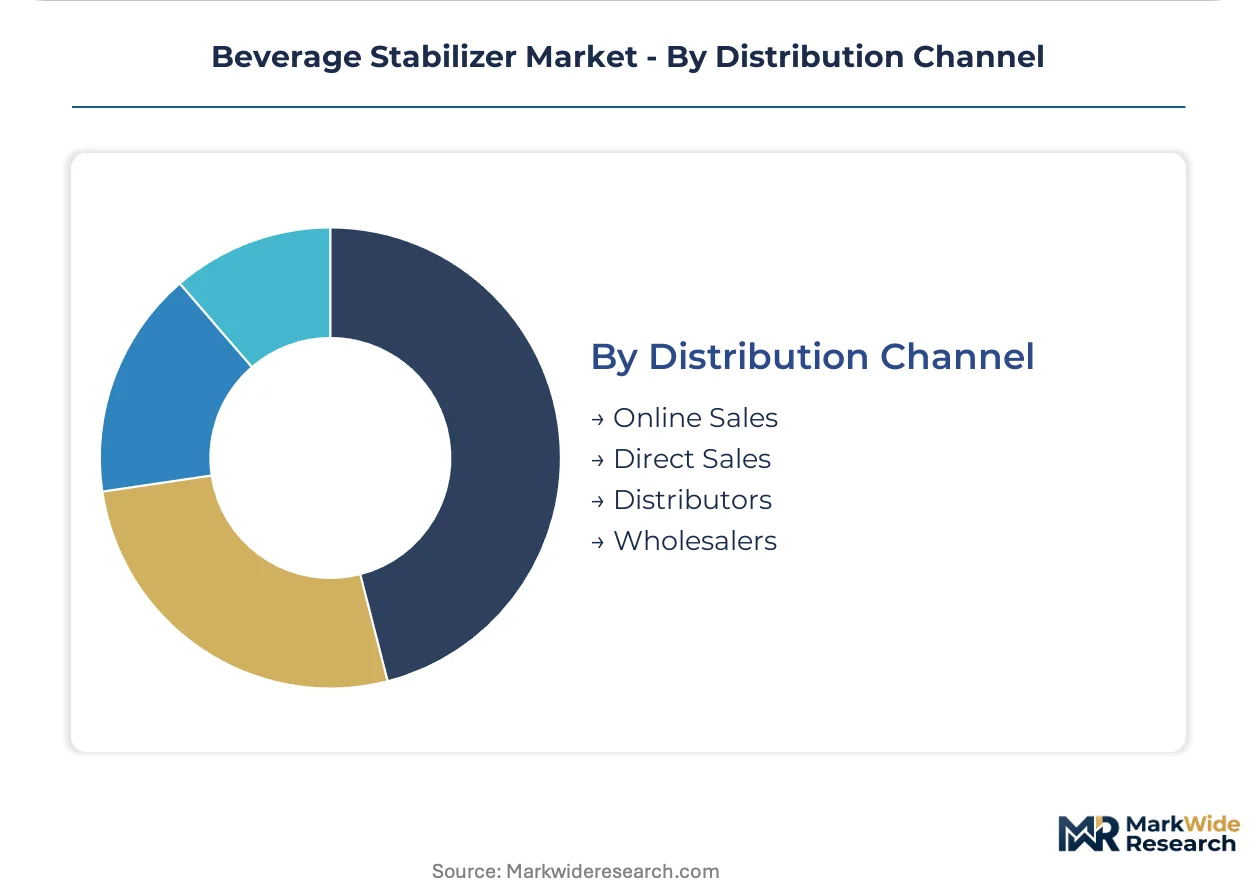
Direct sales capture the highest value per ton, with online sales expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized food chemists and formulation scientists concentrate in Germany's dairy processing belt, anchoring Europe's premium stabilizer demand. Technical talent pools in the Netherlands and Denmark support enzymatic modification pilots. India's regulatory alignment specialists enable cross-border formulation standardization.
Germany
Bavaria's plant-based beverage cluster and North Rhine-Westphalia's dairy processors drive specification-driven procurement for clean-label hydrocolloids. EFSA formulation guidelines tighten qualification timelines for natural stabilizers. Technical service partnerships consolidate around multi-year supply agreements in Munich-Düsseldorf corridor.
United States
Midwest corn processors and California beverage startups diverge on stabilizer grade preferences. FDA GRAS determinations shape cross-border compliance for multinational manufacturers. Chicago-area distribution hubs anchor commodity synthetic stabilizer flows while West Coast innovation centers pilot precision fermentation texturants.
India
Expanding ready-to-drink dairy and juice segments drive stabilizer procurement from Maharashtra and Karnataka processing clusters. FSSAI food additive approvals streamline harmonization with EFSA and FDA standards. Mumbai-Pune corridor beverage manufacturers accelerate natural stabilizer adoption for export qualification.
Netherlands
Dairy processors in Friesland and Gelderland pilot continuous enzymatic starch modification systems. REACH authorization requirements compress synthetic stabilizer import timelines. Wageningen-region technical centers decentralize texturant production control for mid-sized beverage manufacturers.
China
Yangtze River Delta beverage conglomerates balance cost-optimized synthetic stabilizers with clean-label export preparation. SAMR food additive registrations govern domestic formulation compliance. Shanghai-area technical partnerships concentrate on integrated texture-emulsifier systems for plant-based dairy expansion.
Beverage Stabilizer Market Vendor Landscape
Capital-heavy agricultural processors compete with asset-light specialty ingredient designers across the stabilizer value chain. Market structure concentrates around integrated multinationals with captive raw material sourcing and independent hydrocolloid specialists with technical service depth. Three archetypes dominate: agribusiness conglomerates with backward integration into botanical supply, specialty chemical houses with enzymatic modification capabilities, and integrated nutrition platforms combining stabilizers with flavor systems. Competitive moves center on multi-year formulation partnerships replacing spot purchasing, and precision fermentation investments targeting novel texturant molecular architectures.
Within the agribusiness-integrated tier, Cargill, Incorporated anchors natural stabilizer sourcing through agricultural supply chain control. Tate & Lyle occupies a position exemplifying specialty texturant R&D intensity. Kerry Group represents the integrated nutrition archetype, sitting within flavor-stabilizer system partnerships for dairy beverage processors.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Tate & Lyle |
| Ingredion Incorporated |
| CP Kelco |
| Palsgaard |
| Kerry Group |
| BASF SE |
| Ashland |
| Glanbia plc |
| Others |
Supply Flow & Price Mechanics
Captive agricultural sourcing by Cargill and Ingredion anchors both supply security and pricing power across North American hydrocolloid markets, compressing spot-market exposure for downstream beverage manufacturers while elevating contract-based premiums for technical service bundling.
Pricing Analysis
Service bundling separates integrated formulation partnerships from commodity spot transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence under EFSA clean-label guidelines versus REACH-registered synthetic alternatives. Cost compression in commodity modified starches is intensifying because Indian and Chinese processors are expanding export volumes. Private label brands exhibit highest price sensitivity, while German dairy conglomerates accept premium positioning for multi-year technical accountability.
Supply Chain Analysis
Reverse-logistics flows for enzymatic starch modification equipment are emerging as Dutch and Danish processors pilot in-house texturant production, reducing dependency on pre-hydrolyzed supplier networks. Raw material sourcing draws from Moroccan locust bean orchards, Indonesian seaweed cultivation zones, and Midwest corn processing belts. Single-source vulnerability concentrates in Mediterranean gum arabic and locust bean harvests exposed to climate volatility. Distribution runs through direct technical partnerships for tier-one manufacturers and regional distributors for mid-tier spot buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation cost arbitrage between REACH-registered European synthetic stabilizers and FSSAI-aligned Indian natural hydrocolloid production creates geographic repositioning incentives for multinational beverage manufacturers.
For Market Incumbents: Deploy precision fermentation R&D to preempt carrageenan substitution pressure with novel cell-cultured texturants. Deepen backward integration into Moroccan locust bean and Indonesian seaweed supply bases to buffer raw material volatility. Lock multi-year formulation partnerships with Bavarian plant-based beverage clusters before REACH authorization denials accelerate.
For New Entrants and Emerging Players: FSSAI alignment with EFSA standards in India opens a window for cross-border formulation standardization targeting Maharashtra's expanding ready-to-drink dairy segment. Precision fermentation capabilities and D2C functional beverage channels represent the most penetrable white-space targets. Lead with enzymatic modification pilot offerings to Dutch mid-tier processors seeking supply chain decentralization.
For Investors and Strategic Acquirers: Roll-up economics work for specialty hydrocolloid specialists with technical service depth because specification-driven procurement is consolidating buyer power around integrated system suppliers. Five-to-ten year viability hinges on clean-label regulatory harmonization trajectories. Watch EFSA novel food additive authorization timelines as the inflection signal for synthetic-to-natural substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Investment | Cell-cultured hydrocolloids bypass locust bean gum weather volatility for beverage manufacturers. |
| Backward Integration into Seaweed Supply | Captive carrageenan and gellan gum sourcing insulates margins from harvest price swings. |
| Multi-Year Formulation Partnership | Technical service bundling locks German dairy processors into integrated stabilizer-emulsifier systems. |
| Enzymatic Modification Pilot Deployment | In-house starch texturant production compresses lead times for Dutch beverage innovators. |
| FSSAI-EFSA Harmonization Compliance | Cross-border formulation standardization streamlines Indian export qualification for multinational brands. |
Methodological Framework
Multiple input streams — procurement director interviews, regulatory filing analysis, and agricultural trade data — were reconciled to map stabilizer supply chain configurations. Primary discussions with beverage formulation scientists, dairy processing plant managers, hydrocolloid distributor account executives, and EFSA regulatory affairs specialists were cross-validated against secondary sources including REACH registration databases, FSSAI food additive notifications, and customs trade flow records. Bottom-up volume modeling and top-down market sizing were triangulated for convergence.
Data-stream reconciliation across product type, end-user sophistication tier, application complexity, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and value-per-ton expansion patterns across the projection horizon. Industry-specific forecast inputs incorporated enzymatic modification adoption curves and clean-label reformulation cycle timelines for European dairy processors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA authorization delays or locust bean harvest failures. Practitioners should monitor EFSA novel food additive evaluation queues and Mediterranean climate indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Wine Fining Agent Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
North America Clean Label Ingredient Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
Global Lutein and Lutein Esters Market
Food Additives and Ingredients
Brazil Food Acidulants Market
Food Additives and Ingredients
United Kingdom Food Preservatives Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Carob Gum Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Middle East and Africa Clean Label Ingredients Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
South Africa Anti Caking Agents Market