
 South Africa Anti Caking Agents Market | 2026-2036
South Africa Anti Caking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Anti Caking Agents Market Analytics
The South Africa anti-caking agents market is restructuring around a sharp split between premium silica-based formulations for pharmaceutical and food-grade applications and commodity carbonate salts serving bulk agriculture and construction. Evonik Industries leverages its synthetic amorphous silica expertise to dominate high-purity segments where certification and traceability command pricing power. Norkem Group anchors the commodity tier through its extensive distribution network across Southern African fertilizer and animal feed channels.
Anti-caking agents are hygroscopic or desiccant compounds, typically silicon dioxide, calcium carbonate, or magnesium carbonate at particle sizes below 10 microns, that adsorb moisture or physically separate crystalline surfaces to prevent agglomeration during storage and pneumatic conveying. Their primary purpose is preserving free-flow characteristics in powdered and granulated solids across food, chemical, and agricultural supply chains. Calcium carbonate occupies the mature volume position in rubber manufacturing and construction applications where cost efficiency outweighs performance optimization. Sodium silicate represents the fastest-growing structural category, driven by its dual functionality as both anti-caking agent and binding additive in fertilizer granulation processes.
The South African Health Products Regulatory Authority (SAHPRA) governs excipient standards for pharmaceutical applications, while the Department of Agriculture, Land Reform and Rural Development enforces fertilizer and feed additive registrations under the Fertilizers, Farm Feeds, Agricultural Remedies and Stock Remedies Act. Bureau of Standards (SABS) compliance for food-grade additives creates a dual-track certification burden that filters out informal suppliers and elevates compliance costs for market entrants. Stakeholders must monitor pending amendments to the Foodstuffs Act's additive schedules, as these will determine whether imported microcrystalline cellulose formulations gain accelerated approval pathways or face extended local testing requirements.
Market Dynamics
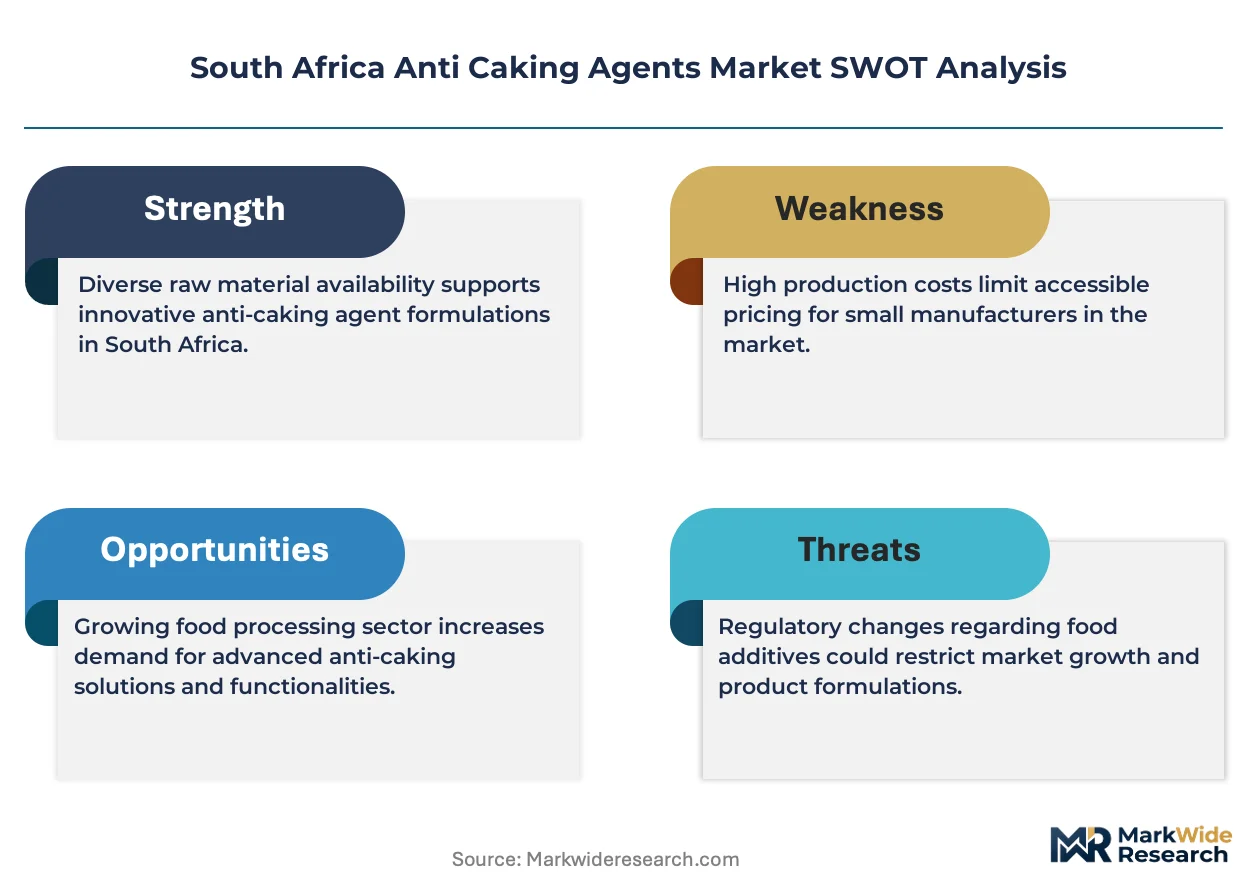
The South Africa anti-caking agents market is bifurcating sharply between premium silica-based formulations certified for pharmaceutical and food-grade applications and commodity carbonate salts serving bulk agriculture. This structural split is compressing mid-tier suppliers while elevating compliance costs as the dominant competitive variable.
Growth Catalysts
- Fertilizer granulation expansion:Bulk agricultural processors in Gauteng and KwaZulu-Natal are expanding pneumatic conveying capacity, driving demand for sodium silicate dual-function additives that bind while preventing caking.
- SAHPRA excipient standardization:The South African Health Products Regulatory Authority's tightening purity requirements for pharmaceutical-grade silicon dioxide is pulling imported high-specification formulations into domestic distribution channels.
- Foodstuffs Act additive schedules:Pending amendments to the Foodstuffs, Cosmetics and Disinfectants Act are accelerating approval pathways for microcrystalline cellulose, reducing time-to-market for compliant suppliers.
Market Restraints
- Import dependency for high-purity silica:Synthetic amorphous silica production is concentrated in European and East Asian manufacturing bases, exposing South African pharmaceutical formulators to currency volatility and shipping disruptions.
- SABS dual-track certification burden:Food-grade additive registration requires parallel Bureau of Standards compliance and Department of Health approval, creating structural friction that filters out smaller domestic compounders.
- Calcium carbonate substitution pressure:Construction and rubber manufacturing end-users are experimenting with ground limestone and talc as lower-cost flowability solutions in non-critical applications.
Strategic Opportunities
- Western Cape pharmaceutical clustering:Cape Town's emerging biotech corridor is attracting active pharmaceutical ingredient manufacturers seeking localized excipient supply, creating demand for domestic compounding capacity.
- Animal feed additive convergence:The Fertilizers, Farm Feeds, Agricultural Remedies and Stock Remedies Act is harmonizing registration pathways, enabling cross-selling of anti-caking agents into poultry and ruminant feed premix channels.
- Silica-carbonate hybrid formulations:Blended particle systems combining sub-5 micron silica surface coatings with calcium carbonate cores are opening mid-tier pricing positions between commodity and premium grades.
Industry Challenges
- Specialized particle engineering talent scarcity:Formulation chemists with expertise in controlled agglomeration and surface modification are concentrated in Johannesburg-Pretoria industrial corridors, constraining expansion into secondary manufacturing zones.
- Legacy pneumatic conveying infrastructure incompatibility:Fertilizer blenders in Mpumalanga and Free State operate equipment designed for untreated bulk materials, requiring retrofit investment to realize anti-caking agent performance benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Anti Caking Agents Market |
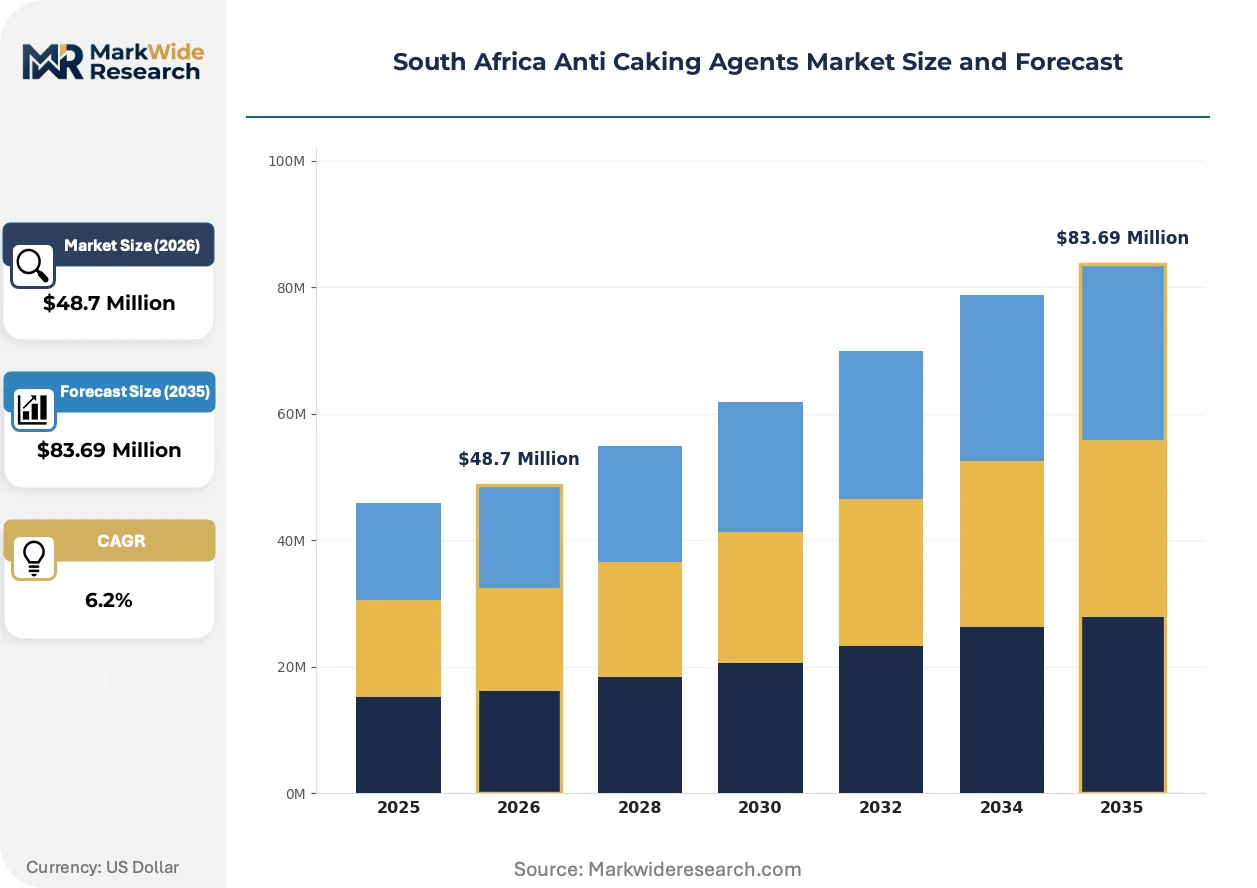
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $83.69 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Silicate, Calcium Carbonate, Magnesium Carbonate, Microcrystalline Cellulose Application: Food Processing, Rubber Manufacturing, Pharmaceuticals, Agriculture Form: Powder, Granules, Liquid, Tablet End User: Food Industry, Chemical Industry, Cosmetics, Construction |
| Companies Covered | Evonik Industries, PPG Industries, Solvay, Norkem Group, Merck KGaA, ArrMaz, PQ Corporation, Fuji Chemical Industries, Huber Engineered Materials, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Anti Caking Agents Market Evolving Landscape
Digital process control and regulatory data integrity requirements are converging to reshape how anti-caking agents are specified, monitored, and validated across South African manufacturing value chains. These shifts are elevating traceability from a compliance checkbox to a competitive differentiator.
Automated particle size distribution monitoring is automating quality assurance in high-volume fertilizer granulation lines. Bulk agricultural processors in the Vaal Triangle are deploying in-line laser diffraction sensors that adjust silicate dosing in real-time. This capability is automating the shift from batch-based additive blending to continuous processing, compressing labor costs and reducing over-dosing waste.
The Department of Health's pending Foodstuffs Act amendments are tightening documentation requirements for imported food-grade additives. Manufacturers must now submit complete supply chain traceability records from raw material source through final formulation. Pharmaceutical and infant nutrition segments are responding by pre-qualifying European and Indian suppliers with established pharmacopeial certification, narrowing the approved vendor base.
Specification-driven procurement is consolidating buyer power among large fertilizer cooperatives and multinational food processors. These organizations are unbundling technical service from product supply, engaging third-party laboratories to validate additive performance independently. The practice is most visible in Gauteng's concentrated food processing corridor, where procurement teams now mandate ISO 17025-accredited testing reports for every silicate or carbonate shipment.
South Africa Anti Caking Agents Market Segmentation
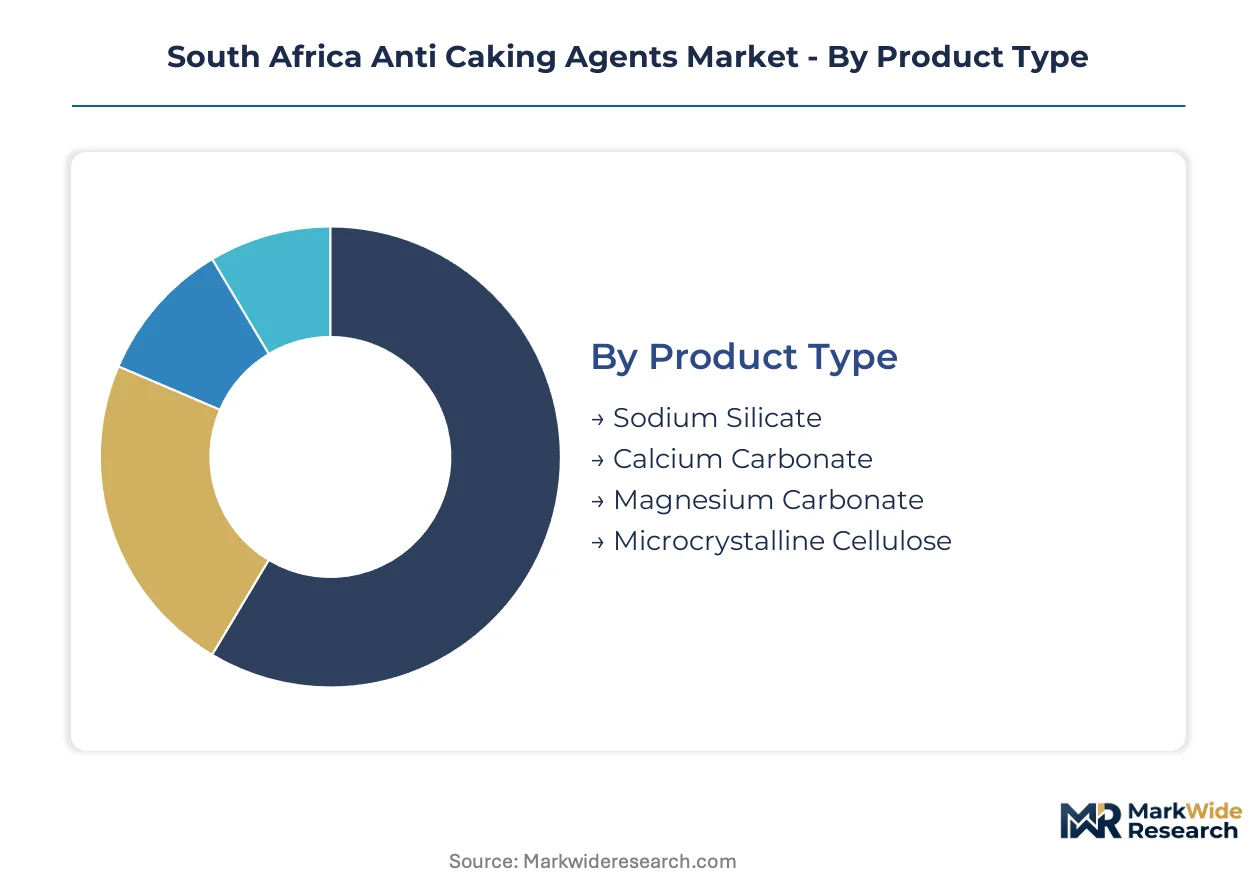
Anti-caking agent procurement in South Africa follows distinct technical and regulatory logics across product chemistry, application requirements, and physical form. Buyers segment suppliers by certification tier and functional performance rather than price alone.
Product Type:
Formulators select chemistry based on moisture sensitivity of the host material and the regulatory burden of the end-use application.
- Sodium Silicate:An alkali metal silicate with hygroscopic binding properties that dual-functions as granulation aid and caking inhibitor in fertilizer processing. Demand concentrates in Gauteng and KwaZulu-Natal bulk agricultural facilities expanding pneumatic conveying capacity for urea and NPK blends.
- Calcium Carbonate:Ground or precipitated carbonate salt with particle sizes ranging 2-10 microns, functioning primarily through physical separation of crystalline surfaces. Rubber manufacturers in Port Elizabeth and construction additive blenders in Durban drive mature volume demand where cost efficiency outweighs premium performance specifications.
- Magnesium Carbonate:Lightweight alkaline compound favored in pharmaceutical tableting for its compressibility and inertness.
- Microcrystalline Cellulose:Purified wood pulp derivative processed to sub-50 micron crystalline structure, commanding food-grade and excipient premiums.
Volume sits with Calcium Carbonate; growth tilts toward Sodium Silicate.
Application:
End-use determines the certification pathway and dictates whether buyers prioritize purity grades or bulk handling efficiency.
- Food Processing:Anti-caking deployment in salt, milk powder, and seasoning blends requiring SABS compliance and full supply chain traceability documentation under pending Foodstuffs Act amendments. Gauteng food manufacturers around Johannesburg represent the concentrated demand cluster.
- Agriculture:Fertilizer granulation and feed premix applications where sodium silicate dual-functionality reduces additive inventory complexity. Mpumalanga and Free State cooperatives are retrofitting legacy blending equipment to realize flowability benefits.
- Pharmaceuticals:SAHPRA-governed excipient applications demanding synthetic amorphous silica with pharmacopeial certification.
- Rubber Manufacturing:Calcium carbonate loading for processing flow in tire and industrial rubber compounding.
Revenue concentrates in Food Processing; expansion accelerates fastest in Agriculture.
Form:
Physical state selection hinges on integration method—batch blending, continuous dosing, or post-process coating—and equipment compatibility.
- Powder:Sub-10 micron particulate enabling homogeneous distribution in dry mixing operations, dominant in food and pharmaceutical batch processing.
- Granules:Agglomerated particles 0.5-2mm for controlled dissolution in fertilizer applications, reducing dust generation during pneumatic conveying.
- Liquid:Colloidal silica or silicate solutions for spray-coating applications in high-speed tablet manufacturing.
- Tablet:Pre-compressed excipient units for direct compression pharmaceutical lines, minimizing powder handling contamination risk.
Shipments favor Powder; formulation innovation targets Granules.
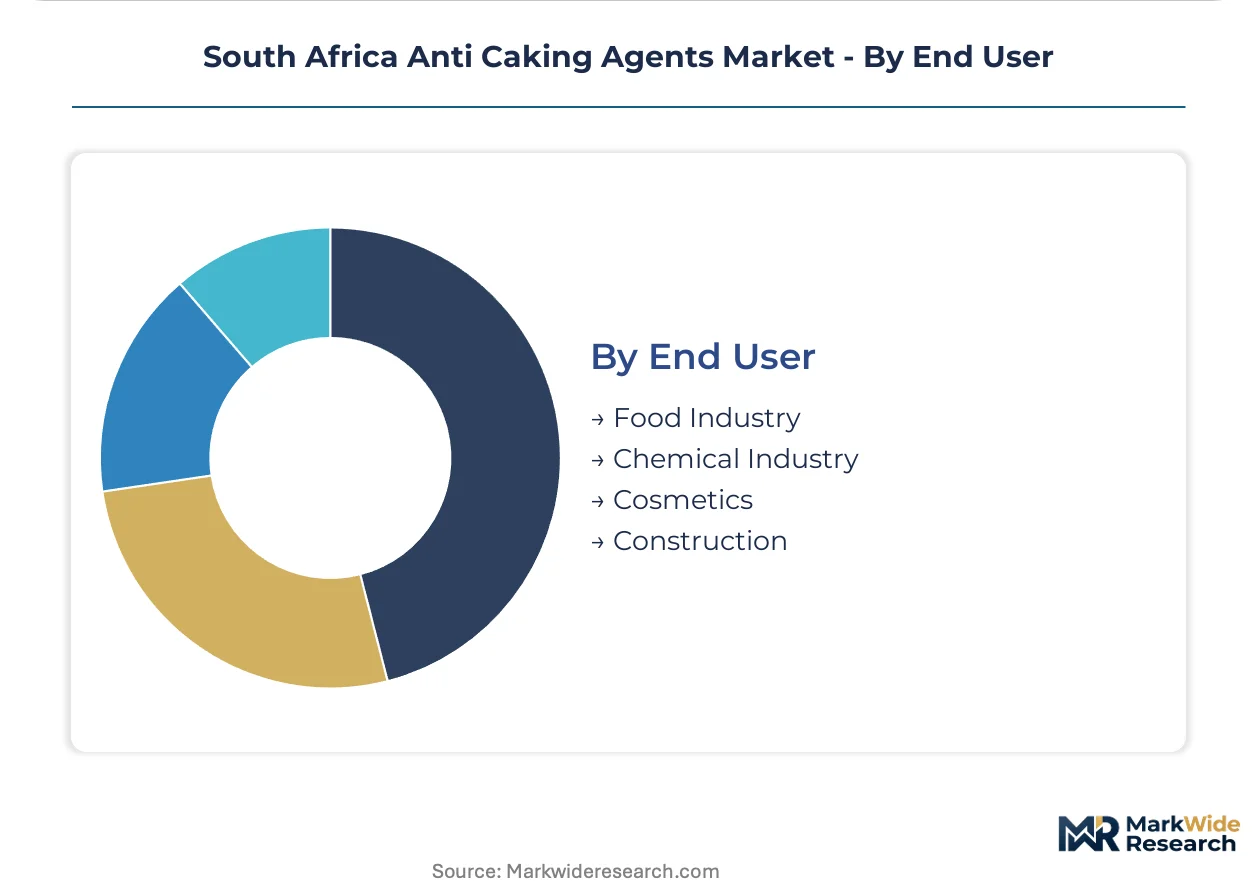
End User:
Industry verticals impose divergent compliance frameworks that filter supplier eligibility and compress margin structures for uncertified entrants.
- Food Industry:Processors of salt, dairy powders, and instant beverages requiring Department of Health registration and SABS dual-track certification.
- Chemical Industry:Fertilizer and industrial chemical manufacturers prioritizing bulk handling efficiency over traceability, served through Norkem Group's Southern African distribution network.
- Cosmetics:Powder formulation houses in Cape Town's emerging personal care cluster seeking low-heavy-metal specifications.
- Construction:Dry-mix mortar and cement additive blenders experimenting with ground limestone substitution for calcium carbonate in non-critical flowability applications.
Procurement scale clusters in the Chemical Industry; compliance complexity peaks in Food Industry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Johannesburg-Pretoria industrial corridor anchors South African anti-caking agent demand, with Gauteng province hosting concentrated food processing and chemical manufacturing clusters that drive procurement scale.
Gauteng
Fertilizer granulation facilities in the Vaal Triangle and food processors around Johannesburg drive sodium silicate and calcium carbonate consumption. The Department of Health's Foodstuffs Act amendments impose dual-track SABS certification requirements on additive suppliers. Pretoria-based regulatory compliance consultancies are expanding to service import registration backlogs.
KwaZulu-Natal
Port Elizabeth rubber manufacturers and Durban construction additive blenders sustain mature calcium carbonate volumes for industrial applications. The Fertilizers, Farm Feeds, Agricultural Remedies and Stock Remedies Act governs feed premix registrations in this coastal manufacturing zone. Richards Bay bulk handling terminals are retrofitting pneumatic conveying systems to accommodate treated fertilizer flows.
Western Cape
Cape Town's emerging biotech corridor attracts active pharmaceutical ingredient manufacturers seeking localized excipient supply chains. SAHPRA's tightening purity standards for pharmaceutical-grade silicon dioxide pull high-specification formulations through domestic distribution channels. Stellenbosch university-industry partnerships are developing particle engineering training programs.
Mpumalanga
Legacy fertilizer cooperatives in this eastern mining belt operate blending equipment designed for untreated bulk materials. The Department of Agriculture's harmonized registration pathways enable cross-selling of anti-caking agents into poultry and ruminant feed channels. Nelspruit agricultural supply depots are piloting silica-carbonate hybrid formulations for mid-tier pricing positions.
Free State
Grain belt fertilizer distributors serve extensive maize and wheat cultivation regions with bulk urea and NPK blends. Bureau of Standards compliance requirements filter out informal suppliers from the additive vendor base. Bloemfontein logistics hubs are consolidating procurement for regional cooperative networks.
South Africa Anti Caking Agents Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across a bifurcated market structure. Synthetic amorphous silica manufacturing demands specialized reactor infrastructure and pharmacopeial certification systems that only European and East Asian bases currently supply. Three archetypes dominate: integrated chemical conglomerates with multi-plant silica synthesis capability, regional distribution specialists with Southern African logistics networks, and excipient-focused pharmaceutical suppliers with SAHPRA pre-qualification status. Competitive moves center on backward integration into raw material sourcing and technology licensing agreements to bypass import dependency.
Among German-based chemical conglomerates, Evonik Industries and Merck KGaA exemplify the premium-tier archetype with synthetic amorphous silica expertise. Solvay occupies a position bridging commodity and specialty grades through its alkali chemistry heritage. Norkem Group anchors the distribution-focused tier with extensive Southern African fertilizer and animal feed channel coverage. These three company structures illustrate how certification depth and logistics scale separate competitive positions in this compliance-intensive market.
| Leading Market Players |
|---|
| Evonik Industries |
| PPG Industries |
| Solvay |
| Norkem Group |
| Merck KGaA |
| ArrMaz |
| PQ Corporation |
| Fuji Chemical Industries |
| Huber Engineered Materials |
| Others |
Value Network & Pricing Analysis
Continuous in-line dosing automation in Gauteng fertilizer granulation lines is compressing unit economics while concentrating procurement leverage among bulk agricultural cooperatives. This shift simultaneously elevates technical service premiums for compliant suppliers and erodes margins for undifferentiated carbonate distributors serving construction and rubber end-users.
Pricing Analysis
Yield-guarantee contracts tied to pneumatic conveying uptime anchor pricing structures for sodium silicate dual-function additives in bulk agriculture. Three-tier pricing stratifies across pharmacopeial-certified silica, food-grade microcrystalline cellulose, and commodity carbonate salts. Cost compression in construction-grade calcium carbonate intensifies as ground limestone substitution trials expand. Fertilizer cooperatives exhibit highest price sensitivity; pharmaceutical formulators prioritize certification over unit cost.
Supply Chain Analysis
Empty silicate container return logistics from Richards Bay to Durban processing hubs create reverse-flow cost burdens for bulk agricultural distributors. Synthetic amorphous silica production draws from Germany, Japan, and China; sodium silicate feeds from South African alkali chemical plants. Single-source vulnerability concentrates in high-purity silica imports for SAHPRA-governed pharmaceutical applications. Distribution runs through Norkem Group's Southern African fertilizer channel network and Evonik's direct pharmaceutical account management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's anti-caking agent market sits in a formulation-technology transition, with silica-carbonate hybrid systems displacing legacy single-chemistry additives across mid-tier fertilizer and feed applications.
For Market Incumbents: Anchor defensible positioning through backward integration into synthetic amorphous silica raw material sourcing and SAHPRA pre-qualification status for pharmaceutical channels. Threaten new entrants by locking long-term offtake agreements with Gauteng fertilizer cooperatives expanding pneumatic conveying capacity. Prioritize certification investment over capacity addition in commoditized carbonate segments. For New Entrants and Emerging Players: The premium-economy price gap in animal feed anti-caking applications opens white-space targeting for silica-carbonate hybrid formulations at mid-tier price points. Penetrate Mpumalanga and Free State legacy fertilizer cooperatives retrofitting untreated bulk blending equipment. Pursue go-to-market partnerships with Pretoria-based regulatory compliance consultancies managing Foodstuffs Act registration backlogs. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking Southern African distribution scale. Long-term viability hinges on positioning upstream of harmonized Fertilizers, Farm Feeds, Agricultural Remedies and Stock Remedies Act registration pathways. Monitor SAHPRA excipient purity standard amendments as inflection signal for pharmaceutical-grade silica demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Silica Raw Materials | Reduces currency exposure on European and East Asian pharmaceutical-grade imports. |
| SAHPRA Pre-Qualification Investment | Unlocks Cape Town biotech corridor demand from active pharmaceutical ingredient manufacturers. |
| Silicate-Carbonate Hybrid Formulation Development | Captures mid-tier pricing between premium silica and commodity carbonate agricultural segments. |
| Long-Term Supply Agreement with Fertilizer Cooperatives | Secures volume anchor as Gauteng and KwaZulu-Natal pneumatic conveying capacity expands. |
| Regulatory Compliance Consultancy Partnership | Accelerates Foodstuffs Act additive schedule approval pathways for microcrystalline cellulose entrants. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fertilizer plant managers, pharmaceutical procurement leads, food processing technical directors, and SABS certification consultants combined with SAHPRA excipient registration databases, Department of Agriculture fertilizer additive filings, and Bureau of Standards compliance records. Bottom-up volume modeling across product chemistry tiers triangulated against top-down agricultural and pharmaceutical sector consumption estimates.
Reconciliation of customs import volumes, domestic alkali chemical production data, and end-use industry consumption surveys shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, application regulatory pathway, physical form factor, and provincial manufacturing cluster. CAGRs derived from fitted growth curves on historical consumption trajectories, adjusted for Foodstuffs Act amendment implementation timelines and fertilizer granulation capacity expansion pipelines.
Inputs from SAHPRA, SABS, and Department of Agriculture officials were available through the study window; gaps in informal sector carbonate salt consumption introduce uncertainty bands in construction and rubber manufacturing end-use estimates. Forecasts reflect documented assumptions on regulatory amendment timing and cooperative infrastructure retrofit rates. Practitioners should monitor pending Foodstuffs Act additive schedule publications and Richards Bay pneumatic conveying terminal commissioning for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
Global Lutein and Lutein Esters Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
Protective Cultures Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
Food Inclusions Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Food Phosphate Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
North America Food Additives Market
Food Additives and Ingredients
Food Grade Distilled Monoglyceride Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
Oleic Acid Market