
 Beverage Clarifier and Stabilizer Market | 2026-2036
Beverage Clarifier and Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Clarifier and Stabilizer Market Outlook
Plant-derived pectin is expanding its share in juice and soft drink applications as beverage makers reduce gelatin dependence for vegetarian label claims. Cargill leverages its integrated citrus peel supply chain to control pectin feedstock costs across North American and European plants. BASF sustains technology leadership in synthetic silica gel grades engineered for high-turbidity wine musts. Kerry Group anchors its position through brewery technical service teams that specify stabilizer protocols on-site.
Beverage clarifiers and stabilizers comprise functional additives that induce flocculation, sedimentation, or colloidal suspension to remove haze-forming proteins, polyphenols, and yeast from finished drinks; pectin operates at dosage levels of 0.05–0.5% w/v to complex with positively charged particulates in acidic fruit matrices. The primary commercial purpose is to extend visual shelf stability and prevent post-bottling precipitation that triggers consumer rejection or retail returns. Gelatin retains dominant share in traditional wine and juice applications where tannin-protein complexation remains cost-optimal, though pectin captures fastest growth as clean-label formulations displace animal-derived inputs across European and North American beverage portfolios. Powder formulations lead volume due to freight efficiency and warehouse stability, while liquid concentrates gain traction in automated dosing systems at large-scale soft drink bottlers where inline blending demands pumpable rheology.
FDA Food Safety Modernization Act traceability mandates compel clarifier suppliers to document allergen-free handling for gelatin and pectin crossing into US beverage manufacturing facilities. EFSA purity specifications for food-grade bentonite restrict heavy metal content to thresholds below 5 ppm lead, shaping sourcing decisions toward Wyoming-mined deposits with certified analytical packages. ISO 22000 certification has become a baseline qualifier for supplier qualification at multinational beverage manufacturers, effectively filtering regional producers from global procurement lists. Stakeholders must monitor evolving EU packaging waste directives that may shift formulation priorities toward lower-dose stabilizers reducing overall additive mass in packaged beverages.
Market Dynamics
Clean-label formulation mandates from major retailers are compressing gelatin's historic dominance as beverage manufacturers race to eliminate animal-derived inputs from premium product lines ahead of 2025 shelf resets.
Growth Catalysts
- EU Packaging Waste Directive:Lower-dose stabilizer formulations reduce additive mass in packaged beverages, creating procurement preference for concentrated pectin and silica gel grades across German and French bottling operations.
- Craft brewery filtration scaling:Small-batch producers in Colorado and Oregon are installing automated clarification systems that specify on-site technical service protocols, locking in stabilizer supplier relationships.
- ISO 22000 procurement baselines:Multinational beverage manufacturers now filter regional producers from global supply lists, consolidating qualified vendor pools around certified pectin and bentonite handlers.
Market Restraints
- Wyoming bentonite concentration:EFSA heavy metal thresholds below 5 ppm lead restrict food-grade sourcing to certified Wyoming deposits, creating single-geography supply vulnerability for wine clarification.
- Gelatin allergen documentation:FDA Food Safety Modernization Act traceability mandates impose handling compliance costs that squeeze margin-competitive animal-derived clarifier suppliers.
- Silica gel performance ceilings:Synthetic grades engineered for high-turbidity wine musts face technical limitations in protein-polyphenol complexation efficiency versus tannin-optimized gelatin protocols.
Strategic Opportunities
- India juice processing expansion:Domestic soft drink bottlers are retrofitting automated dosing systems that demand pumpable liquid concentrate rheology, opening pectin formulation contracts.
- Inline blending automation:Large-scale bottlers are replacing powder handling with continuous liquid stabilizer injection, favoring suppliers with integrated citrus peel feedstock control.
- PLI scheme alignment:India's production-linked incentive framework for food processing infrastructure subsidizes clarifier plant localization for export-oriented beverage manufacturers.
Industry Challenges
- Brewery technical service staffing:On-site stabilizer protocol specification requires trained fermentation specialists, creating talent scarcity as craft production scales fragment across dispersed geographic clusters.
- EFSA purity certification timelines:Heavy metal analytical package verification for Wyoming bentonite deposits extends supplier qualification cycles, delaying new entrant market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Clarifier and Stabilizer Market |
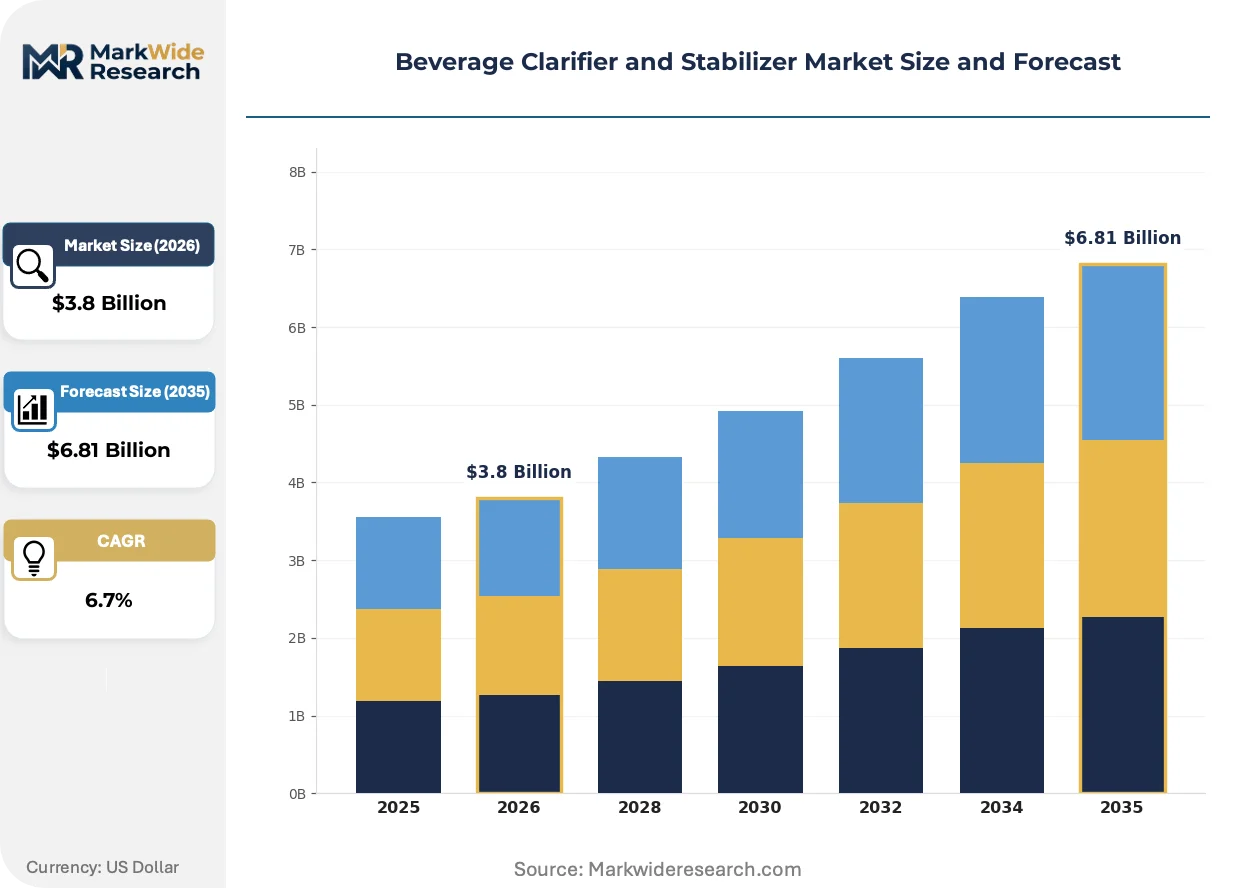
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Bentonite, Silica Gel, Pectin Application: Wines, Juices, Soft Drinks, Dairy Beverages Formulation: Liquid, Powder, Granular, Tablets End User: Beverage Manufacturers, Food Processors, Breweries, Cideries |
| Companies Covered | Cargill, CP Kelco, BASF, Tate & Lyle, PQ Corporation, Koninklijke DSM, Ingredion Incorporated, Kerry Group, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Clarifier and Stabilizer Market Strategic Shifts
Electrification of clarification chemistry is compressing traditional settling timelines while regulatory traceability mandates reshape supplier qualification protocols across beverage manufacturing tiers.
Enzymatic pectin methylesterase treatments are electrifying juice processing workflows by accelerating haze precipitation in citrus and apple matrices. Mid-scale Florida and São Paulo processors are retrofitting cold-pressed lines with inline enzymatic dosing skids that cut clarification hold times from 48 hours to 6 hours. This compression is electrifying competitive positioning for suppliers offering integrated enzyme-stabilizer bundled protocols.
REACH substance evaluation expansions are tightening purity disclosure requirements for silica gel imports entering EU beverage facilities. The industrial consequence is forced reformulation of synthetic clarifier grades to eliminate residual heavy metal contaminants above 0.1 ppm thresholds. Wine must processors in Bordeaux and Tuscany are responding by demanding certified analytical packages that document batch-level contaminant testing.
Retailer-driven vegetarian label claims are restructuring procurement specifications at North American and European beverage conglomerates. Traditional gelatin-dependent wine and juice portfolios face displacement as clean-label mandates filter through 2024-2025 product reformulation cycles. This specification shift concentrates most visibly in German Reinheitsgebot-adjacent brewing traditions and California premium juice private label contracts.
Beverage Clarifier and Stabilizer Market Segmentation
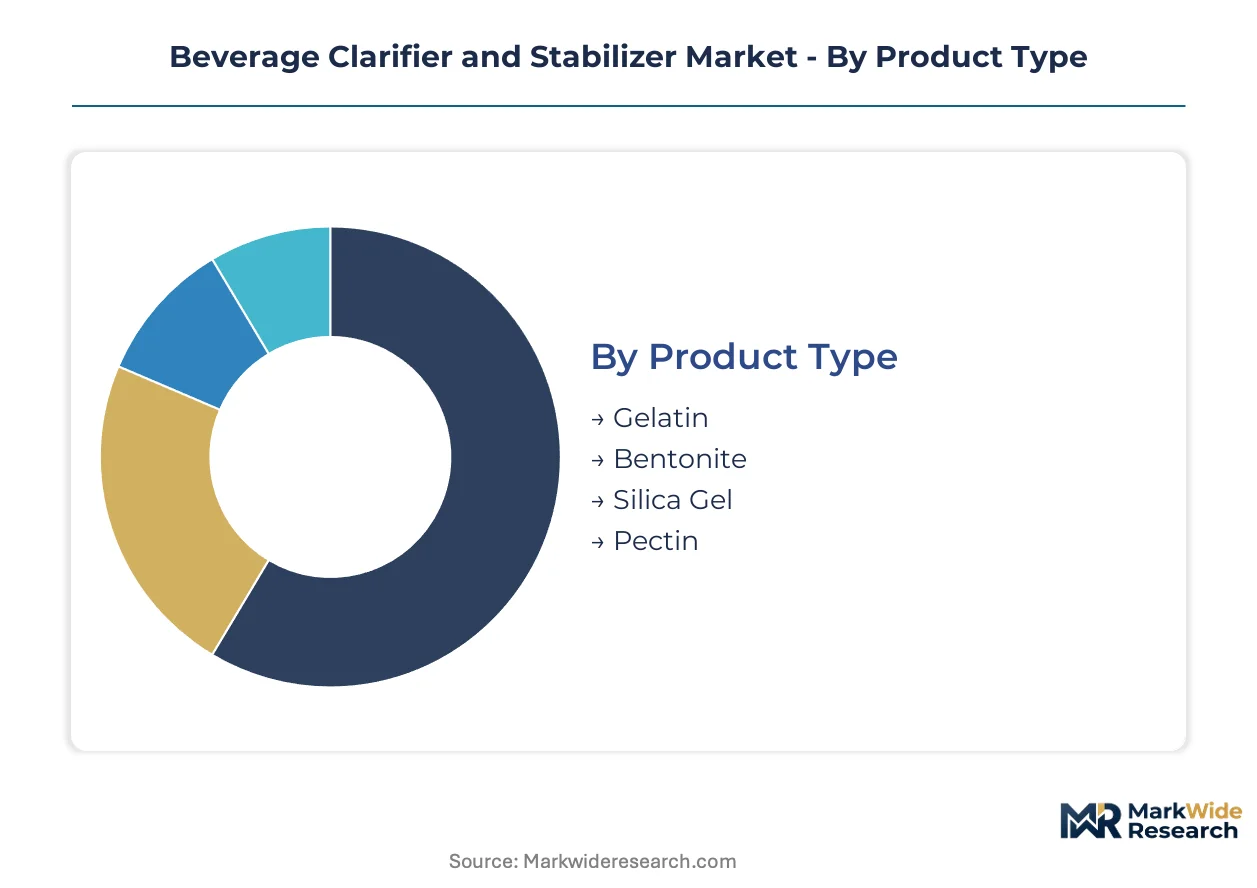
Clarifier procurement patterns diverge sharply across product chemistries and application matrices, with formulation choices directly tied to automation infrastructure and clean-label positioning strategies. Supply concentration in Wyoming bentonite and Brazilian citrus peel pectin shapes sourcing economics for beverage manufacturers across all four segmentation dimensions.
Product Type:
Feedstock control and extraction technology determine margin structures and geographic supply concentration for each clarifier chemistry.
- Gelatin:Collagen-derived protein from bovine and porcine sources complexes with polyphenolic tannins in wine must clarification. Traditional Bordeaux and Napa Valley wineries sustain demand despite allergen documentation burdens under FDA traceability mandates.
- Pectin:Citrus peel polysaccharide extracted via acid hydrolysis functions at 0.05–0.5% w/v dosage in acidic fruit matrices. Vegetarian label claims in German and Californian premium juice portfolios are accelerating displacement of gelatin-dependent formulations.
- Bentonite:Wyoming-mined montmorillonite clay adsorbs positively charged proteins; EFSA heavy metal thresholds below 5 ppm lead restrict food-grade sourcing to certified deposits with analytical package verification.
- Silica Gel:Synthetic amorphous silicon dioxide engineered for high-turbidity wine musts encounters technical ceilings in protein-polyphenol complexation efficiency versus optimized gelatin protocols.
Gelatin absorbs the bulk of installed capacity in traditional wine clarification; pectin is expanding most quickly across clean-label beverage portfolios.
Application:
Matrix chemistry and consumer visibility standards dictate clarifier selection, with turbidity tolerance thresholds varying dramatically across beverage categories.
- Wines:Tannin-protein haze formation in red and white musts demands specialized stabilizer protocols; Bordeaux and Tuscany processors specify batch-level contaminant testing under REACH substance evaluation expansions.
- Juices:Pectin methylesterase enzymatic treatments are compressing clarification hold times from 48 hours to 6 hours in Florida and São Paulo citrus processing facilities.
- Soft Drinks:Automated inline blending systems at large-scale bottlers specify pumpable liquid concentrate rheology, favoring pectin formulations with integrated citrus peel feedstock control.
- Dairy Beverages:Heat-stable stabilizer grades prevent protein aggregation during ultra-high-temperature processing; formulation specifications concentrate in European and North American extended-shelf-life milk operations.
Wines command the deepest technical service requirements; juices are climbing the fastest as enzymatic acceleration reshapes processing economics.
Formulation:
Physical form determines logistics economics and dosing precision, with automation penetration driving format migration across beverage manufacturing tiers.
- Powder:Dominant volume format due to freight efficiency and warehouse stability; bulk handling infrastructure at mid-scale breweries and juice processors sustains procurement preference.
- Liquid:Pumpable concentrates gain traction in automated dosing systems at large-scale soft drink bottlers where inline blending demands controlled rheology.
- Granular:Free-flowing bentonite grades simplify dry bulk handling in winery cellar operations without dust generation concerns of fine powders.
- Tablets:Pre-weighed gelatin and bentonite units serve small-batch craft producers in Colorado and Oregon seeking simplified cellar protocols without analytical equipment.
Powder formulations retain the largest installed base; liquid concentrates are gaining share fastest through bottler automation retrofit cycles.
End User:
Scale and technical capability determine whether clarifier procurement emphasizes on-site service support or commodity price optimization.
- Beverage Manufacturers:Multinational soft drink and juice conglomerates enforce ISO 22000 certification baselines that filter regional producers from global supply lists.
- Breweries:Craft producers in Oregon and Colorado are installing automated clarification systems that lock in supplier relationships through embedded technical service protocols.
- Food Processors:Diversified manufacturers with beverage lines prioritize multi-application stabilizer grades to simplify inventory management across product portfolios.
- Cideries:Apple-based fermentation specialists in Normandy and Virginia leverage pectin-specific expertise from adjacent juice processing supply chains.
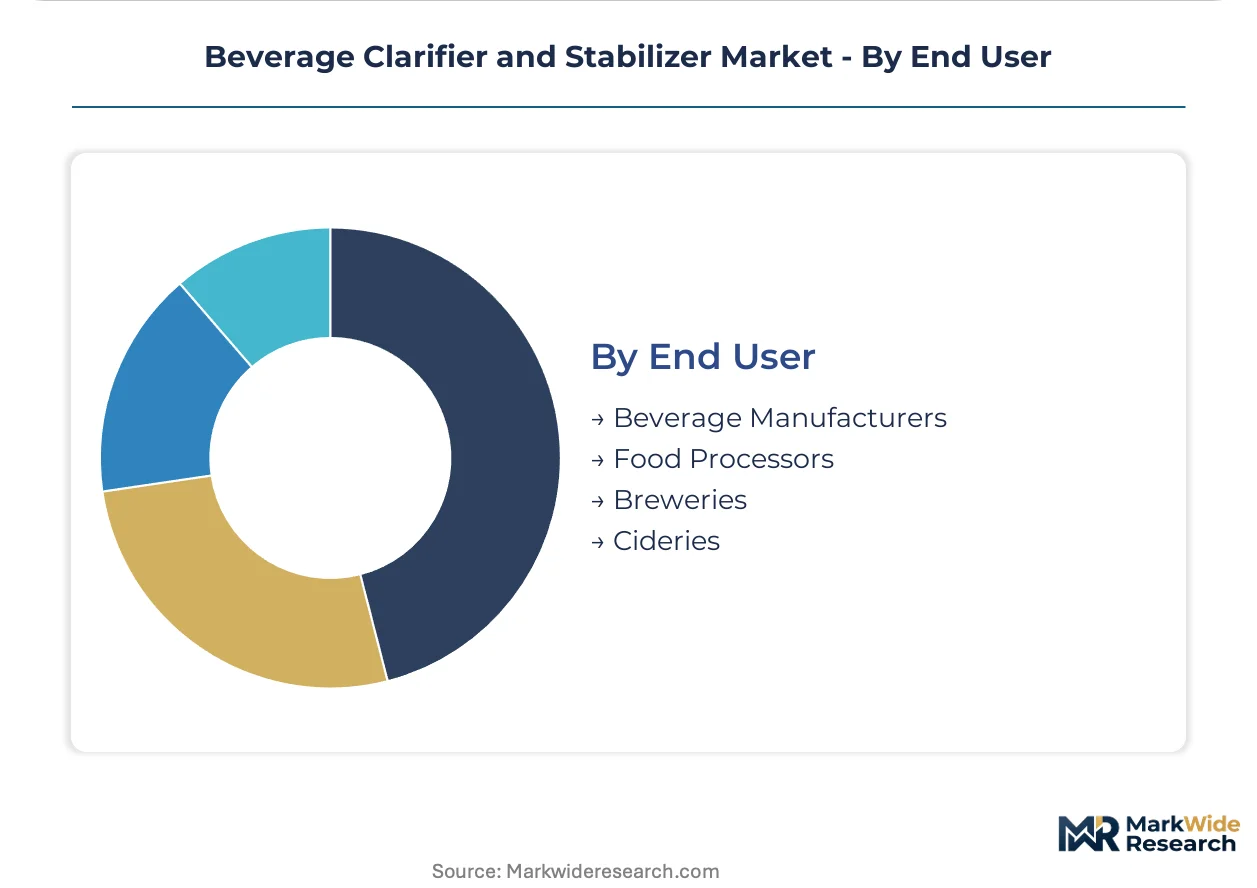
Beverage manufacturers concentrate procurement volume; breweries are expanding most quickly as craft filtration capacity scales across dispersed geographic clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production-Linked Incentive scheme for food processing infrastructure is concentrating clarifier plant investment around export-oriented beverage manufacturing zones in Maharashtra and Gujarat.
United States
Craft breweries in Colorado and Oregon are scaling automated filtration capacity to meet premium positioning requirements. FDA Food Safety Modernization Act traceability mandates compel suppliers to document allergen-free handling for gelatin and pectin crossing into beverage facilities. Small-batch producers in the Pacific Northwest are installing clarification systems that lock in supplier relationships through embedded technical service protocols.
Germany
Reinheitsgebot-adjacent brewing traditions sustain specialized stabilizer consumption for beer clarification applications. EFSA purity specifications for food-grade bentonite restrict heavy metal content to thresholds below 5 ppm lead, shaping sourcing decisions toward certified deposits with analytical packages. Processing facilities in Bavaria specify batch-level contaminant testing under REACH substance evaluation expansions.
India
Domestic soft drink bottlers are retrofitting automated dosing systems that demand pumpable liquid concentrate rheology, opening pectin formulation contracts. The PLI scheme subsidizes clarifier plant localization for export-oriented beverage manufacturers. Processing clusters in Maharashtra and Gujarat are attracting integrated citrus peel feedstock control investments from multinational suppliers.
Brazil
Citrus processors in São Paulo are retrofitting cold-pressed lines with inline enzymatic dosing skids that cut clarification hold times from 48 hours to 6 hours. ANVISA traceability requirements parallel FDA mandates for imported clarifying agents. Mid-scale juice facilities in the state are electrifying competitive positioning through bundled enzyme-stabilizer protocols.
France
Wine must processors in Bordeaux demand certified analytical packages documenting batch-level contaminant testing under REACH expansions. EFSA heavy metal thresholds restrict food-grade bentonite sourcing to certified deposits. Traditional wineries in the region sustain gelatin demand for tannin-protein complexation despite clean-label pressures.
Beverage Clarifier and Stabilizer Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational ingredient conglomerates controlling premium pectin and silica gel grades while regional processors dominate commodity bentonite supply. The vendor base organizes around three strategic archetypes: integrated agricultural processors with captive feedstock control, synthetic specialty chemical manufacturers, and fermentation-focused technical service providers. Consolidation pressure is accelerating through backward integration into citrus peel supply chains and geographic expansion into Indian PLI-subsidized production zones.
Within the integrated agricultural processor tier, Cargill leverages its supply chain position across North American and European plants, while CP Kelco and Kerry Group exemplify technical service-anchored models that specify stabilizer protocols through on-site brewery support teams. These three represent divergent pathways for securing clarifier market position—feedstock control, synthetic chemistry leadership, and embedded fermentation expertise.
| Leading Market Players |
|---|
| Cargill |
| CP Kelco |
| BASF |
| Tate & Lyle |
| PQ Corporation |
| Koninklijke DSM |
| Ingredion Incorporated |
| Kerry Group |
| Ashland |
| Others |
Value Chain & Pricing Dynamics
Multinational beverage manufacturers with ISO 22000 procurement baselines command tiered pricing leverage, compressing margin-competitive regional suppliers while rewarding certified handlers with long-term offtake security. Wyoming bentonite concentration and Brazilian citrus peel pectin dominance anchor cost structures that ripple through formulation economics across all buyer tiers.
Pricing Analysis
Short lead-time premiums concentrate around Wyoming bentonite deposits where EFSA heavy metal certification cycles extend supplier qualification timelines. Three-tier pricing structure across certified premium grades, standard food-tier, and unqualified economy lots reflects ISO 22000, REACH compliance, and raw purity differentials. Pricing pressure stems from FDA Food Safety Modernization Act traceability mandates imposing allergen documentation costs on gelatin handlers. Small-batch craft breweries in Colorado and Oregon exhibit highest price sensitivity; large-scale soft drink bottlers with automated dosing systems absorb premiums for liquid concentrate pumpability.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Charleston anchor hub-and-spoke patterns serving beverage manufacturing clusters across Germany, India, and the United States. Supply draws from Wyoming-mined bentonite, Brazilian citrus peel for pectin extraction, and North American bovine collagen for gelatin. Single-source vulnerability concentrates in Wyoming bentonite where EFSA-certified deposits face geographic concentration risk. Distribution runs through integrated agricultural processors with captive feedstock control and synthetic specialty chemical manufacturers serving high-turbidity wine applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Beverage Clarifier and Stabilizer Market operates as a cost-of-compliance arena where FDA Food Safety Modernization Act traceability mandates and EFSA heavy metal thresholds erect formidable barriers-to-entry, entrenching certified incumbents while filtering margin-competitive regional challengers from global procurement lists.
For Market Incumbents: Deepen backward integration into Brazilian citrus peel supply chains to lock in pectin feedstock cost control against Cargill's integrated position. Fortify on-site technical service teams at craft brewery installations in Oregon and Colorado to embed stabilizer protocol specification before competitors replicate Kerry Group's fermentation-specialist staffing model. For New Entrants and Emerging Players: Enter via India's PLI-subsidized processing clusters in Maharashtra and Gujarat where automated dosing system retrofits demand pumpable liquid concentrate rheology absent established pectin formulation contracts. Target mid-scale juice processors in São Paulo seeking bundled enzyme-stabilizer protocols to compress clarification hold times from traditional settling timelines. For Investors and Strategic Acquirers: The window for entry favors technical service-anchored specialists with embedded brewery fermentation expertise over commodity bentonite handlers facing Wyoming supply concentration risk. Monitor REACH substance evaluation expansion timelines as inflection indicators for synthetic silica gel reformulation costs that could accelerate pectin displacement across European wine portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Peel Supply | Cargill's captive feedstock control across North American and European plants secures pectin margin structures against spot market volatility. |
| Technical Service Team Expansion | Kerry Group's on-site brewery protocol specification locks in supplier relationships through embedded fermentation specialist staffing. |
| PLI-Aligned Plant Localization | India's production-linked incentive framework subsidizes clarifier manufacturing investment for export-oriented beverage processors in Gujarat. |
| Enzymatic Stabilizer Bundling | Mid-scale São Paulo juice facilities electrify competitive positioning through integrated pectin methylesterase-stabilizer protocols. |
| REACH-Compliant Silica Gel Reformulation | BASF's synthetic grade engineering eliminates residual heavy metal contaminants above tightened EU beverage facility thresholds. |
Study Parameters
Multi-period observation of clarifier procurement patterns, formulation migration timelines, and certification compliance rates anchored the trend analysis, supplemented by interviews with beverage plant managers, procurement leads at multinational soft drink conglomerates, distribution channel partners, and technical R&D directors at stabilizer manufacturers. Secondary validation drew from FDA FSMA guidance documents, EFSA purity specifications, REACH substance evaluation expansions, customs and trade data for bentonite and pectin flows, and SEC filings of integrated agricultural processors. Bottom-up volume triangulation across product chemistry, application matrix, formulation type, and end-user tier converged with top-down market sizing.
Input-output matrices modeled clarifier demand across wine, juice, soft drink, and dairy beverage applications segmented by powder, liquid, granular, and tablet formulations. CAGRs were derived through regression analysis of historical procurement volumes against automation infrastructure penetration and clean-label formulation mandates throughout the forecast period. Industry-specific forecast inputs included craft brewery filtration capacity scaling in Colorado and Oregon, enzymatic acceleration adoption curves in Florida and São Paulo citrus processing, and PLI scheme uptake rates in Maharashtra and Gujarat.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EFSA heavy metal threshold revisions or FDA allergen documentation mandate expansions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Protective Cultures Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Asia Food Emulsifiers Market
Food Additives and Ingredients
Casamino Acids Market
Food Additives and Ingredients
Monoglyceride Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Activated Cake Emulsifier Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market